
 NB-IoT Smart Gas Meter Market | 2026-2036
NB-IoT Smart Gas Meter Market Size, Share, and Industry Trends Forecast 2026-2036
NB-IoT Smart Gas Meter Market Insights
Market Context
The EU F-Gas Regulation is hardening compliance thresholds for methane leak detection, forcing meter suppliers to certify cellular-connected accuracy at sub-percent levels. Itron Inc. leverages its AMI software stack to anchor utility contracts across European capitals. Landis+Gyr Group AG dominates Swiss and German distribution networks through in-house production of NB-IoT radio modules. Honeywell International Inc. competes on sensor fusion architectures that integrate pressure and temperature telemetry within the gas meter enclosure.
Technical Definition and Segment Structure
NB-IoT smart gas meters are battery-operated flow measurement devices that transmit consumption data via narrowband cellular channels in licensed spectrum, typically operating at 800 MHz or 900 MHz bands with 10-20 dB deeper building penetration than legacy GPRS modules. These meters enable remote shutoff, demand-response orchestration, and predictive maintenance for gas distribution networks. Residential Meters sustain the highest shipment volumes globally, though Industrial Meters command premium pricing due to explosion-proof housing and custody-transfer certification requirements. Smart Cities as an end-user segment is expanding fastest, driven by municipal net-zero mandates that require granular building-level emissions tracking.
Regulatory Framework and Outlook
The EU Green Deal, CE marking under the MDR framework, and China's MIIT radio-type approval standards collectively shape product roadmaps and market access timelines. ETSI compliance for electromagnetic compatibility and SAMR metrology certification in China create dual-hurdle qualification paths that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor spectrum refarming decisions by national regulators, as 2G sunset schedules directly accelerate NB-IoT migration timelines for installed mechanical meter bases.
Market Dynamics
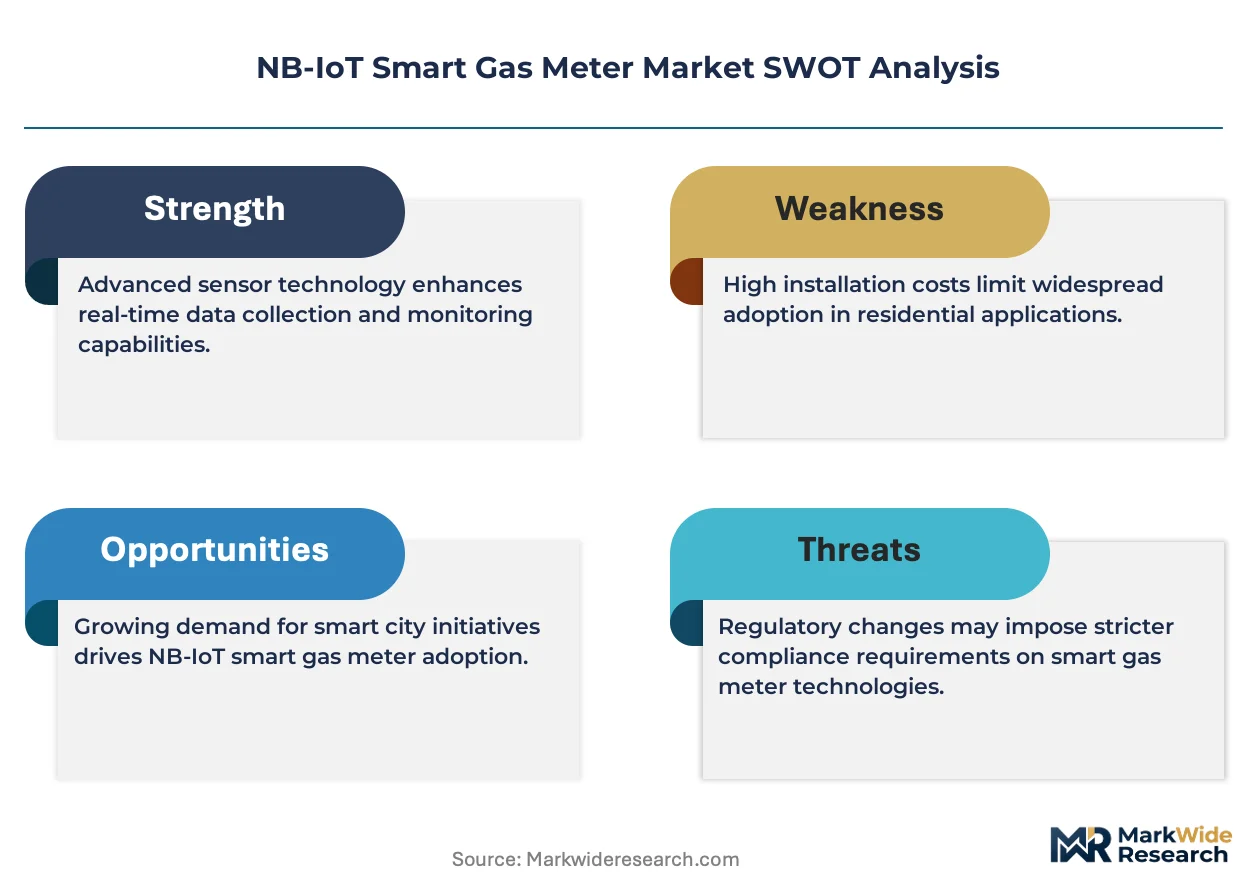
The EU F-Gas Regulation is compressing migration timelines for cellular-connected gas infrastructure, forcing utilities to retire mechanical meter bases ahead of depreciation schedules and recertify entire distribution networks under tightened methane accountability frameworks.
Growth Catalysts
- EU Green Deal net-zero mandates:Municipal utilities in France, Germany, and Italy must deploy building-level emissions tracking by 2030, creating pull-through for NB-IoT modules with sub-percent accuracy certification.
- China MIIT spectrum allocation:Licensed LPWAN bands at 800 MHz and 900 MHz are concentrating manufacturing demand in the Yangtze River Delta cluster, achieving scale economies for radio module production.
- 2G sunset acceleration:National regulators in Spain, Poland, and the Netherlands are refarming legacy spectrum, compelling utilities to migrate installed meter bases to NB-IoT before network shutdown deadlines.
Market Restraints
- Lithium battery supply concentration:Cell production for meter power systems clusters in East Asian suppliers, exposing European utilities to raw material volatility and forced qualification of alternative chemistries.
- Dual-hurdle certification:ETSI electromagnetic compatibility testing combined with SAMR metrology approval in China extends product launch timelines and favors established vendors with dedicated regulatory affairs teams.
- Mechanical meter residual life:Decades-long depreciation schedules for legacy assets create capital allocation friction against premature NB-IoT replacement cycles.
Strategic Opportunities
- Hydrogen blend monitoring:Emerging H2 admixture requirements in Dutch and Danish gas networks create demand for multi-gas sensor fusion architectures that extend meter functionality beyond methane measurement.
- Smart Cities vertical expansion:Municipal net-zero mandates in Barcelona, Copenhagen, and Vienna require granular consumption data for building-level carbon accounting, opening procurement channels outside traditional utility structures.
- Pressure-telemetry integration:Convergence of flow measurement with distribution network monitoring enables predictive maintenance contracts that shift vendor revenue from hardware to recurring service models.
Industry Challenges
- RF engineering talent scarcity:Narrowband cellular optimization for deep-building penetration requires specialized expertise in antenna design and power management that concentrates in semiconductor hubs.
- Legacy AMI integration complexity:Utilities operating mixed fleets of proprietary protocols face data normalization costs when grafting NB-IoT endpoints onto existing head-end systems.
- Explosion-proof certification timelines:Industrial meter variants for custody-transfer applications require ATEX and IECEx testing cycles that extend time-to-revenue for premium product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NB-IoT Smart Gas Meter Market |
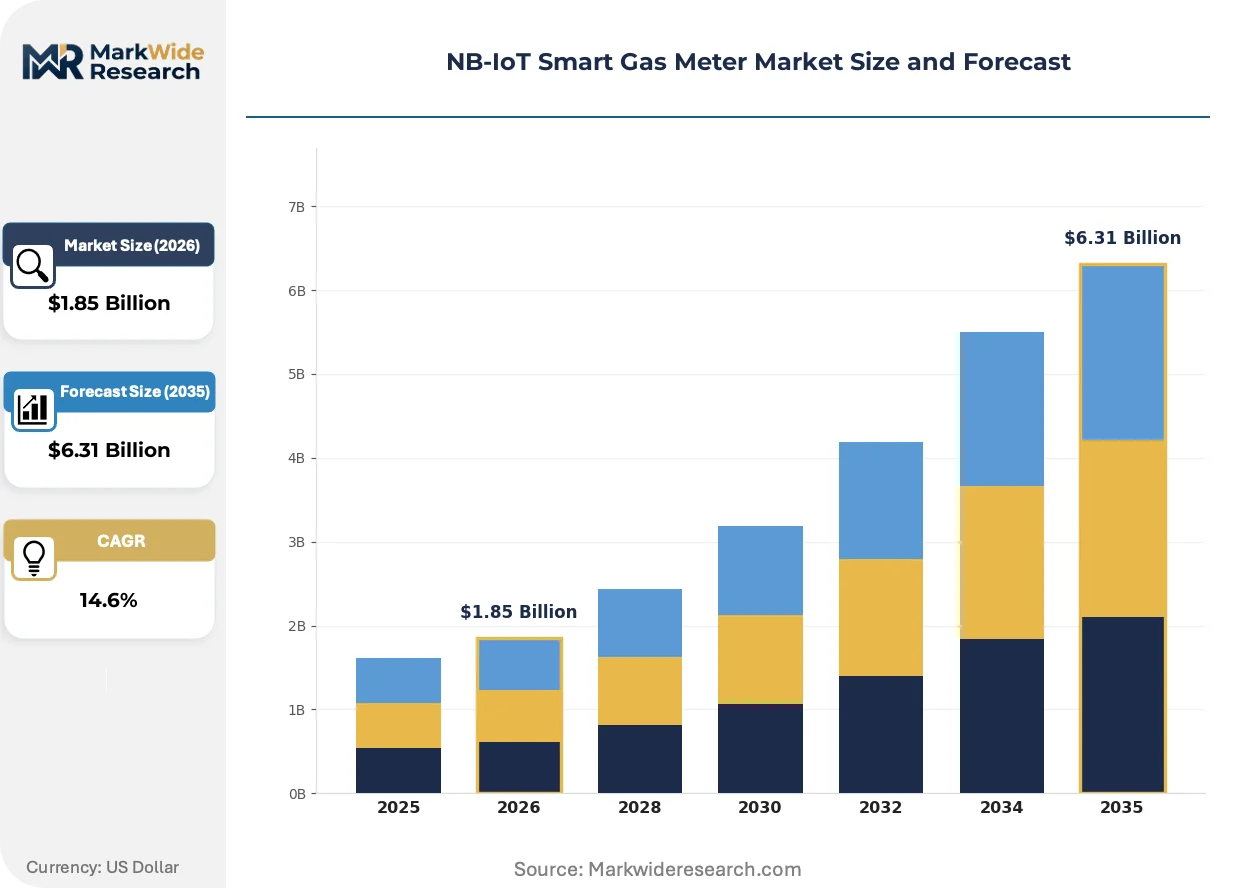
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Meters, Commercial Meters, Industrial Meters, Smart Sensors Technology: LoRa, Sigfox, NB-IoT, LTE-M Installation: Standalone, Integrated, Retrofitted, Wireless End User: Utilities, Service Providers, Industrial Users, Smart Cities |
| Companies Covered | Itron Inc., Landis+Gyr Group AG, Honeywell International Inc., Sensus (Xylem Inc.), Apator S.A., Diehl Stiftung and Co. KG, Siemens, Wasion Group Holdings Limited, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NB-IoT Smart Gas Meter Market Trends and Innovations
Cellular module architecture is consolidating around system-in-package designs that embed baseband, RF front-end, and power management in single-chip configurations, collapsing the historical separation between meter OEMs and radio suppliers.
Sensor fusion is unifying pressure, temperature, and flow telemetry within sealed meter enclosures, eliminating external transducer wiring that previously dominated installation labor. Swiss and German distribution operators are piloting these integrated architectures in high-rise residential deployments where conduit space constraints favor consolidated electronics. The technology is unifying hardware BOMs across residential and light commercial segments that historically required distinct product SKUs.
The EU F-Gas Regulation is hardening leak detection thresholds for methane emissions, mandating connected accuracy verification that mechanical meters cannot satisfy. Meter suppliers must now certify cellular-connected devices through notified bodies under the MDR framework before utility procurement eligibility. Industrial custody-transfer installations face the steepest compliance burden, driving premium pricing for explosion-proof NB-IoT variants with certified metrology chains.
Utility procurement is fragmenting from national tender structures toward municipal-level net-zero contracts that bundle meter deployment with building emissions analytics. Copenhagen and Vienna have unbundled hardware acquisition from data platform subscriptions, creating recurring revenue channels for AMI software vendors. This pattern is most visible in Nordic and Alpine markets where municipal energy agencies hold direct contracting authority outside national utility structures.
NB-IoT Smart Gas Meter Market Segmentation
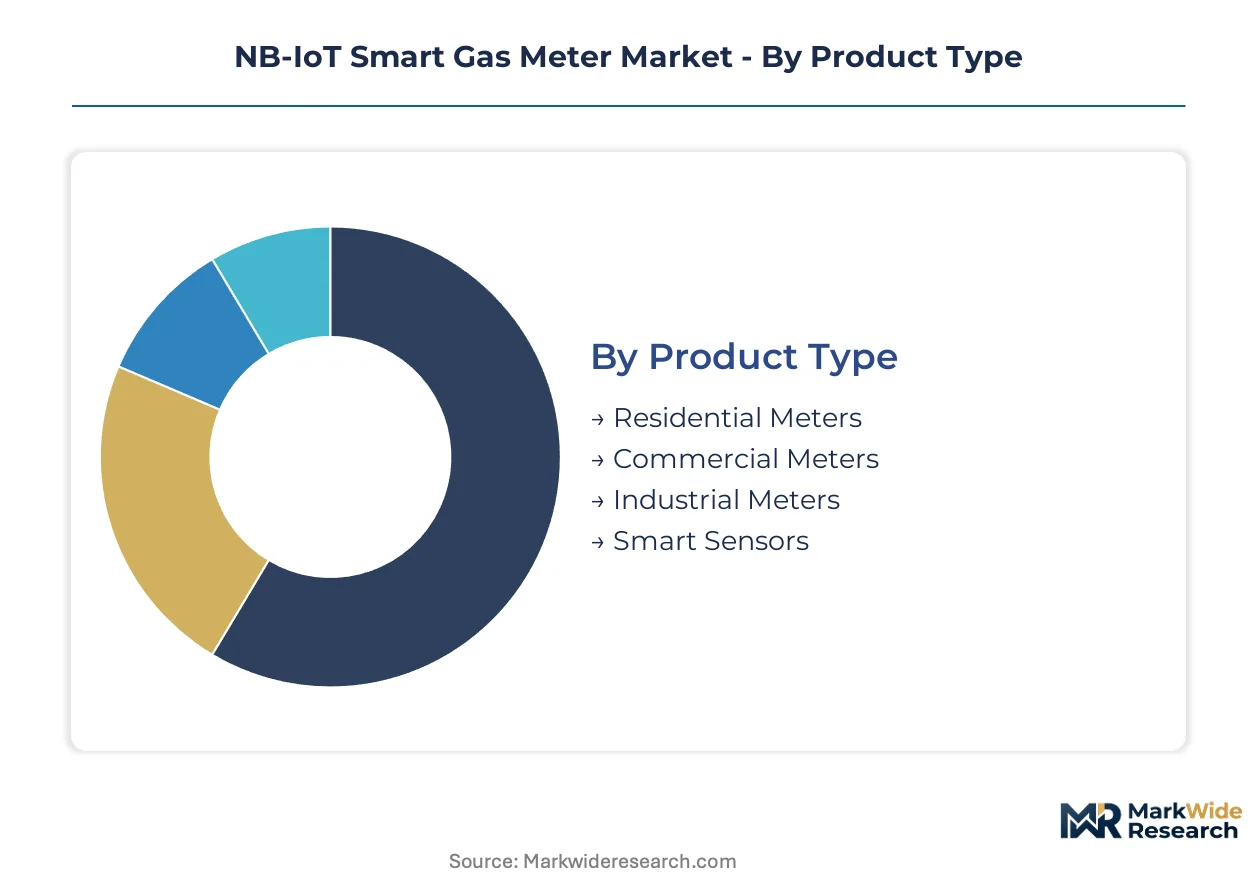
Segmentation in the NB-IoT smart gas meter market reveals distinct capital requirements across product tiers and installation scenarios. Utility procurement patterns diverge sharply between residential volume plays and industrial premium contracts, while technology choices lock in decade-long network commitments.
Product Type:
Capital intensity peaks with explosion-proof industrial variants requiring ATEX certification, while residential meters compete on scale economies in module production.
- Residential Meters:Battery-operated diaphragm or ultrasonic flow devices with NB-IoT radios sealed in IP68 enclosures. Municipal utilities in France and Germany deploy these at building density levels exceeding 500 units per square kilometer in urban cores, driven by EU Green Deal net-zero mandates requiring granular consumption tracking.
- Industrial Meters:Turbine or rotary displacement designs with custody-transfer accuracy certification and flameproof housing. Dutch and Danish gas network operators specify these for hydrogen blend monitoring applications, where multi-gas sensor fusion commands premium positioning.
- Commercial Meters:Mid-range ultrasonic devices serving light industrial and multi-tenant residential complexes.
- Smart Sensors:Pressure and temperature telemetry modules retrofitting existing mechanical meter bases for predictive maintenance contracts.
Most installed capacity flows through Residential Meters. Expansion is steepest in Industrial Meters.
Technology:
Technology selection determines spectrum licensing costs and building penetration depth, with licensed cellular variants requiring carrier partnerships that reshape vendor economics.
- NB-IoT:Narrowband cellular operating in licensed 800 MHz and 900 MHz bands with 10-20 dB deeper penetration than legacy GPRS. China's MIIT spectrum allocation concentrates manufacturing demand in the Yangtze River Delta cluster, achieving module scale that displaces proprietary alternatives.
- LoRa:Unlicensed sub-GHz protocol requiring private gateway infrastructure. Swiss distribution operators favor LoRa in Alpine valleys where cellular coverage gaps persist, though this fragments AMI head-end integration.
- Sigfox:Ultra-narrowband unlicensed service with national network operators in France and Spain.
- LTE-M:Higher bandwidth cellular variant supporting firmware over-the-air updates and voice-capable alarm interfaces.
NB-IoT captures dominant procurement share in European utility tenders. LTE-M is gaining share fastest among industrial users requiring bandwidth for sensor fusion.
Installation:
Installation mode dictates labor cost structure and customer disruption, with wireless retrofits avoiding excavation that dominates integrated new-build economics.
- Integrated:Meters pre-installed during building construction with conduit-embedded antennas and hardwired power. Vienna and Copenhagen municipal energy agencies mandate integrated deployment in new construction to meet net-zero building codes.
- Retrofitted:Battery-powered NB-IoT modules attached to existing mechanical meter bases without pipeline interruption. Spanish utilities accelerate retrofits ahead of 2G sunset deadlines imposed by national spectrum regulators.
- Standalone:Single-point deployments without AMI head-end integration, common in rural German distribution zones.
- Wireless:Self-contained units with integrated antennas eliminating external wiring.
Retrofitted units dominate replacement cycles. Integrated installations are climbing the fastest in Nordic new-build construction.
End User:
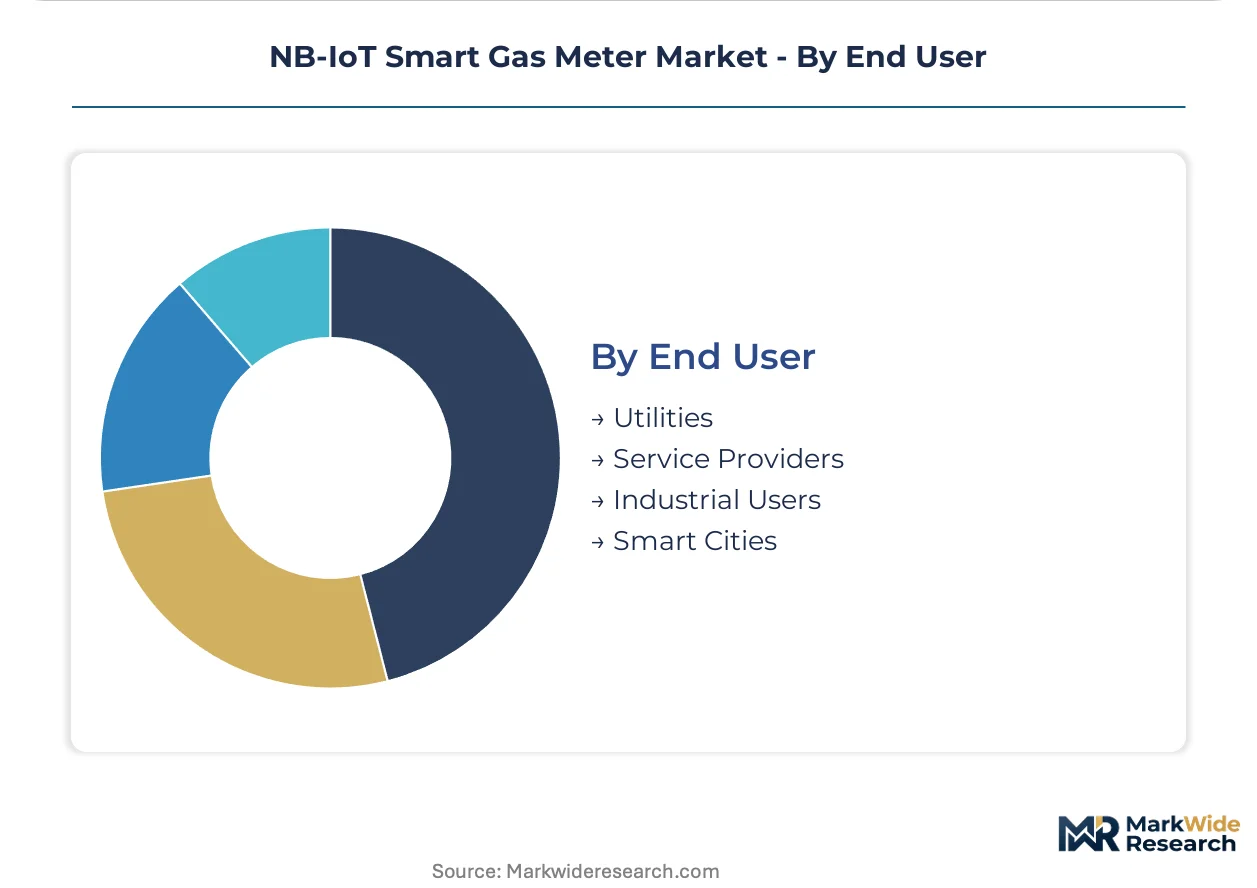
End-user type determines procurement authority and data platform requirements, with Smart Cities unbundling hardware from analytics subscriptions.
- Utilities:National and municipal gas distribution operators with AMI head-end systems and 15-20 year meter depreciation schedules. Italian utilities face compressed migration timelines under EU F-Gas Regulation methane accountability frameworks.
- Smart Cities:Municipal energy agencies in Barcelona and Vienna procuring building-level emissions data for carbon accounting platforms independent of traditional utility structures.
- Service Providers:Third-party meter operators and energy-as-a-service vendors.
- Industrial Users:Large consumers with direct custody-transfer certification requirements and private network monitoring needs.
Utilities retain dominant procurement volume. Smart Cities represent the steepest expansion trajectory as municipal net-zero mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent for narrowband cellular optimization concentrates in semiconductor hubs across Germany, China, Switzerland, and the United States, anchoring regional competitive positioning in NB-IoT module design and systems integration.
Germany
Municipal utilities in Berlin and Hamburg accelerate meter replacement cycles ahead of 2G sunset deadlines. The EU F-Gas Regulation mandates sub-percent methane leak detection accuracy that mechanical meters cannot satisfy, forcing certification of cellular-connected devices through notified bodies. Manufacturing demand clusters in North Rhine-Westphalia, where component suppliers achieve scale in licensed LPWAN radio module production.
China
The Yangtze River Delta manufacturing cluster dominates global NB-IoT module output, serving both domestic utilities and export markets. MIIT spectrum allocation at 800 MHz and 900 MHz bands standardizes licensed LPWAN deployment, eliminating fragmentation from proprietary alternatives. Shanghai and Suzhou-based fabricators supply European utilities under SAMR metrology certification requirements that extend product launch timelines.
Switzerland
Distribution operators in Zurich and Geneva pilot integrated sensor fusion architectures that unify pressure, temperature, and flow telemetry within sealed enclosures. Alpine valley deployments favor LoRa where cellular coverage gaps persist, though NB-IoT captures urban procurement share through deeper building penetration. Swissmedic-equivalent metrology standards under SAMR alignment create dual-hurdle qualification paths favoring established vendors.
Netherlands
Gas network operators in Rotterdam and Amsterdam specify industrial meters for hydrogen blend monitoring applications, where multi-gas sensor fusion commands premium positioning. National regulators compress migration timelines through spectrum refarming decisions that accelerate 2G retirement. The Randstad urban corridor leads European deployment density for building-level emissions tracking under municipal net-zero mandates.
United States
FERC jurisdictional utilities in Texas and California evaluate NB-IoT against unlicensed alternatives for AMI head-end integration, though deployment lags European adoption curves. FCC Part 15 and Part 27 licensing frameworks for cellular spectrum create carrier partnership requirements that reshape vendor economics. RF engineering talent scarcity in antenna design and power management concentrates in Silicon Valley and Austin semiconductor hubs.
NB-IoT Smart Gas Meter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the NB-IoT smart gas meter market, creating a tiered structure where scale-driven module producers coexist with regulatory affairs-heavy system integrators. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with captive AMI software stacks, focused meter OEMs with in-house radio production, and component suppliers consolidating around system-in-package chip designs. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships with municipal energy agencies for Smart Cities vertical expansion.
Among diversified industrial conglomerates, Honeywell International Inc. and Siemens occupy positions exemplifying the sensor fusion architecture tier, while Landis+Gyr Group AG represents the focused meter OEM archetype with European regulatory depth. Itron Inc. anchors the AMI software-centric positioning within the competitive landscape.
| Leading Market Players |
|---|
| Itron Inc. |
| Landis+Gyr Group AG |
| Honeywell International Inc. |
| Sensus (Xylem Inc.) |
| Apator S.A. |
| Diehl Stiftung and Co. KG |
| Siemens |
| Wasion Group Holdings Limited |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with captive radio module production anchor supply discipline and pricing power in European tender markets. Their integrated cost structures resist margin compression from Yangtze River Delta manufacturing clusters while municipal net-zero contracts unbundle hardware from SaaS subscriptions.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware procurement from AMI platform subscriptions in Copenhagen and Vienna municipal tenders. Three-tier pricing structure across premium explosion-proof, standard residential, and economy retrofit tiers reflects ATEX certification grades and volume scale. Pricing pressure stems from Chinese module scale economies displacing proprietary radio alternatives. Municipal utilities exhibit highest price sensitivity in residential volume tenders; industrial custody-transfer buyers prioritize certified accuracy over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European utilities mandate multi-supplier qualification for lithium battery cells and NB-IoT radio modules. Manufacturing concentrates in China, Germany, and Switzerland for semiconductor fabrication and systems integration. Raw material dependencies center on lithium cells, ceramic pressure sensors, and flameproof aluminum castings. Single-source vulnerability concentrates in East Asian battery chemistry suppliers. Distribution runs through national utility tender structures and municipal energy agency procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NB-IoT smart gas meter market compounds steadily as EU F-Gas Regulation mandates cellular-connected accuracy certification that mechanical meters cannot satisfy. This regulatory replacement cycle locks in decade-long demand visibility.
For Market Incumbents: Acquire RF engineering talent pools in semiconductor hubs to defend against module commoditization from Yangtze River Delta scale producers. Backward integration into lithium battery qualification programs mitigates East Asian supply concentration risk. Strengthen regulatory affairs teams to navigate dual-hurdle ETSI and SAMR certification paths that extend competitor launch timelines.
For New Entrants and Emerging Players: Hydrogen blend sensor fusion architectures offer technology-first entry into Dutch and Danish industrial meter tenders where multi-gas certification commands premium positioning. Target Smart Cities municipal energy agencies in Nordic and Alpine markets that hold direct contracting authority outside national utility structures. Lead with predictive maintenance SaaS subscriptions rather than hardware margin capture.
For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers consolidating around system-in-package chip designs that collapse meter OEM and radio supplier boundaries. Long-term viability hinges on regulatory compliance depth rather than manufacturing scale alone. Watch 2G sunset acceleration schedules as the inflection signal that compresses replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Multi-gas telemetry captures hydrogen blend monitoring premiums in Dutch network tenders. |
| AMI Platform Integration | Head-end system convergence reduces data normalization costs for mixed-fleet utilities. |
| Regulatory Certification Investment | Dual-hurdle ETSI and SAMR approval creates procurement eligibility moats in European tenders. |
| Backward Integration into Radio Modules | In-house NB-IoT production defends margin position against Yangtze River Delta module suppliers. |
| Smart Cities Vertical Partnership | Municipal net-zero contracts in Vienna and Copenhagen unbundle hardware from recurring SaaS revenue. |
Research Methodology
Bottom-up utility deployment modeling reconciled against top-down radio module production tracking forms the analytical core of this study. Primary interviews with gas distribution planning officers, AMI software architects, regulatory affairs managers, and municipal energy agency procurement leads combined with secondary validation from MIIT spectrum allocation filings, ETSI electromagnetic compatibility standards, EU F-Gas Regulation implementation directives, and SAMR metrology certification databases. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map NB-IoT module shipments through installation mode, end-user type, and technology variant dimensions across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles against regulatory migration timelines. Industry-specific forecast inputs include 2G sunset schedules by national regulator and hydrogen blend admixture targets by network operator.
The model holds under stable EU Green Deal implementation and MIIT spectrum continuity; deviation in lithium battery supply availability or F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Alcohol Sensor Market
Sensors
Vibration Monitoring Market
Sensors
Data Buoy Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Mobile Mapping Systems Market
Sensors
Traffic Sensor Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Machine Health Monitoring Market
Sensors
Europe RFID Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Global Positioning Systems Market
Sensors
Voice Sounders Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Ultrasonic Technologies Market
Sensors
Transportation Sensors Market
Sensors
Residential Water Leak Detection System Market