
 North America Data Center Networking Market | 2026-2036
North America Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Networking Market Insights
Hyperscale buyer concentration is restructuring procurement leverage across the North America Data Center Networking Market. Arista Networks, Inc. dominates high-density spine-leaf architectures for cloud-scale facilities. Cisco Systems, Inc. sustains enterprise-to-cloud transition portfolios through programmable silicon roadmaps. NVIDIA Corporation anchors AI-optimized InfiniBand and Ethernet fabrics for accelerated computing clusters.
Data center networking encompasses the switching, routing, and interconnect systems that transport traffic between servers, storage arrays, and external networks within centralized compute facilities, typically operating at 100Gbps to 800Gbps port speeds with sub-microsecond latency requirements. The primary purpose is maintaining deterministic throughput for distributed workloads spanning virtualization, artificial intelligence training, and real-time analytics. Ethernet switching captures the dominant hardware spend as cloud providers standardize on merchant silicon-based white-box platforms. InfiniBand maintains premium positioning in AI training environments where lossless transport and remote direct memory access prove essential. Hybrid deployment models are expanding fastest as enterprises retain sensitive workloads on-premises while bursting to cloud infrastructure.
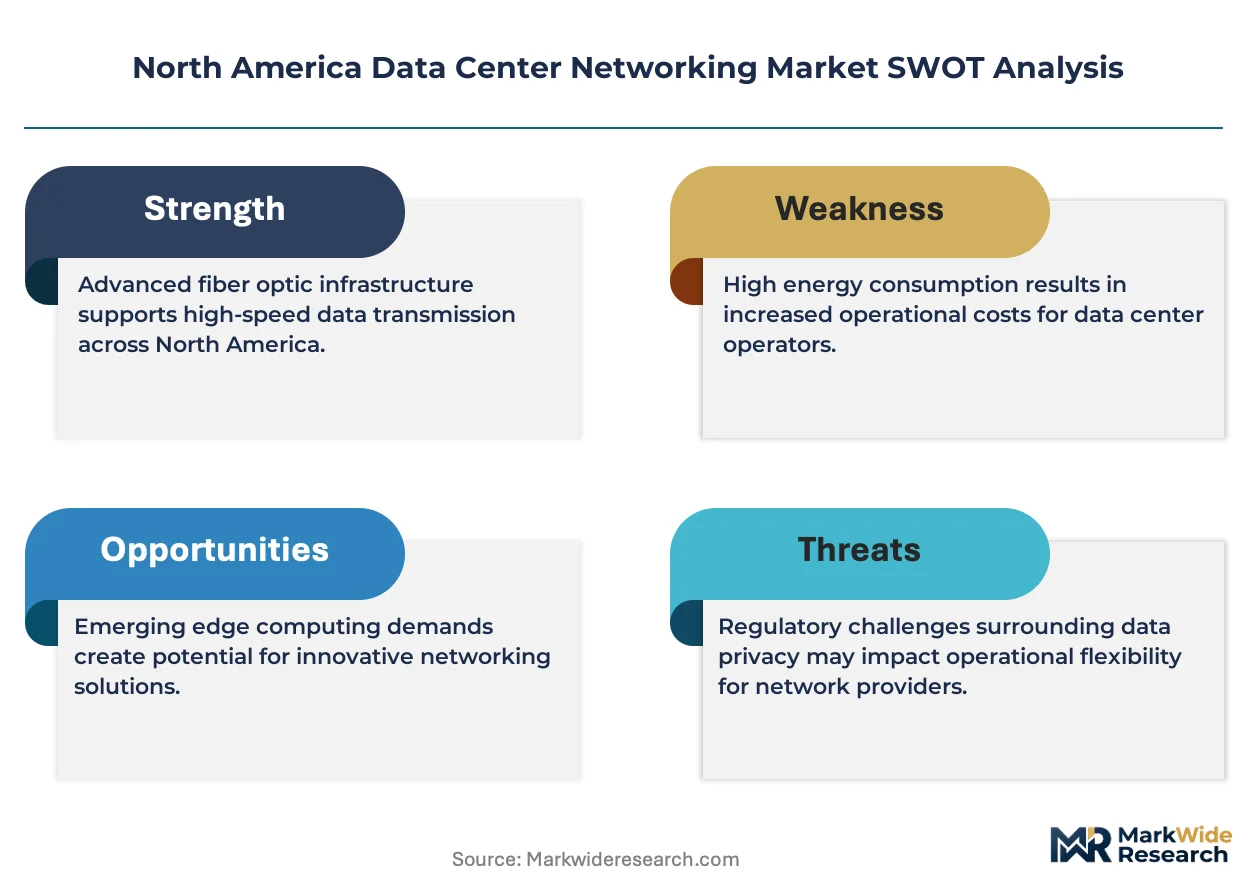
FCC spectrum and infrastructure rules, NIST zero-trust architecture mandates, and state-level renewable energy standards in Virginia and Texas shape equipment procurement timelines and power-density specifications. The EPA Energy Star for Data Centers program and OSHA electrical safety requirements further constrain facility design choices. Stakeholders must monitor how AI workload density drives port-speed migration timelines and whether domestic semiconductor incentives alter merchant silicon supply dynamics.
Market Dynamics
Hyperscale cloud providers are consolidating procurement leverage through spine-leaf architecture standardization, compressing vendor margins while accelerating port-speed migration timelines across Northern Virginia and Dallas-Fort Worth facilities.
Growth Catalysts
- NIST Zero-Trust Architecture:Federal mandates for continuous verification protocols are forcing enterprise data center refreshes of legacy switching hardware, creating replacement demand for compliant programmable silicon platforms.
- AI Training Clusters:Lossless transport requirements for large language model workloads are pulling InfiniBand and high-radix Ethernet deployments into cloud-scale facilities.
- Northern Virginia Data Center Alley:Concentrated hyperscale facility construction is driving fiber-rich backbone investments and 800Gbps port-speed adoption timelines.
Market Restraints
- Merchant Silicon Concentration:Dependence on Taiwan Semiconductor Manufacturing Company and limited domestic foundry capacity creates supply vulnerability for white-box switch ASICs.
- Power Density Constraints:EPA Energy Star for Data Centers requirements and state renewable energy standards in Virginia and Texas limit rack-level power deployment for high-throughput switching.
- Copper Interconnect Limitations:Signal integrity degradation beyond three meters at 800Gbps is restricting top-of-rack architecture flexibility in high-density facilities.
Strategic Opportunities
- Domestic Semiconductor Incentives:CHIPS Act funding for advanced packaging and foundry expansion is creating captive silicon supply opportunities for US-based switching vendors.
- Edge Colocation Hybrid Models:Enterprise retention of sensitive workloads on-premises while bursting to cloud infrastructure is expanding multi-tenant facility networking requirements.
- Co-Packaged Optics Convergence:Integration of silicon photonics with switch ASICs is enabling power-efficient 51.2Tbps aggregate throughput for next-generation spine architectures.
Industry Challenges
- Optical Engineering Talent Scarcity:Shortage of designers experienced in co-packaged optics and silicon photonics integration is extending product development cycles.
- Multi-Vendor Interoperability Certification:Complex conformance testing across merchant silicon, optics, and network operating system combinations delays production deployments.
- Legacy Three-Tier Architecture Migration:Enterprise data centers face forklift upgrade requirements to transition from chassis-based core-aggregation-access to spine-leaf topologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Networking Market |
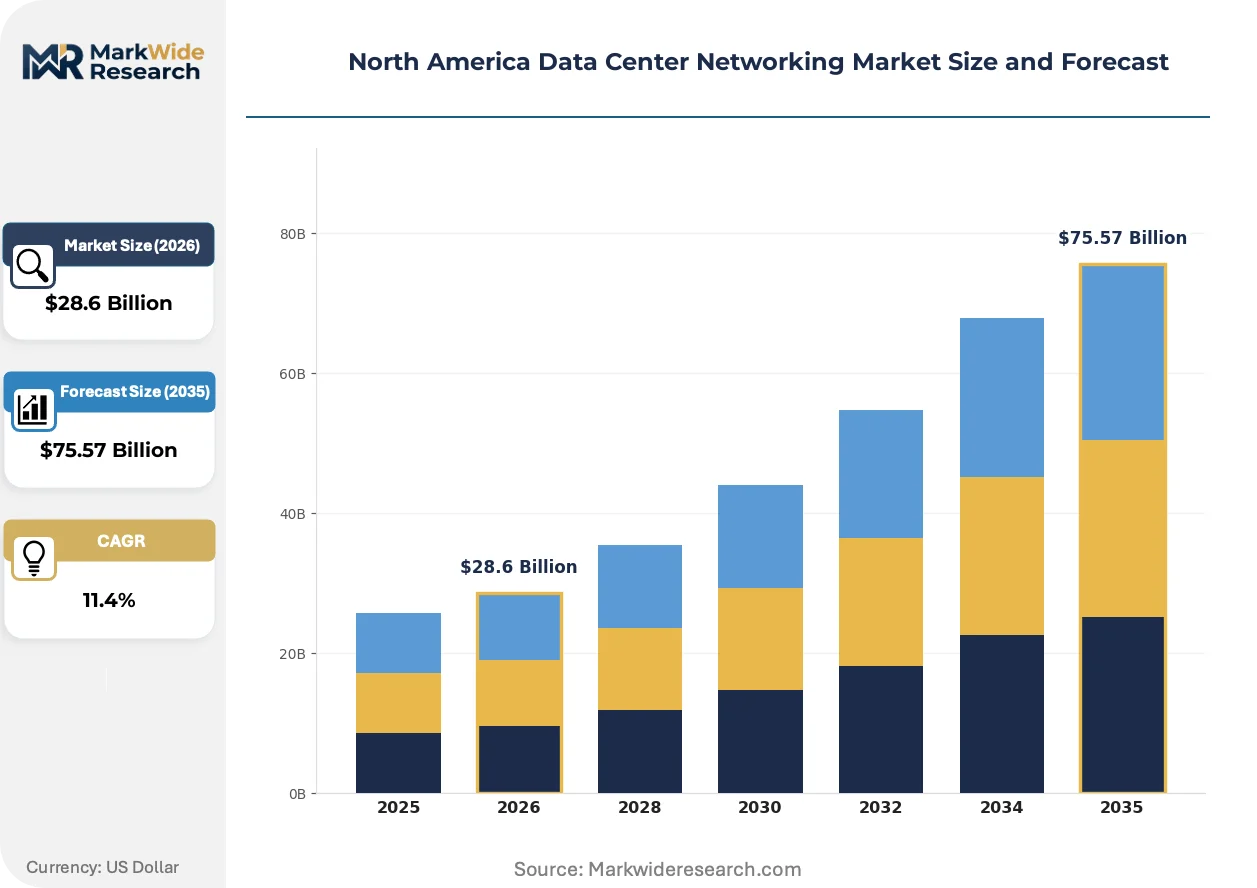
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Firewalls, Load Balancers Technology: Ethernet, InfiniBand, Fibre Channel, MPLS End User: Cloud Providers, Telecom Operators, Enterprises, Hosting Services Deployment Model: On-Premises, Hybrid, Cloud, Managed |
| Companies Covered | Cisco Systems, Inc., Arista Networks, Inc., Juniper Networks, Inc., Hewlett Packard Enterprise Company, Dell Technologies Inc., NVIDIA Corporation, Huawei Technologies Co. Ltd., Broadcom Inc., Ciena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Networking Market Trends and Innovations
Active optical cabling and co-packaged photonics are compressing power-per-bit metrics while federal zero-trust mandates reconfigure hardware procurement specifications across cloud and enterprise facilities.
Co-packaged optics is expanding into spine-layer switches by integrating silicon photonics directly onto switch ASIC substrates, eliminating pluggable transceiver power overhead. Cloud providers are deploying these platforms in new Northern Virginia facilities to support 51.2Tbps aggregate throughput per switch node. This convergence is expanding into merchant silicon roadmaps, forcing traditional pluggable optics vendors to reposition toward linear drive and external laser source components.
FCC infrastructure rules governing spectrum allocation for wireless backhaul are indirectly shaping data center interconnection demand, as 5G edge computing requirements pull fiber deployment toward metro cell sites. NIST cybersecurity frameworks mandating micro-segmentation are accelerating hardware refresh cycles for switches lacking programmable pipeline support. Enterprise buyers in regulated sectors—healthcare under HIPAA and financial services under SEC cybersecurity guidance—are prioritizing switches with embedded MACsec encryption and hardware-rooted trust modules.
Hyperscale self-assembly of network operating systems is displacing traditional vendor-integrated platforms, with cloud providers compiling open-source routing stacks onto merchant silicon white-box switches. This disintermediation compresses value capture for incumbent networking vendors while expanding contract manufacturing demand for original design manufacturers. The pattern is most visible among top-five US cloud operators, who now specify custom thermal and power designs for facility-specific deployment templates.
North America Data Center Networking Market Segmentation
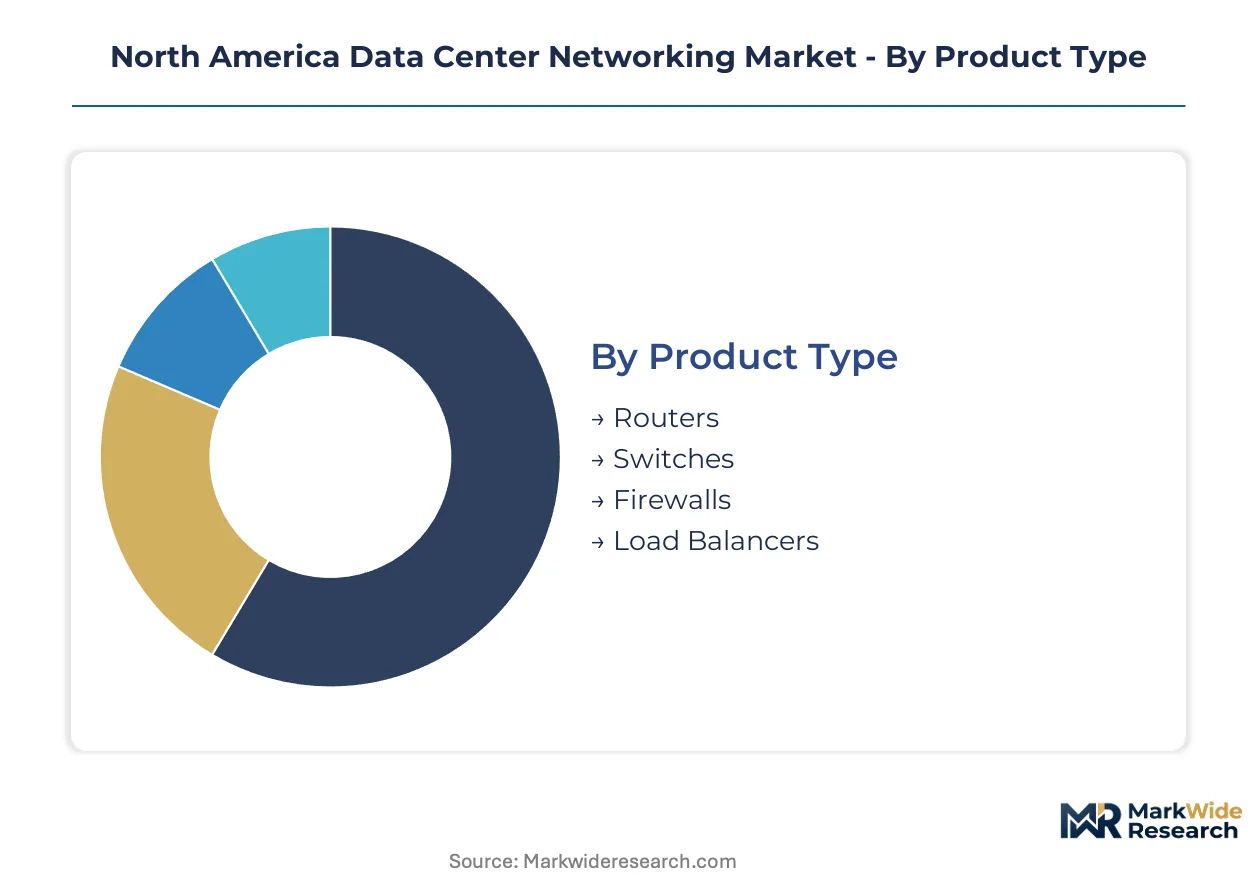
Segmentation in the North America Data Center Networking Market reveals how procurement patterns diverge between hyperscale cloud operators and enterprise buyers. Understanding these splits enables vendors to align silicon roadmaps, port-speed transitions, and compliance features with distinct customer requirements across Virginia, Texas, and secondary markets.
Product Type:
Volume hardware procurement concentrates in high-port-density switching platforms, while premium spend flows toward programmable routing and security appliances with embedded encryption.
- Switches:Spine-leaf architectures dominate hyperscale deployments, with 400Gbps to 800Gbps port speeds now standard in Northern Virginia facilities. Cloud providers in Dallas-Fort Worth are driving merchant silicon white-box adoption for top-of-rack and aggregation layers.
- Routers:Border gateway platforms handle inter-facility traffic across Data Center Alley, where fiber-rich backbones require high-radix fabrics with sub-microsecond convergence. NIST zero-trust mandates are accelerating refreshes of legacy core routers lacking programmable pipeline support.
- Firewalls:Hardware appliances with hardware-rooted trust modules address HIPAA and SEC cybersecurity guidance for financial services and healthcare enterprises retaining sensitive workloads on-premises.
- Load Balancers:Application delivery controllers are standardizing on merchant silicon with DPU offloading for TLS termination at scale in multi-tenant hosting environments.
Mature deployment sits with switches. Newer deployment is concentrated in firewalls with embedded MACsec encryption.
Technology:
Cost tier separation runs through transport protocol selection, with lossless fabrics commanding premium positioning against commodity Ethernet.
- Ethernet:Merchant silicon-based 100Gbps to 800Gbps dominates cloud provider procurement, with IEEE 802.3ck driving 800Gbps standardization across hyperscale facilities. The EPA Energy Star for Data Centers program shapes power-efficiency specifications for switching hardware.
- InfiniBand:Lossless transport and remote direct memory access capabilities anchor AI training clusters, where NVIDIA fabrics connect GPU nodes in accelerated computing deployments. Premium positioning reflects the protocol's essential role in large language model workloads.
- Fibre Channel:Storage area networking persists in enterprise data centers with legacy SAN investments, though convergence toward NVMe over Ethernet is compressing refresh demand.
- MPLS:Traffic engineering for multi-site enterprise connectivity remains relevant in regulated sectors requiring deterministic latency for financial trading applications.
Enterprise retention of Fibre Channel is stabilizing. Cloud provider infrastructure is climbing the fastest toward InfiniBand and high-radix Ethernet.
End User:
Customer type determines procurement leverage, with concentrated hyperscale buyers extracting custom silicon specifications against fragmented enterprise demand.
- Cloud Providers:Self-assembly of network operating systems onto white-box switches displaces vendor-integrated platforms, with top-five US operators specifying custom thermal and power designs. OSHA electrical safety requirements constrain rack-level deployment templates.
- Enterprises:Regulated sectors under HIPAA and SEC guidance prioritize switches with embedded encryption, driving refresh cycles for legacy three-tier architectures in healthcare and financial services.
- Telecom Operators:5G edge computing requirements pull fiber deployment toward metro cell sites, expanding interconnection demand for distributed data center networking.
- Hosting Services:Multi-tenant colocation facilities require flexible cross-connect and interconnection platforms serving hybrid cloud bursting scenarios.
Telecom operator deployment is expanding most quickly at the edge. Cloud provider procurement represents the steepest expansion trajectory for high-radix fabrics.
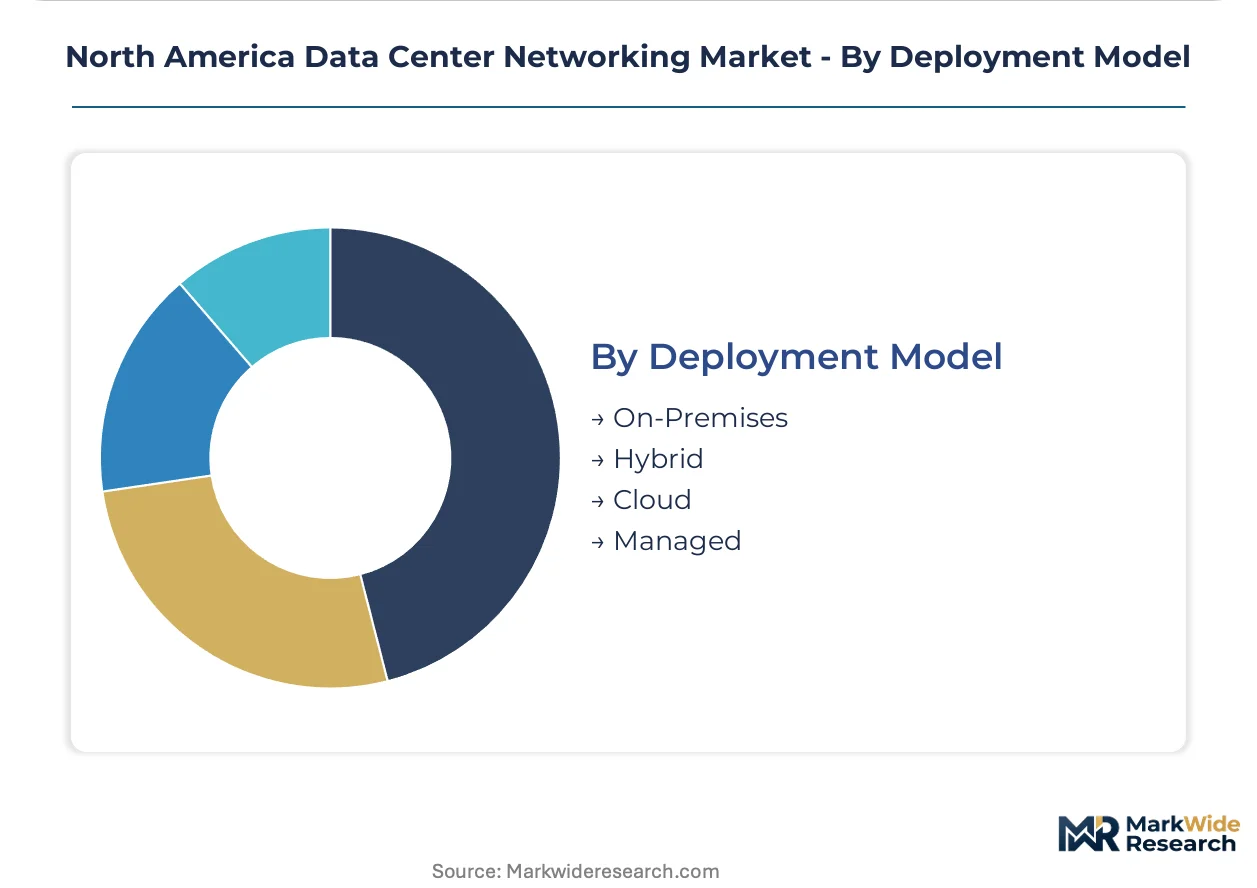
Deployment Model:
Margin structure varies by operational responsibility, with managed services capturing ongoing revenue against capital-intensive on-premises ownership.
- On-Premises:Enterprise retention of sensitive workloads drives hardware procurement for facilities subject to state renewable energy standards in Virginia and Texas, where power density constraints limit rack-level switching deployment.
- Hybrid:Bursting architectures combine on-premises infrastructure with cloud interconnect, requiring consistent networking policies across facility boundaries.
- Cloud:Hyperscale provider-owned facilities standardize on spine-leaf topologies with co-packaged optics for power-efficient throughput.
- Managed:Third-party operation of networking infrastructure appeals to mid-market enterprises lacking internal optical engineering talent for silicon photonics integration.
On-premises ownership dominates regulated sectors. Hybrid deployment is gaining share fastest as enterprises balance control with cloud scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale facility construction concentrates procurement leverage across specific sub-regional clusters, with regulatory frameworks and power availability shaping deployment timelines.
United States
Northern Virginia's Data Center Alley and the Dallas-Fort Worth metroplex anchor hyperscale expansion, driven by fiber-rich backbone investments and tax incentive programs. NIST zero-trust architecture mandates accelerate enterprise switching hardware refreshes. Loudoun County facilities push 800Gbps port-speed adoption timelines.
Canada
Hyperscale providers target Quebec and Ontario for renewable hydroelectric power and cooler climates reducing cooling costs. Canada's national privacy regulator enforces data sovereignty requirements favoring domestic facility construction. Montreal and Toronto clusters attract cloud provider investment for AI training workloads.
Mexico
Querétaro and Mexico City metro areas emerge as edge computing hubs serving Latin American latency requirements. Mexico's federal telecommunications regulator governs spectrum allocation for 5G backhaul driving fiber interconnection demand. Monterrey industrial corridor hosts enterprise colocation facilities.
North America Data Center Networking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue merchant silicon specialization and co-packaged optics integration. The vendor base stratifies across three tiers: integrated platform providers, white-box original design manufacturers, and component-level specialists. Strategic archetypes include spine-leaf architecture standardizers, AI-optimized fabric vendors, and programmable silicon roadmappers. Competitive moves center on strategic partnerships for optical engineering talent and portfolio diversification toward security-embedded switching.
Within the integrated platform tier, Cisco Systems, Inc. and Arista Networks, Inc. exemplify contrasting approaches to enterprise and cloud-scale deployment. NVIDIA Corporation anchors the AI-optimized fabric archetype through InfiniBand and accelerated Ethernet positioning. These three entities represent the dominant competitive anchors shaping procurement specifications across hyperscale and regulated enterprise segments.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Arista Networks, Inc. |
| Juniper Networks, Inc. |
| Hewlett Packard Enterprise Company |
| Dell Technologies Inc. |
| NVIDIA Corporation |
| Huawei Technologies Co. Ltd. |
| Broadcom Inc. |
| Ciena Corporation |
| Others |
Pricing and Supply Chain Analysis
Merchant silicon wafer costs cascade through three pricing tiers, starting with Taiwan Semiconductor Manufacturing Company's foundry pricing and compressing margins for white-box switch vendors serving hyperscale cloud providers in Northern Virginia and Dallas-Fort Worth.
Pricing Analysis
Volume hyperscale procurement extracts steep discounts against premium-tier enterprise switching carrying NIST zero-trust compliance premiums. Price differentiation hinges on port-speed tier and embedded encryption certification, with 800Gbps spine switches commanding substantial premiums over 400Gbps aggregation hardware. Cost compression in merchant silicon white-box platforms is intensifying because cloud providers self-assemble network operating systems, squeezing traditional vendor margins. Enterprise buyers under HIPAA and SEC cybersecurity guidance exhibit lowest price sensitivity, while mid-market colocation operators represent the most price-conscious segment.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing Company's advanced node capacity for switch ASICs, constraining white-box vendor output timelines. Manufacturing concentrates in Taiwan, South Korea, and the United States for merchant silicon, while optics and passive components draw from China and Malaysia. Raw material dependencies span silicon wafers, indium phosphide for photonics, and rare earth elements for magnetics in power supplies. Tariff exposure on Chinese optical components threatens cost structures for pluggable transceiver vendors. Distribution runs through direct procurement contracts between hyperscale operators and original design manufacturers, bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIST zero-trust architecture mandates function as a cost-of-compliance moat, forcing enterprise refreshes that favor incumbent vendors with certified programmable silicon platforms and hardware-rooted trust modules.
For Market Incumbents: Deploy co-packaged optics roadmaps to defend spine-layer positioning against merchant silicon challengers. Deepen backward integration into silicon photonics design to offset optical engineering talent scarcity. Consolidate enterprise switching portfolios around MACsec-embedded platforms to capture HIPAA and SEC-mandated refresh cycles. Target acquisition of linear drive optics specialists to reposition against pluggable transceiver commoditization.
For New Entrants and Emerging Players: A substantial price-point gap between NVIDIA's InfiniBand premiums and commodity Ethernet white-boxes opens white-space in AI-optimized Ethernet fabrics for mid-scale training clusters. Target edge colocation facilities in Querétaro and Mexico City where latency requirements outrun hyperscale backbone reach. Penetrate through managed service wrappers that bundle switching hardware with operational support, appealing to enterprises lacking internal optical engineering capabilities.
For Investors and Strategic Acquirers: CHIPS Act foundry subsidy announcements are the leading indicator that domestic merchant silicon supply will reshape procurement leverage toward US-based switching vendors. Frame long-term viability around captive silicon access and co-packaged optics integration depth rather than legacy chassis portfolios. Target acquisition of original design manufacturers with established hyperscale relationships and custom thermal design capabilities. Monitor port-speed migration timelines at 800Gbps and 1.6Tbps as the inflection signal for next-generation spine architecture deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Eliminates pluggable transceiver power overhead for 51.2Tbps spine switches in Northern Virginia facilities. |
| Merchant Silicon Roadmap Alignment | Secures foundry allocation for white-box ASICs serving hyperscale procurement specifications. |
| Zero-Trust Certification Investment | Unlocks enterprise replacement demand under NIST mandates and SEC cybersecurity guidance. |
| Silicon Photonics Talent Acquisition | Addresses optical engineering scarcity extending product development cycles for next-generation platforms. |
| Edge Colocation Partnership | Captures hybrid cloud bursting demand from regulated enterprises retaining sensitive on-premises workloads. |
Research Methodology
Multi-period observation of hyperscale capex disclosures, port-speed adoption timelines, and NIST compliance certification patterns anchored the trend analysis, supplemented by interviews with data center facility engineers, network architects at cloud providers, procurement officers at financial services firms, and optical component specialists. Secondary validation drew from SEC filings, FCC infrastructure rulemakings, EPA Energy Star program data, and hyperscaler facility expansion announcements. Bottom-up triangulation across merchant silicon vendor shipments and top-down reconciliation against aggregate facility investment flows ensured cross-verified volume estimates.
Segment-weighting applied differential growth assumptions across deployment models, with hybrid architectures receiving elevated weighting reflecting fastest-expanding enterprise adoption. Technology splits modeled Ethernet against InfiniBand penetration based on AI training cluster announcements and GPU interconnect specifications. End-user segmentation weighted cloud provider procurement concentration against fragmented enterprise demand across regulated sectors. CAGRs were derived from facility construction pipeline analysis and port-speed migration elasticity estimates.
Inputs from hyperscale operator procurement teams and original design manufacturer production schedules were available through the study window; gaps in confidential merchant silicon foundry utilization rates introduce uncertainty bands around white-box switch supply forecasts. Deviation in CHIPS Act funding disbursement timelines or Taiwan Semiconductor Manufacturing Company capacity allocation priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Mobile Data Market