
 Eye Tracking Solutions Market | 2026-2036
Eye Tracking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Tracking Solutions Market Analysis
Asian sensor fabs is shifting toward high-resolution infrared arrays for eye tracking modules. Tobii AB leverages its vertical integration across optics and firmware to dominate desktop research systems. Seeing Machines Ltd. anchors driver monitoring contracts with automotive OEMs in Japan and Europe. Smart Eye AB specializes in embedded AI gaze estimation for next-generation vehicle cabins.
Eye tracking solutions employ infrared illumination and corneal reflection mapping to compute point-of-gaze coordinates with sub-degree accuracy, serving applications from usability testing to neurological assessment. Video-based optical tracking leads in installed base across academic institutions, while wearable devices represent the fastest-expanding device category as AR headset manufacturers integrate gaze-contingent rendering. Desktop systems retain the deepest margin pools in clinical diagnostics where precision certification commands premium positioning.
FDA software-as-a-medical-device guidance shapes validation requirements for clinical eye tracking systems in the United States, while EU AI Act risk classifications affect automated emotion recognition deployments in European retail environments. Japan's METI funds gaze-interface standards for aging-population accessibility tools. Stakeholders must monitor evolving biometric consent frameworks across jurisdictions to preserve market access for consumer-facing applications.
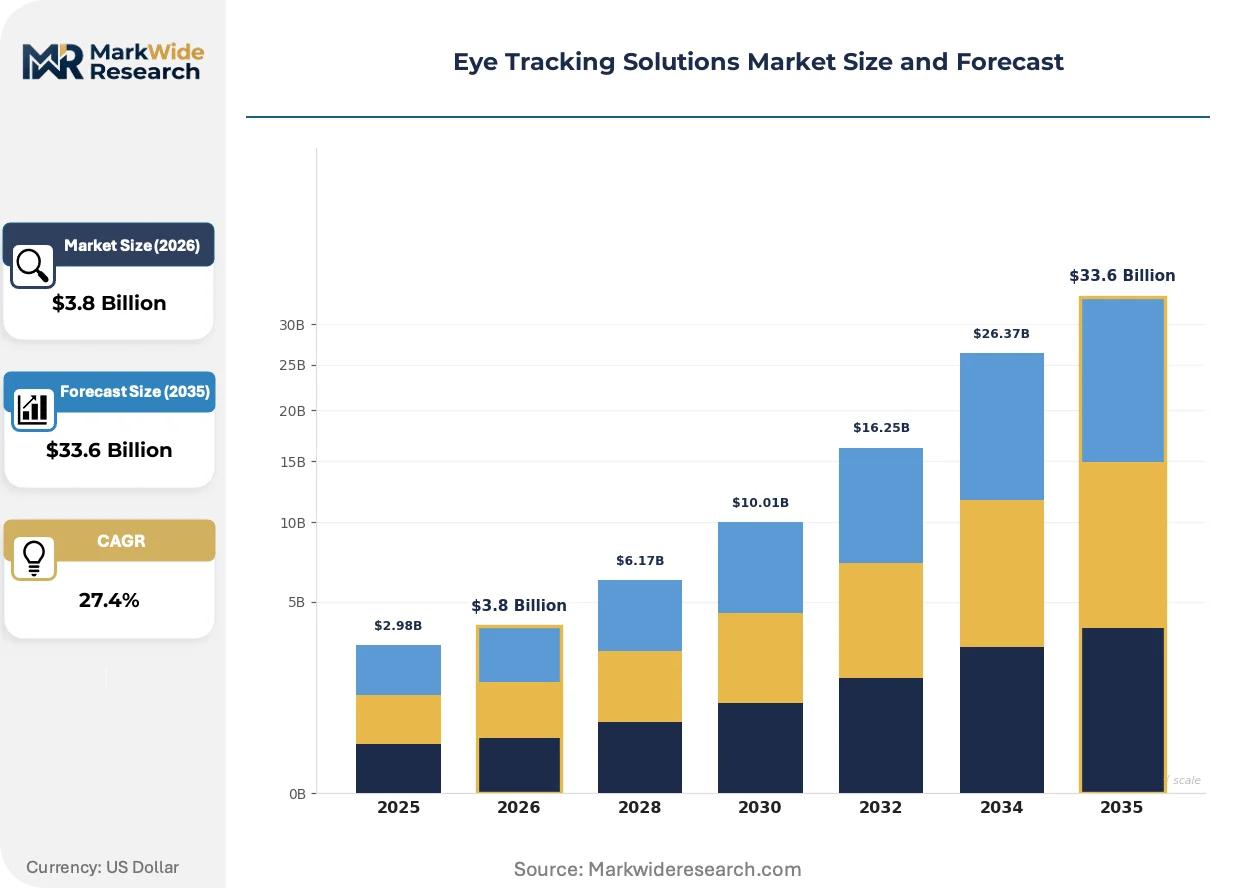
Market Dynamics
The automotive industry's mandatory integration of driver monitoring systems is compressing development cycles for gaze-tracking hardware, forcing suppliers to reconcile clinical-grade precision with automotive cost structures and validation timelines.
Growth Catalysts
- FDA software-as-a-medical-device guidance:The FDA's evolving framework for clinical eye tracking systems in the United States is accelerating validation protocols for neurological diagnostic tools, creating compliant pathways for hospital procurement.
- EU AI Act risk classifications:Automated emotion recognition deployments in European retail environments now face structured compliance requirements, which formalized vendors with pre-certified systems are exploiting to displace unvalidated competitors.
- Japan's METI gaze-interface standards:METI-funded accessibility initiatives for aging populations are standardizing low-latency eye-control protocols, opening institutional procurement channels for assistive technology manufacturers.
Market Restraints
- Infrared sensor supply concentration:High-resolution IR array production clusters in East Asian foundries expose module assemblers to single-source vulnerability and foundry allocation priority shifts toward larger semiconductor customers.
- Clinical certification cost barriers:FDA 510(k) and EU MDR conformity assessment timelines for diagnostic eye tracking systems extend 18-36 months, freezing out capital-constrained entrants from premium-margin healthcare segments.
- Camera-based mobile tracking substitution:Smartphone front-facing camera arrays with AI-driven gaze estimation are capturing low-accuracy use cases in consumer research and casual gaming, compressing addressable volume for dedicated hardware.
Strategic Opportunities
- AR/VR headset integration white space:Gaze-contingent rendering in next-generation mixed reality hardware is expanding module attach rates as foveated display drivers reduce GPU thermal loads and extend battery runtime.
- German automotive R&D corridor concentration:OEM driver monitoring mandates are concentrating engineering partnerships around Stuttgart and Munich, creating captive demand for tier-one suppliers with localized validation capabilities.
- Biometric consent framework harmonization:Jurisdictions including California's CCPA amendments and Brazil's LGPD are clarifying gaze data retention rules, enabling compliant consumer-facing deployments in retail analytics and digital signage.
Industry Challenges
- Embedded AI firmware talent scarcity:Gaze estimation algorithm optimization for automotive-grade MCUs requires rare combinations of computer vision and low-power embedded engineering, extending recruitment cycles to 8-14 months.
- Multi-domain certification complexity:Suppliers serving both clinical and automotive verticals must maintain parallel ISO 13485 and IATF 16949 quality systems, duplicating audit overhead without volume synergies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Tracking Solutions Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $33.6 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical, Video-Based, Electrooculography, Infrared Application: Gaming, Healthcare, Market Research, Human-Computer Interaction End User: Academic Institutions, Clinical Facilities, Retailers, Product Developers Device Type: Wearable Devices, Desktop Systems, Mobile Applications, Fixed Systems |
| Companies Covered | Tobii AB, Seeing Machines Ltd., Smart Eye AB, SR Research Ltd., EyeTech Digital Systems Inc., EyeTracking Inc., iMotions A/S, Gazepoint Research Inc., LC Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Tracking Solutions Market Emerging Trajectories
Silicon photonics and neuromorphic sensor architectures are collapsing the latency-accuracy tradeoff that historically separated research-grade from consumer-grade eye tracking, enabling unified hardware platforms across price tiers.
Event-based vision sensors with microsecond temporal resolution are expanding into automotive driver monitoring systems, where Tier-1 suppliers are adopting them to capture microsaccade patterns for drowsiness detection that frame-based cameras miss. The technology is expanding into adjacent cabin monitoring applications including occupant position tracking and gesture recognition, consolidating multiple sensing modalities behind single hardware footprints.
The EU AI Act's prohibition on real-time biometric identification in public spaces is reshaping retail analytics deployments, forcing platform vendors to rearchitect cloud processing pipelines toward on-device inference with immediate data deletion. German and French retail chains are piloting edge-only gaze heatmap systems that preserve anonymity while satisfying CSRD-mandated customer experience metrics.
Academic research institutions are consolidating procurement around subscription-based eye tracking platform licenses, displacing perpetual hardware ownership models. University technology transfer offices in the United States and United Kingdom are negotiating enterprise-wide site licenses with cloud-based data collaboration features, compressing vendor sales cycles while locking in multi-year recurring revenue streams for platform providers with established research software ecosystems.
Eye Tracking Solutions Market Segmentation
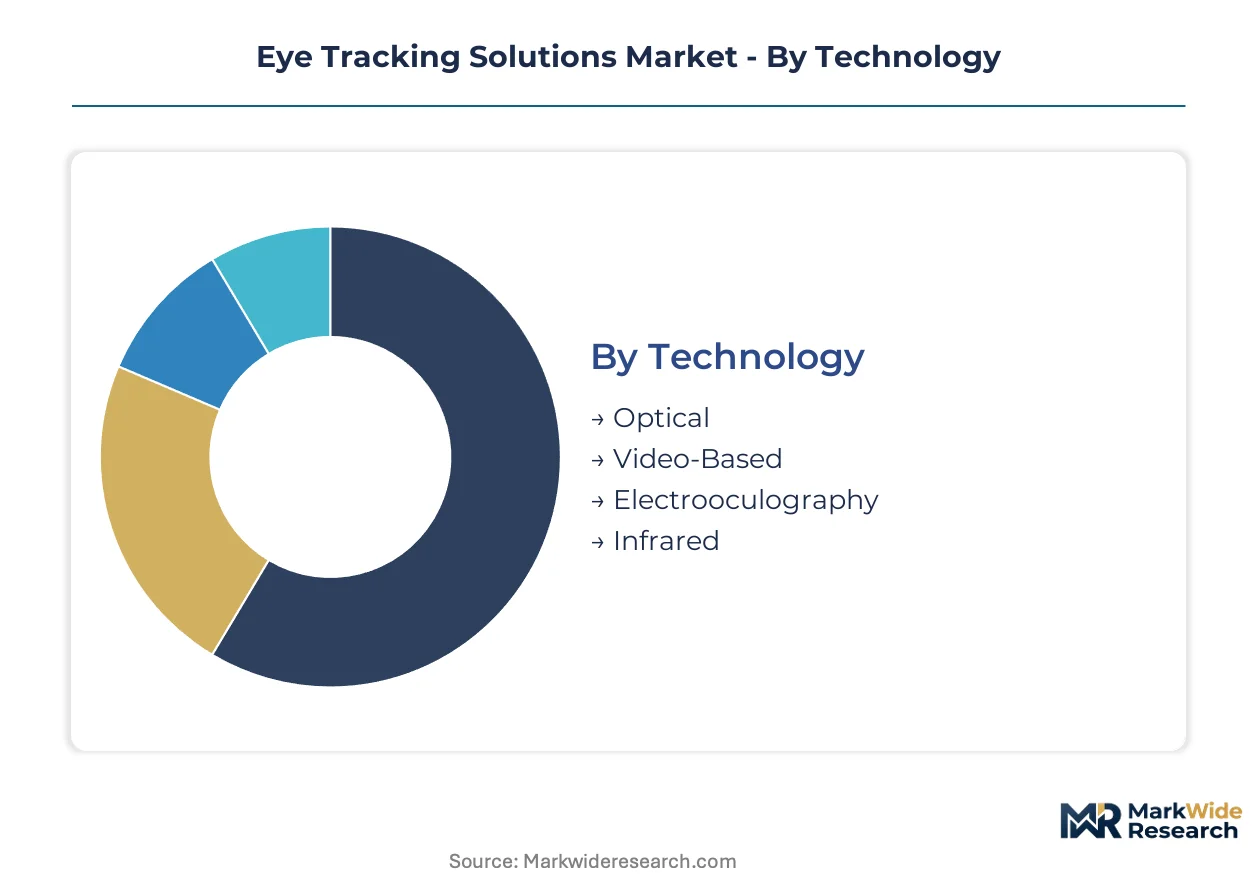
Eye tracking solutions fragment across hardware architectures, software deployment modes, and precision requirements that reshape procurement patterns. Vendors must match sensor specifications to validation tiers that separate clinical diagnostics from consumer gaming applications.
Technology:
Customization intensity varies from turnkey firmware stacks to bespoke optical assemblies requiring cleanroom calibration.
- Optical:Corneal reflection and pupil center detection algorithms process visible-spectrum imagery through standard CMOS sensors. Academic laboratories in Germany and Japan concentrate procurement for behavioral research requiring sub-degree accuracy without infrared illumination constraints.
- Video-Based:Frame-based camera arrays capture full-field gaze data at 60-120Hz for usability testing and marketing analytics. Demand clusters with product developers in California's UX research corridor seeking plug-and-play deployment without specialized hardware.
- Electrooculography:Skin-contact electrodes measure corneo-retinal potential differences for sleep research and vestibular diagnostics. Clinical facilities in the United Kingdom deploy these systems where optical tracking fails due to eyelid closure or extreme gaze angles.
- Infrared:Near-IR illumination penetrates tinted eyewear and operates in darkness for automotive cabin monitoring. Tier-1 suppliers in Stuttgart integrate these modules into driver monitoring systems mandated by NHTSA-equivalent regulators.
Most installed capacity flows through Video-Based systems. Expansion is steepest in Infrared as automotive OEMs consolidate sensing architectures.
Application:
Price tolerance spans three orders of magnitude from disposable consumer research tools to FDA-validated neurological platforms.
- Gaming:Low-latency gaze estimation enables foveated rendering in VR headsets, reducing GPU load by 30-50%. Hardware manufacturers in Taiwan and South Korea attach these modules to next-generation mixed reality devices targeting enthusiast segments.
- Healthcare:FDA 510(k) and EU MDR certification requirements separate diagnostic-grade systems from wellness applications. Neurology departments in the United States procure these for concussion assessment and progressive disease monitoring where gaze pattern biomarkers replace invasive procedures.
- Market Research:Shelf-fixation analytics and advertisement heatmapping drive retailer adoption in France and Germany. CSRD disclosure requirements are accelerating procurement as customer experience metrics enter mandatory sustainability reporting.
- Human-Computer Interaction:Accessibility interfaces for motor-impaired users and hands-free industrial control dominate institutional procurement. Japan's METI-funded standards initiatives are opening municipal procurement channels for aging-population deployment.
Healthcare commands the deepest margin pools. Gaming represents the fastest-growing trajectory as headset attach rates climb.
End User:
Volume concentration favors site-license arrangements while precision requirements drive perpetual hardware ownership.
- Academic Institutions:University technology transfer offices negotiate enterprise-wide platform licenses with cloud collaboration features. Research consortia in the United Kingdom and Netherlands are displacing individual laboratory purchases with shared infrastructure models.
- Clinical Facilities:Hospital procurement committees require ISO 13485 quality systems and FDA 510(k) clearance for neurological diagnostic tools. Neurology and ophthalmology departments in the United States concentrate demand for concussion and strabismus assessment protocols.
- Retailers:French and German retail chains pilot edge-only gaze heatmap systems satisfying EU AI Act anonymity requirements while meeting CSRD customer experience disclosure mandates.
- Product Developers:UX research teams in California and New York integrate eye tracking into iterative design sprints. SaaS platform subscriptions are displacing hardware purchases for remote unmoderated testing workflows.
Academic Institutions anchor baseline volume. Product Developers are gaining share fastest as remote research tools democratize access.
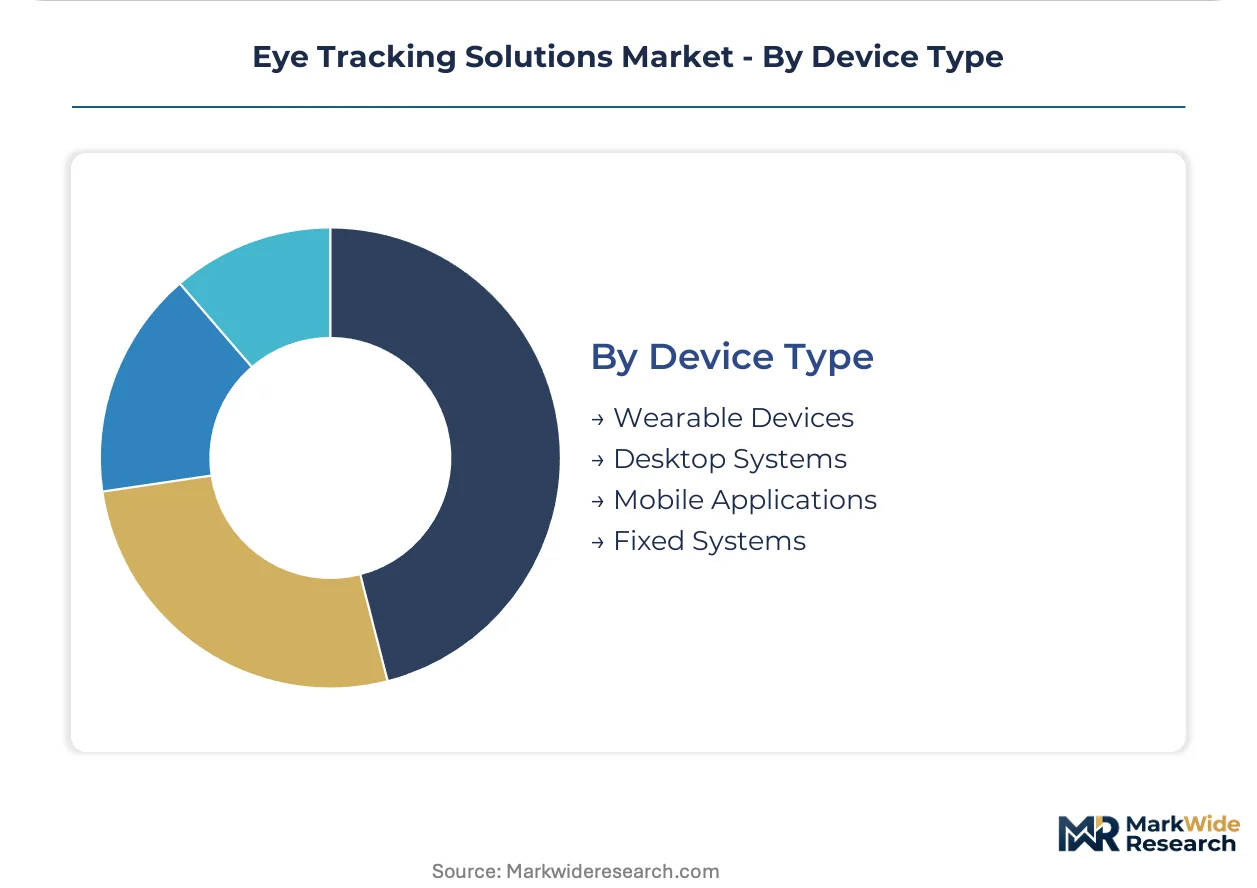
Device Type:
Form factor selection trades spatial precision against mobility and ambient light immunity.
- Wearable Devices:Head-mounted displays and smart glasses integrate micro-optics for AR gaze-contingent rendering. Manufacturers in Taiwan and China concentrate production for next-generation mixed reality hardware.
- Desktop Systems:Remote eye trackers with chin rests deliver laboratory-grade precision for clinical diagnostics. German and United States neurological research centers maintain installed bases despite cloud-platform migration pressure.
- Mobile Applications:Smartphone front-facing cameras with AI-driven gaze estimation capture casual research and gaming use cases. Consumer app developers in South Korea and India deploy these for accessibility features and attention analytics.
- Fixed Systems:Kiosk-integrated sensors enable hands-free public interface control in healthcare and transportation settings. Japan's rail operators and airport authorities deploy these for aging-population accessibility compliance.
Desktop Systems retain the deepest installed base. Wearable Devices show the steepest expansion curve as AR headset shipments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting module assembly toward jurisdictions with streamlined medical-device validation pathways, while automotive-grade certification requirements concentrate engineering partnerships in established testing corridors.
United States
FDA software-as-a-medical-device guidance accelerates hospital procurement of neurological diagnostic tools. Neurology departments in Boston and Baltimore concentrate demand for concussion assessment protocols. California's UX research corridor sustains subscription-based platform adoption for remote product testing workflows.
Germany
OEM driver monitoring mandates under EU General Safety Regulation compress development cycles for gaze-tracking hardware. Stuttgart and Munich anchor engineering partnerships between tier-one suppliers and automotive manufacturers. KBA validation protocols shape module specifications for cabin-integrated systems.
Japan
METI-funded gaze-interface standards open municipal procurement channels for aging-population accessibility tools. Rail operators and airport authorities in Tokyo and Osaka deploy fixed kiosk systems for hands-free public interface control. PMDA consultation pathways guide clinical-grade system development.
China
MIIT standards for intelligent vehicle cabins mandate driver fatigue monitoring in commercial fleets. Yangtze River Delta sensor fabs shift capacity toward high-resolution infrared arrays for automotive modules. NMPA medical device classification rules separate diagnostic-grade from wellness applications.
United Kingdom
University technology transfer offices negotiate enterprise-wide platform licenses with cloud collaboration features. Research consortia in Cambridge and Oxford displace individual laboratory purchases with shared infrastructure models. MHRA post-Brexit conformity assessment timelines extend for clinical eye tracking systems.
Eye Tracking Solutions Market Vendor Landscape
Swedish producers anchor the premium research-system tier; Australian specialists hold automotive driver monitoring contracts. The vendor base stratifies across three layers: vertically integrated optics manufacturers, embedded AI firmware developers, and SaaS platform aggregators. Dominant competitive moves include backward integration into infrared sensor supply and geographic expansion through localized validation partnerships.
Within the integrated-optics tier, Tobii AB exemplifies vertical control across hardware and software stacks. Seeing Machines Ltd. and Smart Eye AB occupy positions in the automotive-embedded segment, representing contrasting approaches to driver monitoring system deployment. These three anchors illustrate how specialization depth separates research-grade precision from automotive cost-optimization imperatives.
| Leading Market Players |
|---|
| Tobii AB |
| Seeing Machines Ltd. |
| Smart Eye AB |
| SR Research Ltd. |
| EyeTech Digital Systems Inc. |
| EyeTracking Inc. |
| iMotions A/S |
| Gazepoint Research Inc. |
| LC Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Infrared LED wafer pricing indices from Taiwanese foundries cascade through module assembly tiers, compressing margins for mid-range eye tracking systems while premium clinical-grade hardware retains pricing power through FDA validation barriers.
Pricing Analysis
Distributor markups of 15-25% separate factory-gate module costs from end-user system prices across automotive and healthcare verticals. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—FDA 510(k) cleared diagnostic platforms command 4-6x premiums over uncertified research tools. Cost compression in standard-tier video-based systems is intensifying because smartphone camera substitution erodes dedicated hardware volumes. Academic institutions show highest price sensitivity, while hospital procurement committees prioritize validation status over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart and Munich automotive engineering centers, bypassing distribution layers for driver monitoring module contracts. High-resolution CMOS sensor fabrication concentrates in Taiwan, South Korea, and Japan, while near-infrared LED epitaxy draws from Chinese and Taiwanese compound semiconductor foundries. Supply chain vulnerability rests on single-source dependencies for automotive-grade infrared arrays qualified to AEC-Q100 standards. Distribution runs through tier-one automotive electronics suppliers and specialized medical device distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Eye Tracking Solutions Market functions as a stable compounder anchored by mandatory automotive safety regulations that institutionalize recurring OEM procurement cycles regardless of macroeconomic cycles.
For Market Incumbents: Extend firmware development partnerships with German KBA-validated tier-one suppliers to lock in driver monitoring platform positions against emerging Chinese sensor module competitors. Deepen backward integration into infrared sensor supply through joint ventures with Taiwanese foundries to neutralize allocation priority risks from larger semiconductor customers. Prioritize ISO 13485 quality system maintenance alongside IATF 16949 certification to serve parallel clinical and automotive verticals without audit duplication. For New Entrants and Emerging Players: The gap between premium FDA-validated diagnostic systems and economy-tier consumer research tools creates entry space for mid-market SaaS platforms with cloud-native analytics. Target accessibility interface deployments in Japanese municipal procurement channels opened by METI standardization funding. Pursue white-label module supply to Taiwan-based AR headset manufacturers seeking gaze-contingent rendering capabilities without captive optical engineering. For Investors and Strategic Acquirers: Asymmetric upside sits with embedded AI firmware specialists possessing automotive-grade MCU optimization capabilities and existing OEM validation relationships. Five-to-ten year viability favors suppliers with diversified revenue across clinical diagnostics, automotive safety, and AR/VR headset verticals rather than single-application pure-plays. Monitor NHTSA-equivalent regulatory expansion timelines across Asia-Pacific jurisdictions as inflection signals for driver monitoring module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Validation Partnership | KBA certification pathways in Stuttgart anchor tier-one supplier selection criteria for OEM driver monitoring mandates. |
| Clinical Certification Investment | FDA 510(k) submission for neurological diagnostic platforms unlocks hospital procurement committee budgets in Boston and Baltimore. |
| AR Headset Module Integration | Gaze-contingent rendering partnerships with Taiwan manufacturers attach eye tracking to next-generation mixed reality hardware shipments. |
| Backward Sensor Supply Integration | Joint ventures with Taiwanese infrared LED foundries secure allocation priority against larger semiconductor customers. |
| Cloud Platform Subscription Migration | Enterprise site licenses with UK university technology transfer offices displace perpetual hardware ownership with recurring revenue. |
Methodological Framework
Bottom-up automotive and healthcare deployment modeling reconciled against top-down sensor module production tracking forms the analytical core of this study. Primary interviews with driver monitoring system engineers at German OEMs, FDA regulatory affairs specialists, hospital biomedical engineering directors, and AR headset platform engineers were validated against secondary sources including FDA 510(k) filings, KBA type-approval databases, METI standardization documents, and automotive tier-one supplier SEC disclosures. Triangulation across these sources ensures volume estimates reflect actual procurement patterns rather than manufacturer shipment claims.
Historical trendline analysis of infrared sensor array pricing and automotive safety mandate adoption curves informed projection frameworks across the analysis window. Segmentation modeling incorporated technology tier, application vertical, certification status, and regional regulatory cluster dimensions. CAGRs were derived from installed base growth rates adjusted for replacement cycles and attach rate assumptions in emerging AR headset categories. Forecast inputs included OEM driver monitoring mandate effective dates, FDA software-as-a-medical-device guidance evolution, and METI accessibility procurement channel expansion.
Caveats apply where NHTSA-equivalent regulatory delays, EU AI Act biometric consent enforcement variations, or smartphone camera gaze estimation accuracy improvements could materially shift the outlook. Forecasts reflect documented assumptions regarding automotive safety regulation harmonization and clinical validation timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asset Tags Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Smart Barcode Readers Market
Sensors
Handheld GPS Units Market
Sensors
Alcohol Sensor Market
Sensors
Indoor Location Market
Sensors
Weigh-In-Motion System Market
Sensors
Bluetooth Beacons Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Vision Positioning System Market
Sensors
Body Area Network Market
Sensors
Telemetric Devices Market
Sensors
Voice Sounders Market
Sensors
Location-Based Ambient Intelligence Market