
 Global System Integrator for Industrial Automation Market | 2026-2036
Global System Integrator for Industrial Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global System Integrator for Industrial Automation Market Outlook
Copper wiring is pivoting toward fiber-optic and industrial Ethernet cabling in new plant deployments, cutting signal latency and electromagnetic interference costs for integrators. ABB leverages its robotics heritage to anchor large automotive line contracts across Europe and North America. Siemens dominates the DCS integration layer for oil and gas clients, while Rockwell Automation specializes in PLC-based architectures for discrete manufacturing in the United States.
A system integrator for industrial automation engineers, commissions, and maintains heterogeneous control environments spanning programmable logic controllers, supervisory control and data acquisition networks, distributed control systems, and human-machine interfaces, typically integrating fieldbus protocols with cycle times under ten milliseconds to synchronize actuators, sensors, and enterprise resource planning layers. The PLC segment retains the largest installed base across legacy brownfield sites, though the Industrial IoT technology dimension is expanding fastest as edge computing nodes proliferate on factory floors. Process automation applications command premium integration fees due to hazardous environment certifications and continuous uptime requirements.
The U.S. Occupational Safety and Health Administration mandates lockout-tagout integration in automated systems, while the EU Machinery Directive enforces functional safety validation for robotic work cells, and China's Ministry of Industry and Information Technology imposes GB standards on industrial control system cybersecurity. These frameworks elevate compliance costs but create barriers that favor established integrators with certified safety engineering benches. Stakeholders must weigh captive engineering investments against specialist outsourcing as plant complexity outpaces in-house automation competency.
Market Dynamics
The EU AI Act is forcing integrators to reengineer algorithmic transparency into automated decision systems, compressing delivery timelines while elevating engineering costs for automotive and process sector deployments.
Growth Catalysts
- Automotive OEM Retrofit Cycles:German and U.S. manufacturers are accelerating factory modernization programs, creating sustained demand for robotic welding and assembly line synchronization expertise.
- EU AI Act Compliance Mandates:Algorithmic transparency requirements for automated decision systems are generating specialized integration contracts across European manufacturing facilities.
- Edge Computing Proliferation:Industrial IoT node deployment on factory floors is expanding the addressable integration base beyond traditional PLC architectures.
Market Restraints
- Copper-to-Fiber Transition Costs:Signal infrastructure upgrades in brownfield sites require substantial rewiring capital before latency benefits materialize.
- Certified Safety Engineer Scarcity:OSHA lockout-tagout and EU Machinery Directive functional safety validation requirements exceed available qualified personnel pools.
- Legacy PLC Lock-In:Brownfield installed bases resist migration to open architectures, constraining integrator margin expansion on maintenance contracts.
Strategic Opportunities
- Indian Manufacturing Scale-Up:PLI scheme incentives for electronics and automotive production are creating greenfield integration demand in Gujarat and Tamil Nadu corridors.
- Converged IT-OT Security:China's MIIT GB cybersecurity standards and comparable frameworks elsewhere are opening managed security service attachments for control system integrators.
- Hazardous Environment Specialization:Process automation certifications for continuous uptime environments command premium fees in oil, gas, and chemical verticals.
Industry Challenges
- Multiprotocol Integration Complexity:Fieldbus standard fragmentation forces integrators to maintain expertise across EtherCAT, Profinet, and legacy DeviceNet simultaneously.
- Cycle Time Compression:Sub-ten-millisecond synchronization requirements between actuators, sensors, and ERP layers strain commissioning timelines and debugging resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global System Integrator for Industrial Automation Market |
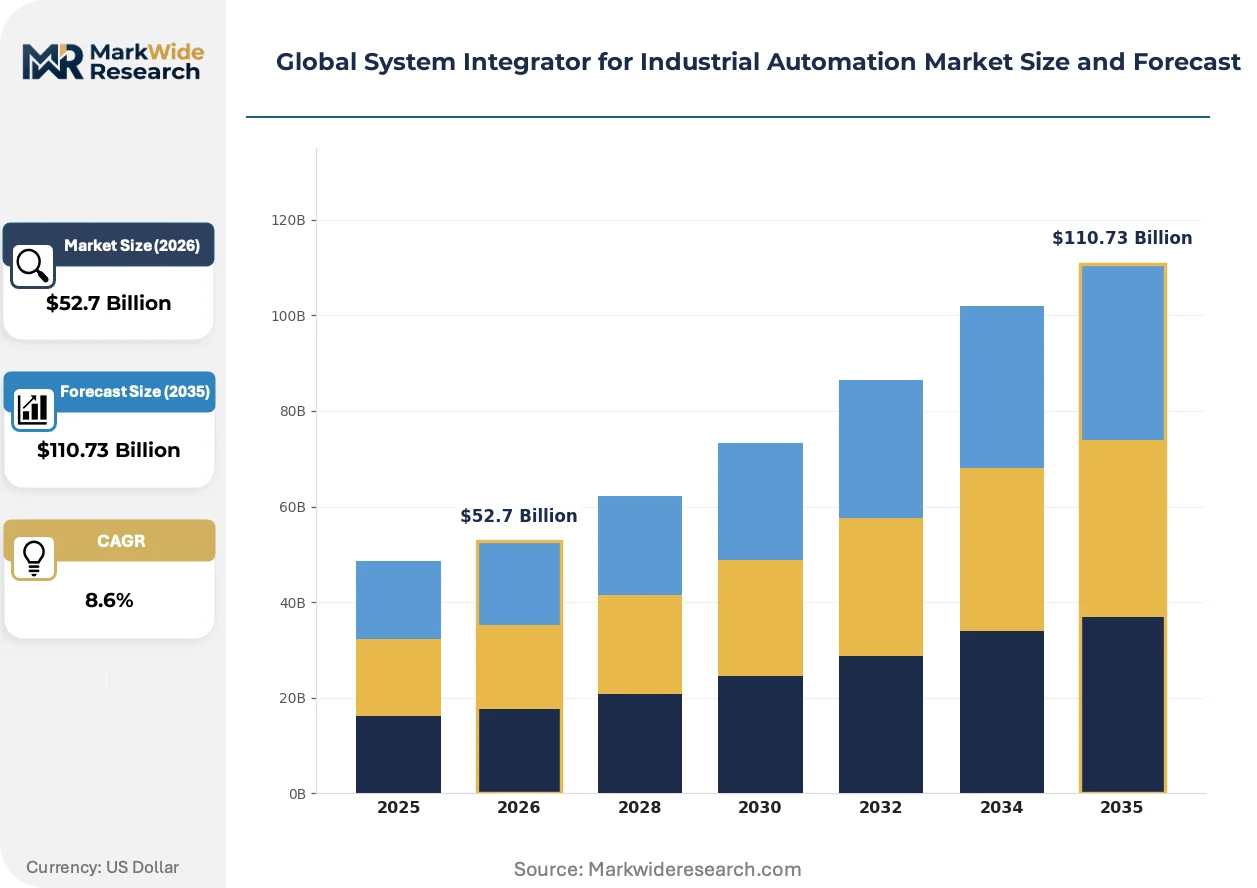
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, SCADA, DCS, HMI Technology: Industrial IoT, Robotics, AI, Cloud Computing End User: Manufacturing, Oil & Gas, Food & Beverage, Automotive Application: Process Automation, Factory Automation, Energy Management, Building Automation |
| Companies Covered | Logicon Technosolutions, ABB, RoviSys, Emerson Electric, Rockwell Automation, Wunderlich-Malec, Siemens, Honeywell International, Grantek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global System Integrator for Industrial Automation Market Strategic Shifts
Industrial Ethernet architectures are displacing fieldbus dominance in new plant deployments, while regulatory pressure on algorithmic accountability and buyer consolidation around outcome-based contracts are restructuring competitive dynamics.
Time-sensitive networking over industrial Ethernet is overtaking deterministic fieldbus protocols in automotive and semiconductor fabrication deployments. German OEMs and Taiwanese chip foundries are specifying TSN-enabled backbones for new lines. This convergence is compressing vendor differentiation around proprietary protocol stacks.
REACH substance restrictions and RoHS compliance deadlines are compelling integrators to audit component supply chains for restricted materials. Cable and connector selections now require documented substance declarations before site acceptance. Process sector clients in the Netherlands and Belgium are imposing the strictest upstream verification requirements.
Automotive buyers are consolidating vendor panels and demanding lifecycle performance guarantees rather than discrete project fees. Tier-1 suppliers in Stuttgart and Detroit are piloting outcome-based contracts where integrators assume uptime risk. This transfer compresses integrator working capital cycles and rewards predictive maintenance capabilities over pure engineering hours.
Global System Integrator for Industrial Automation Market Segmentation
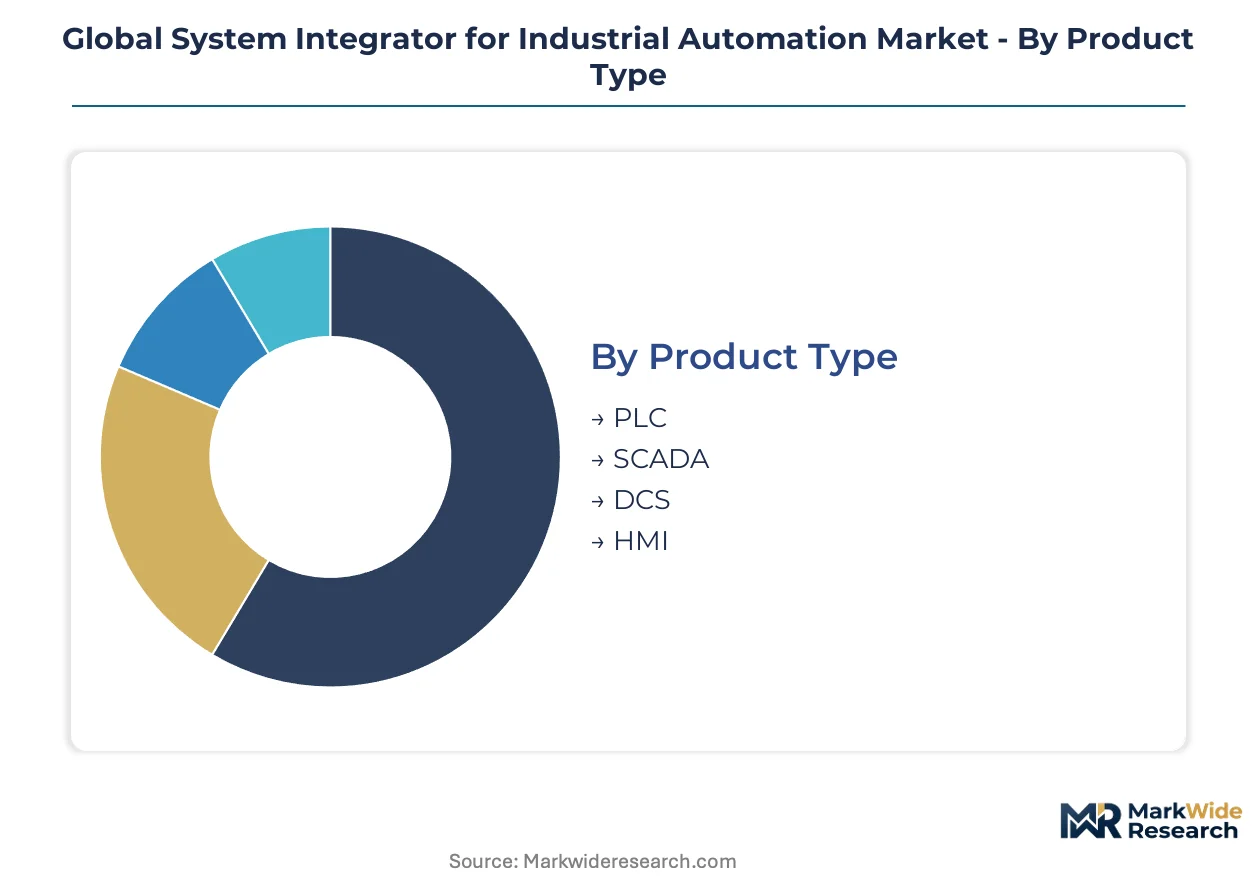
System integrators segment their service portfolios to match heterogeneous control architectures with specific compliance burdens and uptime requirements. Each dimension shapes engineering bench composition, certification investments, and margin structures differently.
Product Type:
Supply concentration among PLC specialists in Germany and Japan creates asymmetric pricing power for brownfield maintenance contracts.
- PLC:Programmable logic controllers coordinate discrete manufacturing sequences through ladder logic and structured text programming. German automotive OEMs in Stuttgart and Wolfsburg drive sustained demand for legacy PLC migration services amid skilled technician shortages.
- SCADA:Supervisory control and data acquisition networks aggregate field-level telemetry into centralized visualization layers. Water treatment utilities across France and Italy are modernizing SCADA infrastructure under EU cybersecurity directives, compressing vendor qualification timelines.
- DCS:Distributed control systems manage continuous process variables in hazardous environments.
- HMI:Human-machine interfaces bridge operator cognition with machine state visualization.
PLC absorbs the bulk of installed capacity; Industrial IoT is expanding most quickly.
Technology:
Cost tier differentiation separates premium AI-enabled integration from commodity robotics deployment.
- Industrial IoT:Edge computing nodes and sensor networks enable predictive maintenance through real-time data streaming. Semiconductor foundries in Taiwan and South Korea are specifying IoT-enabled condition monitoring for wafer fabrication equipment, driving protocol standardization investments.
- Robotics:Articulated and collaborative robot integration demands kinematic calibration and safety cell validation. Automotive welding lines in Detroit and Spartanburg require synchronized multi-robot coordination, elevating commissioning complexity.
- AI:Machine learning models for quality inspection and predictive analytics.
- Cloud Computing:Scalable compute resources for manufacturing execution system hosting.
Robotics commands premium project fees; Industrial IoT is climbing the fastest.
End User:
Application maturity varies sharply between continuous process and discrete assembly environments.
- Manufacturing:Discrete production lines for electronics, machinery, and consumer goods. Electronics contract manufacturers in Shenzhen and Ho Chi Minh City are expanding automated surface-mount technology lines under supply chain relocation pressures.
- Oil & Gas:Upstream, midstream, and downstream process control with hazardous area certifications. North Sea platform operators in Norway and the UK impose the strictest functional safety validation requirements under IEC 61511.
- Food & Beverage:Hygienic design compliance and batch recipe management.
- Automotive:High-volume assembly synchronization and paint shop automation.
Automotive absorbs the bulk of integration revenue; Food & Beverage is gaining share fastest.
Application:
Customer type segmentation separates asset owners from engineering-procurement-construction contractors with divergent risk allocation preferences.
- Process Automation:Continuous manufacturing control with safety instrumented systems. Chemical producers in Belgium and the Netherlands are retrofitting ethylene crackers with advanced process control under REACH substance tracking mandates.
- Factory Automation:Discrete part handling, machining, and assembly coordination. Machine tool builders in Turin and Osaka are integrating force-controlled grinding operations for aerospace component precision.
- Energy Management:Power monitoring, demand response, and microgrid control.
- Building Automation:HVAC, lighting, and access control integration.
Process Automation captures premium fee structures; Factory Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Mittelstand suppliers concentrate retrofit demand for complex factory synchronization projects. The EU AI Act compresses delivery timelines across European manufacturing facilities. Chinese MIIT cybersecurity standards and India's PLI manufacturing incentives are redrawing integration contract geography.
United States
Detroit and Spartanburg automotive clusters drive multi-robot welding line synchronization contracts. OSHA lockout-tagout mandates elevate certified safety engineering requirements for brownfield retrofits. Gulf Coast petrochemical facilities in Texas and Louisiana command premium fees for hazardous environment DCS integration under continuous uptime requirements.
Germany
Stuttgart and Wolfsburg automotive OEMs sustain legacy PLC migration demand amid technician shortages. The EU AI Act compels algorithmic transparency reengineering into automated decision systems. North Rhine-Westphalia chemical producers impose REACH substance tracking mandates on component supply chain audits.
China
Shenzhen electronics contract manufacturers expand automated surface-mount technology lines under supply chain relocation pressures. MIIT GB cybersecurity standards enforce industrial control system hardening requirements. Yangtze River Delta semiconductor foundries specify IoT-enabled condition monitoring for wafer fabrication equipment.
India
Gujarat and Tamil Nadu corridors generate greenfield integration demand from PLI scheme incentives for electronics and automotive production. Central Electricity Authority grid codes shape power monitoring system specifications. Maharashtra industrial zones attract robotics deployment for precision machining operations in aerospace component fabrication.
Japan
Osaka and Nagoya machine tool builders integrate force-controlled grinding operations for aerospace component precision. METI industrial standards govern functional safety validation protocols for collaborative robot work cells. Kyushu semiconductor facilities specify TSN-enabled industrial Ethernet backbones for deterministic cycle time control.
Global System Integrator for Industrial Automation Market Competitive Environment
Strategic partnerships dominate the current landscape as integrators bundle predictive maintenance capabilities with traditional engineering contracts. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive robotics heritage, pure-play automation specialists with certified safety benches, and regional system houses with deep local plant relationships. Technology licensing arrangements proliferate as fieldbus protocol convergence compresses proprietary differentiation. Geographic expansion through acquisition targets Indian and Southeast Asian manufacturing corridors.
Within the diversified industrial tier, ABB leverages its Swiss robotics heritage to anchor large automotive line contracts, while Siemens occupies a position exemplifying DCS integration dominance for oil and gas process environments. Rockwell Automation sits within the PLC-specialist archetype, anchoring discrete manufacturing architectures across North American industrial clusters. These three represent contrasting strategic postures: robotics-led vertical integration, process-layer control dominance, and programmable logic controller installed base monetization.
| Leading Market Players |
|---|
| Logicon Technosolutions |
| ABB |
| RoviSys |
| Emerson Electric |
| Rockwell Automation |
| Wunderlich-Malec |
| Siemens |
| Honeywell International |
| Grantek |
| Others |
Value Chain & Pricing Dynamics
German automotive OEMs and Mittelstand suppliers concentrate procurement decisions for complex factory retrofit projects, anchoring project-based pricing with lifecycle performance guarantees rather than discrete engineering hours. This buyer consolidation compresses integrator working capital cycles and rewards predictive maintenance capabilities.
Pricing Analysis
Volume concentrates in legacy PLC maintenance contracts while margins migrate toward AI-enabled integration and hazardous environment certifications. Pricing stratifies across premium tier certified safety engineering, standard tier brownfield migration services, and economy tier commodity robotics deployment. Cost compression in standard-tier services intensifies because certified safety engineer scarcity exceeds available personnel pools. Tier-1 automotive suppliers in Stuttgart and Detroit exhibit least price sensitivity for uptime-guaranteed outcome contracts, while electronics contract manufacturers in Shenzhen demonstrate highest sensitivity to engineering hour rates.
Supply Chain Analysis
India's PLI scheme local-content mandates and China's MIIT GB cybersecurity standards are reshaping component sourcing for control system hardware. Supply concentrates in Germany for precision motion control components, Japan for collaborative robot servo motors, and Taiwan for industrial Ethernet switch silicon. Raw material dependencies span copper and fiber-optic cabling, safety-rated programmable logic controllers, and edge computing node processors. Single-source vulnerability runs through semiconductor foundry capacity for deterministic cycle time chipsets. Distribution runs through direct OEM relationships for large automotive line contracts and regional system houses for Mittelstand supplier retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified safety engineer scarcity props pricing power for established integrators, creating a supply-constrained market structure favoring incumbents with validated engineering benches.
For Market Incumbents: Anticipate margin compression in commodity robotics deployment as outcome-based contracts transfer uptime risk from automotive buyers. Defend position by deepening captive safety certification investments under EU Machinery Directive and OSHA lockout-tagout mandates. Prioritize backward integration into predictive maintenance software stacks to capture recurring revenue attachments. For New Entrants and Emerging Players: Launch via hazardous environment specialization in North Sea oil platforms and Belgian chemical corridors where IEC 61511 certification barriers limit incumbent density. Target Indian electronics manufacturing clusters in Gujarat and Tamil Nadu under PLI scheme incentives with greenfield integration expertise. Penetrate through IT-OT converged security service bundles addressing China's MIIT GB standards and comparable frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play automation specialists with certified safety benches in European manufacturing corridors. Long-term viability hinges on algorithmic transparency capabilities under EU AI Act compliance mandates. Watch for inflection when automotive OEMs consolidate vendor panels below five integrators per regional cluster.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Safety Bench Expansion | EU Machinery Directive and OSHA mandates elevate barrier to entry for competitors lacking validated engineers. |
| Algorithmic Transparency Investment | EU AI Act compliance creates specialized contract differentiation for automotive decision system deployments. |
| IT-OT Converged Security Service Launch | China MIIT GB standards and comparable frameworks open managed security attachments for control integrators. |
| Indian Manufacturing Corridor Entry | PLI scheme incentives in Gujarat and Tamil Nadu generate greenfield demand for electronics and automotive lines. |
| Predictive Maintenance Capability Buildout | Outcome-based contracts with Stuttgart and Detroit OEMs reward uptime risk assumption over engineering hours. |
Study Parameters
SEC 10-K filings, EU regulatory submission databases, and industrial automation trade association reports formed the secondary backbone, cross-referenced with primary interviews across plant engineers at German automotive OEMs, procurement leads at Tier-1 suppliers, certified safety engineering directors, and channel partners in Indian manufacturing corridors. Bottom-up project pipeline analysis and top-down sector spend estimates were triangulated to anchor market sizing.
Historical trendline analysis of integration contract volumes and value migration patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include control architecture type, technology tier, end-use vertical, application maturity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed contract values and announced capacity expansions. Industry-specific forecast inputs encompass EU AI Act implementation timelines and PLI scheme incentive disbursement trajectories.
The model assumes a particular technology adoption path; alternative pathways for time-sensitive networking over industrial Ethernet would alter the outlook for fieldbus protocol convergence. Forecasts reflect assumptions around certified safety engineer supply elasticity and automotive OEM consolidation behavior. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
UV Curing System Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Smart Elevator Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Global SCADA Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Industrial Multiprotocol Gateways Market