
 Gesture Recognition in Retail Market | 2026-2036
Gesture Recognition in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Gesture Recognition in Retail Market Analysis
Subscription-based software licensing for gesture analytics is broadening the addressable revenue pool beyond one-time hardware sales. Intel Corporation leverages its RealSense depth-sensing portfolio to anchor vision-based deployments in North American big-box retail. Google LLC differentiates through cloud-native gesture APIs that integrate with existing point-of-sale ecosystems. Microsoft Corporation extends its Azure Kinect developer platform to sustain engagement among retail systems integrators building custom checkout solutions.
Gesture recognition in retail encompasses computer vision and sensor-fusion systems that interpret human body movements—hand trajectories, arm sweeps, and micro-gestures—without physical contact, typically operating at 30-60 frames per second with sub-10 centimeter spatial accuracy to trigger transactions, navigate digital signage, or authenticate shoppers. The technology serves the commercial purpose of eliminating touchpoints while capturing behavioral data for merchandising optimization. Vision-Based systems dominate current installations due to mature camera supply chains and falling CMOS sensor costs, while Hybrid architectures represent the fastest-expanding category as retailers demand redundancy between optical and radar modalities for 24/7 operational reliability. Touchless deployment through edge-computing nodes is gaining share where latency requirements for real-time gesture response fall below 100 milliseconds.
The EU AI Act classifies biometric inference systems as high-risk, mandating conformity assessments before retail deployment, while GDPR imposes strict purpose limitation on gesture-derived behavioral profiles. The Federal Trade Commission in the United States has signaled heightened scrutiny of biometric data practices through enforcement actions against unfair or deceptive collection methods. Retail technology buyers must evaluate whether their gesture platforms can demonstrate algorithmic auditability and geographic data residency before committing to multi-store rollouts.
Market Dynamics
The retail gesture recognition sector faces a structural pivot as edge-computing architectures absorb inference workloads previously routed to cloud data centers, compressing latency below the 100-millisecond threshold demanded by real-time checkout authentication.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of biometric inference systems forces retailers to deploy auditable gesture platforms, accelerating replacement cycles for legacy vision systems across German and French grocery chains.
- Self-service checkout proliferation:Convenience retail formats in the United States deploy frictionless gesture interfaces to reduce labor costs and shrinkage at autonomous store formats.
- CMOS sensor cost deflation:Mature camera supply chains enable sub-$50 depth-sensing modules for mass-market point-of-sale integration.
Market Restraints
- GDPR purpose limitation:Strict constraints on behavioral profile retention limit secondary monetization of gesture-derived merchandising analytics in European deployments.
- Radar sensor supply concentration:Millimeter-wave component fabrication clusters in Taiwan and South Korea create single-source vulnerability for hybrid architecture rollouts.
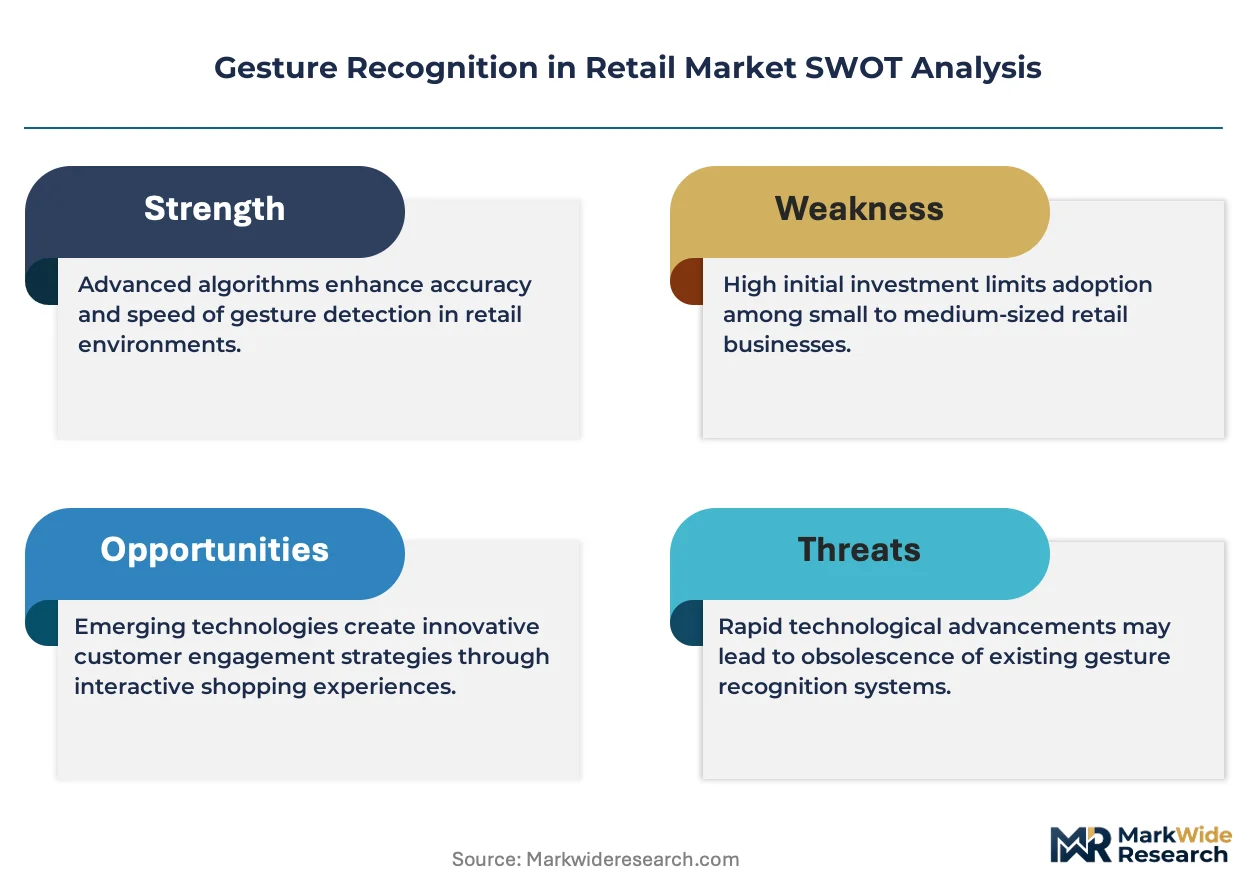
- Algorithmic auditability gaps:Current neural network architectures resist explainability requirements under emerging conformity assessment frameworks.
Strategic Opportunities
- Indian retail modernization:PLI scheme incentives for electronics manufacturing position domestic OEMs to capture gesture-enabled kiosk demand in tier-2 urban centers.
- Pharmacy drive-through automation:Contactless prescription pickup interfaces represent an underpenetrated application vector in North American healthcare retail.
- Radar-vision sensor fusion:Convergence of depth-sensing modalities enables 24/7 operational reliability in variable lighting conditions.
Industry Challenges
- Computer vision talent scarcity:Shortage of edge-AI optimization engineers delays deployment timelines for multi-store rollouts.
- Legacy POS integration complexity:Proprietary payment protocols in incumbent retail systems require custom middleware development for gesture-triggered transaction handoff.
- Conformity assessment bottlenecks:Notified body capacity constraints under the EU AI Act extend certification timelines for biometric inference deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gesture Recognition in Retail Market |
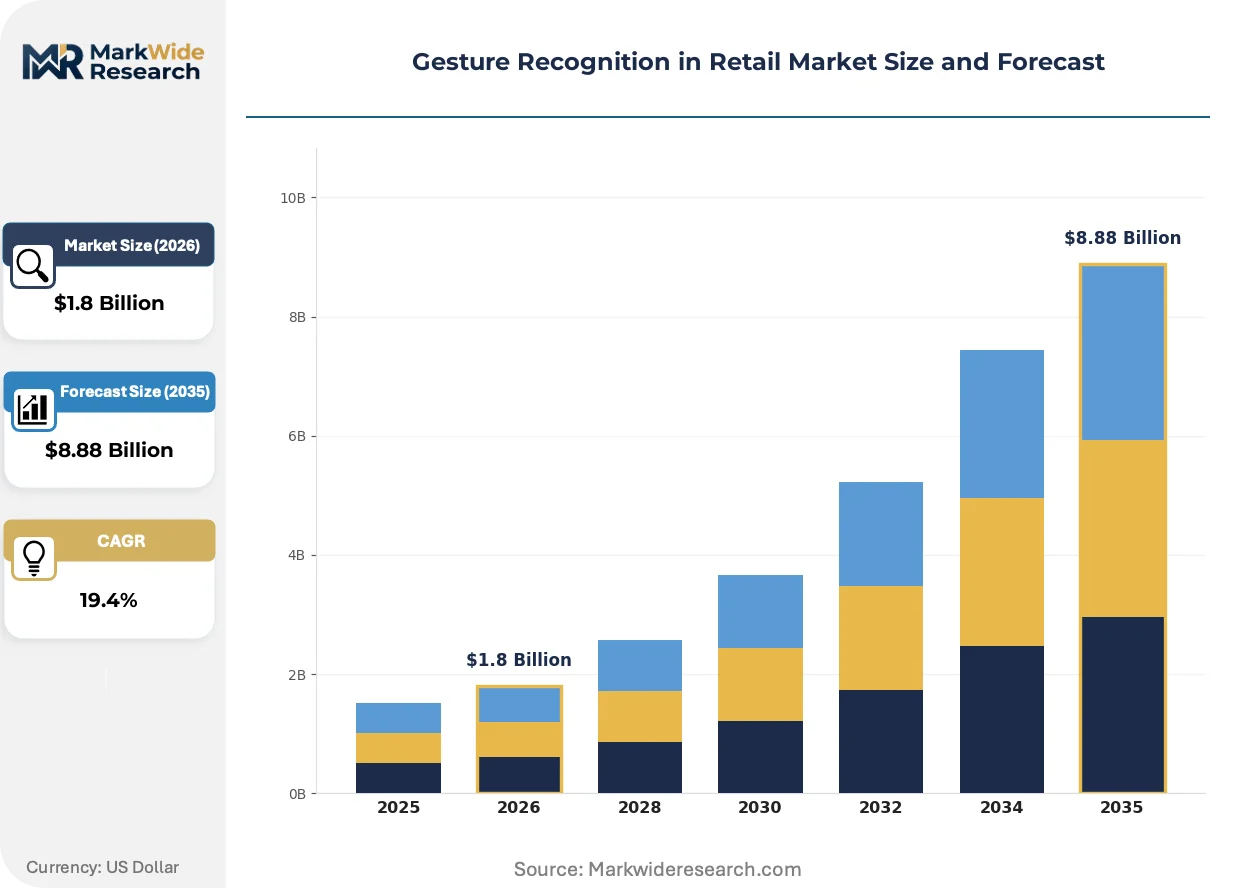
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vision-Based, Sensor-Based, Hybrid, Touchless Application: Customer Engagement, Checkout Experience, Inventory Management, Advertising Deployment: On-Premises, Cloud-Based, Edge Computing, Mobile Device Type: Smart Displays, Wearables, Kiosks, Surveillance Systems |
| Companies Covered | Infineon Technologies AG, Cognitec Systems GmbH, Apple Inc., GestureTek Inc, Intel Corporation, Google LLC, Sony Corporation, Elliptic Labs, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gesture Recognition in Retail Market Emerging Trajectories
Retail gesture systems are absorbing inference workloads onto localized edge nodes, severing dependency on cloud connectivity for real-time shopper authentication. This architectural shift compresses response latency while complicating software update distribution.
Time-of-flight depth sensors are absorbing market share from structured-light alternatives in high-throughput checkout environments. Grocery chains in the United States and Germany deploy these modules at 30-60 frames per second to track hand trajectories with sub-10 centimeter accuracy. The technology is absorbing capital allocation previously directed toward RFID-enabled shopping carts, consolidating sensing infrastructure at the point-of-sale terminal.
The EU AI Act's high-risk classification for biometric inference systems is forcing algorithmic auditability into platform procurement specifications. Retail technology buyers now demand documentation of training data provenance and model performance variance across demographic cohorts. European deployments face the strictest scrutiny, with conformity assessments required before multi-store activation.
Pharmacy chains are unbundling after-sales service contracts from hardware procurement, favoring subscription-based gesture analytics licensing over perpetual software ownership. This shift transfers operational risk to platform vendors while capturing continuous model improvement. The pattern is most visible in United States autonomous store pilots, where monthly per-lane fees replace upfront capital expenditure.
Gesture Recognition in Retail Market Segmentation
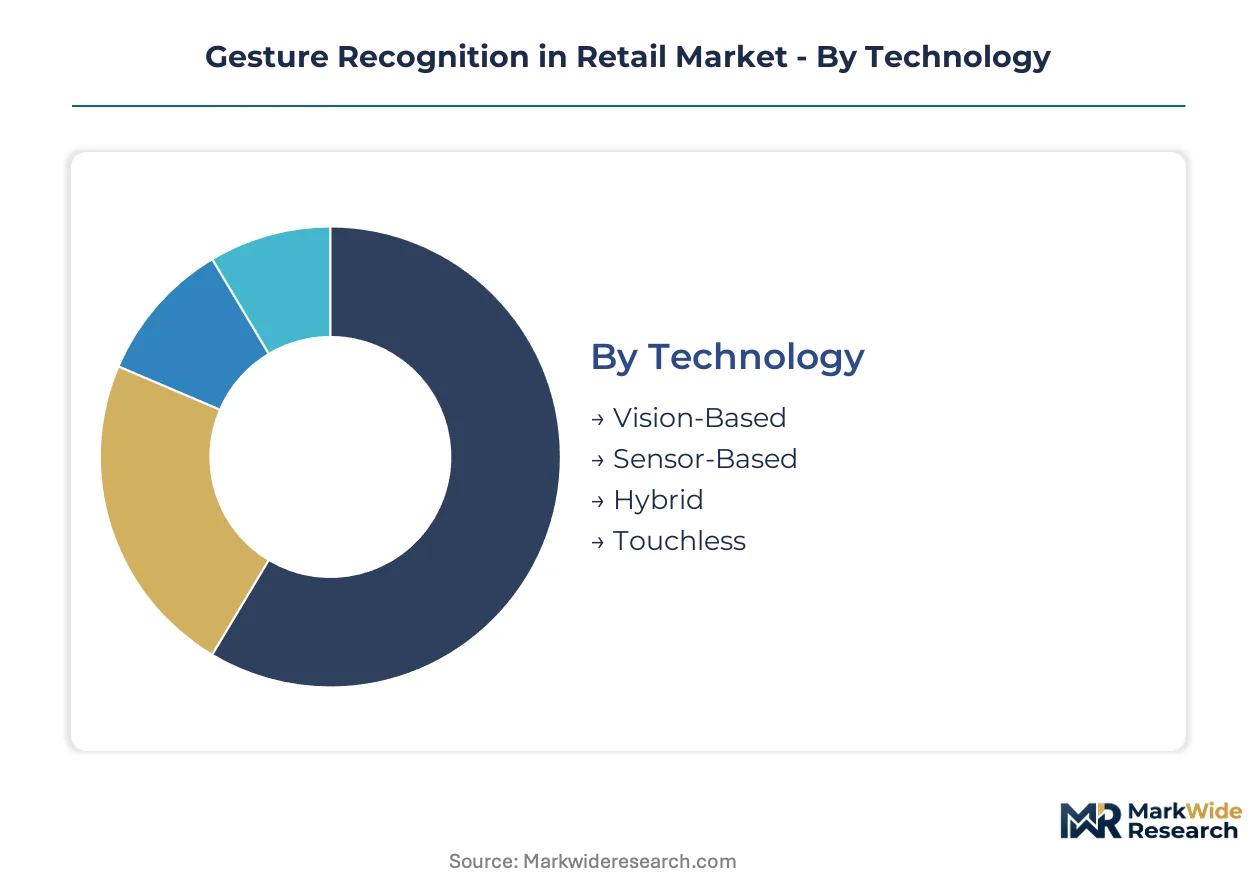
Technology heterogeneity in retail gesture systems creates divergent procurement economics across deployment scales. Retailers must match sensor modality to operational constraints—lighting conditions, throughput requirements, and biometric compliance exposure.
Technology:
Capital intensity varies sharply across sensing modalities, with hybrid architectures demanding the most complex integration budgets.
- Vision-Based:Camera arrays interpret hand trajectories and body positioning through depth-sensing CMOS modules operating at 30-60 frames per second. Grocery chains in the United States deploy these systems at self-service checkout lanes where sub-10 centimeter spatial accuracy reduces transaction friction. Falling sensor costs below $50 per module accelerate mass-market point-of-sale integration.
- Hybrid:Sensor fusion combines optical and radar modalities to ensure 24/7 operational reliability across variable lighting conditions. German and French retailers favor this architecture under EU AI Act high-risk classification mandates requiring redundancy for biometric inference systems. Dual-modality redundancy absorbs the highest upfront capital allocation but minimizes compliance failure exposure.
- Sensor-Based:Dedicated proximity and motion detectors trigger discrete retail actions without full computer vision pipelines.
- Touchless:Edge-computing nodes process gesture inference locally, severing cloud dependency for sub-100 millisecond latency requirements.
Vision-Based systems absorb the bulk of installed capacity; Hybrid architectures are expanding most quickly.
Application:
Use-case maturity determines software licensing models, with transactional applications commanding premium subscription pricing over analytics-only deployments.
- Checkout Experience:Frictionless payment authentication through gesture recognition eliminates physical contact at point-of-sale terminals. Autonomous store formats in the United States leverage this capability to reduce labor costs and shrinkage simultaneously. Amazon Go-style deployments drive enterprise-scale rollouts among pharmacy chains seeking differentiation.
- Customer Engagement:Interactive digital signage responds to shopper proximity and gesture to deliver personalized promotional content. Retailers capture behavioral data for merchandising optimization while respecting GDPR purpose limitation constraints on profile retention.
- Inventory Management:Warehouse and backroom gesture interfaces enable hands-free stock verification and replenishment workflows.
- Advertising:Anonymous audience measurement through gesture tracking informs programmatic display placement without individual identification.
Checkout Experience commands the dominant share of current revenue; Customer Engagement is climbing the fastest as retailers seek secondary monetization of installed sensor infrastructure.
Deployment:
Latency requirements and data residency obligations fragment procurement preferences across retail formats and regulatory jurisdictions.
- Edge Computing:Localized inference nodes process biometric gesture data without transmission to centralized data centers. This architecture satisfies GDPR geographic data residency mandates while compressing response latency below real-time authentication thresholds. European deployments under EU AI Act conformity assessment requirements favor edge localization for auditability.
- Cloud-Based:Centralized processing enables continuous model improvement and cross-store analytics aggregation.
- On-Premises:Dedicated server infrastructure retains full data control within retail facility boundaries.
- Mobile:Smartphone-integrated gesture interfaces extend touchless interaction to curbside pickup and loyalty program engagement.
Edge Computing is gaining share fastest in regulated markets; Cloud-Based retains dominance where latency tolerance exceeds 100 milliseconds.
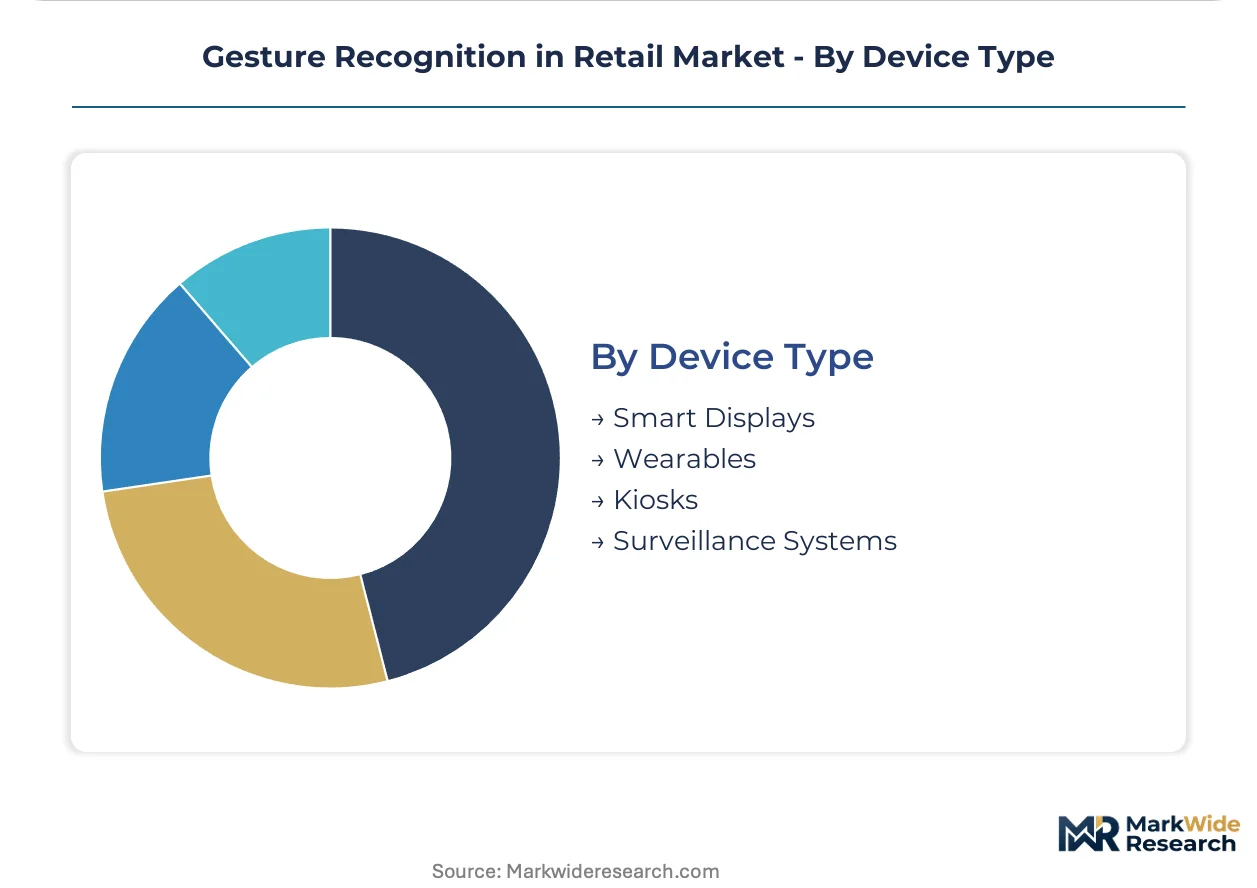
Device Type:
Hardware form factor dictates installation complexity and replacement cycle economics across retail environments.
- Kiosks:Self-contained gesture-enabled terminals consolidate sensing, display, and payment processing for standalone deployment. Convenience retail formats in the United States favor these units for rapid lane expansion without building modification. Pharmacy drive-through automation represents an underpenetrated vector for prescription pickup interfaces.
- Smart Displays:Integrated screens with embedded depth sensors enable interactive product discovery and wayfinding.
- Surveillance Systems:Security camera infrastructure repurposed for gesture analytics leverages existing capital investment.
- Wearables:Retail staff armbands and customer-facing wrist devices enable specialized gesture control scenarios.
Kiosks absorb the bulk of current hardware procurement; Smart Displays are expanding most quickly as digital signage refresh cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gesture recognition system manufacturing clusters in Taiwan and South Korea supply hardware to retail deployers concentrated in the United States and Germany. Consumption patterns diverge sharply between North American autonomous store rollouts and European compliance-heavy installations.
United States
Amazon Go-format autonomous stores and major pharmacy chains drive enterprise-scale gesture checkout deployments. FTC enforcement actions against biometric data practices tighten vendor selection criteria. San Francisco and Seattle tech corridors host pilot programs testing sub-100 millisecond latency edge architectures.
Germany
German grocery chains replace legacy vision systems ahead of EU AI Act conformity assessment deadlines. KBA vehicle safety expertise cross-pollinates retail radar-vision fusion development in Stuttgart engineering clusters. Munich-based systems integrators specialize in auditable gesture platforms for high-risk biometric classification.
France
French retail technology procurement emphasizes GDPR geographic data residency for gesture-derived behavioral profiles. ANSM medical device traceability standards influence pharmacy chain authentication requirements. Parisian convenience retail formats deploy frictionless interfaces to reduce labor costs in urban high-rent locations.
India
PLI scheme electronics manufacturing incentives position domestic OEMs to capture gesture-enabled kiosk demand. Tier-2 urban centers in Maharashtra and Karnataka modernize retail infrastructure with touchless interaction systems. Bangalore software developers adapt edge-AI gesture inference for cost-sensitive deployment scales.
Japan
Japanese retail automation prioritizes 24/7 operational reliability through hybrid radar-vision architectures. METI industrial digitization programs subsidize gesture system integration in convenience store chains. Tokyo-Osaka corridor deployments emphasize sub-10 centimeter spatial accuracy for aging-population accessibility.
Gesture Recognition in Retail Market Vendor Landscape
Top-tier vendors anchor the premium sensor fusion segment, while mid-tier specialists populate vision-only and edge computing niches. The vendor base stratifies across three tiers: semiconductor foundries supplying CMOS depth modules, systems integrators assembling retail-specific solutions, and cloud platforms offering gesture analytics APIs. Strategic archetypes include hardware-centric depth-sensing specialists, cloud-native API providers, and retail-focused systems integrators. Competitive moves concentrate on M&A for radar sensor capabilities and strategic partnerships bridging legacy POS protocols.
Within the semiconductor archetype, Infineon Technologies AG and Intel Corporation exemplify hardware-anchored positioning. Google LLC and Microsoft Corporation occupy the cloud-platform tier with API-centric offerings. Sony Corporation represents the diversified electronics conglomerate model spanning consumer and enterprise gesture applications.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Cognitec Systems GmbH |
| Apple Inc. |
| GestureTek Inc |
| Intel Corporation |
| Google LLC |
| Sony Corporation |
| Elliptic Labs |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's high-risk classification for biometric inference systems gates both qualified supply and premium-tier pricing access, forcing retailers to source only from vendors with demonstrable conformity assessment documentation while absorbing 40-60% cost premiums for auditable edge-computing architectures over non-compliant alternatives.
Pricing Analysis
Cost-down pressure on hybrid sensor-fusion systems accelerates because millimeter-wave radar component shortages concentrate supply leverage with Taiwanese and South Korean foundries. Subscription-based SaaS-tiered licensing dominates revenue models, with pricing stratifying across premium, standard, and economy tiers based on algorithmic auditability certification level and after-sales service bundling. European grocery chains exhibit the highest price sensitivity due to GDPR compliance overhead, while United States autonomous store operators prioritize sub-100 millisecond latency performance regardless of per-lane cost.
Supply Chain Analysis
CE marking and EU AI Act conformity assessment documentation gate supplier qualification more stringently than technical performance benchmarks. CMOS depth-sensing module fabrication concentrates in Taiwan, South Korea, and Japan, with millimeter-wave radar sensors drawing from the same East Asian manufacturing clusters. Single-source vulnerability for radar components creates supply chain risk, particularly for German and French retailers facing hard conformity assessment deadlines. Distribution runs through retail systems integrators in Munich, Paris, and San Francisco who assemble vendor-agnostic solutions from discrete sensor, edge-computing, and software components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints under the EU AI Act prop pricing premiums for pre-certified gesture platforms, creating a supply-constrained market where qualified vendor availability limits rollout velocity more than capital availability.
For Market Incumbents: Anticipate margin compression from cloud-native API providers by deepening backward integration into radar sensor supply and securing exclusive distribution partnerships with German systems integrators specializing in high-risk biometric classification compliance. Lock in multi-year edge-AI engineering talent contracts to preempt computer vision talent scarcity from delaying multi-store rollout timelines. For New Entrants and Emerging Players: The price-point gap between premium hybrid architectures and economy vision-only systems creates entry space for mid-tier sensor-fusion specialists targeting Indian tier-2 urban centers under PLI scheme electronics manufacturing incentives. Pharmacy drive-through automation in North America represents the most penetrable application vector, with kiosk-based deployment models offering faster proof-of-concept cycles than full-store retrofits. For Investors and Strategic Acquirers: The first major FTC enforcement action against biometric data collection practices in retail is the leading indicator that algorithmic auditability capabilities will separate viable acquisition targets from stranded assets. Favor edge-AI optimization engineering teams with demonstrated EU conformity assessment navigation over pure computer vision research talent. A model refresh is warranted upon material change in notified body capacity allocation under the EU AI Act.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Vision Sensor Fusion Development | Dual-modality redundancy satisfies EU AI Act high-risk classification mandates for 24/7 operational reliability. |
| Edge-Computing Node Localization | Sub-100 millisecond latency compliance captures GDPR geographic data residency requirements in European deployments. |
| Conformity Assessment Pre-Certification | Documented algorithmic auditability accelerates procurement cycles with German and French grocery chains facing deadlines. |
| Subscription Analytics Licensing | Monthly per-lane fee structures transfer operational risk from pharmacy chains to platform vendors in United States pilots. |
| PLI Scheme Manufacturing Partnership | Domestic OEM qualification under Indian electronics incentives opens cost-sensitive tier-2 urban center demand. |
Methodological Framework
Independent corroboration across retail technology procurement officers, edge-AI engineering directors, and notified body auditors underwrites the qualitative findings in this study. Primary interviews with systems integrators in Stuttgart, Munich, and Paris captured EU AI Act implementation timelines, while discussions with San Francisco and Seattle pilot program managers documented sub-100 millisecond latency architecture preferences. Secondary validation drew from SEC filings of publicly traded semiconductor vendors, EU official journal conformity assessment notifications, and Indian PLI scheme electronics manufacturing disbursement records. Bottom-up sensor shipment estimates and top-down retail technology capex aggregates were cross-referenced for triangulation.
Comparable-period anchoring referenced historical adoption curves for self-service checkout and RFID-enabled shopping carts to inform penetration assumptions across the projection horizon. The analytical framework modeled technology segmentation across vision-based, hybrid, sensor-based, and touchless architectures; application segmentation across checkout experience, customer engagement, inventory management, and advertising; and deployment segmentation across edge computing, cloud-based, on-premises, and mobile. CAGRs were derived from installed base growth rates adjusted for replacement cycle compression under regulatory compliance mandates. Forecast inputs included CMOS sensor cost deflation trajectories and notified body capacity expansion schedules.
Inputs from retail systems integrators and semiconductor vendor sales teams were available through the study window; gaps in real-time notified body queue depth data introduce uncertainty bands around EU deployment timing assumptions. Forecasts reflect documented assumptions regarding edge-AI optimization engineer supply elasticity and radar sensor fabrication capacity allocation. A model refresh is warranted upon material change in FTC biometric data enforcement posture or EU AI Act delegated act amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Body Area Network Market
Sensors
Voice Sounders Market
Sensors
Vision Positioning System Market
Sensors
Beacon Market
Sensors
Underground Service Locator Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Smart Beacon Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Transport Monitoring System Market
Sensors
Global RFID Market
Sensors
IO-Link Technology Market
Sensors
Low Power Geolocation Market
Sensors
Temperature Data Loggers Market
Sensors
Barcode Scanner Market
Sensors
Asia Pacific Container Monitoring Market