
 Collaborative Office Software Market | 2026-2036
Collaborative Office Software Market Size, Share, and Industry Trends Forecast 2026-2036
Collaborative Office Software Market Insights
GDPR enforcement on cross-border data transfers is pivoting vendor strategies toward regional data residency architectures. Microsoft anchors its competitive stance through deep integration of productivity suites with sovereign cloud deployments. Google differentiates via AI-native workspace tools that automate document workflows. Atlassian specializes in developer-centric collaboration, sustaining loyalty among agile software teams.
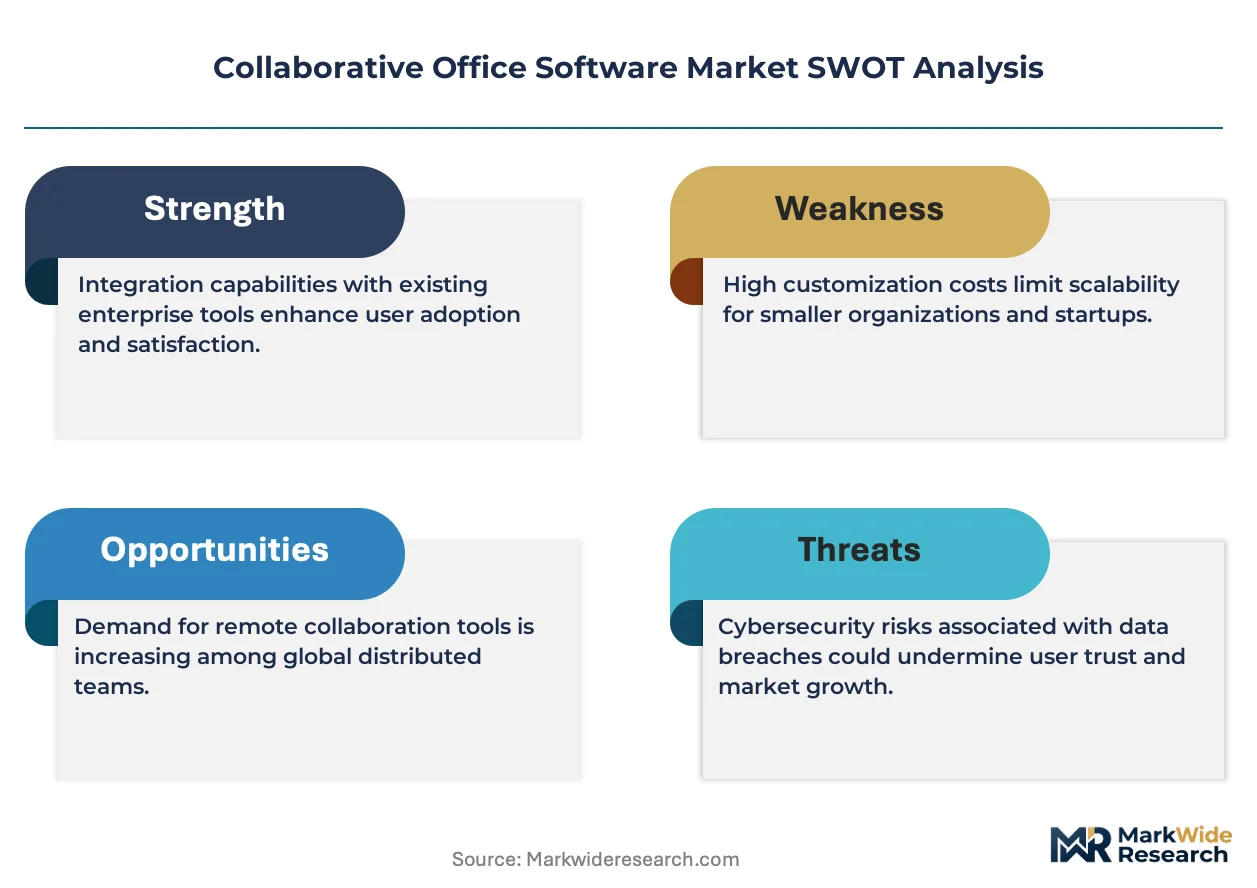
Collaborative office software denotes applications enabling synchronous and asynchronous document creation, communication, and project coordination across distributed users, typically delivered through browser-based interfaces or native clients with sub-100-millisecond latency targets for real-time editing. These systems serve commercial and institutional buyers by replacing physical workplace proximity with digital presence, task orchestration, and knowledge repositories. Cloud-based deployment leads absolute revenue contribution due to lower capital barriers and automatic update cycles, while hybrid configurations capture expanding margin pools from regulated industries requiring on-premises data custody. Enterprise end users dominate contract value through multi-year seat agreements, though educational institutions represent an accelerating growth vector as learning management systems converge with workplace collaboration tools.
The EU AI Act, HIPAA in the United States, and China's GB standards for data security collectively elevate compliance costs and create divergent product certification pathways across jurisdictions. Vendors must architect separate feature flags, consent mechanisms, and audit trails to satisfy these overlapping regimes, effectively fragmenting what was once a uniform SaaS delivery model. Stakeholders should monitor how forthcoming sector-specific AI guidance from the FDA and analogous bodies reshapes permissible automation within document review and clinical collaboration workflows.
Market Dynamics
Cloud-based collaboration suites are displacing on-premises legacy systems as enterprise IT departments prioritize distributed workforce enablement and automatic update cycles over capital-intensive infrastructure ownership.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are forcing vendors to build explainable AI features into document workflows, creating differentiated product roadmaps that accelerate procurement cycles among regulated European enterprises.
- Federal secure-collaboration standards:US defense contractors and civilian agencies are driving procurement specifications that favor vendors with FedRAMP authorization and end-to-end encryption architectures.
- Real-time editing latency thresholds:Sub-100-millisecond synchronization standards are pushing infrastructure investments toward edge computing deployments, expanding addressable markets in bandwidth-constrained environments.
Market Restraints
- Cross-border data transfer restrictions:GDPR enforcement on transatlantic flows is fragmenting SaaS delivery models, forcing redundant regional data residency architectures that inflate operational overhead.
- Converged compliance certification costs:Overlapping obligations under HIPAA, EU AI Act, and China's GB standards require separate feature flags and audit trails, compressing margins for multi-jurisdictional deployments.
- Technical debt in legacy integration:Hybrid configurations demand bespoke middleware to bridge cloud-native collaboration tools with on-premises document management systems, extending implementation timelines.
Strategic Opportunities
- Educational institution convergence:Learning management systems are merging with workplace collaboration platforms, opening seat agreements among universities and K-12 districts previously served by disconnected toolchains.
- Sovereign cloud deployment models:National data localization mandates in France, Germany, and India are creating captive markets for vendors with in-country infrastructure partnerships.
- AI-native workflow automation:Natural language processing convergence with document generation is enabling new pricing tiers for automated contract review and clinical collaboration use cases.
Industry Challenges
- Specialized compliance engineering scarcity:Vendors face acute recruitment pressure for professionals capable of architecting simultaneous GDPR, HIPAA, and sector-specific FDA guidance adherence.
- Legacy system API fragmentation:Enterprise customers maintain heterogeneous on-premises repositories with inconsistent integration protocols, forcing custom development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaborative Office Software Market |
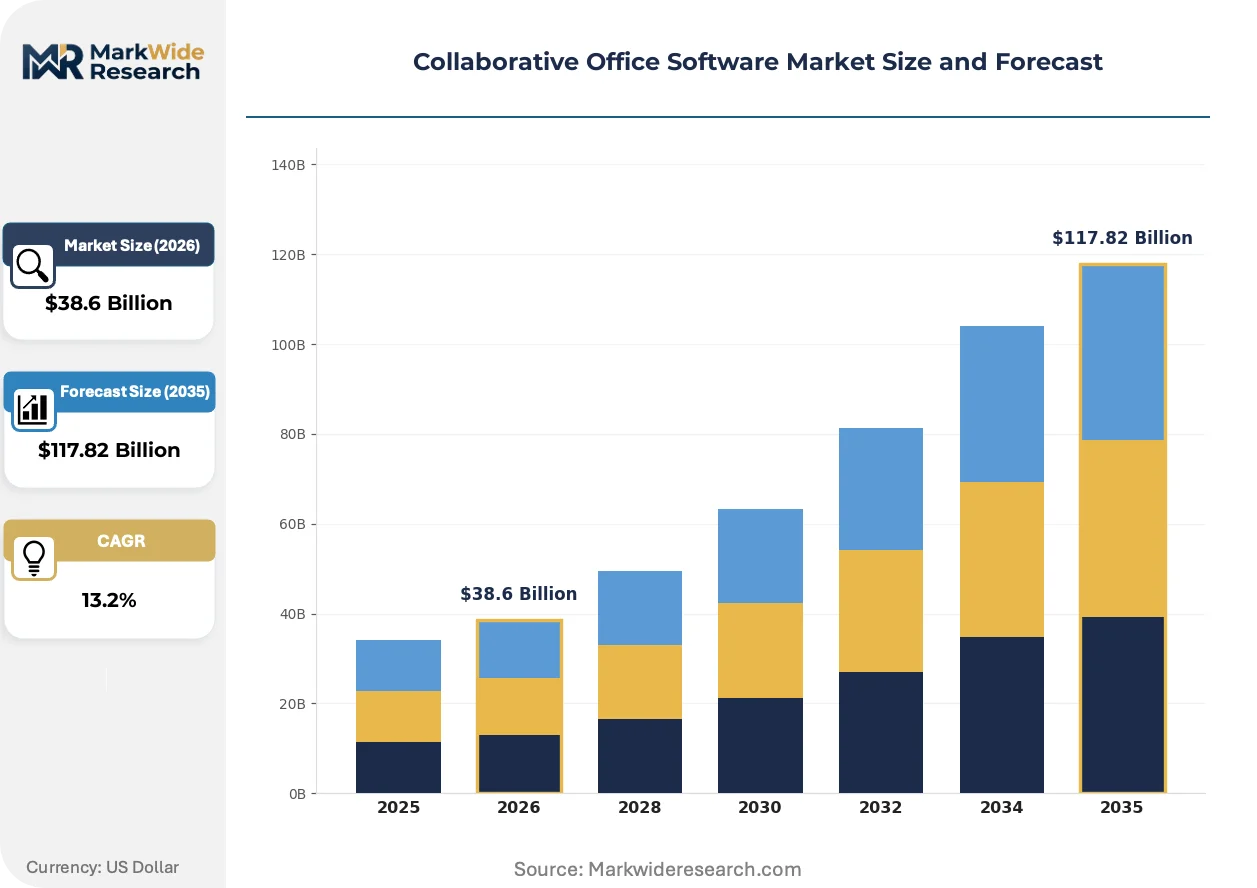
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $117.82 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Local Server End User: Small Business, Enterprise, Freelancers, Educational Institutions Solution: Document Management, Project Management, Communication Tools, Collaboration Platforms Feature: Real-Time Editing, File Sharing, Video Conferencing, Integrated Chat |
| Companies Covered | Microsoft, Google, Zoom, Salesforce, Cisco Systems, Atlassian, Slack Technologies, IBM, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaborative Office Software Market Trends and Innovations
Artificial intelligence is compressing document creation cycles while regulatory fragmentation is forcing architectural specialization. These forces are reshaping vendor R&D priorities and customer procurement criteria simultaneously.
Generative AI copilots embedded within collaborative suites are unifying previously separate drafting, review, and approval workflows into continuous processes. Legal departments and pharmaceutical regulatory teams are adopting these tools fastest, compressing document turnaround from weeks to hours. This unification is collapsing the addressable market for standalone contract lifecycle management vendors.
EMA guidance on AI-assisted clinical documentation and FDA draft rules for algorithmic decision support are mandating human-in-the-loop audit trails for automated recommendations. Vendors must now engineer explicit override mechanisms and explanation interfaces that slow feature release velocity. Pharmaceutical and medical device manufacturers face the steepest compliance burdens, driving preference toward vendors with pre-validated quality management system integrations.
Enterprise buyers are consolidating vendor relationships through multi-year platform agreements that bundle communication, project management, and document creation under single procurement umbrellas. Value-added resellers and systems integrators are losing standalone collaboration implementation revenue to direct vendor professional services organizations. This concentration is most visible among US federal contractors and Fortune 500 technology departments with centralized IT governance structures.
Collaborative Office Software Market Segmentation
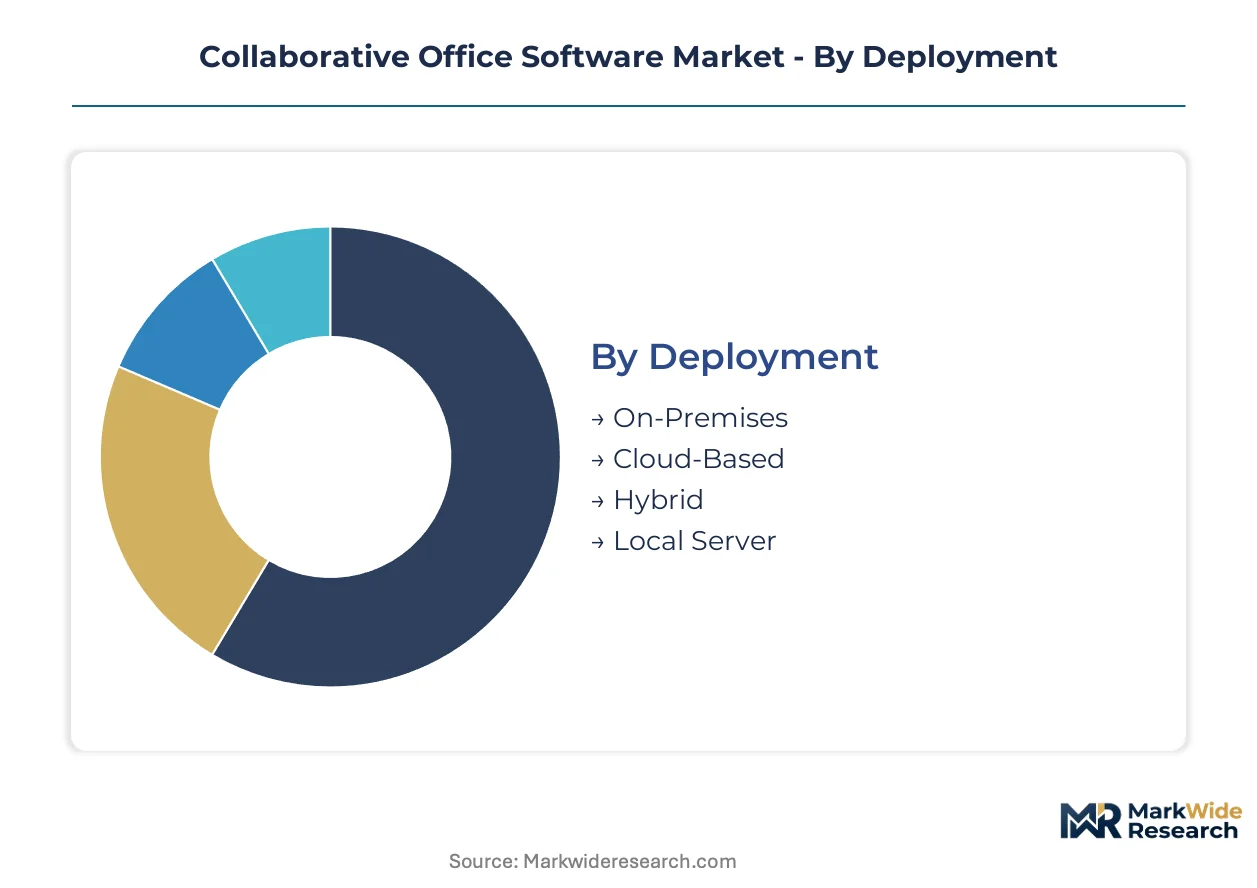
Segmentation in collaborative office software reveals how procurement criteria diverge across technical architectures and organizational scale. Understanding these fault lines exposes where vendor R&D investments concentrate and which customer profiles command premium pricing power.
Deployment:
Standalone cloud deployments dominate procurement volumes, while embedded hybrid configurations capture the steepest margin premiums from regulated verticals.
- Cloud-Based:Browser-native delivery with automatic update cycles eliminates capital expenditure barriers for distributed workforces. US federal agencies and European enterprises under GDPR pressure are consolidating seat agreements here, though data residency requirements are forcing regional infrastructure investments.
- Hybrid:Split architectures maintain sensitive document repositories on-premises while routing collaboration traffic through cloud gateways. Financial services firms in Germany and healthcare systems under HIPAA are driving this configuration's expansion.
- On-Premises:Fully captive infrastructure serving defense contractors and classified government facilities with air-gapped security requirements.
- Local Server:Single-tenant installations for mid-market manufacturers with legacy ERP integration constraints and limited IT staffing.
Cloud-Based leads volumes today; Hybrid is gaining share fastest.
End User:
Customer scale determines contract structure complexity, with procurement centralization correlating directly to platform stickiness and switching costs.
- Enterprise:Multi-year platform agreements spanning 10,000+ seats with centralized IT governance and custom compliance certifications. Fortune 500 technology departments and US defense contractors anchor this segment's contract values.
- Educational Institutions:Universities and K-12 districts converging learning management systems with workplace collaboration tools, creating new procurement cycles previously served by disconnected vendors.
- Small Business:Self-serve subscription tiers with standardized feature sets and minimal implementation support.
- Freelancers:Individual productivity suites with project-based billing and lightweight client collaboration features.
Enterprise commands absolute revenue contribution; Educational Institutions are expanding most quickly.
Solution:
Functional specialization depth shapes competitive moats, with integrated platforms displacing point solutions through workflow unification.
- Collaboration Platforms:Unified environments combining document creation, communication, and project coordination in continuous interfaces. Legal departments and pharmaceutical regulatory teams are adopting these tools fastest, collapsing demand for standalone contract lifecycle management.
- Document Management:Version-controlled repositories with audit trails and approval workflows, remaining critical for FDA-regulated clinical documentation.
- Project Management:Task orchestration systems with resource allocation and timeline visualization, sustaining loyalty among agile software teams.
- Communication Tools:Messaging and notification layers increasingly embedded as features rather than standalone purchases.
Collaboration Platforms lead volumes today; Document Management is climbing the fastest among regulated verticals.
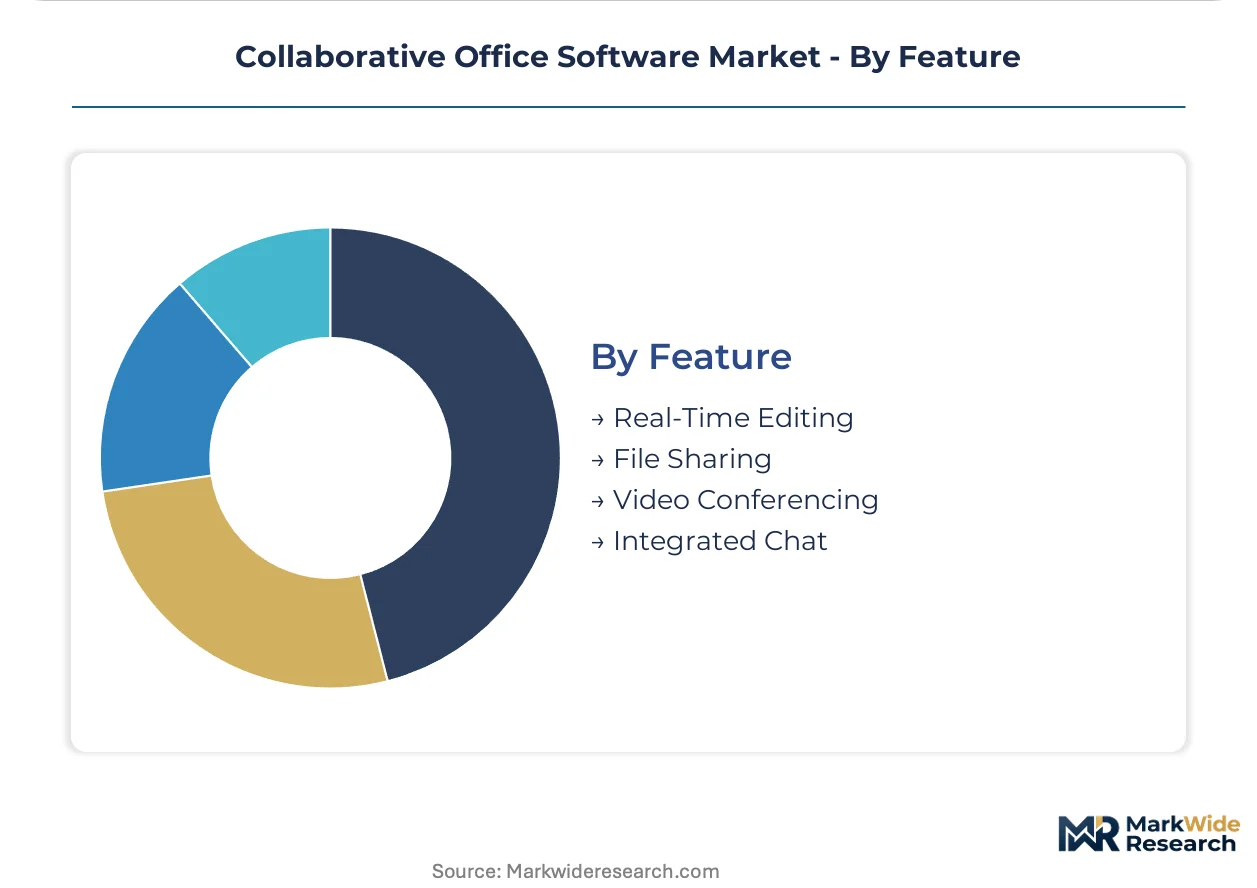
Feature:
Technical performance thresholds differentiate premium tiers, with latency-sensitive capabilities commanding infrastructure investments that smaller vendors cannot replicate.
- Real-Time Editing:Sub-100-millisecond synchronization engines enabling simultaneous document manipulation across distributed users. Edge computing deployments are expanding addressable markets in bandwidth-constrained environments.
- Video Conferencing:High-definition synchronous communication with AI-powered transcription and translation, now table stakes for enterprise procurement.
- File Sharing:Encrypted transfer protocols with granular permission architectures, commoditized across all major platforms.
- Integrated Chat:Persistent messaging layers embedded within document contexts, reducing context switching but raising e-discovery compliance burdens.
Real-Time Editing leads volumes today; Video Conferencing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in the United States, India, and Germany anchor collaborative office software development and enterprise procurement decisions. Cloud infrastructure density and regulatory stringency shape regional deployment preferences.
United States
Federal contractors and Fortune 500 technology departments drive demand for FedRAMP-authorized platforms with end-to-end encryption. HIPAA compliance requirements shape healthcare sector procurement specifications. Seattle and San Francisco Bay Area clusters concentrate vendor engineering operations and enterprise sales headquarters.
Germany
Industrial conglomerates and automotive manufacturers prioritize sovereign cloud deployments with domestic data residency. GDPR enforcement through the Federal Commissioner for Data Protection mandates regional infrastructure investments. Munich and Stuttgart engineering hubs sustain demand for developer-centric collaboration tools with on-premises integration capabilities.
India
IT services exporters and domestic unicorns scale seat agreements to support distributed delivery teams. The Digital Personal Data Protection Act creates compliance frameworks for cross-border workflow orchestration. Bangalore and Hyderabad technology corridors concentrate SaaS development centers and enterprise adoption pilots.
United Kingdom
Financial services firms in London and Edinburgh drive hybrid deployment configurations for regulated document workflows. The Information Commissioner's Office enforces GDPR-aligned data transfer protocols. Cambridge and Manchester technology clusters sustain startup adoption of AI-native workspace automation.
Japan
Manufacturing keiretsu and pharmaceutical companies require localized infrastructure with METI-aligned cybersecurity certifications. The Personal Information Protection Commission mandates explicit consent mechanisms for AI-assisted document processing. Tokyo and Osaka metropolitan areas concentrate enterprise procurement decision-making and vendor partnership negotiations.
Collaborative Office Software Market Competitive Landscape
The competitive structure tilts toward platform consolidators with multi-product integration capabilities. Enterprise procurement centralization favors vendors offering unified communication, document creation, and project coordination under single contracts. Three archetypes dominate: hyperscale cloud providers with productivity suite bundling, developer-tooling specialists with agile workflow integration, and security-focused vendors with federal compliance certifications. Dominant competitive moves include strategic partnerships with sovereign cloud operators and portfolio diversification into AI-native workflow automation.
Within the hyperscale platform tier, Microsoft and Google occupy positions defined by productivity suite integration depth and AI copilot deployment velocity. Atlassian represents the developer-centric specialization archetype, sustaining loyalty among software engineering teams through agile project tooling. These three companies exemplify how competitive positioning fragments between horizontal platform breadth and vertical workflow depth.
| Leading Market Players |
|---|
| Microsoft |
| Zoom |
| Salesforce |
| Cisco Systems |
| Atlassian |
| Slack Technologies |
| IBM |
| Adobe |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up collaboration specialists have compressed margin discipline across the mid-market tier, forcing hyperscale incumbents to defend pricing power through sovereign cloud bundling while regional data residency mandates inflate operational overhead. This ownership pattern concentrates supply-side negotiating leverage among three hyperscale platforms, translating into tiered subscription structures that penalize fragmented procurement.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise platform agreements from point-solution subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects compliance certification grade and integration complexity. Cost compression in the mid-market tier is intensifying because educational institutions and small businesses demand freemium entry points with transparent upgrade paths. Federal contractors and Fortune 500 technology departments exhibit the lowest price sensitivity due to security mandate non-negotiability, while K-12 districts and freelance users drive the steepest discount pressure.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand through vendor professional services organizations, displacing value-added resellers. Engineering talent concentrates in the United States, India, and Germany, with cloud infrastructure provisioning anchored in domestic data centers for GDPR, HIPAA, and FedRAMP compliance. The supply chain draws from specialized semiconductor foundries for edge computing hardware, undersea fiber consortiums for latency-sensitive synchronization, and sovereign cloud operators for regional custody. Single-source vulnerability in FedRAMP-authorized infrastructure creates procurement bottlenecks for defense contractors. Distribution runs through direct vendor relationships with centralized IT governance structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU AI Act compliance costs and US federal security clearance premiums creates margin expansion opportunities for vendors with dual-jurisdiction certification architectures. This geographic spread allows selective capacity placement where data residency mandates are least restrictive.
For Market Incumbents: Cement platform stickiness through deep integration of AI-native workflow automation with pre-validated quality management systems for FDA-regulated verticals. Defend against developer-centric specialists by acquiring agile tooling capabilities. Prioritize certification investment in sovereign cloud partnerships across France, Germany, and India where data localization mandates create captive demand.
For New Entrants and Emerging Players: Edge computing orchestration platforms offer a technology-first wedge into bandwidth-constrained environments where sub-100-millisecond latency requirements exceed incumbent infrastructure reach. Target educational institutions converging learning management systems with workplace collaboration tools, the most penetrable segment due to fragmented legacy procurement. Pursue white-label partnerships with established LMS providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with healthcare and financial services vertical depth. Long-term viability hinges on regulatory compliance engineering scarcity creating durable moats against SaaS commoditization. Monitor FDA draft guidance finalization on algorithmic decision support as the inflection indicator for clinical collaboration workflow automation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | GDPR and EU AI Act mandates in Germany and France require domestic data residency infrastructure. |
| AI-Native Workflow Automation | FDA-regulated pharmaceutical teams compress document turnaround from weeks to hours using generative copilots. |
| FedRAMP Authorization Acceleration | US defense contractors consolidate procurement around end-to-end encryption architectures with federal certification. |
| Educational Institution Convergence | Universities merge learning management systems with workplace platforms, opening previously disconnected seat agreements. |
| Edge Computing Infrastructure Deployment | Sub-100-millisecond latency targets expand addressable markets in bandwidth-constrained emerging economies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and enterprise software procurement databases. Bottom-up seat-count modeling and top-down market sizing triangulated volume estimates across deployment configurations, organization scales, and vertical applications.
Segment-weighting approaches distributed value across cloud-based, hybrid, on-premises, and local server deployments, with additional stratification by end-user scale and solution functional depth. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating AI adoption velocity, regulatory implementation timelines, and infrastructure investment cycles as software-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance finalization, EU AI Act enforcement intensity, and sovereign cloud partnership formation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Proofing Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Recruitment Software Market
Software & Services
Global Call Tracking Software Market
Software & Services
Home Design Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Human Identification Analysis Software Market
Software & Services
Webcasting Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Global SEO Software Market
Software & Services
Global Contract Lifecycle Management Software Market