
 Yield Monitoring Systems Market | 2026-2036
Yield Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Yield Monitoring Systems Market Analytics
Sub-inch GPS accuracy tier is unwinding older yield mapping standards across North American grain operations. Trimble Inc leverages its constellation correction services to dominate high-precision positioning for combine installations. Deere & Company anchors its installed base through proprietary CAN bus integration that locks in hardware-software bundles. AGCO Corporation competes via open-architecture platforms that accommodate third-party sensor arrays.
Yield monitoring systems comprise sensor arrays, GPS receivers, and data-logging modules that measure grain flow, moisture content, and georeferenced productivity across harvesting equipment. Core technical specifications include mass-flow sensor accuracy within one percent, moisture measurement ranges from eight to thirty-five percent, and sub-meter differential GPS correction for spatial resolution. Hardware segments sustain the majority of current revenue as combine OEMs bundle sensors with new equipment sales, while cloud solutions represent the fastest-expanding margin pool as subscription telemetry overtakes one-time software licenses. Agricultural producers occupy the dominant end-user position, though research institutions differentiate through grant-funded hyperspectral validation studies that stress-test commercial sensor calibration.
The USDA Natural Resources Conservation Service shapes demand through Environmental Quality Incentives Program cost-share provisions for precision agriculture adoption. EPA water-quality frameworks and state-level nutrient management regulations in Iowa and Illinois compel documented yield variability mapping as compliance infrastructure. Stakeholders must monitor evolving EPA Chesapeake Bay watershed rules and FCC rural broadband expansion timelines, as connectivity gaps determine whether cloud-based analytics or edge-computing architectures capture the next wave of farm-level deployment decisions.
Market Dynamics
Sub-inch GPS correction tiers are compressing hardware refresh cycles across North American grain operations, forcing incumbent sensor manufacturers to recalibrate pricing architectures against subscription-based telemetry models.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Cost-share provisions for precision agriculture adoption lower capital barriers for row-crop producers in Iowa and Illinois.
- IoT sensor miniaturization:Reduced component footprint enables retrofits on legacy combine fleets without hydraulic system overhauls.
- Water-quality compliance frameworks:EPA Chesapeake Bay watershed rules and state-level nutrient management regulations mandate documented yield variability mapping.
Market Restraints
- Silicon supply concentration:MEMS fabrication for mass-flow sensors depends on concentrated Asian foundry capacity, exposing lead times to geopolitical friction.
- Rural broadband gaps:FCC coverage maps overstate connectivity in Nebraska and Kansas, forcing edge-computing investments that inflate per-unit costs.
- CAN bus protocol fragmentation:Proprietary data architectures from major combine OEMs lock third-party sensors out of critical telemetry streams.
Strategic Opportunities
- Hyperspectral imaging convergence:Integration of near-infrared spectroscopy with yield monitors enables real-time grain protein mapping for premium pricing.
- Research institution channel:Grant-funded validation studies at land-grant universities create reference-grade calibration datasets that commercialize into subscription analytics.
- Brazilian soybean belt expansion:Unpenetrated large-scale operations in Mato Grosso lack localized moisture calibration curves, opening first-mover positioning for sensor-telemetry bundles.
Industry Challenges
- RF interference mitigation:Dense GPS correction networks in the Corn Belt suffer signal degradation from wind turbine installations, requiring firmware updates that strain technical support capacity.
- Data standardization delays:Competing file formats between cloud platforms force agricultural producers to maintain parallel data pipelines, increasing operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yield Monitoring Systems Market |
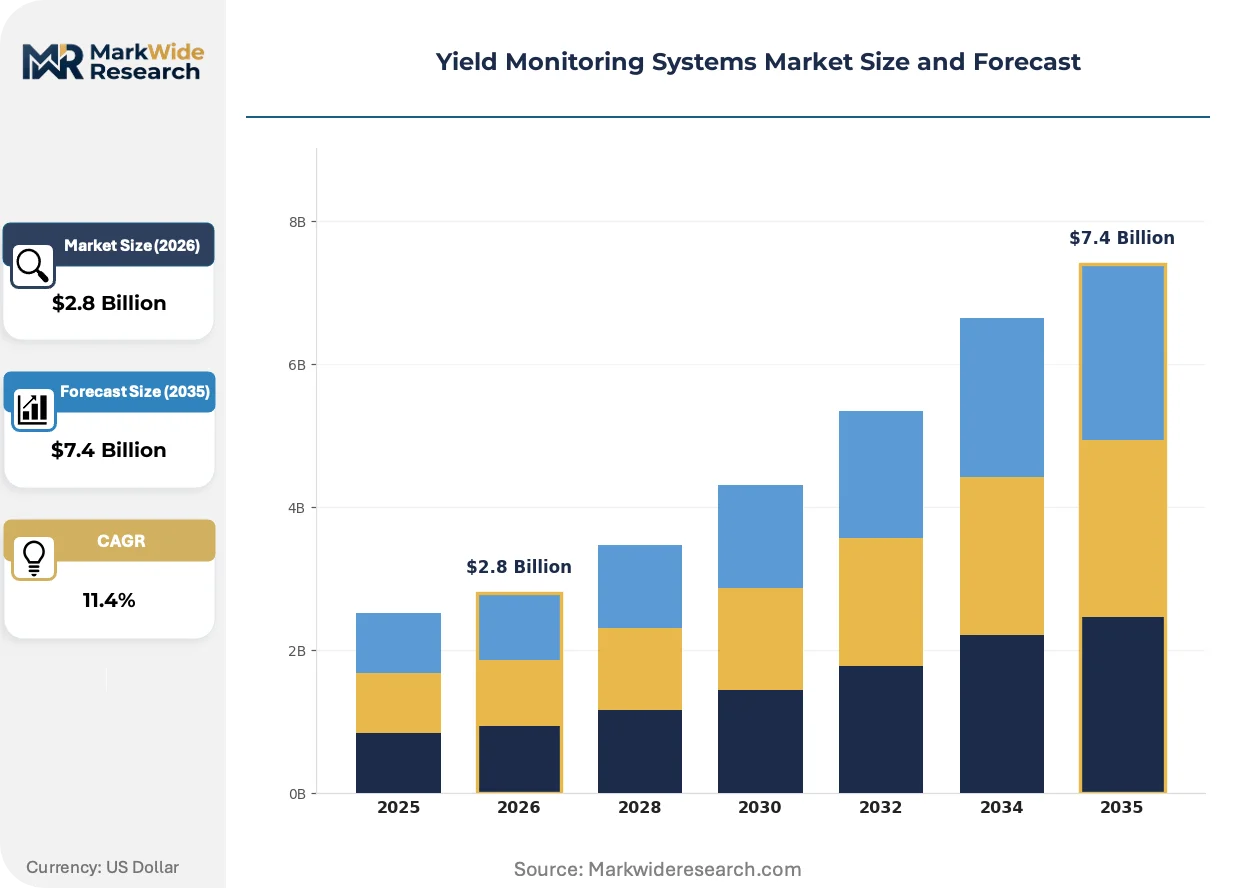
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integrated Systems, Cloud Solutions End User: Agricultural Producers, Agronomists, Research Institutions, Co-ops Installation Type: Fixed Systems, Mobile Systems, Portable Units, Stationary Equipment Technology: IoT, Data Analytics, Satellite Imaging, Remote Sensing |
| Companies Covered | Trimble Inc, AGCO Corporation, Deere & Company, CNH Industrial N.V., Ag Leader Technology, Raven Industries Inc., Topcon Corporation, Precision Planting Inc., AgJunction Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yield Monitoring Systems Market Evolving Landscape
Telemetry architectures are bifurcating between edge-heavy and cloud-native designs, with connectivity infrastructure determining which technical path dominates specific agricultural geographies.
Multi-spectral sensor arrays are miniaturizing from standalone units to integrated harvester-mounted modules. Large-scale producers across the US Corn Belt are retrofitting 2015-2019 combine vintages at accelerating pace. This compression of sensor form factors is miniaturizing the addressable market for aftermarket installation services while expanding OEM bundled-capture rates.
EPA water-quality frameworks now require documented nutrient management plans tied to georeferenced yield data. Industrial consequence falls most heavily on Illinois and Iowa operations exceeding 500 acres, where variability mapping becomes compliance infrastructure. Row-crop producers are responding by consolidating sensor purchases with telemetry subscriptions that automate report generation.
Service unbundling is separating hardware warranties from data analytics subscriptions. Agricultural equipment dealers in Minnesota and Indiana now face margin pressure as producers source sensors through OEM direct channels while purchasing cloud analytics from specialized software vendors. This channel fragmentation is most visible among 1,000-5,000 acre operations seeking to optimize per-acre technology spend.
Yield Monitoring Systems Market Segmentation
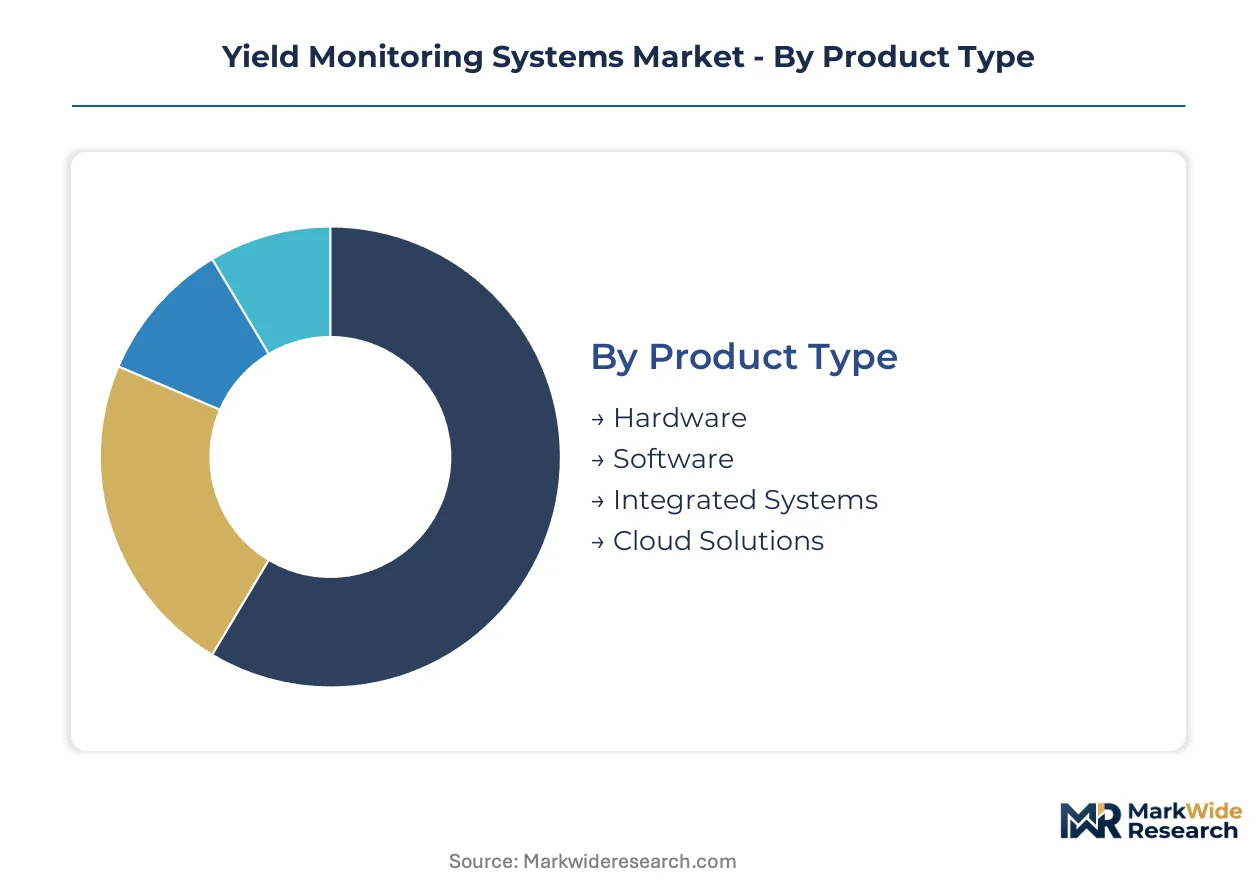
Yield monitoring systems fragment across product architectures, user sophistication, and connectivity infrastructure. Each segmentation axis carries distinct margin profiles and regulatory exposure. Understanding these divisions reveals where capital concentrates and which deployment models resist commoditization.
Product Type:
USDA cost-share provisions under the Environmental Quality Incentives Program favor capital-intensive hardware bundles over pure software plays, tilting procurement toward integrated physical systems.
- Hardware:Sensor arrays, GPS receivers, and data-logging modules form the physical measurement layer. Mass-flow sensors achieving one percent accuracy dominate combine retrofits across Iowa and Illinois row-crop operations, where equipment refresh cycles compress under sub-inch GPS correction mandates.
- Software:Yield mapping platforms and calibration algorithms process raw telemetry into actionable field intelligence. Demand concentrates among 1,000-5,000 acre operations seeking to unbundle dealer warranties from analytics subscriptions.
- Integrated Systems:OEM-bundled hardware-software combinations with proprietary CAN bus architectures. These configurations lock in installed base through factory-installed sensor arrays on new combine deliveries.
- Cloud Solutions:Subscription telemetry and remote data access platforms. FCC rural broadband gaps in Nebraska and Kansas force edge-computing investments that inflate per-unit costs for this segment.
Hardware handles the majority of throughput; cloud solutions are climbing the fastest on share.
End User:
Customer sophistication spans from compliance-driven documentation to grant-funded validation research, with procurement authority split between operational and institutional budgets.
- Agricultural Producers:Row-crop operators managing corn and soybean rotations across the US Corn Belt. EPA Chesapeake Bay watershed rules and state nutrient management regulations in Illinois compel documented yield variability mapping as compliance infrastructure.
- Agronomists:Independent crop consultants and input retailers delivering variable-rate prescriptions. These users prioritize open-architecture platforms that accommodate third-party sensor arrays across mixed equipment fleets.
- Research Institutions:Land-grant universities conducting hyperspectral validation studies. Grant-funded calibration datasets at these institutions stress-test commercial sensor accuracy and commercialize into reference-grade analytics.
- Co-ops:Member-owned purchasing and grain handling cooperatives. Shared equipment pools drive demand for portable sensor configurations that transfer across multiple combine platforms.
Agricultural producers absorb the dominant equipment volume; research institutions command premium pricing for validation-grade specifications.
Installation Type:
Physical mounting configurations determine retrofit feasibility on legacy fleets versus factory-integrated capture rates on new equipment.
- Fixed Systems:Permanent sensor installations on dedicated harvest equipment. These dominate large-scale operations in Iowa and Illinois where single-platform specialization justifies capital investment.
- Mobile Systems:Transferable configurations between multiple machines. Co-op shared-equipment pools and custom harvesting operations favor this flexibility despite calibration overhead.
- Portable Units:Rapid-attach sensor packages requiring minimal hydraulic integration. IoT sensor miniaturization enables retrofits on 2015-2019 combine vintages without system overhauls.
- Stationary Equipment:Fixed-location processing and measurement infrastructure. Grain elevator receiving facilities deploy these for inbound load verification independent of field-level monitoring.
Fixed systems anchor the installed base; portable units are expanding most quickly as retrofit demand accelerates.
Technology:
Data generation and transmission architectures bifurcate between edge-heavy and cloud-native designs, with connectivity infrastructure determining technical path dominance.
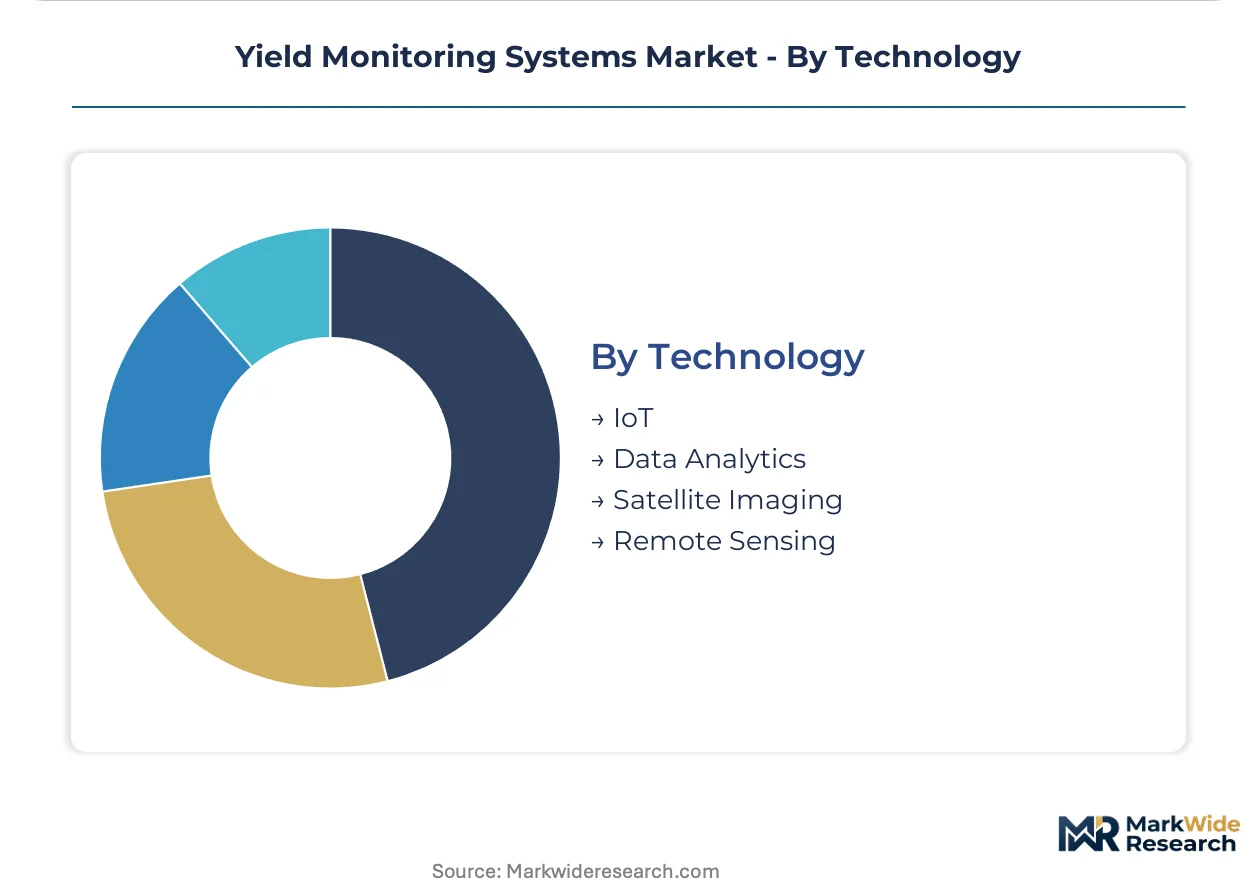
- IoT:Networked sensor arrays with embedded connectivity modules. Miniaturized MEMS fabrication enables mass-flow measurement in compact footprints, though Asian foundry concentration exposes lead times to geopolitical friction.
- Data Analytics:Machine learning pipelines for yield prediction and variability mapping. Research institutions differentiate through grant-funded algorithm development that commercializes into subscription services.
- Satellite Imaging:Remote sensing for pre-harvest crop health assessment. These platforms complement ground-based yield monitors but face resolution limitations for sub-field precision.
- Remote Sensing:Non-contact measurement including hyperspectral and near-infrared spectroscopy. Integration with yield monitors enables real-time grain protein mapping for premium pricing capture.
IoT sensors generate the dominant data volume; remote sensing shows the steepest expansion trajectory as hyperspectral convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in yield monitoring systems favor technology-exporting economies with advanced precision agriculture sectors over import-dependent agricultural regions. The United States and Germany generate trade surpluses in high-accuracy sensor assemblies, while Brazil and Australia remain net importers of telemetry infrastructure despite expanding domestic adoption.
United States
Corn Belt row-crop operations in Iowa and Illinois drive hardware refresh cycles as sub-inch GPS mandates compress equipment replacement timelines. USDA Environmental Quality Incentives Program cost-share provisions lower capital barriers for precision agriculture adoption. The Des Moines-Rock Island corridor concentrates OEM bundling activity where Deere and Trimble anchor factory-installed sensor deployments.
Brazil
Mato Grosso soybean belt expansion creates first-mover positioning for sensor-telemetry bundles lacking localized moisture calibration curves. ANVISA agricultural equipment registration requirements shape import timelines for foreign-manufactured sensor arrays. São Paulo-based dealer networks coordinate retrofit installations across the Cerrado frontier where 2015-2019 combine vintages dominate.
Germany
Baden-Württemberg precision engineering clusters supply MEMS fabrication for mass-flow sensors serving European combine OEMs. EU Green Deal agricultural digitization incentives accelerate telemetry adoption among East German large-scale cooperatives. Bavarian equipment manufacturers integrate yield monitors with ISOBUS-compliant architectures for export markets.
Australia
Wheat belt operations in Western Australia and New South Wales confront connectivity gaps that force edge-computing investments inflating per-unit telemetry costs. The country's national agricultural regulator mandates georeferenced yield documentation for drought relief eligibility. Adelaide-based research institutions develop hyperspectral validation datasets commercializing into subscription analytics for export.
Canada
Prairie Provinces canola and wheat producers adopt portable sensor configurations for seasonal equipment sharing across Saskatchewan and Manitoba cooperatives. Health Canada/PMRA equipment certification requirements delay deployment of non-validated moisture sensing technologies. Winnipeg-Toronto distribution channels consolidate procurement for 1,000-5,000 acre operations seeking unbundled warranty-analytics splits.
Yield Monitoring Systems Market Competitive Landscape
Listed leaders compete with private specialists across telemetry subscription models and hardware-software bundling architectures. The vendor base concentrates around three tiers: diversified agricultural equipment conglomerates with proprietary CAN bus ecosystems, pure-play precision agriculture technology firms with open-architecture platforms, and specialized sensor component suppliers serving retrofit markets. Strategic moves center on M&A-driven telemetry portfolio expansion and backward integration into MEMS fabrication capacity.
Within the diversified equipment tier, Deere & Company and AGCO Corporation exemplify contrasting bundling philosophies—proprietary lock-in versus third-party accommodation. Trimble Inc anchors the positioning-technology specialist segment with constellation correction services. Among precision agriculture pure-plays, Ag Leader Technology and Raven Industries Inc. occupy positions emphasizing open data architectures. Topcon Corporation represents the Japanese industrial conglomerate archetype with cross-sector sensor technology applications.
| Leading Market Players |
|---|
| Trimble Inc |
| AGCO Corporation |
| Deere & Company |
| CNH Industrial N.V. |
| Ag Leader Technology |
| Raven Industries Inc. |
| Topcon Corporation |
| Precision Planting Inc. |
| AgJunction Inc. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between combine OEMs and MEMS foundries lock in sensor supply access while anchoring hardware price visibility across multi-year refresh cycles. These arrangements concentrate procurement leverage among Deere, AGCO, and CNH Industrial, compressing margin capture for third-party retrofit suppliers dependent on spot-market component access.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the yield monitoring systems market. Premium tiers bundle sub-inch GPS correction with proprietary CAN bus integration, while economy configurations target 2015-2019 combine retrofits with portable sensor packages. Pricing pressure stems from subscription telemetry models displacing one-time software licenses, forcing hardware margin compression. Small-scale producers operating under 1,000 acres exhibit highest price sensitivity, whereas research institutions absorb premium validation-grade specifications without volume negotiation.
Supply Chain Analysis
Taiwan and South Korea anchor MEMS fabrication for mass-flow sensors serving North American and European combine OEMs. German precision engineering clusters in Baden-Württemberg supply secondary sensor assemblies and ISOBUS-compliant data modules. Raw material dependencies center on silicon wafers, rare-earth magnets for GPS antenna arrays, and specialized polymers for moisture-sensing housings. Single-source vulnerability concentrates in Taiwanese foundry capacity for sub-micron MEMS etching. Distribution runs through agricultural equipment dealer networks in Iowa, Illinois, and Mato Grosso, with direct OEM channels gaining share among large-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yield monitoring systems sit in early-cycle expansion as EPA water-quality compliance mandates in Illinois and Iowa convert documented yield variability mapping from optional precision agriculture into regulatory infrastructure. This compliance-driven tailwind accelerates hardware refresh cycles and telemetry subscription penetration simultaneously.
For Market Incumbents: Consolidate proprietary CAN bus ecosystems through backward integration into MEMS fabrication capacity, neutralizing third-party sensor interoperability threats. Lock in dealer channel control across the Des Moines-Rock Island corridor where OEM bundling captures factory-installed sensor deployments. Prioritize certification investment for EPA Chesapeake Bay watershed compliance documentation to anchor replacement demand cycles. For New Entrants and Emerging Players: ANVISA fast-track certification for Brazilian agricultural equipment creates first-mover positioning in Mato Grosso's unpenetrated soybean belt lacking localized moisture calibration curves. Target co-op shared-equipment pools in Saskatchewan and Manitoba seeking portable sensor configurations with minimal hydraulic integration. Pursue grant-funded validation partnerships with land-grant universities to commercialize reference-grade calibration datasets into subscription analytics. For Investors and Strategic Acquirers: Capital is best deployed toward open-architecture telemetry pure-plays with hyperspectral imaging convergence capabilities across the analysis window. These specialists command premium multiples as real-time grain protein mapping enables premium pricing capture for agricultural producers. Watch FCC rural broadband expansion timelines as the inflection signal determining whether edge-computing or cloud-native architectures dominate farm-level deployment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Imaging Integration | Near-infrared spectroscopy convergence enables real-time grain protein mapping for premium pricing capture. |
| MEMS Fabrication Backward Integration | Captive sensor production insulates against Asian foundry lead-time exposure and geopolitical friction. |
| Subscription Telemetry Migration | Recurring revenue models displace one-time software licenses across 1,000-5,000 acre producer segments. |
| ANVISA Certification Fast-Track | Brazilian regulatory approval unlocks first-mover positioning in Mato Grosso's expanding soybean belt. |
| Land-Grant University Partnership | Grant-funded validation studies commercialize into reference-grade calibration datasets for premium analytics tiers. |
Research Methodology
Operator-level perspectives from combine fleet managers, precision agriculture specialists at agricultural cooperatives, OEM procurement directors, and aftermarket service technicians anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against USDA Environmental Quality Incentives Program documentation, EPA Chesapeake Bay watershed compliance filings, FCC rural broadband coverage maps, and SEC 10-K disclosures from listed agricultural equipment manufacturers. Bottom-up equipment shipment tallies triangulated against top-down precision agriculture adoption curves across Iowa, Illinois, and Mato Grosso.
Sensitivity analysis tested forecast outputs against variable assumptions for sub-inch GPS correction penetration rates, IoT sensor miniaturization cost curves, and cloud telemetry subscription conversion ratios across the projection horizon. Segmentation dimensions modeled include product architecture, end-user sophistication tier, installation configuration, and connectivity infrastructure type. CAGRs derived from equipment refresh cycle compression analysis and regulatory mandate adoption timelines. Industry-specific inputs incorporated MEMS fabrication capacity utilization and hyperspectral imaging module cost trajectories.
Decision-makers should treat outputs as directional under sustained EPA water-quality enforcement and FCC rural broadband expansion assumptions; material deviation in either regulatory trajectory would warrant model refresh. Specific risk factors include silicon supply concentration disruption, CAN bus protocol fragmentation intensification, and Brazilian import tariff regime shifts. Recalibration cycles align with material shifts in precision agriculture incentive program funding and hyperspectral sensor commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Transportation Sensors Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
2D Barcode Reader Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Mobile Mapping Systems Market
Sensors
Machine Health Monitoring Market
Sensors
Eye Tracking Market
Sensors
Underground Utility Mapping Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Asset Tags Market
Sensors
Conveyor Monitoring Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Cloud Camera Market
Sensors
Vision Positioning System Market