
 Indoor Location Market | 2026-2036
Indoor Location Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Location Market Intelligence
Software-as-a-Service (SaaS) licensing for analytics and platform management is decoupling the value of indoor location solutions from one-time hardware sales. This shift creates recurring revenue streams for vendors. Cisco Systems, Inc. leverages its extensive enterprise networking footprint to bundle location services. Meanwhile, Qualcomm Incorporated specializes in the underlying semiconductor technologies that power a wide array of positioning devices.
Indoor location technologies identify the real-time geographic position of objects or people within a building. These systems utilize signals from various emitters to calculate position, often achieving sub-meter accuracy. While Wi-Fi-based solutions remain a mature segment, Ultra-Wideband (UWB) technology represents the fastest-growing segment due to its precision. Asset tracking and navigation assistance are the dominant applications, with strong uptake in retail chains and logistics companies.
Regulatory frameworks from bodies like the U.S. Federal Communications Commission (FCC) govern radio spectrum usage for positioning technologies. Concurrently, data privacy regulations such as Europe's GDPR impose strict requirements on the collection and processing of personal location data, shaping system design. Navigating the patchwork of spectrum allocation and privacy laws is a critical challenge for vendors seeking to scale their solutions across different jurisdictions.
Market Dynamics
The central dynamic is the market's pivot from hardware-centric deployments toward software and data analytics. This shift decouples solution value from one-time device sales, creating a new competitive landscape based on recurring revenue and platform-level services for vendors.
Growth Catalysts
- UWB Chipset Proliferation:The integration of Ultra-Wideband chipsets into smartphones creates a vast infrastructure for high-precision location services, lowering deployment barriers.
- Industrial Automation:Manufacturing and logistics firms in Germany and the United States adopt asset tracking to enhance supply chain visibility and support Industry 4.0.
- Worker Safety Mandates:Regulations from the U.S. Occupational Safety and Health Administration (OSHA) encourage personnel tracking in hazardous environments to monitor safety zones.
Market Restraints
- Spectrum Allocation Fragmentation:Disparate radio frequency regulations from bodies like the U.S. FCC complicate the development of universally compliant hardware, hindering global scalability.
- Signal Propagation Physics:The accuracy of radio-frequency systems degrades in environments with high metallic obstruction or multipath interference, common in heavy industrial plants.
- Legacy Technology Inertia:Existing Wi-Fi infrastructure provides "good enough" location data for some applications, slowing investment in more precise but costly UWB systems.
Strategic Opportunities
- Smart Building Integration:Tying location data to building management systems offers capabilities in energy efficiency, where occupancy information can dynamically control HVAC and lighting.
- Healthcare in Japan:Japan's aging demographic creates an opportunity for indoor navigation within hospitals and elder care facilities to assist patients and track medical equipment.
- Digital Twin Synchronization:Converging indoor positioning with digital twin platforms enables real-time monitoring and simulation of factory floor operations for predictive maintenance.
Industry Challenges
- Legacy System Integration:A significant hurdle is the complex and costly process of integrating modern location platforms with enterprises' existing ERP and security systems.
- Data Privacy Governance:Implementing robust consent management and data anonymization to comply with regulations like Europe's GDPR presents a continuous operational challenge.
- Interoperability Standards:The absence of a universal standard across vendors creates closed ecosystems, limiting customer choice and making multi-vendor deployments difficult.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Location Market |
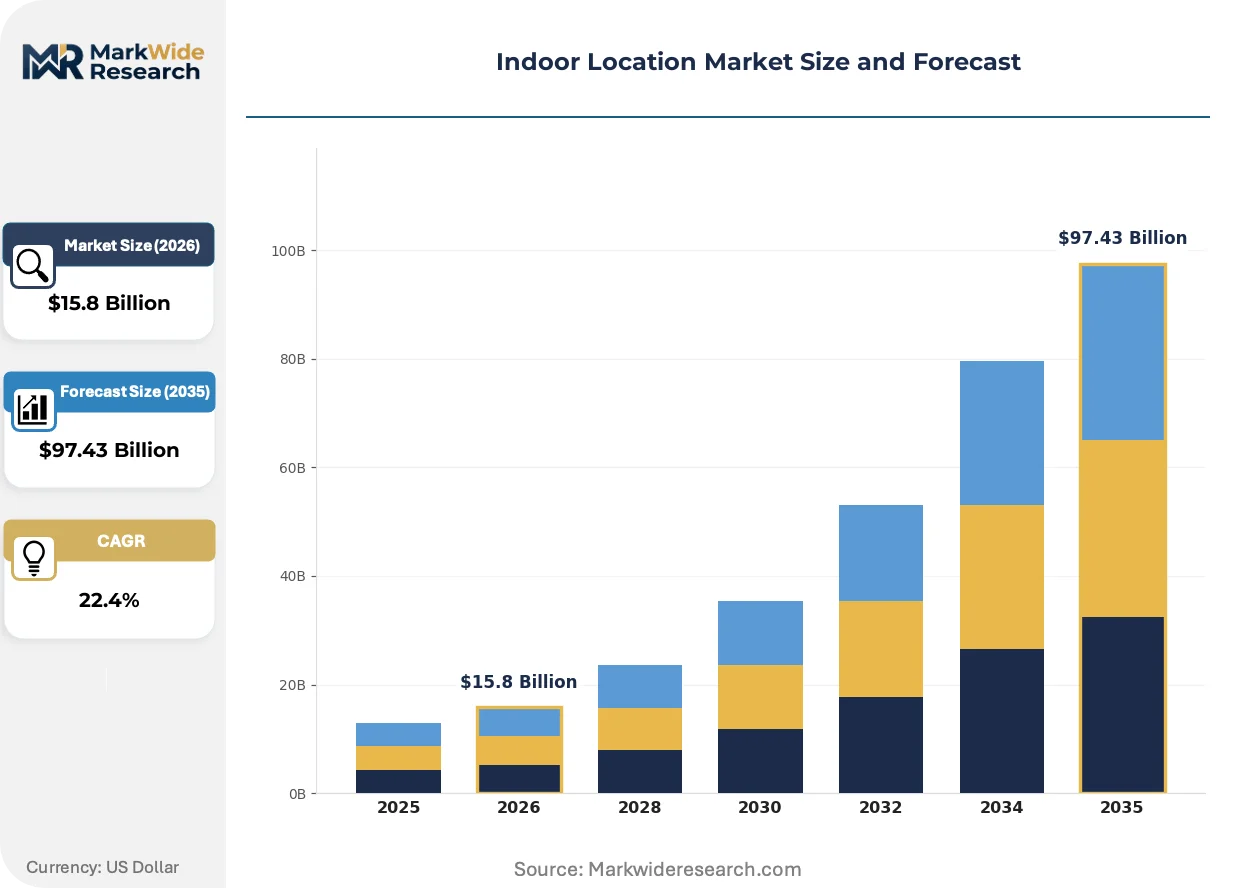
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $97.43 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth Low Energy, Ultra-Wideband, RFID, Infrared, Ultrasonic Application: Asset Tracking, Personnel Tracking, Visitor Management, Navigation Assistance, Inventory Management, Security Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing End User Industry: Retail Chains, Logistics Companies, Hospitality, Manufacturing Plants, Educational Institutions, Event Management |
| Companies Covered | Broadcom Inc., HERE Global B.V., Apple Inc., Inpixon, IndoorAtlas Ltd., Cisco Systems, Inc., Qualcomm Incorporated, Microsoft Corporation, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Location Market Strategic Shifts & Innovations
The market's evolution is defined by a move beyond simple position tracking toward contextual intelligence. Innovations are now focused on fusing multiple data streams to create richer analytics and actionable insights for enterprise operations.
Sensor fusion combines inputs from UWB, inertial measurement units, and other signals to deliver reliable positioning. High-value asset management in logistics and aerospace is adopting this technique. This multi-modal approach is overtaking single-technology solutions in critical applications where consistent accuracy is paramount.
Regulatory frameworks on data privacy, particularly Europe's GDPR, mandate strict user consent and purpose limitation. This forces vendors to engineer privacy-by-design features like on-device processing and anonymization. The retail and corporate real estate sectors are most affected, prioritizing solutions with clear compliance pathways.
Subscription-based licensing for analytics platforms is becoming the dominant model, shifting focus from one-time hardware sales. This allows enterprises to treat location services as an operating expense, lowering the barrier to entry. This procurement behavior is most advanced in North American retail for customer journey analysis.
Indoor Location Market Segmentation
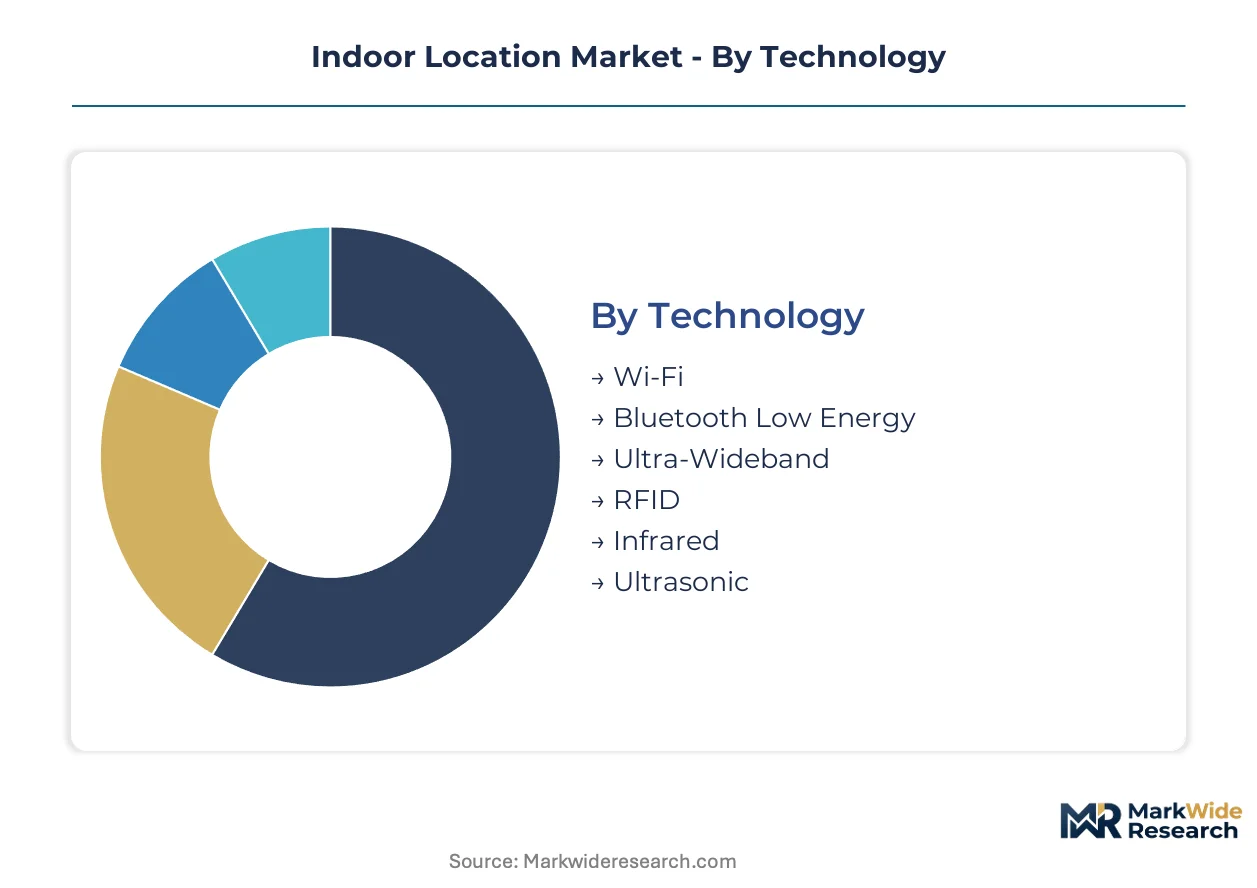
The Indoor Location Market segments across distinct technological approaches, diverse application areas, deployment models, and end-user industries. Understanding these differentiations is crucial for vendors to align product development with specific enterprise requirements and for enterprises to select solutions optimized for their operational contexts.
Technology:
Enterprises frequently evaluate indoor location technologies based on their existing infrastructure's upgrade cycle and the precision requirements of new applications.
- Ultra-Wideband:This technology provides highly accurate, real-time positioning data using short-range radio signals. Demand concentrates in logistics and manufacturing facilities in the United States and Germany, driven by the need for sub-meter precision in asset tracking.
- Wi-Fi:Leveraging existing wireless network infrastructure, Wi-Fi-based solutions offer broad coverage for location services, albeit with lower precision than UWB. Retail chains in developed economies utilize Wi-Fi for visitor management and basic navigation assistance due to its cost-effectiveness.
- Bluetooth Low Energy:BLE beacons emit signals that smartphones and other devices can detect for proximity-based location services and micro-navigation.
- RFID:Radio Frequency Identification tags are passive or active devices used for identifying and tracking objects within a defined area.
- Infrared:Infrared systems use line-of-sight signals for highly localized positioning, often in controlled environments for specific tasks.
- Ultrasonic:Ultrasonic technology employs sound waves for precise indoor positioning, frequently used in niche industrial automation applications.
Volume placements concentrate in Wi-Fi solutions; the faster expansion belongs to Ultra-Wideband technology.
Application:
The core value proposition for indoor location solutions centers on specific operational outcomes across diverse enterprise applications.
- Asset Tracking:This application involves monitoring the real-time location of valuable equipment, tools, and inventory within a facility. Logistics companies and manufacturing plants in Germany and the United States implement asset tracking to enhance supply chain visibility and operational efficiency.
- Navigation Assistance:Providing intuitive indoor directions helps individuals find their way within large, complex buildings. Retail chains and healthcare facilities in Japan leverage navigation assistance to improve customer experience and guide patients.
- Personnel Tracking:Monitoring the location of staff members enhances safety, particularly in hazardous industrial environments, and optimizes workforce management.
- Visitor Management:Solutions for visitor management streamline check-ins, provide directional guidance, and analyze traffic flows in public and commercial spaces.
- Inventory Management:Optimizing the location and movement of goods within warehouses and retail stores improves stock accuracy and reduces search times.
- Security:Indoor location systems enhance security protocols by monitoring restricted areas, tracking suspicious movements, and aiding emergency response.
Asset tracking and navigation assistance command significant market share; personnel tracking solutions are gaining traction in safety-critical sectors.
Deployment:
Customer preferences for indoor location deployment models often reflect internal IT capabilities and data governance policies.
- Cloud-Based:These solutions host the location platform and data processing on remote servers, accessed via the internet. Retail enterprises in North America favor cloud-based models for their scalability and lower upfront infrastructure costs, often adopting SaaS licensing.
- On-Premise:On-premise deployments involve installing and managing the location system infrastructure directly within the client's facility. Manufacturing plants and government entities prioritize on-premise solutions for enhanced data security and control over sensitive operational data.
- Hybrid:Hybrid models combine elements of both cloud-based and on-premise deployments, allowing flexibility for data storage and processing.
- Edge Computing:Edge computing processes location data closer to the source, reducing latency and bandwidth requirements for real-time applications.
Cloud-based platforms offer scalability advantages; on-premise deployments provide enhanced data control for sensitive operations.
End User Industry:
The maturity of indoor location adoption varies significantly across different end-user industries, reflecting distinct operational needs.
- Retail Chains:Large-scale retail chains adopt indoor location for visitor management, customer journey analysis, and optimizing store layouts. North American retail segments show strong uptake for understanding shopper behavior.
- Logistics Companies:Logistics providers utilize indoor location for precise asset tracking, fleet management within warehouses, and optimizing material flow. German logistics firms integrate these systems to enhance supply chain visibility.
- Manufacturing Plants:Industrial automation initiatives, particularly Industry 4.0, drive the adoption of indoor location for tracking work-in-progress and personnel safety.
- Hospitality:Hotels and resorts use indoor location for guest services, staff management, and optimizing facility operations.
- Educational Institutions:Universities and schools deploy indoor navigation for students and staff, and for tracking valuable equipment.
- Event Management:Indoor location solutions enhance attendee experience, manage crowd flow, and track assets at large-scale events.
Retail chains and logistics companies drive the largest demand volumes; manufacturing plants exhibit a rapidly expanding need for precision tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial heartland, particularly in Bavaria and North Rhine-Westphalia, drives significant demand for indoor location systems. Developed economies like the United States and Japan also exhibit strong market growth, fueled by specific industry needs and technological advancements. These regions are actively integrating indoor location solutions into their operational frameworks.
United States
Manufacturing facilities and large retail chains in the United States demand precise indoor location for asset tracking and customer analytics. The U.S. FCC regulates spectrum usage, impacting hardware design for positioning technologies. Silicon Valley and Texas industrial zones actively integrate UWB and sensor fusion for advanced operational insights.
Germany
Industrial automation initiatives in Germany, especially within logistics and manufacturing, propel the adoption of high-precision indoor location. Europe's GDPR imposes strict data privacy requirements, shaping system design for personnel tracking. The Ruhr region and Bavaria demonstrate strong uptake for Industry 4.0 applications.
Japan
Japan's aging demographic creates a strong need for indoor navigation within healthcare facilities and elder care centers. The METI promotes smart building technologies, encouraging integration of location services for energy efficiency. Tokyo and Osaka's advanced urban infrastructure support sophisticated indoor positioning deployments.
China
Rapid expansion of smart factories and vast retail networks across China fuels demand for indoor location solutions. The MIIT guides technology development and spectrum allocation for positioning systems in industrial settings. Yangtze River Delta and Pearl River Delta manufacturing hubs are integrating these systems for efficiency gains.
United Kingdom
UK retail chains and smart infrastructure projects seek indoor location for visitor management and operational optimization. GDPR compliance is a critical factor for systems handling personal location data in commercial environments. London's commercial districts and technology clusters are exploring advanced indoor mapping applications.
Indoor Location Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure for indoor location solutions. The competitive landscape fragments across specialized hardware manufacturers, dedicated software platform providers, and integrated solution developers. Strategic partnerships and technology licensing agreements are common competitive moves among these diverse entities.
Semiconductor specialists like Qualcomm Incorporated anchor the underlying technology stack for a wide array of positioning devices. Cisco Systems, Inc. exemplifies an integrated approach, leveraging its extensive enterprise networking footprint to bundle location services. Consumer electronics giant Apple Inc. occupies a position driving UWB chipset proliferation into mainstream devices.
| Leading Market Players |
|---|
| Broadcom Inc. |
| HERE Global B.V. |
| Apple Inc. |
| Inpixon |
| IndoorAtlas Ltd. |
| Cisco Systems, Inc. |
| Qualcomm Incorporated |
| Microsoft Corporation |
| Google LLC |
| Others |
Cost & Logistics Intelligence
Enterprises' increasing preference for OpEx models compels hardware vendors to integrate SaaS offerings, recalibrating traditional hardware-centric pricing structures. This shift drives a move towards recurring revenue models.
Pricing Analysis
Cost compression in basic UWB hardware is intensifying because chipset proliferation drives down component costs. Subscription-based licensing for analytics platforms dominates the market, shifting focus from one-time sales. Price differentiation stems from customization levels for specific enterprise needs and comprehensive after-sales service bundles. North American retail segments exhibit higher price sensitivity for initial deployments, while German logistics firms prioritize solution robustness over the lowest cost.
Supply Chain Analysis
Dual-sourcing requirements for critical UWB chipsets mitigate supply disruptions for indoor location system integrators. Component supply primarily centers on manufacturing hubs in China and Taiwan for semiconductors, with specialized industrial sensors often sourced from Germany. The ecosystem relies on a stable supply of UWB chipsets, creating single-source vulnerability for advanced technologies. Distribution runs through direct sales channels for large enterprise deployments and a network of system integrators for smaller-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The indoor location market is poised for consolidation, driven by intense pricing pressure on basic hardware solutions forcing smaller, undifferentiated vendors to exit. This creates opportunities for strategic acquisitions.
For Market Incumbents:Lock in existing enterprise customers by deepening integration with their ERP and building management systems. Expand subscription-based SaaS offerings to counter the commoditization of basic hardware, which threatens margins. Invest in R&D for advanced sensor fusion capabilities, addressing the threat from emerging pure-play software vendors. Leverage established enterprise networking footprints for bundled location services, reinforcing channel control.
For New Entrants and Emerging Players:Begin with highly specialized niche applications where existing solutions fall short, such as healthcare navigation in Japan. Target smart building integration for energy efficiency, leveraging occupancy data from location systems. Mid-sized facilities in specific verticals requiring specialized solutions represent the most penetrable segment for focused entry. Differentiate through value-based pricing models tied directly to demonstrable operational efficiency gains for customers.
For Investors and Strategic Acquirers:Re-rating potential sits with pure-play SaaS providers given the shift to recurring revenue models and strong platform stickiness. The market offers long-term viability, driven by the essential role of indoor location in enterprise digital transformation initiatives. Acquisition targets should focus on companies with proprietary analytics and strong integration capabilities. UWB chipset adoption rates in new consumer devices serve as a critical signal for future market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances stickiness for enterprise clients and reduces deployment friction. |
| SaaS Offering Expansion | Shifts revenue to recurring models and lowers customer entry barriers. |
| Sensor Fusion R&D | Improves accuracy and reliability in complex industrial environments. |
| Niche Vertical Specialization | Captures underserved segments with high-value application requirements. |
| UWB Chipset Partnerships | Secures component supply and influences future technology roadmaps. |
Research Approach
Independent corroboration across industry association reports, technology vendor whitepapers, and patent databases underwrites the qualitative findings. This study integrates primary interviews with CTOs, IT procurement officers, logistics managers, and facility managers, alongside secondary validation. Bottom-up market sizing and top-down revenue analysis provide a robust framework. Academic research and regulatory filings further inform the analysis.
Rate-of-change decomposition across technology adoption curves and end-user spending patterns drives the market forecast. The analytical framework models market evolution across the analysis window, segmented by technology, application, deployment, and end-user industry. Compound annual growth rates derive from historical trends and projected technological advancements. UWB chipset integration rates and evolving regulatory compliance costs serve as key forecast inputs.
Geopolitical shifts, rapid technological disruption, and unexpected regulatory changes are the dominant revision risks. Forecasts reflect current market assumptions, but these factors introduce volatility. Deviation in UWB standardization or privacy legislation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global Remote Tank Monitoring System Market
Sensors
Vision Positioning System Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Drain Camera Market
Sensors
Refrigeration Monitoring Market
Sensors
Indoor Positioning and Navigation Market
Sensors
Weigh-In-Motion System Market
Sensors
Machine Health Monitoring Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
IO Link Market
Sensors
Global Positioning Systems Market
Sensors
Underground Service Locator Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Industrial Automation Sensors Market