
 Diameter Signaling Control Market | 2026-2036
Diameter Signaling Control Market Size, Share, and Industry Trends Forecast 2026-2036
Diameter Signaling Control Market Outlook
The EU AI Act is broadening compliance obligations for automated network management systems that process subscriber signaling data across European telecommunications infrastructure. Oracle Corporation leverages its consolidated signaling portfolio to sustain enterprise-grade deployment credibility in carrier core networks. Cisco Systems Inc. anchors its position through integrated policy and routing architectures that dominate North American operator procurement cycles.
Diameter Signaling Control encompasses the routing, translation, and policy mediation infrastructure that manages authentication, authorization, and accounting messages between mobile core network elements using the Diameter protocol at transaction rates exceeding millions of operations per second. Its primary commercial purpose is ensuring scalable subscriber session management while preventing signaling storms that degrade voice-over-LTE and 5G core services. Cloud deployment configurations are capturing accelerated procurement momentum as hyperscale carriers virtualize signaling functions to reduce capital intensity and improve elasticity. Diameter technology itself remains the revenue backbone despite SIP and HTTP/2 migration trajectories because legacy IMS interworking requirements persist through at least the next technology transition cycle.
3GPP standards frameworks and ETSI NFV specifications govern functional architecture and interoperability testing for virtualized signaling controllers sold into European operator environments. The FCC in the United States enforces network reliability directives that elevate signaling resilience to a compliance-mandated procurement criterion for nationwide carriers. Stakeholders must monitor how 3GPP Release 18 and subsequent specifications reframe Diameter's role relative to HTTP-based service-based architectures in 5G-Advanced core implementations.
Market Dynamics
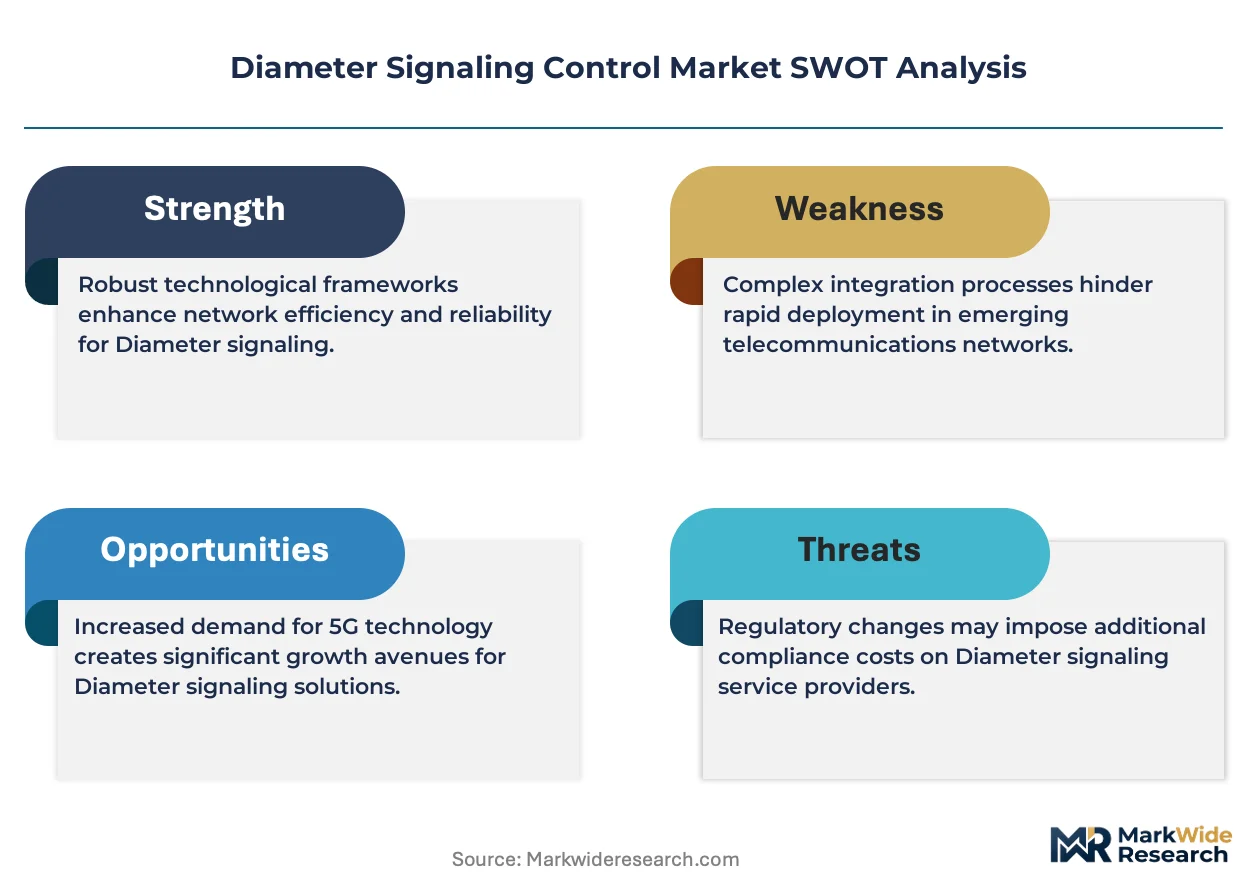
The migration from hardware-based signaling controllers to cloud-native network functions is compressing deployment timelines and forcing incumbent vendors to rearchitect product portfolios around Kubernetes-orchestrated containers. This infrastructure transformation sits at the center of carrier procurement decisions.
Growth Catalysts
- 5G Standalone Core Deployments:Mobile operators in India and South Korea are mandating Diameter routing agent upgrades to support service-based architecture interworking with legacy IMS cores.
- EU AI Act Compliance:Automated signaling analytics platforms must now embed audit trails and human oversight mechanisms for subscriber data processing across European networks.
- GSMA Open Gateway:Standardized northbound APIs for network capability exposure are creating fresh demand for policy mediation layers that translate Diameter into RESTful service interfaces.
Market Restraints
- Silicon Supply Concentration:Advanced packet processing ASICs for high-throughput signaling controllers depend on TSMC fabrication capacity concentrated in Taiwan.
- Protocol Substitution Pressure:HTTP/2 and gRPC service meshes in 5G-Advanced cores threaten Diameter's role in authentication flows, forcing dual-stack investment cycles.
- ETSI NFV Certification Burden:Virtualized network function validation timelines extend 14-18 months for European operators, delaying revenue recognition for software vendors.
Strategic Opportunities
- Private 5G Enterprise Networks:Manufacturing campuses and logistics hubs in Germany require localized Diameter policy control for sliced industrial IoT connectivity.
- Edge Signaling Micro-Clouds:Distributed user plane functions in multi-access edge computing sites need compact Diameter routing agents with sub-10 millisecond latency guarantees.
- India Production-Linked Incentive:The PLI scheme for telecom equipment manufacturing is attracting signaling controller assembly investments to Pune and Chennai industrial corridors.
Industry Challenges
- Container Orchestration Expertise Gap:Tier-2 operators lack internal Kubernetes engineering capacity to manage cloud-native signaling function lifecycles.
- Interoperability Testing Complexity:Multi-vendor Diameter stack validation for roaming federation requires sustained investment in protocol conformance labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diameter Signaling Control Market |
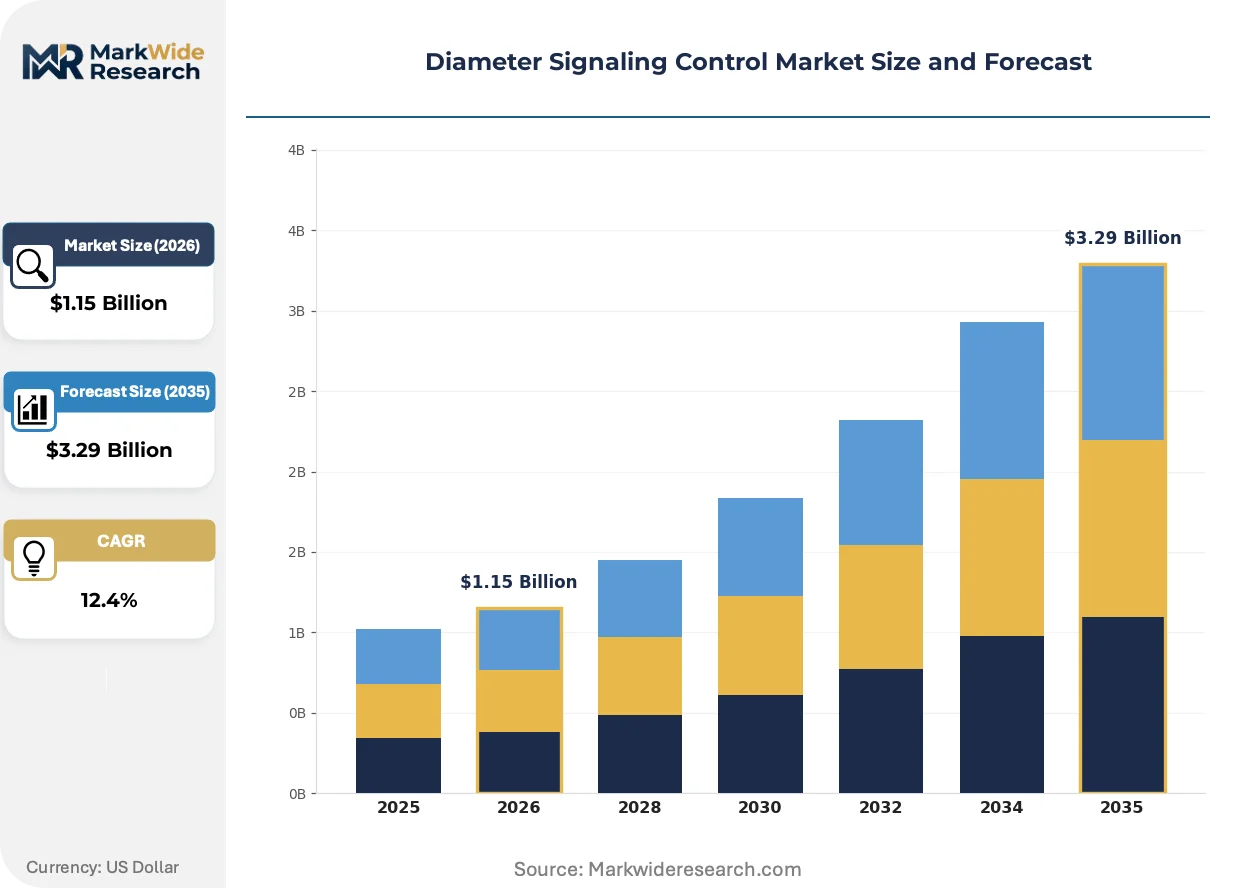
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SS7, SIP, Diameter, HTTP/2 Deployment: Cloud, On-Premises, Hybrid, Virtual End User: Telecommunications, Cloud Providers, Enterprises, Data Centers Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | Oracle Corporation, Cisco Systems Inc., Huawei Technologies Co., Ltd., Nokia Corporation, Ericsson AB, F5 Networks, Enghouse Systems, Juniper Networks Inc., Mavenir Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diameter Signaling Control Market Strategic Shifts
Control plane disaggregation is fragmenting monolithic signaling architectures into composable microservices, enabling carriers to swap individual functions without core network overhaul. This modularization trend is rewriting vendor competitive dynamics and procurement evaluation criteria.
Service mesh technology is decentralizing policy enforcement from centralized Diameter routing agents to sidecar proxies colocated with individual network functions. Tier-1 carriers in Japan and South Korea are piloting Istio-based control planes for subscriber session management. The architectural shift is compressing vendor switching costs and enabling best-of-breed component sourcing.
The EU AI Act is mandating algorithmic transparency for automated network optimization systems that process Diameter signaling metadata. European operators must now maintain model cards documenting decision logic for congestion control and fraud detection algorithms. Compliance investments are elevating procurement weightings for explainable AI capabilities in signaling analytics platforms.
Hyperscale cloud providers are unbundling traditional signaling hardware procurement by offering Diameter routing as a managed network function on sovereign cloud instances. German automotive manufacturers building private 5G networks are sourcing signaling control through AWS and Azure marketplace channels rather than direct OEM relationships. The channel shift is fragmenting vendor-customer relationships and compressing pricing power for traditional equipment suppliers.
Diameter Signaling Control Market Segmentation
Diameter Signaling Control procurement splits sharply between legacy protocol maintenance and cloud-native transformation investments. Carrier technology roadmaps and regulatory compliance requirements reshape how each segment captures operator budgets across deployment cycles.
Technology:
Volume concentrates in mature signaling stacks sustaining interworking requirements, while premium pricing attaches to HTTP-based architectures enabling 5G-Advanced service meshes.
- Diameter:The incumbent transaction protocol manages authentication, authorization, and accounting at millions of operations per second across IMS cores. Indian operators Reliance Jio and Bharti Airtel are mandating Diameter routing agent upgrades for VoLTE convergence, sustaining procurement momentum despite protocol aging.
- HTTP/2:Service-based architecture interfaces in 5G standalone cores are displacing Diameter for new authentication flows. South Korean carriers piloting HTTP/2 signaling meshes report reduced latency for network slice selection, though dual-stack investments persist for legacy interworking.
- SS7:Legacy circuit-switched signaling persists for 2G/3G interworking and roaming federation in emerging markets.
- SIP:Session initiation protocol stacks handle VoLTE and VoNR call control alongside Diameter policy binding.
Today's leader: Diameter. Tomorrow's challenger: HTTP/2.
Deployment:
Cost tier separation runs deepest between capital-intensive hardware refresh and operating-expense-driven cloud subscriptions.
- Cloud:Kubernetes-orchestrated network functions on hyperscale infrastructure compress deployment timelines from months to weeks. German automotive manufacturers sourcing private 5G signaling through AWS and Azure marketplace channels are accelerating this shift away from direct OEM procurement.
- Hybrid:Mixed environments preserve on-premises policy control while bursting analytics workloads to sovereign cloud instances. European operators under EU AI Act compliance mandates favor hybrid deployments for audit trail localization.
- On-Premises:Dedicated hardware controllers dominate Tier-1 carrier core networks requiring sub-millisecond latency guarantees.
- Virtual:ETSI NFV-compliant virtualized network functions extend hardware lifecycle through software abstraction layers.
Cloud deployments are expanding most quickly; on-premises maintains the revenue base.
End User:
Customer type stratification separates volume-driven carrier procurement from emerging enterprise segment premiums.
- Telecommunications:Mobile network operators constitute the foundational demand base for Diameter routing infrastructure. 5G standalone core deployments across India and South Korea are driving the largest current procurement cycles for signaling control modernization.
- Enterprises:Manufacturing campuses and logistics hubs in Germany are deploying localized Diameter policy controllers for industrial IoT network slicing. Private 5G licensing frameworks are unlocking this greenfield segment for specialized signaling vendors.
- Cloud Providers:Hyperscalers bundle signaling functions into managed network service portfolios for enterprise resale.
- Data Centers:Colocation facilities host virtualized signaling controllers for regional carrier edge expansion.
Telecommunications anchors volume; enterprises are climbing fastest.
Service Type:
Margin structure favors recurring revenue streams over one-time implementation fees.
- Support:24/7 operational assistance for mission-critical signaling infrastructure commands premium pricing. FCC network reliability directives in the United States elevate support contracts to compliance-mandated procurement criteria for nationwide carriers.
- Maintenance:Software updates and security patch management for virtualized network functions generate predictable recurring revenue. ETSI NFV certification requirements extend maintenance engagement durations as validation cycles stretch 14-18 months.
- Consulting:Architecture design and migration planning services guide protocol transition strategies.
- Integration:Multi-vendor stack interoperability testing and deployment execution for roaming federation.
Support commands the premium; maintenance delivers the annuity base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Diameter Signaling Control industry traces its commercial scaling to early 4G LTE deployments in Western Europe and North America during the 2010s, where mobile operators first required centralized routing infrastructure to manage authentication storms across converged IMS cores.
United States
AT&T and Verizon Communications are driving 5G standalone core modernization programs that mandate Diameter routing agent upgrades for legacy interworking. The FCC enforces network reliability directives that elevate signaling resilience to compliance-mandated procurement criteria for nationwide carriers. Dallas-Fort Worth and Seattle metropolitan clusters host concentrated engineering centers where cloud-native signaling function development accelerates.
India
Reliance Jio and Bharti Airtel are executing the world's largest concurrent Diameter routing deployments to support VoLTE convergence and 5G core interworking. TRAI spectrum allocation frameworks and the PLI scheme for telecom equipment manufacturing are attracting signaling controller assembly investments to Pune and Chennai industrial corridors. Bangalore and Hyderabad technology hubs concentrate vendor engineering support for these carrier modernization cycles.
Germany
Deutsche Telekom and Vodafone Germany are deploying localized Diameter policy controllers for private 5G network slicing across automotive manufacturing campuses. The EU AI Act mandates algorithmic transparency for automated signaling analytics platforms processing subscriber metadata. Stuttgart and Munich industrial regions anchor demand for edge signaling micro-clouds with sub-10 millisecond latency guarantees.
South Korea
SK Telecom and KT Corporation are piloting HTTP/2 service mesh architectures that displace Diameter for new 5G-Advanced authentication flows while maintaining dual-stack legacy interworking. MFDS cybersecurity frameworks govern virtualized network function certification timelines for carrier core deployments. Seoul metropolitan area technology clusters concentrate vendor interoperability testing labs for multi-vendor stack validation.
United Kingdom
BT Group and Vodafone UK are migrating signaling control to hybrid cloud configurations that preserve on-premises policy control while bursting analytics workloads to sovereign cloud instances. GDPR and post-Brexit data localization requirements are elevating procurement weightings for audit trail localization capabilities. London and Reading technology corridors host concentrated carrier procurement decision centers for European signaling infrastructure.
Diameter Signaling Control Market Competitive Environment
Premium-margin players sit above commodity-margin players across deployment complexity tiers, with consolidated signaling portfolios commanding sustained enterprise-grade credibility in Tier-1 carrier core networks. The vendor base organizes around three strategic archetypes: integrated networking conglomerates with consolidated policy-routing portfolios, specialized signaling software vendors with cloud-native transformation expertise, and telecommunications equipment suppliers with embedded carrier relationships. Dominant competitive moves include strategic partnerships with hyperscale cloud providers for managed network function distribution and vertical integration into container orchestration platforms to compress deployment timelines.
Within the integrated networking tier, Oracle Corporation and Cisco Systems Inc. exemplify archetype positioning through consolidated signaling portfolios that anchor carrier procurement cycles. Nokia Corporation occupies a position representing European telecommunications equipment heritage with embedded operator relationships across EMEA markets. These three entities sit within the premium-tier vector where enterprise-grade deployment credibility determines competitive positioning.
| Leading Market Players |
|---|
| Oracle Corporation |
| Cisco Systems Inc. |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Ericsson AB |
| F5 Networks |
| Enghouse Systems |
| Juniper Networks Inc. |
| Mavenir Systems Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud-native containerization of signaling functions is compressing deployment economics while fragmenting procurement channels away from traditional OEM relationships toward hyperscale marketplace distribution. This infrastructure transition simultaneously reduces capital intensity for buyers and erodes pricing power for hardware-centric incumbents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Oracle and Cisco enterprise deployments from Mavenir cloud-native offerings and white-label virtualized controllers. Price differentiation hinges on ETSI NFV certification grade and bundled 24/7 operational support contracts mandated by FCC reliability directives. Pricing pressure stems from AWS and Azure marketplace channels offering Diameter routing as managed network functions to German automotive manufacturers. Tier-2 operators exhibit highest price sensitivity due to limited Kubernetes engineering capacity, while Tier-1 carriers prioritize latency guarantees over cost.
Supply Chain Analysis
ETSI NFV certification gating extends validation timelines 14-18 months for European operators, creating supply bottlenecks for software vendors seeking market entry. Hardware fabrication concentrates in Taiwan through TSMC advanced packet processing ASIC capacity, with assembly investments shifting to Pune and Chennai under India's PLI scheme. Raw material dependencies span silicon wafers, high-performance memory modules, and specialized network interface controllers. Single-source vulnerability in TSMC fabrication exposes signaling controller supply to geopolitical disruption. Distribution runs through direct carrier procurement for Tier-1 deployments and hyperscale marketplace channels for enterprise private 5G networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Diameter Signaling Control market functions as a stable compounder anchored by irreplaceable legacy IMS interworking requirements that persist through at least the next technology transition cycle.
For Market Incumbents: Extend cloud-native portfolio coverage through Kubernetes-orchestrated container platforms to defend against hyperscale marketplace disintermediation. Deepen backward integration into container orchestration tooling to compress deployment timelines for Tier-2 operators lacking internal engineering capacity. Prioritize ETSI NFV certification investments to maintain procurement eligibility across European operator environments. For New Entrants and Emerging Players: Begin with edge signaling micro-cloud deployments for German automotive manufacturing campuses requiring sub-10 millisecond latency guarantees for industrial IoT network slicing. Target private 5G enterprise networks as the most penetrable segment, leveraging sovereign cloud marketplace distribution to bypass entrenched carrier procurement relationships. Lead with managed network function offerings that abstract Kubernetes complexity for resource-constrained buyers. For Investors and Strategic Acquirers: Roll-up economics work for specialized signaling software vendors because carrier cloud-native transformation mandates create predictable consolidation demand for interoperability testing capabilities and container orchestration expertise. Five-to-ten year viability rests on dual-stack Diameter-HTTP/2 investment cycles persisting through 5G-Advanced core deployments. Signal to watch: 3GPP Release 18 specifications reframing Diameter's role relative to service-based architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Kubernetes-orchestrated signaling functions reduce deployment timelines from months to weeks for Indian operators. |
| Strategic Partnership with Hyperscalers | AWS and Azure marketplace distribution fragments traditional OEM procurement channels for German enterprises. |
| Acquisition of Specialist Firm | Container orchestration expertise acquisitions address Tier-2 operator Kubernetes engineering capacity gaps. |
| Geographic Expansion | Pune and Chennai assembly investments capture India PLI scheme incentives for telecom equipment manufacturing. |
| Product Launch | HTTP/2 service mesh pilots by South Korean carriers displace Diameter for new 5G-Advanced authentication flows. |
Study Parameters
Direct dialogue with network engineering executives at Tier-1 mobile operators, cloud-native signaling software vendors, hyperscale cloud provider marketplace teams, and ETSI NFV certification laboratory directors grounded qualitative findings. Secondary validation drew from 3GPP specification releases, TRAI spectrum allocation frameworks, FCC network reliability directives, and GSMA Open Gateway API documentation. Bottom-up and top-down triangulation cross-checked carrier procurement cycle timing against vendor revenue recognition patterns.
Bottom-up modeling segmented the market by technology protocol, deployment architecture, end-user category, and service type across the analysis window. Top-down validation anchored aggregate demand to 5G standalone core deployment schedules reported by Reliance Jio, Bharti Airtel, SK Telecom, and Deutsche Telekom. CAGRs were derived from carrier capital expenditure disclosures and vendor order backlog trajectories. Industry-specific forecast inputs included ETSI NFV certification timeline distributions and PLI scheme incentive uptake rates.
Several conditions sit outside the modeled scope, including unannounced 3GPP specification changes, abrupt geopolitical disruption to TSMC fabrication capacity, and carrier bankruptcy or consolidation events. Forecasts reflect assumptions about persistent legacy IMS interworking requirements and gradual HTTP/2 protocol substitution rather than abrupt technology transitions. A model refresh is warranted upon material change in 3GPP Release 18 Diameter positioning or MFDS cybersecurity framework revisions affecting South Korean carrier certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
IP PBX Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Cloud RAN Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
South Korea Telecom Market
Telecommunications
Turkey Telecom Market
Telecommunications
DECT System Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
China ICT Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Global 5G Services Market
Telecommunications
Diameter Signaling Market
Telecommunications
Belgium ICT Market
Telecommunications
Malaysia Telecom Market