
 Near Field Communication (NFC) Tags Market | 2026-2036
Near Field Communication (NFC) Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Near Field Communication (NFC) Tags Market Foresight
ISO/IEC 14443 certification is rotating as the primary gating standard for NFC tag suppliers seeking access to payment and transit infrastructure contracts. NXP Semiconductors leverages its early certification archive to dominate secure-element supply for banking applications. Texas Instruments anchors its position through specialized antenna-tuning IP that reduces interference in dense retail environments.
Near Field Communication tags are passive or active transponders operating at 13.56 MHz, typically embedding copper or aluminum antenna coils with EEPROM storage from 96 bytes to 8 KB, designed for contactless data exchange across distances under 10 centimeters. Passive NFC Tags lead volume shipments due to minimal unit cost and battery-free operation in inventory management and marketing deployments. NFC Forum Type 4 Tags capture premium positioning through AES-128 encryption support, which payment processors and access control integrators specify for high-assurance transactions.
The US Federal Communications Commission governs 13.56 MHz spectrum allocation, while the EU Radio Equipment Directive mandates CE marking with harmonized EN 302 291 standards for electromagnetic compatibility. Japan's Ministry of Economy, Trade and Industry coordinates NFC-F FeliCa interoperability requirements through JIS X 6319-4, creating fragmented certification paths for vendors targeting transit applications across multiple jurisdictions. Stakeholders must monitor evolving national spectrum reallocation proposals and payment-network tokenization mandates that could render existing tag architectures non-compliant without firmware updates.
Market Dynamics
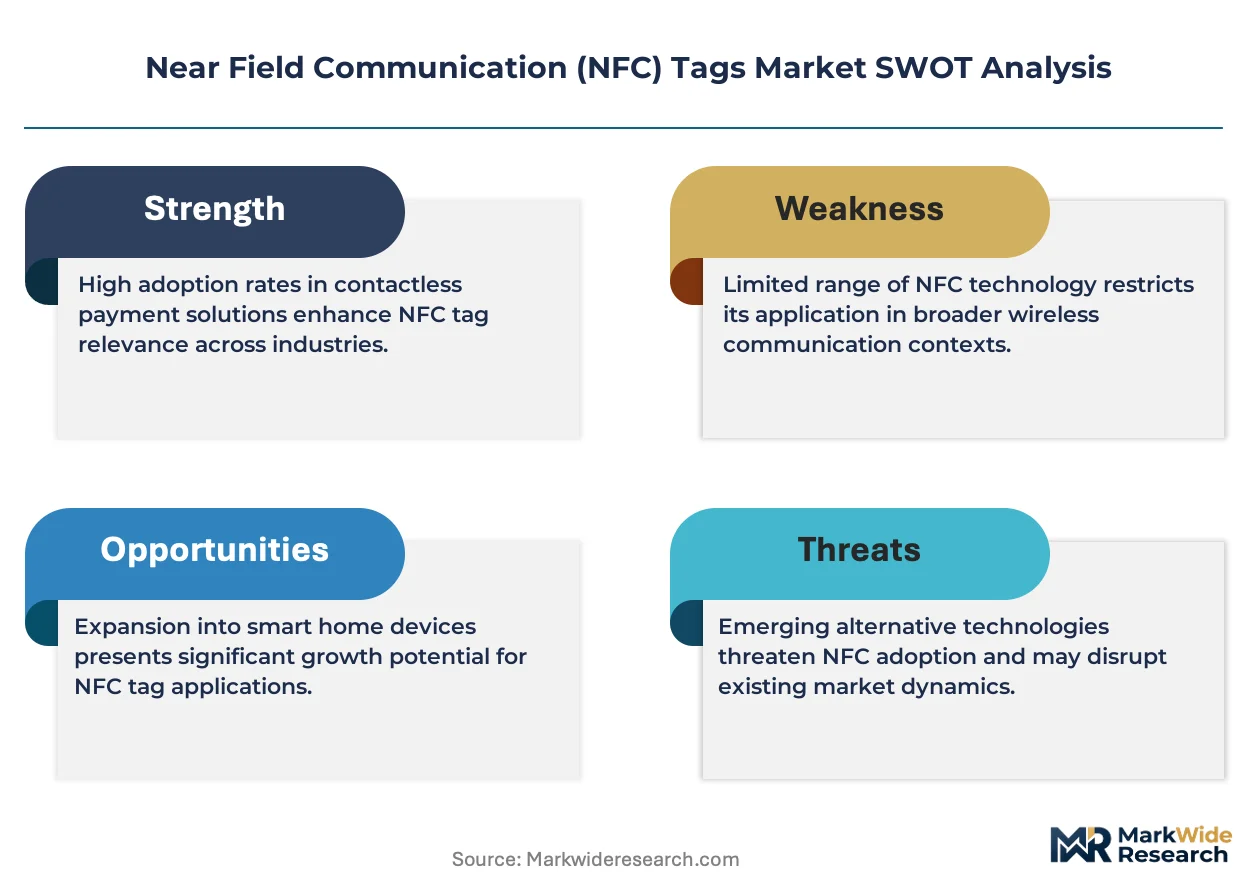
The NFC tag market is experiencing a structural compression as ISO/IEC 14443 certification requirements harden into non-negotiable procurement criteria for payment and transit infrastructure contracts, forcing suppliers to front-load compliance investment before volume economics materialize.
Growth Catalysts
- EU Radio Equipment Directive harmonization:CE marking under EN 302 291 standards is accelerating cross-border tag deployment by reducing duplicate testing costs for vendors targeting multiple European transit authorities.
- Contactless retail infrastructure:Dense antenna-tuning deployments in grocery and quick-service restaurant chains are pulling passive tag volumes as merchants retrofit point-of-sale terminals for sub-10-centimeter transaction ranges.
- Smartphone integration in China:Domestic handset manufacturers embedding NFC across mid-tier device portfolios are expanding the installed base of compatible readers beyond premium flagship segments.
Market Restraints
- Copper coil input volatility:Antenna fabrication depends on thin-gauge copper and aluminum supply chains concentrated in East Asian smelting operations, exposing tag assemblers to LME price swings without pass-through mechanisms.
- Secure-element supply concentration:Banking-grade NFC deployments rely on a narrow supplier base for AES-128 encryption cores, creating single-source vulnerability for payment processor certification timelines.
- Fragmented spectrum allocation:Japan's JIS X 6319-4 FeliCa requirements diverge from ISO/IEC 14443-A/B standards, forcing vendors to maintain dual-certification inventories for transit applications.
Strategic Opportunities
- Healthcare asset tracking:FDA Unique Device Identification mandates for medical equipment are opening high-assurance tag demand where sterilization-resistant packaging meets NFC Forum Type 4 encryption specifications.
- Automotive digital key integration:CCC Digital Key specification convergence with NFC Forum standards is creating vehicle access control applications that bypass traditional fob infrastructure.
- India BIS certification pathway:The Bureau of Indian Standards is formalizing domestic NFC testing protocols, positioning early certifiers for government payment and transit tenders as digital rupee infrastructure expands.
Industry Challenges
- Antenna design talent scarcity:Specialized electromagnetic simulation expertise for 13.56 MHz coil optimization remains concentrated within semiconductor firms, limiting independent tag designers' ability to meet dense-field interference specifications.
- Firmware update architecture gaps:Legacy tag deployments lack over-the-air reprogramming capabilities, forcing physical replacement cycles when payment-network tokenization mandates evolve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near Field Communication (NFC) Tags Market |
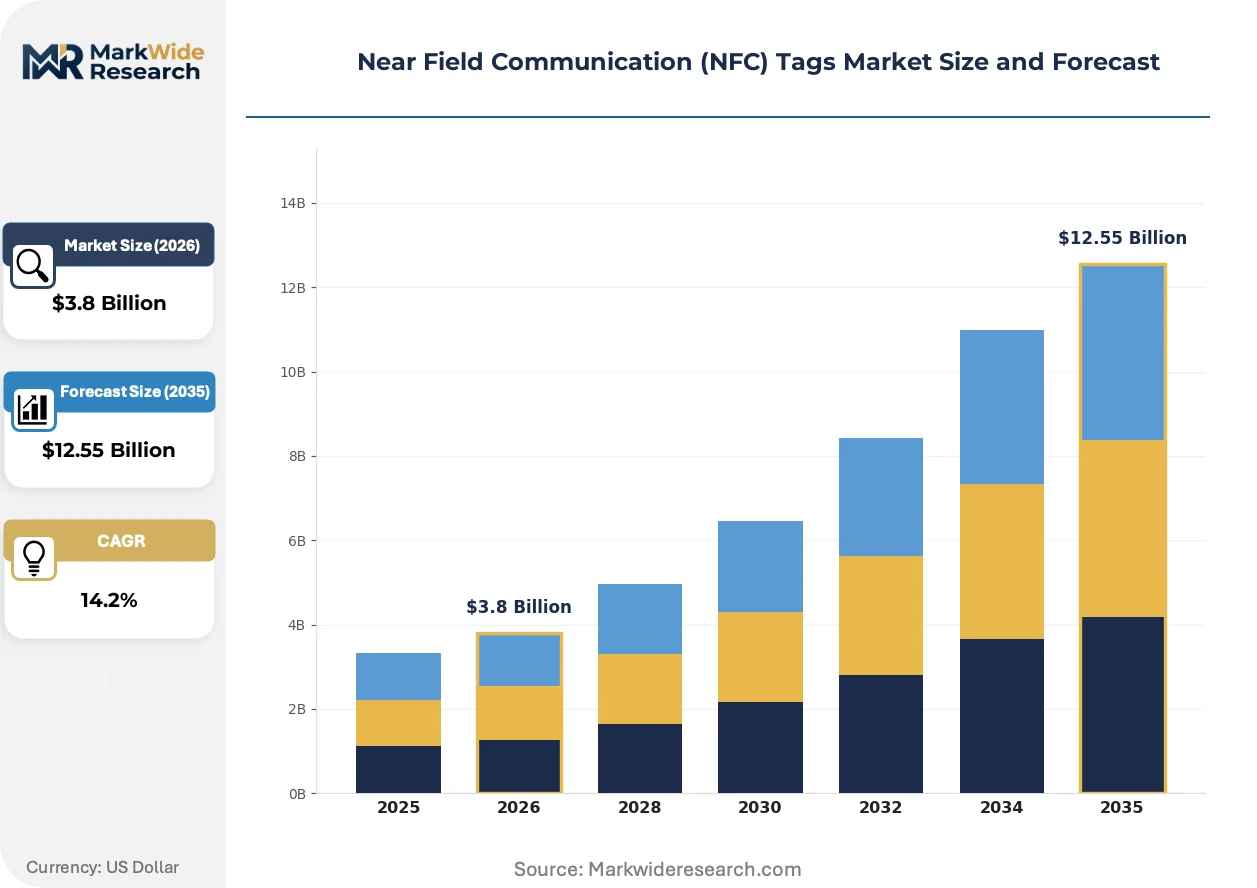
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active NFC Tags, Passive NFC Tags, NFC Reader, NFC Controller Technology: NFC Forum Type 1 Tag, NFC Forum Type 2 Tag, NFC Forum Type 3 Tag, NFC Forum Type 4 Tag Application: Access Control, Payment Transactions, Marketing, Inventory Management End User: Retail, Healthcare, Transportation, Consumer Electronics |
| Companies Covered | Infineon Technologies, Texas Instruments, NXP Semiconductors, Samsung Electronics, Qualcomm Technologies, Broadcom, Sony Corporation, Identiv, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near Field Communication (NFC) Tags Market Shifts & Advancements
Antenna-tuning intellectual property and encryption firmware architectures are separating into distinct competitive battlegrounds, with specialists pursuing divergent capability investments rather than converging on unified platform strategies.
Dual-interface NFC controllers are bifurcating the secure-element market by enabling single-chip solutions that bridge contact and contactless payment terminals. Transit authorities in South Korea and the Netherlands are specifying these controllers for multimodal fare collection systems. This technology is compressing the addressable market for discrete secure-element suppliers by embedding cryptographic functions into broader microcontroller portfolios.
Japan's METI is coordinating NFC-F FeliCa interoperability requirements through revised JIS standards that mandate backward compatibility with legacy transit card formats. Railway operators in Tokyo and Osaka are demanding firmware-upgradeable readers to accommodate both existing FeliCa and emerging NFC Forum Type 4 tag populations. Vendors targeting Japanese transit infrastructure must maintain dual-protocol certification stacks, extending product development cycles by 8-14 months.
Merchant procurement of NFC-enabled point-of-sale terminals is rotating toward integrated hardware-software bundles where payment processors subsidize reader deployment in exchange for transaction fee commitments. Quick-service restaurant chains in the United States and Germany are consolidating vendor relationships around three terminal manufacturers. This concentration is squeezing independent tag suppliers into commodity pricing tiers unless they embed proprietary antenna-tuning IP that demonstrates measurable interference reduction in dense retail environments.
Near Field Communication (NFC) Tags Market Segmentation
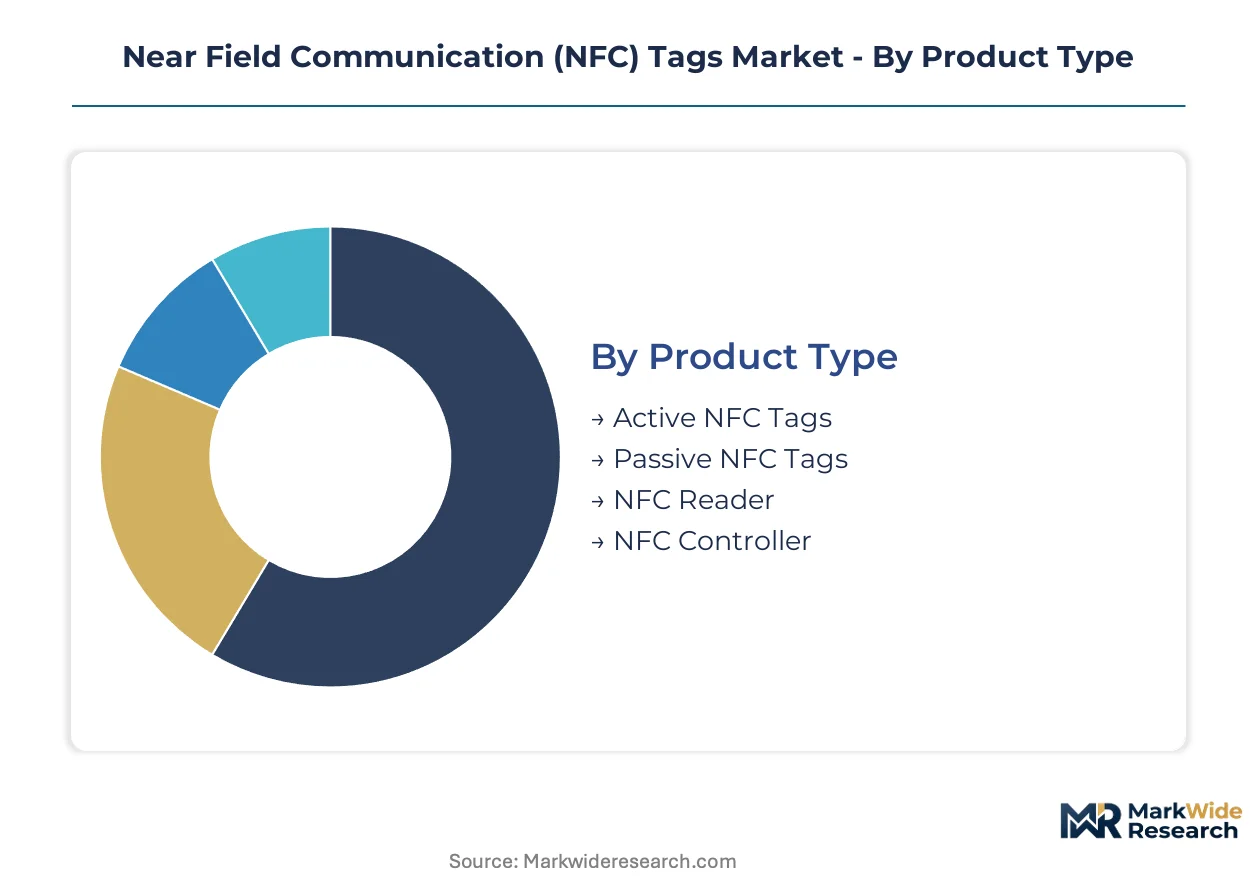
NFC tag architectures fragment across power requirements, encryption tiers, and use-case assurance levels. Regulatory mandates from the FCC, EU Radio Equipment Directive, and Japan's METI create divergent certification paths that reshape segment prioritization for vendors.
Product Type:
FCC spectrum allocation for 13.56 MHz operation distinguishes battery-dependent from battery-free architectures, with compliance costs concentrating procurement decisions.
- Active NFC Tags:Self-powered transponders embed lithium coin cells enabling read ranges up to 100 meters for industrial asset tracking. Cold-chain logistics operators in Germany specify these for pharmaceutical shipment monitoring where temperature logging demands continuous transmission.
- Passive NFC Tags:Harvest energy from reader magnetic fields through copper or aluminum antenna coils, operating without onboard power. Grocery retailers across the United States deploy these for sub-10-centimeter payment authentication where unit economics favor disposable form factors.
- NFC Reader:Transmit 13.56 MHz carrier signals and demodulate tag responses for host system integration. Transit authorities in South Korea specify multimodal readers for fare collection bridging contact and contactless protocols.
- NFC Controller:Manage protocol stacks and security handshakes between reader hardware and application processors. Smartphone manufacturers in China integrate these across mid-tier device portfolios to expand compatibility beyond flagship segments.
Passive NFC Tags handle the majority of throughput; Active NFC Tags are expanding most quickly on share as industrial IoT deployments accelerate.
Technology:
Encryption capability tiers separate commodity inventory applications from banking-grade payment infrastructure, with AES-128 support commanding certification premiums.
- NFC Forum Type 1 Tag:Based on ISO/IEC 14443 Type A with 96 bytes to 2 KB memory, offering basic read-write functionality. Museum operators in France deploy these for exhibit information retrieval where cost minimization outweighs security requirements.
- NFC Forum Type 2 Tag:ISO/IEC 14443 Type A foundation with 48 bytes to 2 KB EEPROM and anti-collision support. Marketing agencies embed these in product packaging for consumer engagement campaigns requiring simple URL redirection.
- NFC Forum Type 3 Tag:FeliCa-compliant architecture with 2 KB to 1 MB memory and native transaction speed optimization. Japan's railway operators maintain these for legacy transit card compatibility under METI-coordinated JIS X 6319-4 standards.
- NFC Forum Type 4 Tag:ISO/IEC 14443 Type A or Type B with AES-128 encryption and up to 32 KB storage. Payment processors mandate these for contactless card emulation where tokenized transaction security is non-negotiable.
NFC Forum Type 2 Tag dominates volume shipments; NFC Forum Type 4 Tag captures the steepest expansion trajectory as payment infrastructure hardens encryption requirements.
Application:
Use-case assurance levels range from convenience-oriented marketing to financial-system criticality, with FDA and PCI-DSS compliance creating divergent specification paths.
- Access Control:Employee badge and facility entry systems leveraging UID authentication and encrypted credential storage. Corporate campuses in the United States specify NFC Forum Type 4 Tags for high-assurance perimeter security.
- Payment Transactions:Contactless card emulation and mobile wallet authentication requiring EMVCo certification and tokenization support. Quick-service restaurant chains in Germany retrofit point-of-sale terminals for sub-10-centimeter transaction ranges.
- Marketing:Product packaging and print media embedding URL pointers for consumer engagement analytics. Retail brands deploy Type 1 and Type 2 tags for disposable campaign materials where per-unit cost must fall below five cents.
- Inventory Management:Warehouse and supply chain tracking with batch-level serialization and environmental sensing integration. Pharmaceutical distributors combine passive tags with temperature loggers for FDA-compliant cold-chain documentation.
Payment Transactions concentrates revenue per unit; Inventory Management is gaining share fastest as serialization mandates expand beyond pharmaceuticals.
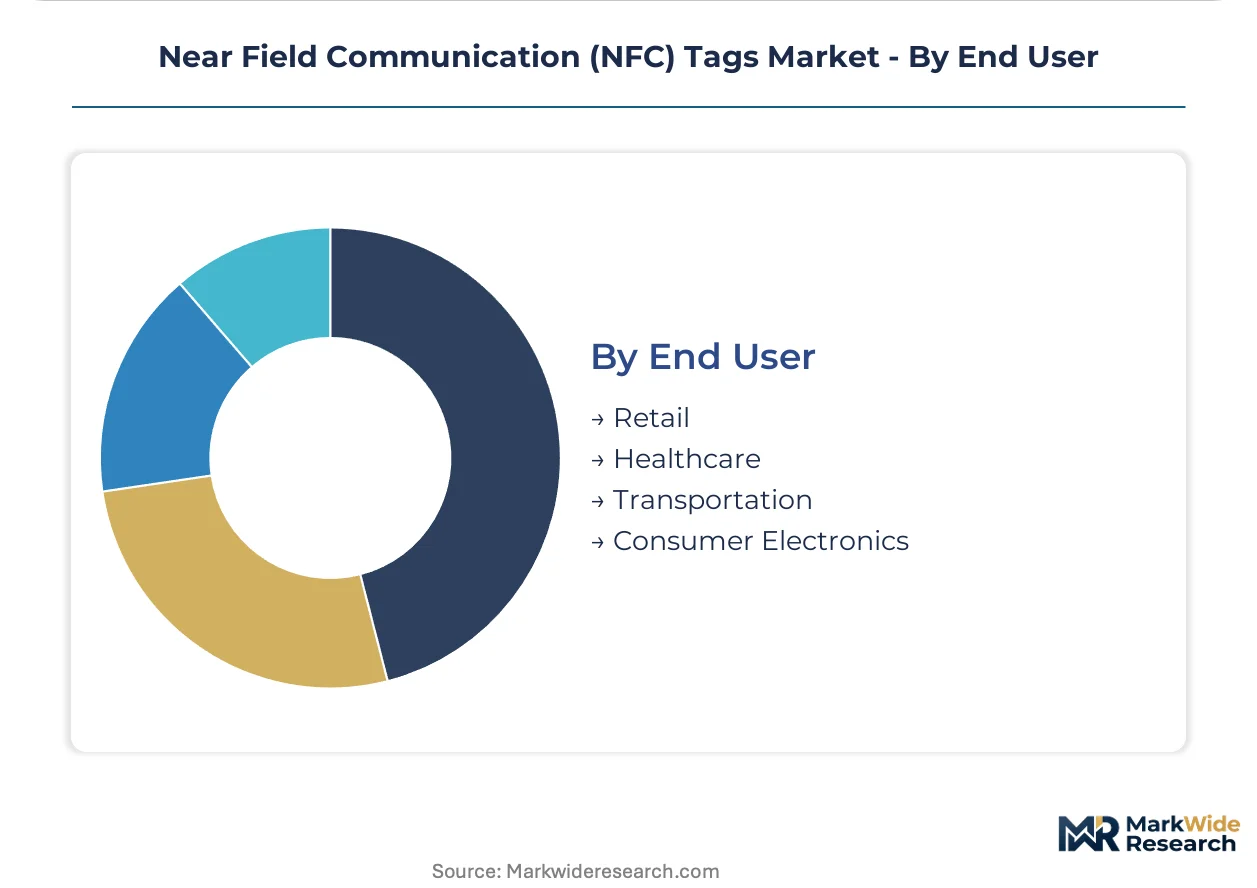
End User:
Sector-specific regulatory frameworks reshape tag specification, with healthcare sterilization requirements and automotive CCC Digital Key standards creating specialized demand pockets.
- Retail:Point-of-sale terminals, loyalty programs, and inventory visibility across grocery and apparel chains. Dense antenna-tuning deployments in quick-service restaurants pull passive tag volumes as merchants consolidate around subsidized reader bundles.
- Healthcare:Medical equipment tracking, patient identification, and pharmaceutical authentication under FDA Unique Device Identification mandates. Sterilization-resistant packaging for surgical instruments specifies NFC Forum Type 4 encryption for asset lifecycle documentation.
- Transportation:Transit fare collection, vehicle access control, and logistics fleet management. Railway operators in Tokyo demand firmware-upgradeable readers accommodating both legacy FeliCa and emerging NFC Forum standards.
- Consumer Electronics:Smartphone integration, wearable device pairing, and smart home authentication. Domestic handset manufacturers in China embed NFC across mid-tier portfolios, expanding the installed base of compatible readers.
Retail generates the largest addressable volume; Healthcare is climbing the fastest as FDA mandates harden asset-tracking requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment processors and transit authorities dominate procurement decisions, with certification requirements from multiple national regulators shaping vendor prioritization. The installed base of NFC-enabled smartphones is expanding fastest in Asia-Pacific manufacturing clusters, while European transit harmonization is compressing cross-border deployment timelines.
United States
Quick-service restaurant chains and grocery retailers are retrofitting point-of-sale terminals for contactless authentication. The FCC governs 13.56 MHz spectrum allocation with specific emission limits for dense retail environments. Silicon Valley semiconductor clusters supply antenna-tuning intellectual property to payment terminal manufacturers seeking interference reduction.
China
Domestic smartphone manufacturers embed NFC controllers across mid-tier device portfolios, expanding compatible reader penetration beyond flagship segments. MIIT coordinates GB standards for electromagnetic compatibility with payment network tokenization mandates. Shenzhen manufacturing corridors concentrate tag assembly operations serving both domestic deployment and export markets.
Germany
Cold-chain logistics operators specify active NFC tags for pharmaceutical shipment monitoring with temperature logging requirements. The EU Radio Equipment Directive mandates CE marking under EN 302 291 standards for cross-border transit authority procurement. Munich industrial corridors host antenna design specialists serving automotive digital key integration programs.
Japan
Railway operators in Tokyo and Osaka demand firmware-upgradeable readers accommodating both legacy FeliCa and emerging NFC Forum standards. METI coordinates JIS X 6319-4 interoperability requirements through revised standards mandating backward compatibility. Nagoya manufacturing clusters produce dual-protocol certification stacks extending product development cycles for transit infrastructure vendors.
South Korea
Transit authorities specify multimodal NFC controllers bridging contact and contactless protocols for fare collection systems. The national regulator enforces electromagnetic compatibility standards aligned with ISO/IEC 14443 certification requirements. Seoul metropolitan infrastructure projects are deploying firmware-upgradeable readers to accommodate evolving payment network specifications.
Near Field Communication (NFC) Tags Market Competitive Landscape
Player mix skews toward diversified semiconductor conglomerates with secure-element archives, supplemented by specialized antenna-tuning boutiques and integrated device manufacturers. The competitive terrain stratifies across three tiers: banking-grade certification holders, industrial IoT volume suppliers, and retail-focused commodity assemblers. Dominant competitive moves include strategic partnerships with payment processors for terminal subsidization and technology licensing for antenna optimization intellectual property.
Among diversified semiconductor suppliers, NXP Semiconductors, Infineon Technologies, and Texas Instruments occupy positions representing distinct competitive archetypes. NXP exemplifies the secure-element certification anchor with early ISO/IEC 14443 archive leverage. Infineon represents the industrial-grade encryption specialist serving automotive and healthcare applications. Texas Instruments anchors the antenna-tuning differentiation vector with electromagnetic simulation expertise for dense-field retail deployments.
| Leading Market Players |
|---|
| Infineon Technologies |
| Texas Instruments |
| NXP Semiconductors |
| Samsung Electronics |
| Qualcomm Technologies |
| Broadcom |
| Sony Corporation |
| Identiv |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Aluminum antenna coil substitution for copper windings is redrawing procurement geography toward Chinese smelting corridors while compressing unit economics for passive tag assemblers locked into long-term supply agreements. This materials pivot simultaneously exposes vendors to London Metal Exchange volatility and creates arbitrage opportunities for buyers with flexible metallurgy specifications.
Pricing Analysis
Cost-plus contracts indexed to LME copper and aluminum spot prices dominate antenna fabrication procurement, with pass-through clauses protecting East Asian coil suppliers from margin erosion. Three-tier pricing structure across NFC Forum Type 4 encryption-certified, Type 2 commodity, and unbranded white-label tiers separates banking-grade secure-element premiums from disposable marketing tag economics. Price compression intensifies in retail-facing passive segments as quick-service restaurant chains consolidate terminal vendor relationships around subsidized reader bundles. Inventory management buyers exhibit highest price sensitivity, while healthcare asset-tracking procurement prioritizes sterilization-resistant packaging and FDA compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of thin-gauge copper and aluminum feedstock prevails among antenna coil specialists, contrasting with just-in-timed assembly operations in Shenzhen manufacturing corridors. Taiwan, South Korea, and China concentrate secure-element wafer fabrication, while Germany and Japan host electromagnetic simulation talent for dense-field antenna tuning. Raw material dependencies center on LME-traded non-ferrous metals, polyimide substrate films, and EEPROM die supply from captive foundry operations. Single-source vulnerability for AES-128 encryption cores creates certification timeline risk for payment processor deployments. Distribution runs through semiconductor distributors serving terminal OEMs and direct contracts with transit authority procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromagnetic simulation expertise for 13.56 MHz coil optimization remains locked within a handful of semiconductor firms, constraining independent tag designers' ability to meet dense-field interference specifications and creating acquisition premiums for antenna-tuning boutiques.
For Market Incumbents: Fortify secure-element certification archives through accelerated ISO/IEC 14443 Type B pathway investments before India's BIS domestic testing protocols harden procurement requirements for government payment tenders. Deepen backward integration into copper coil winding operations to offset LME price volatility exposure. Prioritize firmware-upgradeable reader architectures that accommodate evolving payment-network tokenization mandates without physical replacement cycles. For New Entrants and Emerging Players: Differentiate on healthcare asset-tracking specialization where FDA Unique Device Identification mandates create sterilization-resistant packaging demand that incumbent commodity suppliers underserve. Target pharmaceutical distributors combining passive NFC tags with temperature loggers for cold-chain documentation. Pursue direct hospital system partnerships bypassing distributor markups in medical equipment procurement channels. For Investors and Strategic Acquirers: The market sits at a certification-concentration phase that favors secure-element archive holders with early ISO/IEC 14443 leverage and antenna-tuning IP portfolios. Long-term viability hinges on dual-protocol capability spanning FeliCa and NFC Forum standards as Japanese transit infrastructure upgrades. Acquisition candidates with electromagnetic simulation talent and existing METI coordination relationships command structural scarcity premiums. Watch India's digital rupee infrastructure procurement timelines as inflection signal for emerging geography exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Antenna-Tuning IP Licensing | Texas Instruments and specialized boutiques monetize dense-field interference reduction patents for retail terminal deployments. |
| Dual-Protocol Certification Investment | Vendors targeting Tokyo and Osaka railway operators must stack JIS X 6319-4 FeliCa with NFC Forum Type 4 standards. |
| Healthcare Sterilization Packaging Development | FDA UDI mandates for surgical instruments pull NFC Forum Type 4 encryption into medical asset lifecycle documentation. |
| India BIS Early Certification | First-movers in domestic NFC testing protocols position for government payment and transit tenders as digital rupee expands. |
| Automotive CCC Digital Key Integration | Munich industrial corridors develop vehicle access control bypassing traditional fob infrastructure through NFC Forum convergence. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with NFC tag procurement managers at transit authorities, payment processor certification leads, semiconductor antenna design directors, and healthcare biomedical engineering heads; alongside secondary validation through FCC 13.56 MHz spectrum allocation filings, EU Radio Equipment Directive CE marking databases, METI JIS standard revision notices, and SEC 10-K disclosures from diversified semiconductor suppliers. Bottom-up tag shipment estimates triangulated against top-down payment terminal deployment data from quick-service restaurant chain investor presentations.
Across the projection horizon, the analytical framework modeled volume and value trajectories segmented by power architecture (active versus passive), encryption tier (NFC Forum Type 1 through Type 4), application assurance level (marketing convenience to PCI-DSS criticality), and end-user regulatory cluster (retail POS retrofit, FDA medical device tracking, automotive CCC digital key). CAGRs derived from historical smartphone NFC controller integration curves and transit authority reader replacement cycles. Forecast inputs incorporated MIIT GB standards coordination for Chinese mid-tier handset embedding and India's BIS protocol formalization timeline.
Material uncertainties — copper and aluminum LME price volatility, payment-network tokenization mandate evolution, and national spectrum reallocation proposals — sit outside the modeled envelope. Forecasts reflect assumptions regarding ISO/IEC 14443 certification pathway stability and FeliCa backward compatibility maintenance. Revision becomes warranted when secure-element supply concentration crosses single-source vulnerability thresholds or when transit authority procurement specifications diverge from harmonized EN 302 291 standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
In-Counter Barcode Scanners Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Alcohol Sensor Market
Sensors
India Asset Tracking Market
Sensors
Traffic Sensor Market
Sensors
Global RFID Market
Sensors
Vision Positioning System Market
Sensors
Remote Sensing Technology Market
Sensors
Smart Mat Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Body Area Network Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Eye Tracking Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Asset Tags Market
Sensors
IO Link Market