
 Indonesia Prepaid Cards Market | 2026-2036
Indonesia Prepaid Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Prepaid Cards Market Intelligence
Bank Indonesia's electronic money licensing framework is consolidating the cost-of-entry calculus for prepaid card issuers. Mandiri Bank leverages its state-backed branch network to sustain distribution dominance across second-tier cities. Bank Central Asia anchors its position through aggressive mobile app integration that links prepaid balances to e-commerce checkouts. Fintech Payment Service Providers compete on onboarding speed, differentiating through instant virtual card issuance for gig economy workers.
Indonesia prepaid cards are stored-value instruments issued by licensed financial institutions, functioning through embedded chip or magnetic stripe technology with optional NFC contactless capability, designed to facilitate payments without requiring traditional bank account linkage. Their primary commercial purpose centers on financial inclusion for unbanked populations and controlled spending for corporate disbursements. Reloadable cards lead transaction volume among product types due to recurring salary and remittance loading cycles, while virtual cards represent the fastest-expanding segment as QRIS-compatible mobile issuance displaces physical plastic. Retail Consumers dominate the customer type base, though corporate users command superior margin pools through bulk procurement and white-label program structures.
Bank Indonesia regulates electronic money issuance through capital adequacy and safeguarding requirements, while the Financial Services Authority (OJK) supervises consumer protection standards for prepaid products. BIS technical standards for chip card security and the national payment gateway interoperability rules shape product certification timelines and cross-platform usability. Stakeholders must monitor BI's evolving e-money licensing tiers and OJK's digital wallet consolidation mandates to anticipate which distribution channels retain operational viability.
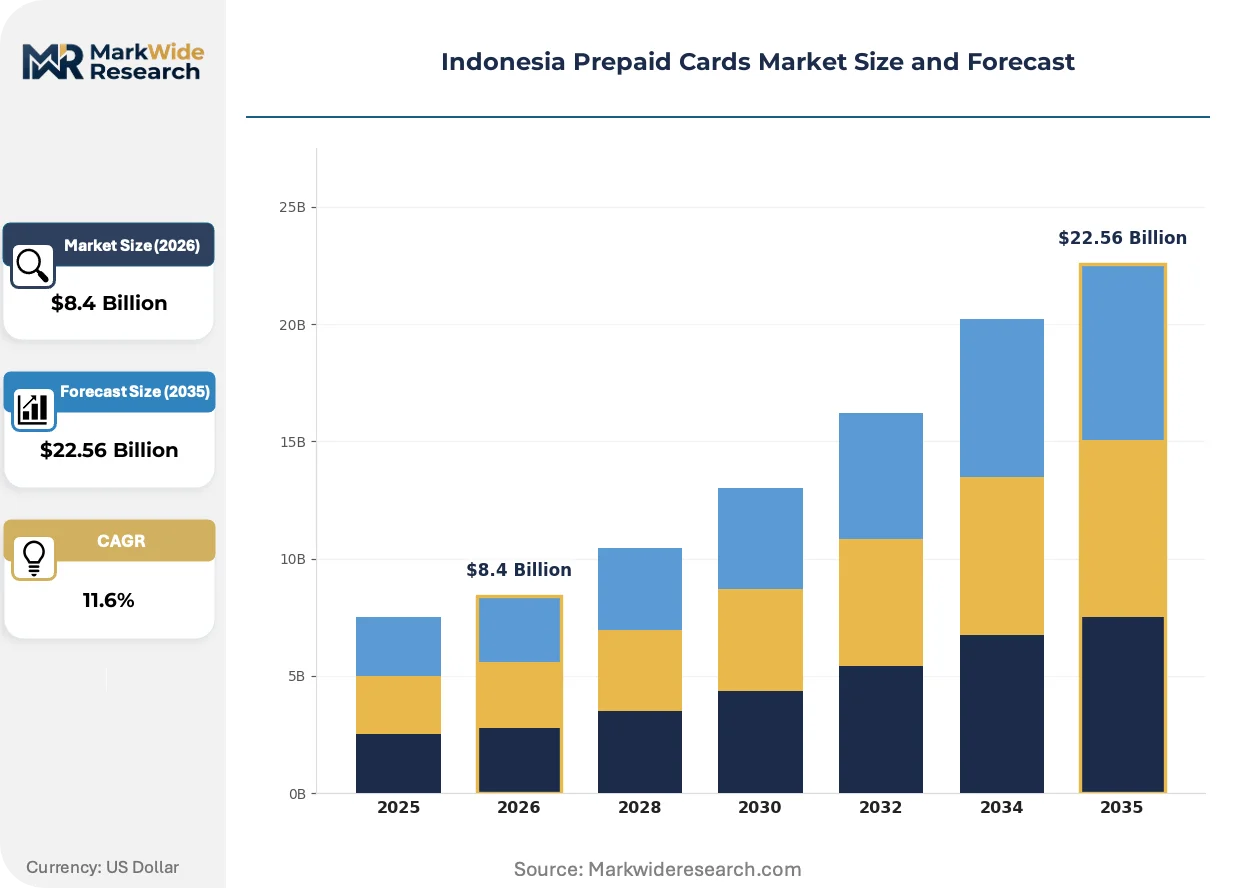
Market Dynamics
Bank Indonesia's QRIS interoperability mandate is compressing the technical stack for prepaid card issuance, forcing licensed e-money providers to consolidate onto a single national payment gateway infrastructure while expanding virtual card distribution through mobile-first channels.
Growth Catalysts
- Financial inclusion policy:Bank Indonesia's tiered e-money licensing framework lowers capital barriers for fintech entrants serving unbanked retail consumers in second-tier cities. This regulatory architecture accelerates virtual prepaid card onboarding for gig economy workers without traditional bank relationships.
- QRIS infrastructure convergence:The national payment gateway interoperability standard is unifying previously fragmented mobile wallet acceptance networks. Prepaid card issuers leveraging this shared rails system gain instant merchant coverage across Java and outer island regions.
- E-commerce checkout integration:Major marketplace platforms are embedding prepaid balance payments directly into their mobile apps. This channel convergence drives reload frequency among retail consumers who previously relied on cash-on-delivery.
Market Restraints
- Capital adequacy requirements:Bank Indonesia mandates minimum core capital thresholds for electronic money operators that exclude smaller fintech ventures from obtaining independent licenses. This regulatory floor consolidates issuance capacity among state-backed banking groups.
- Physical distribution concentration:Plastic prepaid card reloading depends on licensed bank branch networks and partner agent locations concentrated in Jakarta, Surabaya, and Bandung. Outer island consumers face geographic access gaps that limit adoption velocity.
- Interoperability cost burden:The national payment gateway certification process imposes fixed technical compliance costs that disproportionately burden low-volume issuers. This cost structure favors incumbents with existing IT infrastructure.
Strategic Opportunities
- Eastern Indonesia penetration:Sulawesi, Maluku, and Papua present underbanked populations where mobile network coverage now exceeds physical banking infrastructure. Virtual prepaid cards distributed through telco-integrated apps can capture remittance and micro-payment flows before branch networks expand.
- Corporate disbursement digitization:Plantation, construction, and maritime employers are replacing cash payroll with reloadable prepaid instruments. White-label program structures for these sectors command superior margin pools through bulk issuance contracts.
- Cross-border remittance linkage:ASEAN payment connectivity initiatives are creating interoperability corridors between Indonesia, Malaysia, Singapore, and Thailand. Prepaid card issuers positioning on these rails can capture outbound worker remittance loading.
Industry Challenges
- EMV chip certification timelines:Bank Indonesia's migration to contactless EMV standards requires hardware recertification for existing card portfolios. Issuers face 12-18 month compliance windows that compress product refresh cycles and strain technical teams.
- Legacy core banking integration:Established banks must reconcile real-time prepaid balance management with batch-oriented legacy account systems. This architecture friction delays virtual card issuance speed that fintech competitors achieve through cloud-native stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Prepaid Cards Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.56 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gift Cards, Travel Cards, Reloadable Cards, Virtual Cards Customer Type: Retail Consumers, Corporate Users, Students, Tourists Distribution Channel: Online Platforms, Retail Stores, Banks, Mobile Apps Technology: Contactless, NFC-enabled, Magnetic Stripe, Chip Cards |
| Companies Covered | Bank Rakyat Indonesia, Bank BNI, Mandiri Bank, International Payment Providers, Fintech Payment Service Providers, Bank Central Asia, Bank DKI, Digital Wallet Operators, Bank Negara Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Prepaid Cards Market Strategic Shifts & Innovations
Prepaid card architecture is pivoting from physical plastic toward virtual mobile issuance, with NFC contactless capability and QRIS compatibility becoming baseline technical requirements rather than premium features.
Virtual card technology is expanding into gig economy disbursement workflows through instant mobile issuance APIs that bypass plastic production and logistics entirely. Platform employers in ride-hailing, delivery, and freelance marketplaces are adopting these instruments for same-day earnings access. This shift compresses the traditional 3-5 day payroll cycle and displaces cash handling costs for both employers and workers.
Bank Indonesia's electronic money safeguarding rules now require segregated trust account structures for customer funds held by licensed issuers. This regulatory tightening elevates operational compliance costs but strengthens consumer protection standards that differentiate licensed operators from unregulated wallet providers. Smaller fintech issuers are responding through partnership models that leverage bank licenses rather than obtaining independent authorization.
Retail consumer purchasing patterns are fragmenting across multiple prepaid instruments rather than consolidating on single primary cards. Users maintain separate balances for transport, e-commerce, and remittance purposes, creating account proliferation that complicates personal financial management. This behavior is most visible among Jakarta and Surabaya mobile-first demographics who prioritize transaction-specific rewards and promotional loading bonuses over unified account convenience.
Indonesia Prepaid Cards Market Segmentation
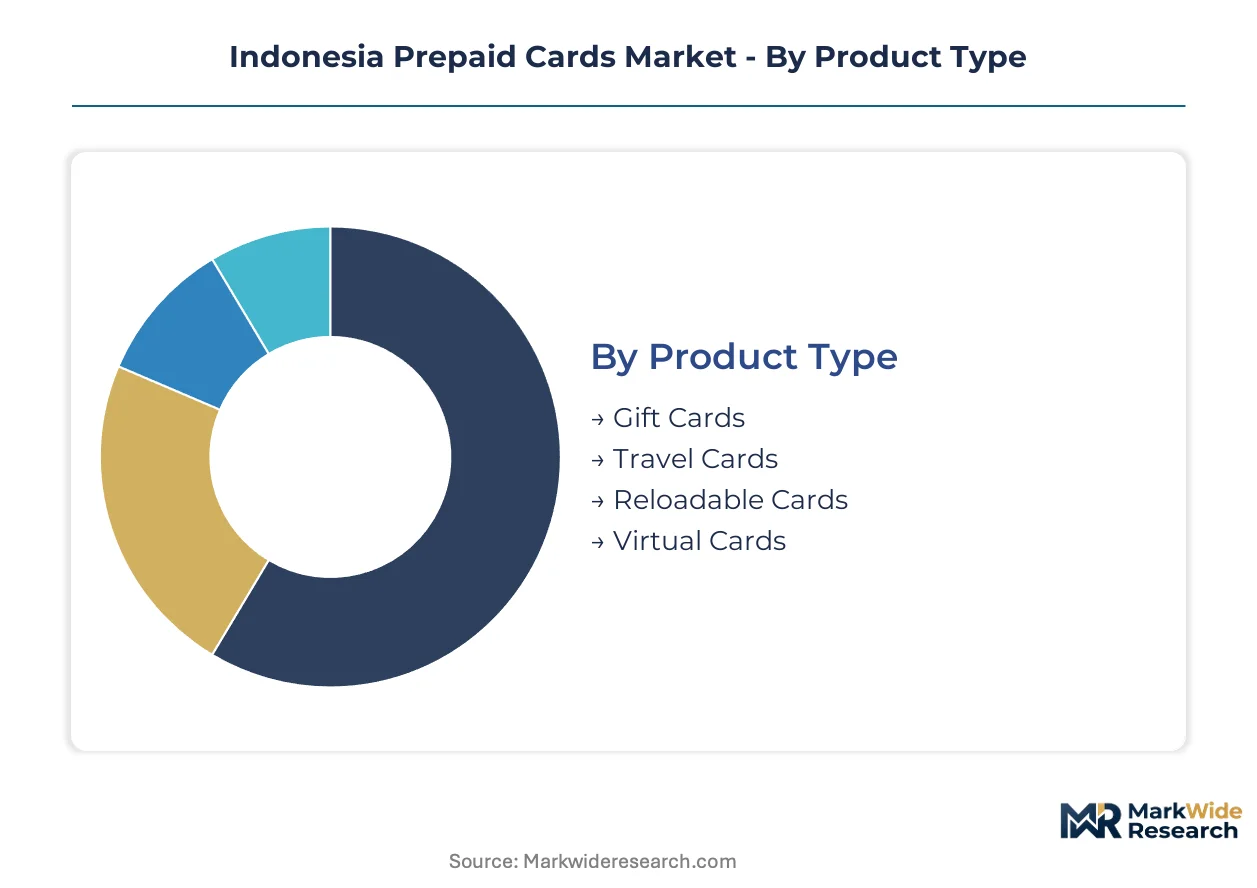
Segmentation reveals how prepaid card architecture diverges across use cases and technical specifications in Indonesia. Each dimension exposes distinct margin structures, regulatory touchpoints, and channel economics that shape issuer strategy.
Product Type:
Upgrade cycles in Indonesia prepaid cards are compressing as virtual issuance displaces physical plastic and reloadable instruments absorb recurring salary flows.
- Reloadable Cards:These stored-value instruments support repeated funding through bank transfers, agent networks, or payroll integration. Demand clusters among corporate employers in plantation and construction sectors across Java who use them for controlled wage disbursement. Bank Indonesia's safeguarding rules for segregated trust accounts elevate compliance costs but strengthen institutional adoption.
- Virtual Cards:Mobile-native instruments issued instantly through APIs without physical production. Gig economy platforms in Jakarta and Surabaya deploy these for same-day earnings access, compressing traditional payroll cycles. QRIS compatibility has become a baseline technical requirement rather than premium feature.
- Gift Cards:Single-load instruments with fixed denominations, commonly distributed through retail partnerships for promotional campaigns.
- Travel Cards:Multi-currency stored-value products targeting outbound tourists and business travelers with pre-locked exchange rates.
Volume placements concentrate in Reloadable Cards; the faster expansion belongs to Virtual Cards.
Customer Type:
Cost tier differentiation separates mass-market retail adoption from premium-margin corporate procurement structures.
- Retail Consumers:Unbanked and underbanked individuals using prepaid instruments for daily transactions, e-commerce checkout, and remittance receipt. This base dominates transaction counts across Java's mobile-first urban corridors.
- Corporate Users:Employers and disbursement platforms purchasing bulk issuance for payroll, incentives, and expense management. White-label program structures command superior margin pools through negotiated volume contracts.
- Students:Campus-linked prepaid products with parental controls and restricted merchant categories, concentrated in university towns.
- Tourists:Short-term visitors requiring rupiah-denominated payment instruments without local bank account requirements.
Transaction volume concentrates among Retail Consumers; margin capture concentrates with Corporate Users.
Distribution Channel:
Channel economics favor mobile-first issuance as QRIS infrastructure convergence reduces merchant acceptance fragmentation.
- Mobile Apps:Telco-integrated and standalone wallet applications enabling instant virtual card provisioning. These platforms capture gig worker onboarding through API-linked employer integrations.
- Banks:Licensed e-money operators leveraging branch networks for physical card distribution and trust account safeguarding compliance.
- Online Platforms:E-commerce marketplaces embedding prepaid balance payments directly into checkout flows, driving reload frequency.
- Retail Stores:Licensed agent locations and convenience chains handling cash-to-card loading, with geographic concentration in Jakarta, Surabaya, and Bandung.
Physical presence concentrates in Banks and Retail Stores; the steepest expansion trajectory belongs to Mobile Apps.
Technology:
Technical certification timelines are compressing as Bank Indonesia mandates EMV contactless migration across all issued portfolios.
- Chip Cards:EMV-compliant embedded microprocessor cards with dynamic authentication. These dominate corporate and high-value retail issuance due to security requirements.
- Contactless:Tap-to-pay enabled instruments using NFC or QR code presentation. Merchant acceptance networks across Java now treat contactless capability as baseline rather than premium.
- NFC-enabled:Near-field communication variants supporting specific mobile wallet integrations and transit system interoperability.
- Magnetic Stripe:Legacy stripe technology facing phased obsolescence as Bank Indonesia's technical standards prioritize chip migration.
Active issuance concentrates in Chip Cards and Contactless; Magnetic Stripe is losing operational viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Batam Free Trade Zone and Special Economic Zone concentrates prepaid card processing infrastructure through tax incentives for fintech back-office operations. This zone anchors technical development for virtual issuance platforms serving the broader archipelago.
Java
Jakarta's mobile-first banking penetration drives virtual prepaid card adoption among gig economy workers in ride-hailing and delivery platforms. Bank Indonesia's QRIS interoperability mandate requires all licensed e-money operators to connect through the national payment gateway. Surabaya and Bandung host the densest concentrations of reload agent networks, though outer island access gaps persist.
Sumatra
Medan and Palembang serve as distribution hubs for corporate payroll prepaid programs in plantation and palm oil sectors. The Financial Services Authority supervises consumer protection standards for these bulk disbursement instruments. Aceh's sharia-compliant financial institutions are developing segregated trust account structures for Islamic prepaid products.
Sulawesi
Makassar anchors prepaid card growth as mobile network coverage now exceeds physical banking infrastructure across the island. Telco-integrated wallet applications capture remittance flows from Eastern Indonesian workers. Bank Indonesia's tiered licensing framework enables regional fintech entrants to serve underbanked populations without independent capital reserves.
Kalimantan
Balikpapan and Samarinda concentrate mining sector corporate disbursement demand for reloadable payroll instruments. The national payment gateway certification process imposes fixed compliance costs that favor incumbent bank issuers with existing IT infrastructure. Pontianak presents emerging demand from cross-border trade with Malaysian Borneo.
Bali and Nusa Tenggara
Tourism-dependent economies in Denpasar drive demand for multi-currency travel prepaid products with pre-locked exchange rates. Digital wallet operators compete through instant virtual issuance for informal sector workers in hospitality. Lombok's post-earthquake reconstruction has accelerated mobile payment adoption as physical banking infrastructure recovers slowly.
Indonesia Prepaid Cards Market Key Industry Players
Jakarta-based banking groups anchor one tier; Singapore-linked international payment providers hold specialized positions in cross-border corridors. The market structure consolidates around state-backed institutions with branch network advantages, while fintech specialists compete on virtual issuance speed. Three archetypes dominate: legacy banks with trust account compliance, mobile-native wallet operators, and corporate white-label program managers. Competitive moves center on API integration partnerships with gig platforms and EMV contactless certification acceleration.
Among state-backed institutions, Bank Rakyat Indonesia, Mandiri Bank, and Bank Central Asia exemplify the branch-network archetype leveraging distribution density across Java's second-tier cities. These entities occupy positions where physical reload infrastructure and regulatory licensing create defensive moats against pure-digital entrants. Fintech Payment Service Providers and Digital Wallet Operators represent the velocity-focused tier, competing through instant onboarding without traditional account relationships.
| Leading Market Players |
|---|
| Bank Rakyat Indonesia |
| Bank BNI |
| Mandiri Bank |
| International Payment Providers |
| Fintech Payment Service Providers |
| Bank Central Asia |
| Bank DKI |
| Digital Wallet Operators |
| Bank Negara Indonesia |
| Others |
Cost & Logistics Intelligence
Corporate payroll digitization mandates across plantation and mining sectors are compressing procurement timelines for reloadable prepaid instruments, forcing issuers to pre-position EMV-certified card stock and absorb safeguarding compliance costs that elevate baseline pricing tiers.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as employers demand same-month issuance for seasonal workforce onboarding. Three-tier pricing structure across premium, standard, and economy levels reflects EMV certification grade and trust account safeguarding tier. Cost compression in economy-tier virtual issuance is intensifying because fintech entrants compete on API integration speed. Plantation sector buyers exhibit highest price sensitivity; white-label corporate programs show lowest sensitivity due to bundled compliance services.
Supply Chain Analysis
Direct-to-corporate channels handle bulk payroll procurement while retail distribution runs through licensed bank branches and telco-integrated mobile apps. EMV chip manufacturing concentrates in Taiwan, South Korea, and China. Card personalization and fulfillment draws from domestic Jakarta and Surabaya facilities. Single-source vulnerability in NFC module supply creates exposure to semiconductor allocation constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed e-money issuance capacity remains bottlenecked by Bank Indonesia's tiered capital requirements, propping pricing power for incumbents with established trust account infrastructure.
For Market Incumbents: Anticipate fintech API competitors by accelerating virtual card certification timelines and securing exclusive payroll platform integrations. Defensive consolidation through acquisition of regional agent networks in outer island markets protects reload infrastructure moats. For New Entrants and Emerging Players: Plantation sector employers in Kalimantan and Sulawesi represent underserved buyer archetype with unmet demand for sharia-compliant disbursement instruments. White-label program structures for mining contractors offer most penetrable entry path through compliance-light partnership models. For Investors and Strategic Acquirers: The window for entry favors mobile-native wallet operators with cloud-native core banking stacks. Long-term viability hinges on QRIS gateway certification completion. Watch Bank Indonesia's e-money licensing tier consolidation as inflection signal for regulatory capture value.| Strategic Initiative | Industry Significance |
|---|---|
| EMV Contactless Certification Acceleration | Bank Indonesia's migration timeline compresses 12-18 month compliance windows for existing portfolios. |
| API Integration Partnership | Gig platform employers in Jakarta demand same-day virtual card issuance for earnings access. |
| Agent Network Expansion | Outer island reload infrastructure gaps limit adoption velocity in Eastern Indonesia markets. |
| Trust Account Safeguarding Investment | Segregated fund structures differentiate licensed operators from unregulated wallet providers. |
| Corporate White-Label Program Development | Bulk issuance contracts for plantation and mining sectors command superior margin pools. |
Research Approach
Independent corroboration across prepaid card program managers, Bank Indonesia regulatory affairs officers, and corporate payroll directors underwrites the qualitative findings. Primary interviews with fintech product leads, bank e-money operations heads, and telco wallet strategists combined with secondary validation from BI licensing disclosures, OJK consumer protection bulletins, and QRIS gateway participation records. Bottom-up issuer capacity modeling and top-down transaction volume estimates triangulate market sizing.
Rate-of-change decomposition across product type, customer segment, distribution channel, and technology tier shapes the analytical framework. Segmentation dimensions modeled include reloadable versus virtual instrument architecture, retail versus corporate procurement patterns, mobile app versus branch-based distribution economics, and EMV chip versus contactless NFC technical specifications. CAGRs derive from issuer volume disclosures and gateway transaction throughput data across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Bank Indonesia licensing tier revisions and QRIS merchant acceptance expansion rates. Forecasts reflect assumptions around regulatory compliance timelines and infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Telecom Cloud Billing Market
Payments
POS Terminals Market
Payments
Global Accounts Payable Software Market
Payments
APAC Mobile Payments Market
Payments
Online Payment Gateway Market
Payments
Remittance Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Buy Now Pay Later Market
Payments
Digital Money Transfer Market
Payments
Japan Credit Cards Market
Payments
Germany Real Time Payments Market
Payments
Canada Payments Market
Payments
Clearing Houses and Settlements Market
Payments
Malaysia Payments Market
Payments
United States Payments Market
Payments
Online Charging System (OCS) Market