
 Digital Money Transfer Market | 2026-2036
Digital Money Transfer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Money Transfer Market Insights
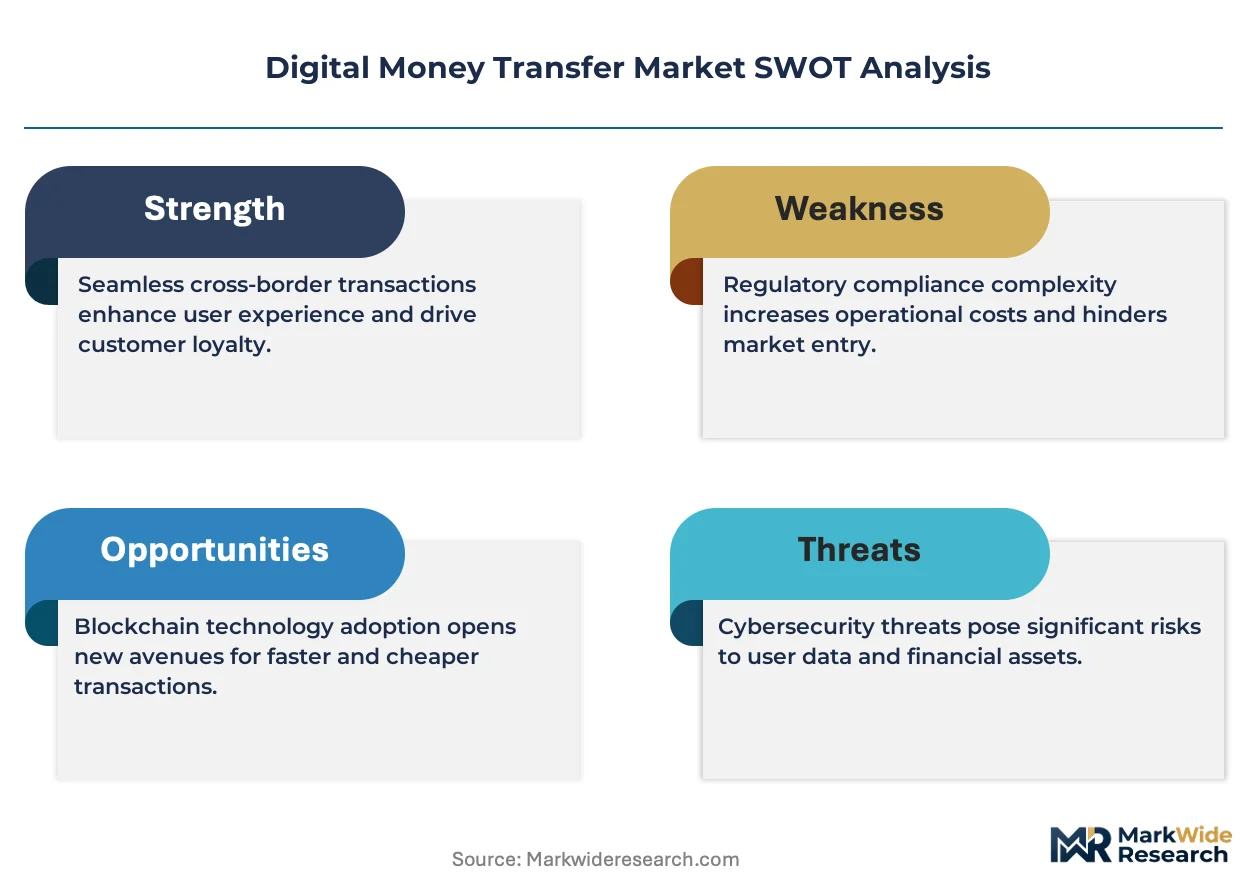
A shortage of compliance-trained software engineers is unwinding product development timelines across the sector. Western Union Holdings Inc. sustains its agent network density in cash-heavy corridors. Wise Payments Limited differentiates through transparent, mid-market-rate pricing architecture. Remitly Inc. specializes in mobile-first onboarding for underbanked senders in North America.
Digital money transfer denotes electronic movement of monetary value between parties without physical currency exchange, relying on encrypted API protocols, real-time gross settlement systems, and distributed ledger reconciliation to clear transactions within seconds. Peer-to-Peer transaction volume dominates retail flows, while Business-to-Business cross-border settlement commands wider spreads and stickier platform relationships. Mobile Apps capture the fastest-growing share of initiation channels, though Agent Networks retain critical last-mile utility in emerging markets with limited smartphone penetration.
The US Treasury's Financial Crimes Enforcement Network enforces Bank Secrecy Act compliance on dollar-denominated transfers, while the EU's Payment Services Directive 2 mandates open banking access and strong customer authentication across European corridors. India's Reserve Bank supervises UPI interoperability standards that foreign fintechs must adopt for local clearing access. Stakeholders must weigh licensing fragmentation against the operational leverage of unified global compliance stacks.
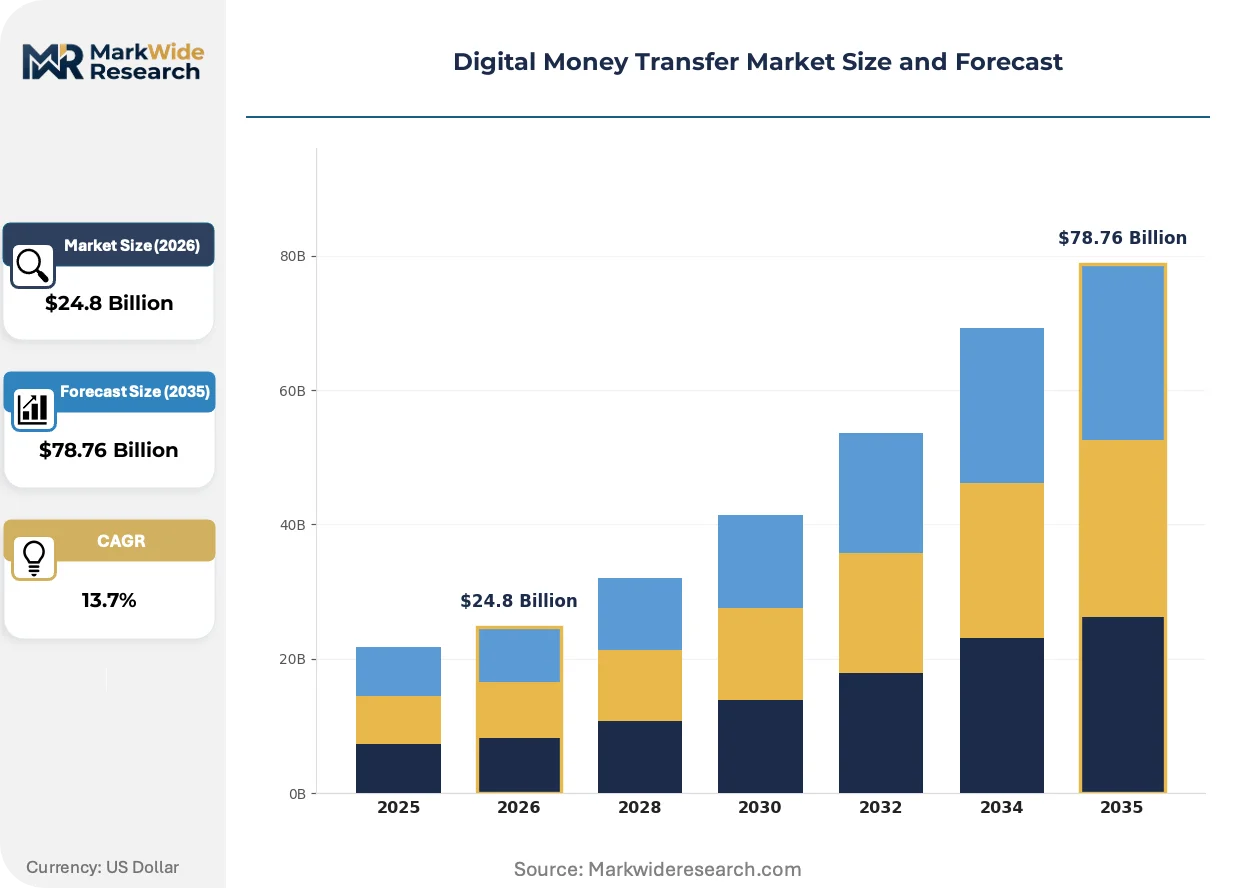
Market Dynamics
Real-time payment rails are compressing correspondent banking margins and forcing incumbents to abandon legacy settlement layers. India's UPI interoperability standards and the EU's Payment Services Directive 2 are rewriting clearing economics across high-volume corridors.
Growth Catalysts
- India's UPI Interoperability Mandate:Foreign fintechs must adopt Reserve Bank of India protocols for local clearing access, accelerating platform localization.
- Open Banking APIs:Account-to-account rails in European corridors eliminate card network interchange, reducing sender fees by half.
- Gulf-to-South Asia Remittance Density:Migrant worker flows from UAE, Saudi Arabia, and Qatar sustain volume anchors for digital onboarding.
Market Restraints
- Compliance Talent Scarcity:Shortages of Bank Secrecy Act-trained engineers in US corridors extend product development cycles by quarters.
- Agent Network Lock-In:Cash-heavy last-mile infrastructure in Sub-Saharan Africa limits pure-digital market penetration.
- Stablecoin Settlement Risk:Regulatory ambiguity around dollar-pegged crypto rails creates correspondent bank derisking.
Strategic Opportunities
- Philippines Digital Wallet Convergence:GCash and Maya interoperability gaps create white space for embedded remittance APIs.
- EU Strong Customer Authentication Tailwind:PSD2 mandate for biometric verification lowers fraud costs for compliant entrants.
- Blockchain-Nostro Bridge Tech:Distributed ledger pre-funding is compressing FX settlement from T+2 to near-real-time in pilot corridors.
Industry Challenges
- Fragmented Licensing Stacks:State-by-state money transmitter licenses in the US require 50+ regulatory filings for national coverage.
- Core Banking Integration Friction:Legacy COBOL systems at tier-2 banks in South Asia resist API-native reconciliation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Money Transfer Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.76 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Peer-to-Peer, Business-to-Business, Cross-Border, Mobile Wallet Platform: Mobile Apps, Web Portals, USSD Systems, Agent Networks Service Model: Real-Time Payment, Batch Processing, Scheduled Transfers, Cash Pickup End User: Individual Consumers, Small Enterprises, Nonprofit Organizations, Financial Institutions |
| Companies Covered | Western Union Holdings Inc., PayPal Holdings Inc., Wise Payments Limited, Moneygram International Inc., Remitly Inc., WorldRemit Ltd., Ria Financial Services Ltd., NIUM Pte. Ltd., TransferGo Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Money Transfer Market Trends and Innovations
Settlement architecture is splitting between real-time retail rails and batch wholesale systems. Incumbents face binary choices: rebuild core infrastructure or cede high-frequency corridors to API-native competitors.
Distributed ledger reconciliation is bifurcating correspondent banking economics. RippleNet and Stellar-based pilots settle dollar-rupee flows in seconds versus traditional SWIFT gpi's 24-hour windows. Tier-1 banks in Singapore and London are adopting these rails for high-value B2B corridors while retail platforms in India and Brazil bypass them entirely for domestic UPI or Pix networks.
The EU's Payment Services Directive 2 is mandating open banking access and strong customer authentication across European corridors. Banks must expose account data via standardized APIs, enabling third-party fintechs to initiate transfers without card rails. German and Dutch incumbents are responding by acquiring API gateway providers to retain payment initiation control.
Sender behavior is rotating from branch-based initiation toward mobile-first onboarding with biometric verification. Underbanked migrants in North America now complete KYC via selfie liveness checks rather than document uploads. This shift is most visible in corridors linking US metropolitan areas to rural Pakistan and Bangladesh, where smartphone penetration exceeds formal banking access.
Digital Money Transfer Market Segmentation
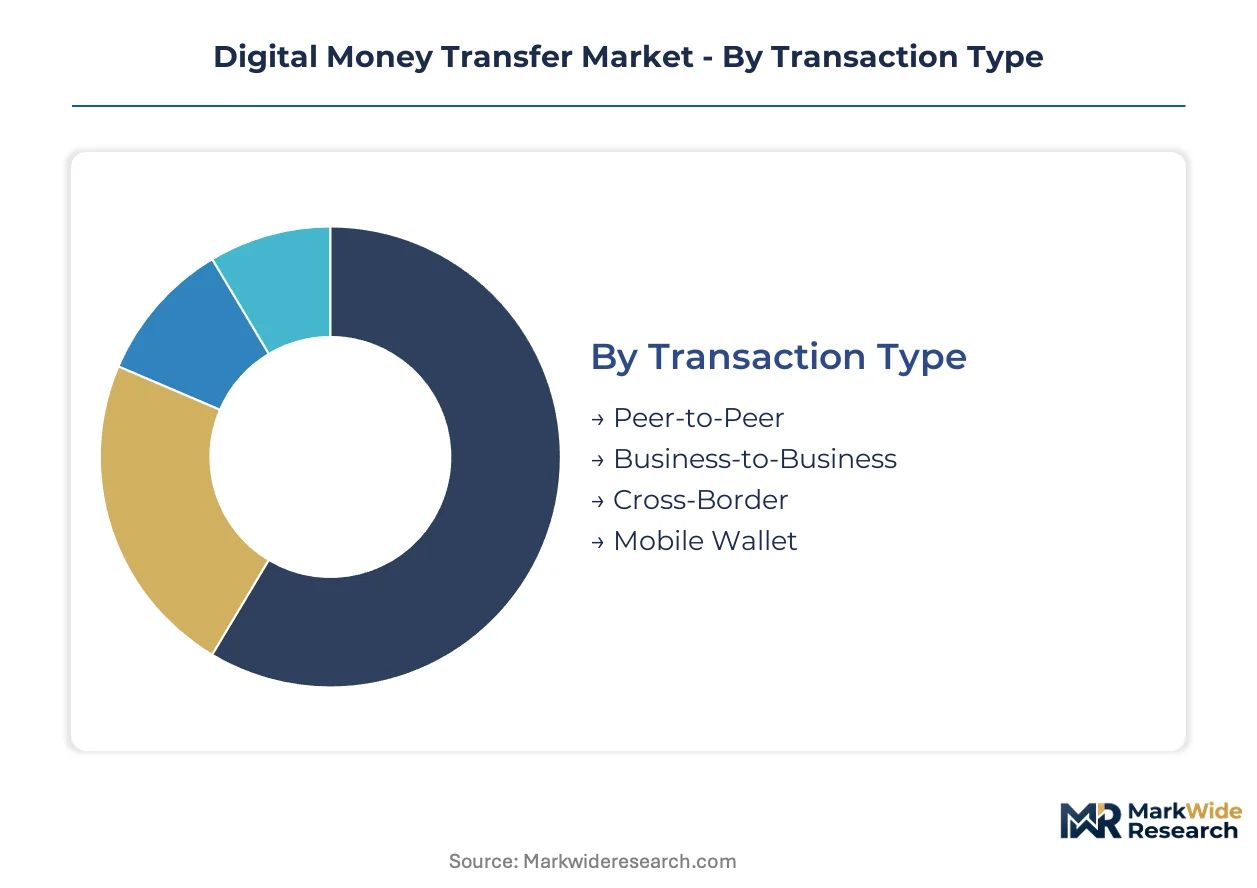
Segmentation in digital money transfer reveals how platform architecture and transaction economics create divergent margin profiles. Substitution pressures vary sharply across channels, with mobile-native rails displacing legacy correspondent banking in high-frequency corridors while cash infrastructure retains defensive moats in underbanked regions.
Transaction Type:
Substitute pressure concentrates most intensely on cross-border retail flows, where real-time domestic rails and stablecoin pilots erode traditional SWIFT economics.
- Peer-to-Peer:Direct account-to-account transfers between individuals, typically under $1,000 per transaction, executing through encrypted API protocols. Demand clusters in Gulf Cooperation Council-to-South Asia corridors where migrant workers send recurring family support, with India's UPI interoperability mandate accelerating platform localization for inbound rupee settlement.
- Business-to-Business:Cross-border commercial settlements involving invoices, trade finance, and supply chain payments, commanding wider FX spreads and stickier banking relationships. Volume concentrates in Singapore-London corridors where distributed ledger pilots compress settlement from T+2 to near-real-time, though regulatory ambiguity around dollar-pegged crypto rails creates correspondent bank derisking.
- Cross-Border:Retail remittances traversing national jurisdictions, subject to Bank Secrecy Act compliance in US corridors and PSD2 authentication mandates in Europe. Corridors linking UAE, Saudi Arabia, and Qatar to India, Pakistan, and the Philippines sustain volume anchors despite margin compression from open banking APIs.
- Mobile Wallet:Stored-value account transfers closed within proprietary ecosystems like GCash or Maya, creating interoperability gaps that embedded remittance APIs exploit. Philippines digital wallet convergence presents white space for API-native entrants seeking to bridge fragmented clearing layers.
Peer-to-Peer retains volume leadership; Mobile Wallet holds the steepest expansion curve.
Platform:
Cost tier stratification separates high-frequency digital initiation from high-touch cash servicing, with hybrid models capturing corridor-specific premiums.
- Mobile Apps:Smartphone-native interfaces with biometric KYC and real-time FX quoting, capturing the fastest-growing share of initiation channels. Underbanked migrants in US metropolitan areas complete onboarding via selfie liveness checks rather than document uploads, particularly for flows to rural Pakistan and Bangladesh where smartphone penetration exceeds formal banking access.
- Web Portals:Browser-based platforms targeting desktop users and higher-value transactions, maintaining relevance in business-to-business corridors where multi-step approval workflows require larger screens. German and Dutch incumbents are acquiring API gateway providers to retain payment initiation control against open banking disintermediation.
- USSD Systems:Unstructured Supplementary Service Data protocols enabling feature-phone transfers through SMS-like menus, critical for last-mile penetration in Sub-Saharan Africa. Agent network lock-in limits pure-digital market penetration where cash-heavy infrastructure dominates.
- Agent Networks:Physical cash-in/cash-out points sustaining critical utility in emerging markets with limited smartphone penetration. Western Union Holdings Inc. defends density in cash-heavy corridors despite compression from real-time payment rails.
Agent Networks retain the widest geographic coverage; Mobile Apps are expanding most quickly.
Service Model:
Application urgency separates instant settlement premiums from scheduled transfer discounts, with batch systems retaining cost advantages for non-time-sensitive flows.
- Real-Time Payment:Immediate gross settlement through domestic rails like India's UPI or Brazil's Pix, eliminating correspondent banking delays. Reserve Bank of India protocols require foreign fintech adoption for local clearing access, accelerating platform localization.
- Batch Processing:Aggregated transactions cleared at fixed intervals, reducing per-unit processing costs for low-priority transfers. Legacy COBOL systems at tier-2 banks in South Asia resist API-native reconciliation protocols, creating integration friction.
- Scheduled Transfers:Recurring automated payments for rent, tuition, or family support, reducing sender cognitive load and improving platform retention. Wise Payments Limited differentiates through transparent, mid-market-rate pricing architecture for repeat users.
- Cash Pickup:Physical collection at designated payout locations, preserving optionality for unbanked recipients. Remitly Inc. specializes in mobile-first onboarding for underbanked senders in North America targeting cash payout endpoints.
Real-Time Payment commands the highest sender willingness-to-pay; Scheduled Transfers show the steepest volume climb.
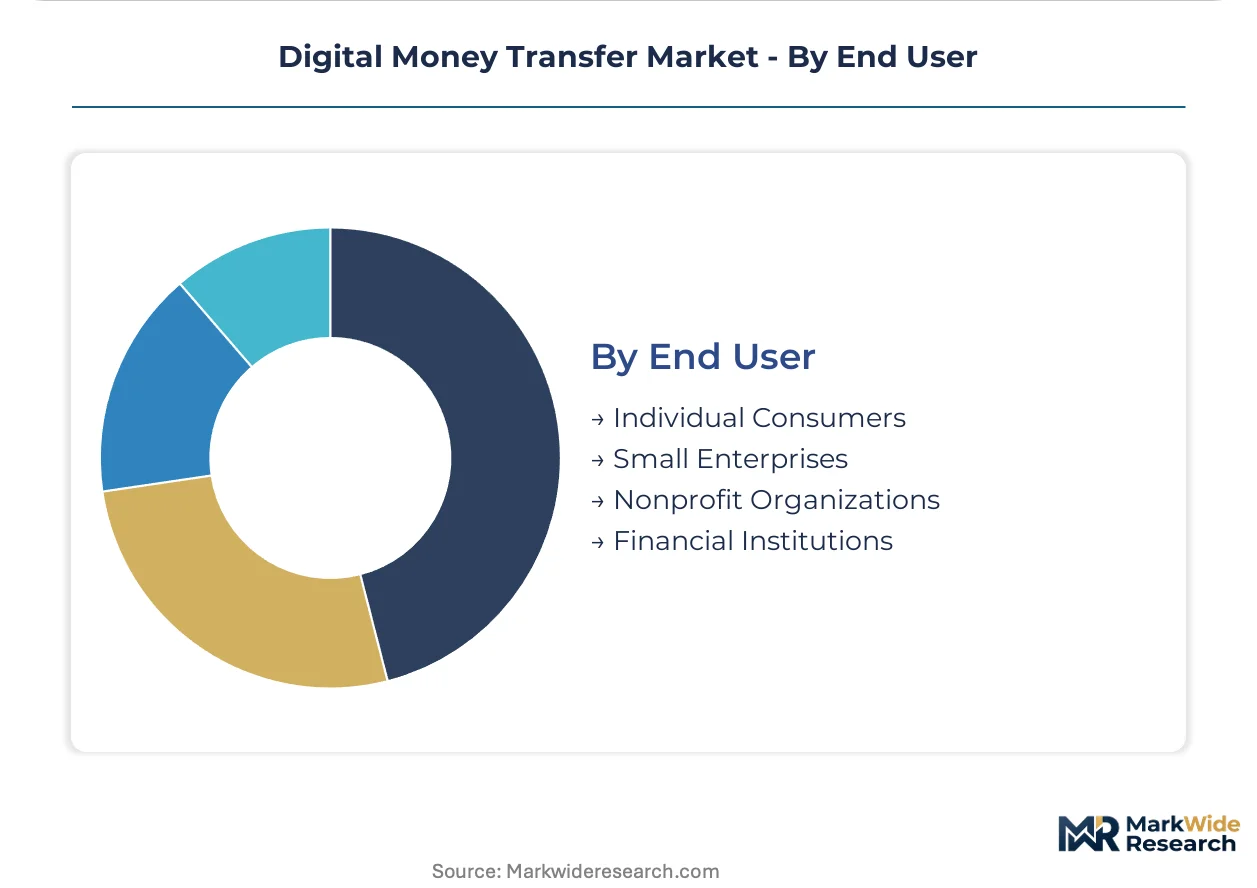
End User:
Customer sophistication determines compliance burden and pricing power, with financial institutions extracting steepest volume discounts.
- Individual Consumers:Retail senders prioritizing speed, transparency, and low fees, typically transacting under $500 per month. Migrant worker remittances to South Asia and Sub-Saharan Africa anchor volume growth for this segment.
- Small Enterprises:Micro-businesses and sole proprietors managing cross-border supplier payments and freelance settlements. Open banking APIs in European corridors eliminate card network interchange, reducing sender fees by half for compliant users.
- Nonprofit Organizations:Aid disbursements and development fund flows requiring audit trails and regulatory reporting. PSD2 strong customer authentication mandates lower fraud costs for compliant entrants serving this risk-sensitive segment.
- Financial Institutions:Banks, credit unions, and payment processors seeking white-label infrastructure or correspondent relationships. Tier-1 banks in Singapore and London adopt distributed ledger rails for high-value B2B corridors while retail platforms bypass them entirely.
Individual Consumers retain transaction volume leadership; Small Enterprises are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI rails process retail transfers instantaneously while the United States retains batch-based correspondent banking for dollar corridors, revealing a stark infrastructure gap between real-time and legacy settlement economies.
United States
Migrant worker remittances from Gulf states anchor volume flows into South Asian corridors. FinCEN enforces Bank Secrecy Act compliance on dollar-denominated transfers, extending product timelines through stringent AML protocols. Silicon Valley fintech clusters concentrate API-native platform development despite state-by-state licensing fragmentation.
India
Inbound rupee settlement from UAE and Saudi Arabia drives platform localization mandates. RBI supervises UPI interoperability standards that foreign fintechs must adopt for clearing access. Mumbai's financial district hosts domestic payment processors integrating real-time rails with legacy core banking systems.
United Kingdom
Cross-border B2B settlement concentrates in London-Singapore corridors where distributed ledger pilots compress FX timing. FCA alignment with PSD2 strong customer authentication reduces fraud costs for compliant entrants. The City of London anchors correspondent banking relationships despite margin compression from open banking APIs.
Germany
Account-to-account rails eliminate card network interchange for European corridor transfers. BaFin supervision of payment institutions mandates operational resilience for real-time infrastructure. Frankfurt's banking cluster defends wholesale settlement relationships against API-native disintermediation.
Singapore
High-value B2B corridors to London and Dubai sustain tier-1 bank adoption of blockchain-nostro bridge technology. MAS regulatory clarity on digital payment tokens enables pilot settlement programs. The Marina Bay financial district hosts distributed ledger reconciliation trials compressing T+2 to near-real-time.
Digital Money Transfer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with agent network density separating cash-heavy incumbents from API-native challengers. The market structure bifurcates between legacy correspondent banking relationships and real-time domestic rail integration. Two strategic archetypes dominate: hybrid cash-digital platforms defending last-mile infrastructure, and mobile-first specialists capturing smartphone-native senders. Competitive moves concentrate on M&A for API gateway control and geographic licensing expansion.
Within the hybrid infrastructure tier, Western Union Holdings Inc. and Moneygram International Inc. occupy positions anchored by physical payout density in underbanked corridors. Wise Payments Limited exemplifies the transparent pricing archetype through mid-market-rate architecture. These three entities represent the spectrum from legacy agent networks to digital-native transparency, with each archetype capturing distinct sender segments based on corridor maturity and recipient banking access.
| Leading Market Players |
|---|
| Western Union Holdings Inc. |
| PayPal Holdings Inc. |
| Wise Payments Limited |
| Moneygram International Inc. |
| Remitly Inc. |
| WorldRemit Ltd. |
| Ria Financial Services Ltd. |
| NIUM Pte. Ltd. |
| TransferGo Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term correspondent banking contracts lock in FX spread visibility for tier-1 institutions while compressing margins for retail-focused platforms dependent on spot-rate volatility. This contract-structure pattern anchors supply access to legacy SWIFT rails for B2B corridors while forcing API-native competitors into real-time domestic rail partnerships that sacrifice pricing power for settlement speed.
Pricing Analysis
Per-unit transactional pricing dominates retail peer-to-peer flows, with FX spreads and flat fees constituting the primary revenue architecture. Price differentiation hinges on corridor density and settlement rail choice—UPI-linked rupee corridors command tighter spreads than cash-heavy Sub-Saharan Africa routes. Cost compression in high-frequency Gulf-to-South Asia corridors is intensifying because open banking APIs eliminate card network interchange. Individual consumers exhibit highest price sensitivity, while financial institutions extract volume discounts through nostro pre-funding arrangements.
Supply Chain Analysis
Settlement infrastructure lead times stretch from instantaneous UPI clearing to 24-hour SWIFT gpi windows, creating inventory-like liquidity management challenges for platform operators. Software engineering capacity concentrates in India, Singapore, and the United States, with compliance-trained talent pools particularly shallow in US corridors. Raw material dependencies include encrypted API protocols, biometric verification modules, and distributed ledger reconciliation engines. Single-source vulnerability around Reserve Bank of India UPI access protocols creates regulatory chokepoint risk. Distribution runs through hybrid models combining mobile app storefronts with agent network cash-out points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Migrant worker remittance volumes track Gulf state economic cycles, positioning the market for recovery as construction and hospitality sectors rebound from regional downturns. This cyclical driver justifies near-term capacity positioning despite current margin compression.
For Market Incumbents: Fortify agent network density in cash-heavy Sub-Saharan corridors against pure-digital disintermediation. Acquire API gateway providers in European markets to retain payment initiation control under PSD2 open banking mandates. Prioritize backward integration into compliance software stacks to reduce engineering talent dependency.
For New Entrants and Emerging Players: RBI UPI certification fast-tracks unlock immediate access to India's inbound remittance volume anchors. Target Philippines digital wallet interoperability gaps where GCash-Maya fragmentation creates embedded remittance API white space. Lead with mobile-first biometric KYC to capture underbanked North American sender segments.
For Investors and Strategic Acquirers: API-native mid-cap specialists with Gulf corridor licenses represent the most defensible acquisition archetype. Long-term viability centers on real-time rail integration density rather than legacy correspondent banking relationships. Watch Reserve Bank of India foreign fintech licensing velocity as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| UPI Interoperability Certification | RBI protocol adoption unlocks instant rupee settlement access for foreign platforms. |
| API Gateway Acquisition | German and Dutch incumbents retain payment initiation control against open banking disintermediation. |
| Biometric KYC Platform Launch | Selfie liveness checks capture underbanked US migrants sending to rural Pakistan corridors. |
| Blockchain-Nostro Bridge Pilot | Singapore-London tier-1 banks compress FX settlement from T+2 to near-real-time. |
| Agent Network Density Expansion | Western Union defends cash-heavy last-mile penetration in Sub-Saharan Africa. |
Research Methodology
A standing panel of payment platform CTOs, compliance officers at money transmitters, Reserve Bank of India regulatory liaisons, and Gulf corridor remittance operators provided ongoing calibration across the study period. Primary interview data triangulated against secondary sources including FinCEN enforcement actions, RBI circulars on UPI interoperability, EU PSD2 implementation reports, and Singapore MAS digital payment token guidelines. Bottom-up transaction volume estimates from corridor-specific flows reconciled with top-down market sizing from banking association disclosures.
Consistency checks validated volume and value outputs against SWIFT gpi traffic data, UPI transaction dashboards, and correspondent banking relationship filings across the projection horizon. Segmentation modeling spanned transaction type, platform architecture, service model urgency, and end-user sophistication. CAGRs derived from corridor-specific volume trajectories, rail adoption curves, and regulatory implementation timelines. Forecast inputs incorporated migrant worker population flows, smartphone penetration curves, and real-time payment rail expansion schedules.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf Cooperation Council economic recovery and stable RBI foreign fintech access policies; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Accounts Payable Automation Market
Payments
Face-Swiping Payment Market
Payments
Luxembourg POS Terminals Market
Payments
Taiwan Mobile Payments Market
Payments
Italy POS Terminals Market
Payments
Credit Card Payments Market
Payments
South Korea Mobile Payment Market
Payments
Mobile Card Reader Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Mobile Money Market
Payments
Money Transfer Agencies Market
Payments
Contactless Payment Ring Market
Payments
Europe Real Time Payments Market
Payments
Smart POS System Market
Payments
North America Payment Gateway Market
Payments
Russia Payments Market