
 Remittance Market | 2026-2036
Remittance Market Size, Share, and Industry Trends Forecast 2026-2036
Remittance Market Intelligence
Fragmentation among sender demographics is realigning competitive priorities across the remittance landscape. Temporary workers and students now represent distinct digital-native cohorts demanding instant, low-cost channels. Western Union Holdings Inc. leverages its agent network density to sustain cash pickup dominance in corridors with limited banking penetration. Wise Payments Limited differentiates through transparent mid-market pricing and multi-currency account infrastructure. Remitly Inc. specializes in mobile-first onboarding tailored to migrant worker profiles in North American origin markets.
Remittance denotes cross-border fund transfers initiated by individuals, typically migrant workers or expatriates, to recipients in their home countries through formal financial channels including banks, money transfer operators, and digital payment platforms. The transaction flow relies on correspondent banking relationships, real-time gross settlement systems, and increasingly API-driven fintech rails to achieve velocity and cost efficiency below traditional wire thresholds. Mobile wallets represent the fastest-expanding transfer method as smartphone penetration and agent interoperability deepen across emerging corridors. Banks retain structural margin pools in high-value business payment segments where compliance overhead favors institutional infrastructure. Fintech service providers occupy the growth frontier by unbundling foreign exchange markup and settlement latency from legacy operator models.
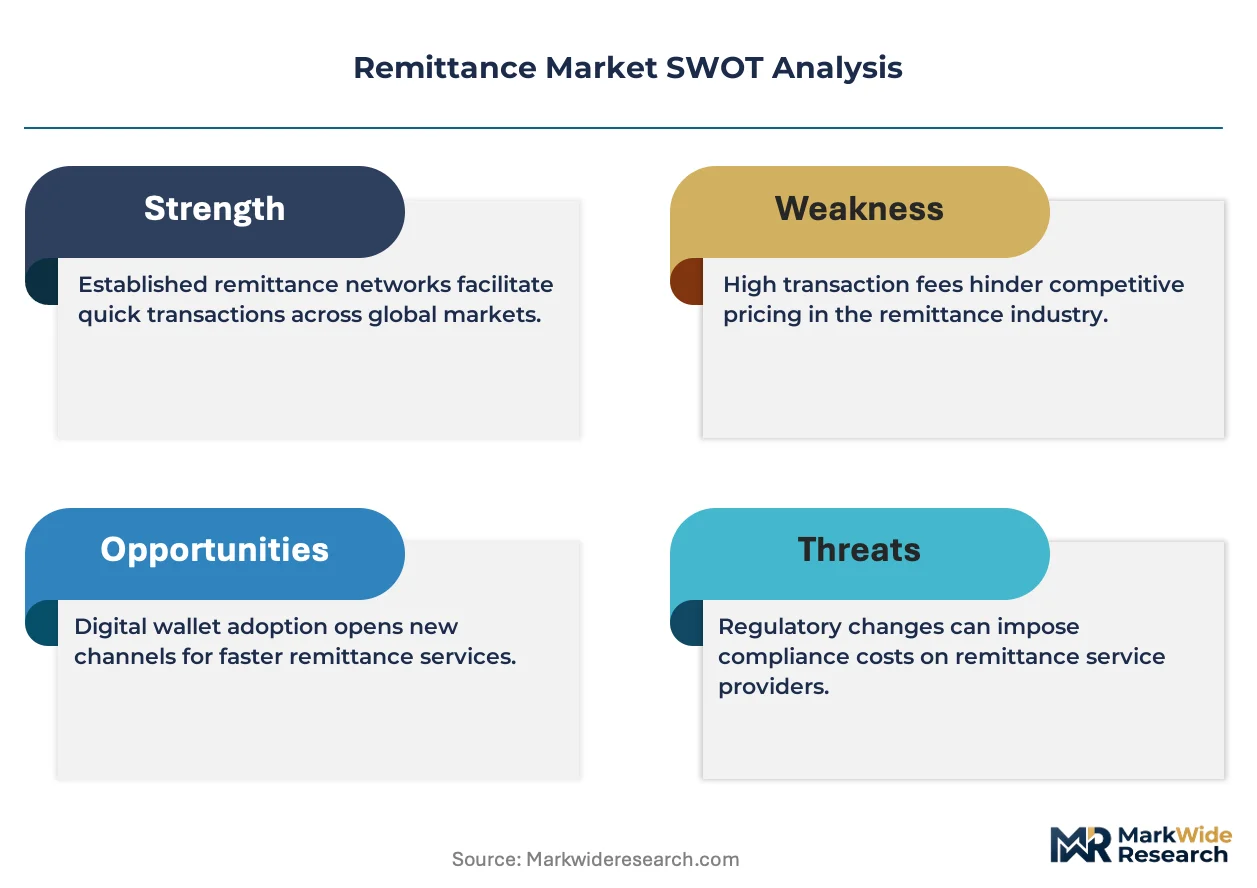
Regulatory frameworks including India's RBI outward remittance rules under the Liberalised Remittance Scheme, the EU's Payment Services Directive 2 open banking standards, and the US FinCEN Bank Secrecy Act compliance requirements collectively shape market access, capital controls exposure, and customer due diligence burdens. The Philippines central bank and Mexico's CNBV impose licensing and capital reserve conditions that filter participant viability and corridor pricing power. Stakeholders must monitor evolving central bank digital currency pilots and their potential to disintermediate traditional correspondent banking relationships in high-volume corridors.
Market Dynamics
Mobile wallet interoperability is compressing settlement timelines from days to minutes across Gulf Cooperation Council to South Asian corridors, forcing legacy money transfer operators to reprice foreign exchange markups or lose volume to API-native fintech rails.
Growth Catalysts
- India's Liberalised Remittance Scheme:RBI outward remittance rules enable resident individuals to transfer up to $250,000 annually without prior approval, expanding formal channel participation and reducing hawala dependency.
- Smartphone penetration:Android device density in Philippine provinces now exceeds 85 percent, enabling mobile-first onboarding for unbanked recipients previously dependent on cash pickup networks.
- Open banking APIs:EU Payment Services Directive 2 standards are migrating to Mexican and Indian regulatory frameworks, permitting third-party fintech access to core banking infrastructure for real-time verification.
Market Restraints
- Correspondent banking concentration:Dollar clearing remains dominated by New York-based clearing banks, exposing non-US operators to de-risking pressures and account termination.
- Compliance cost escalation:US FinCEN Bank Secrecy Act requirements mandate multi-layered customer due diligence, elevating operational overhead disproportionately for sub-$500 transaction corridors.
- Capital control variability:Philippines central bank and Mexico's CNBV impose divergent licensing reserve requirements, fragmenting operational scale economics across priority corridors.
Strategic Opportunities
- Rural Mexico banking penetration:Oxxo convenience store networks and SPEI real-time settlement integration create last-mile distribution infrastructure for cash-to-mobile conversion.
- Central bank digital currency pilots:India's digital rupee and UAE's CBDC experiments may disintermediate correspondent banking entirely in high-volume dirham-rupee corridors.
- Student remittance vertical:University-sponsored disbursement programs in Canada and Australia represent uncaptured volume with lower fraud incidence than general population transfers.
Industry Challenges
- Sanctions screening latency:Real-time transaction screening against OFAC, UN, and EU lists introduces friction that conflicts with consumer expectations for instant confirmation.
- Legacy core banking integration:Mainframe-based settlement systems at tier-one banks resist API modernization, forcing fintechs to maintain expensive dual-rail architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remittance Market |
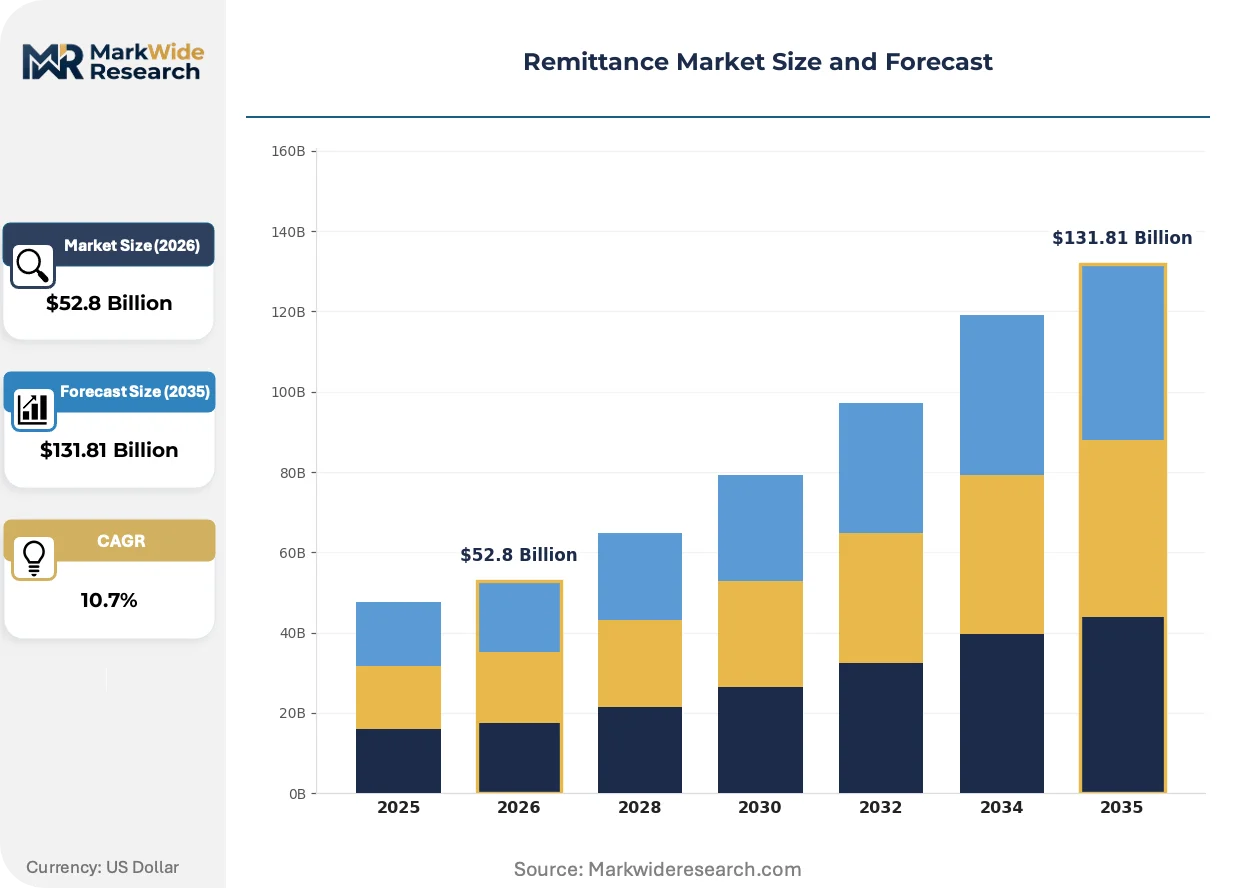
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $131.81 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transfer Method: Bank Transfers, Mobile Wallets, Cash Pickup, Online Transfers Sender Type: Expatriates, Temporary Workers, Students, Migrants Receiver Type: Family Support, Business Payments, Emergency Funds, Investment Service Provider: Telecom Companies, Banks, Payment Processors, Fintechs |
| Companies Covered | Western Union Holdings Inc., MoneyGram International Inc., Ria Financial Services Ltd., Wise Payments Limited, PayPal Holdings Inc., Remitly Inc., WorldRemit Ltd., ZEPZ, Revolut Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remittance Market Strategic Shifts & Innovations
API-first infrastructure is unbundling the traditional money transfer stack, separating foreign exchange execution, compliance verification, and last-mile disbursement into modular, best-of-breed components that recombine dynamically per corridor.
Embedded finance APIs are electrifying remittance origination by enabling payroll platforms, gig economy apps, and neobanks to offer branded cross-border transfer without building licensed money transmitter infrastructure. Southeast Asian fintechs and Gulf-based labor recruitment platforms are the fastest adopters, integrating white-label remittance into worker onboarding workflows. This compression of origination cost is enabling sub-1 percent pricing in high-frequency corridors previously dominated by 4-6 percent agent-based models.
EU Payment Services Directive 2 open banking standards are mandating account-to-account payment initiation services that bypass card networks entirely. The industrial consequence is direct bank-to-bank settlement at mid-market rates, stripping interchange and scheme fees from the economics. UK-EU corridors and intra-European transfers are the most affected segments, with consumer behavior shifting toward app-based price comparison before execution.
Recipient preference is pivoting from cash pickup toward mobile wallet credit in Bangladesh, Kenya, and Nigeria, where MFS Africa and bKash interoperability creates account-to-account finality without bank branch dependency. Urban migrants in Dhaka and Nairobi are the visible leading edge, demanding instant notification and balance visibility that cash agents cannot replicate. This behavioral shift is compressing the addressable market for physical agent networks and elevating smartphone ownership to a core market access determinant.
Remittance Market Segmentation
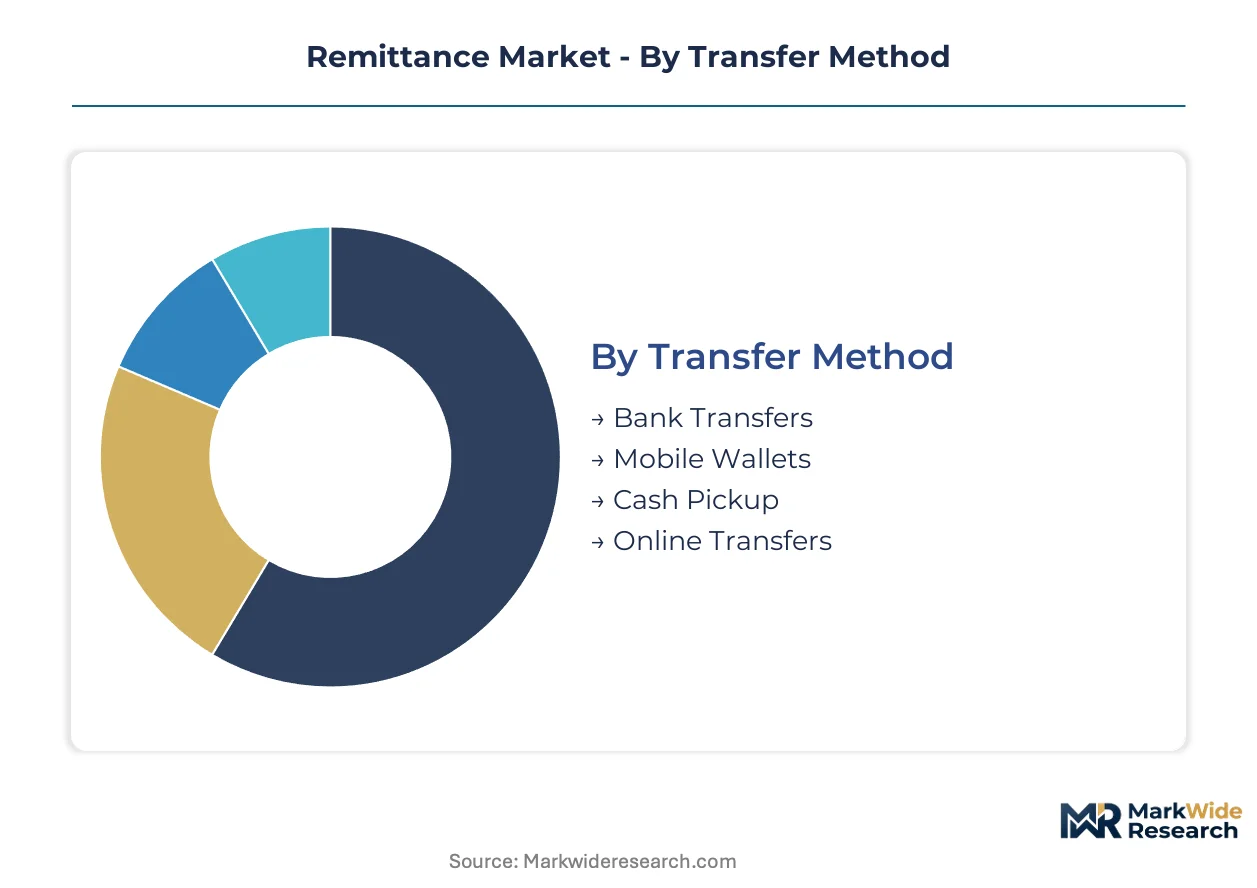
Remittance flows fragment across four distinct dimensions that determine pricing power, compliance burden, and technology infrastructure requirements. Transfer method and sender type dominate volume concentration, while receiver purpose and service provider selection shape margin capture across corridor-specific competitive dynamics.
Transfer Method:
Supply concentration in digital rails is compressing settlement timelines and repricing legacy operator models.
- Bank Transfers:Correspondent banking relationships process high-value transactions through SWIFT messaging and real-time gross settlement systems. India's RBI outward remittance rules under the Liberalised Remittance Scheme and EU Payment Services Directive 2 standards favor institutional rails for transactions above $10,000 where compliance documentation requirements escalate.
- Mobile Wallets:API-driven fintech rails achieve minute-level settlement across Gulf Cooperation Council to South Asian corridors through interoperability protocols like MFS Africa and bKash. Smartphone penetration exceeding 85 percent in Philippine provinces enables cash-to-mobile conversion that bypasses physical agent dependency.
- Cash Pickup:Agent network density sustains dominance in corridors with limited banking penetration, particularly rural Mexico Oxxo convenience store networks and unbanked recipient markets in Bangladesh and Nigeria.
- Online Transfers:Web-based onboarding platforms aggregate price comparison across multiple service providers, capturing digitally native sender demographics in North American and European origin markets.
Bank transfers absorb the bulk of installed capacity; mobile wallets are expanding most quickly.
Sender Type:
Demographic fragmentation is realigning product design priorities toward corridor-specific onboarding workflows.
- Expatriates:High-income professionals in Gulf Cooperation Council economies generate recurring high-value flows to South Asian family dependents, demanding hedging tools and multi-currency account infrastructure.
- Temporary Workers:Construction and domestic labor cohorts in Saudi Arabia and UAE require mobile-first interfaces with minimal documentation friction and low minimum transfer thresholds.
- Students:University-sponsored disbursement programs in Canada and Australia represent concentrated volume with lower fraud incidence, favoring institutional partnerships over consumer marketing.
- Migrants:Long-term resident populations in European and North American markets exhibit behavioral loyalty to established brands while price-sensitive to foreign exchange markup transparency.
Temporary workers absorb the bulk of transaction volume; students are climbing the fastest as an emerging vertical.
Receiver Type:
End-use purpose determines disbursement velocity requirements and regulatory scrutiny intensity.
- Family Support:Recurring low-value transfers to household dependents constitute the core volume base across all major corridors, with preference shifting from cash pickup toward mobile wallet credit in Bangladesh, Kenya, and Nigeria.
- Business Payments:Cross-border supplier settlements and trade-related flows require invoice documentation and enhanced due diligence, sustaining bank dominance despite fintech price competition.
- Emergency Funds:Time-critical disaster relief and medical expense transfers command premium pricing tolerance, favoring instant confirmation rails over cost-optimized batch settlement.
- Investment:Outward remittances for property acquisition and securities purchases trigger capital controls monitoring under India's RBI Liberalised Remittance Scheme annual limits and Philippines central bank reporting requirements.
Family support absorbs the bulk of corridor volume; investment flows are gaining share fastest as regulatory thresholds expand.
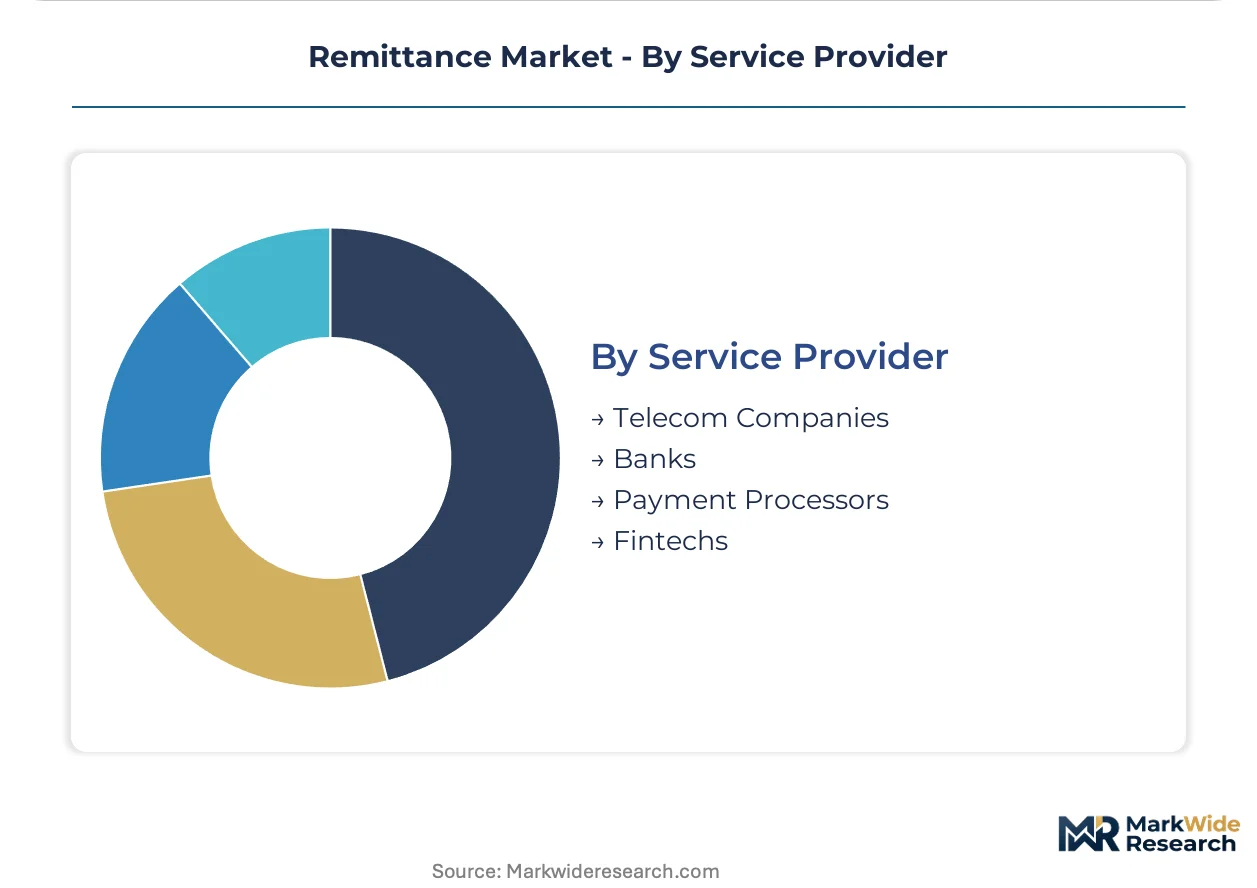
Service Provider:
Competitive positioning stratifies across licensed infrastructure ownership and technology stack modularity.
- Telecom Companies:Mobile network operators leverage subscriber identity verification and airtime distribution networks to capture last-mile disbursement in African and South Asian markets.
- Banks:Tier-one institutions retain structural margin pools in high-value segments where US FinCEN Bank Secrecy Act compliance overhead and correspondent banking relationships filter fintech participation.
- Payment Processors:Card network-linked platforms intermediate consumer-facing origination, absorbing interchange fees that API-native account-to-account rails increasingly bypass under open banking frameworks.
- Fintechs:API-first specialists unbundle foreign exchange execution, compliance verification, and settlement into modular components that recombine dynamically per corridor, achieving sub-1 percent pricing in high-frequency Gulf-rupee and Gulf-peso channels.
Banks absorb the bulk of value-based revenue; fintechs are expanding most quickly across transaction count metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India generates the largest inbound remittance volume globally, with Gulf Cooperation Council economies supplying the dominant share of migrant worker flows. Corridor concentration between specific origin-destination pairs determines pricing power and infrastructure investment priorities across regional markets.
India
Kerala and Tamil Nadu receive disproportionate Gulf-origin flows from construction and domestic labor cohorts in UAE and Saudi Arabia. RBI's Liberalised Remittance Scheme caps outward transfers at $250,000 annually, channeling investment-oriented flows through formal banking rails. Mumbai's financial district hosts the headquarters of major money transfer operators serving the Gulf-rupee corridor.
Philippines
Overseas Filipino Workers in Saudi Arabia, UAE, and Singapore sustain recurring family support transfers exceeding $30 billion annually. Bangko Sentral ng Pilipinas mandates licensing and capital reserves for remittance service providers, filtering participant viability. Metro Manila concentrates fintech development while provincial smartphone penetration enables mobile wallet adoption.
Mexico
Migrant workers in the United States originate the second-largest remittance corridor globally, with concentration in California, Texas, and Illinois origin markets. CNBV licensing requirements and SPEI real-time settlement integration shape competitive access. Oxxo convenience store networks in rural states provide last-mile cash distribution infrastructure.
United Arab Emirates
Expatriate professionals and temporary laborers from India, Pakistan, and Bangladesh generate high-frequency outbound flows. UAE central bank digital currency pilots target dirham-rupee and dirham-rupee corridor efficiency. Dubai International Financial Centre clusters fintech infrastructure serving South Asian remittance corridors.
United States
Mexico-bound transfers dominate outbound volume, with secondary corridors to Philippines, India, and Nigeria. FinCEN Bank Secrecy Act compliance mandates multi-layered customer due diligence, elevating operational overhead. New York-based correspondent banks control dollar clearing access, exposing non-US operators to de-risking pressures.
Remittance Market Key Industry Players
United States-based operators anchor one tier; European and Asian fintech specialists hold differentiated positions through technology-first pricing models. Market structure stratifies across three tiers: legacy money transfer operators with agent network density, digital-native specialists with API-driven infrastructure, and embedded finance platforms integrating remittance into payroll and gig economy workflows. Dominant competitive moves include strategic partnerships with mobile wallet providers and geographic expansion through white-label licensing.
Within the legacy operator tier, Western Union Holdings Inc. exemplifies agent network-dependent positioning, while Wise Payments Limited and Remitly Inc. represent the digital-native specialist archetype with transparent pricing and mobile-first onboarding. These three companies occupy distinct competitive positions: Western Union leverages physical infrastructure in cash-dependent corridors, Wise emphasizes mid-market foreign exchange execution, and Remitly targets migrant worker demographics in North American origin markets.
| Leading Market Players |
|---|
| Western Union Holdings Inc. |
| MoneyGram International Inc. |
| Ria Financial Services Ltd. |
| Wise Payments Limited |
| PayPal Holdings Inc. |
| Remitly Inc. |
| WorldRemit Ltd. |
| ZEPZ |
| Revolut Ltd. |
| Others |
Cost & Logistics Intelligence
Foreign exchange markup compression flows from correspondent banking concentration through to consumer-facing pricing tiers, with New York-based dollar clearing banks capturing structural margin pools that constrain downstream pricing flexibility for non-US operators. API-native fintech rails bypass these legacy intermediaries, enabling sub-1 percent pricing in high-frequency Gulf-rupee corridors while agent-dependent models sustain 4-6 percent markups in cash-pickup corridors.
Pricing Analysis
High-volume transactional corridors absorb margin compression while low-frequency corridors retain pricing power. Per-unit transactional pricing dominates, with foreign exchange markup transparency serving as the primary differentiation driver alongside settlement velocity guarantees. Pricing pressure stems from API-driven fintech entry stripping foreign exchange spreads from legacy operator models. Temporary workers exhibit highest price sensitivity, demanding minimal thresholds and zero documentation friction, while expatriate professionals accept premium pricing for hedging tools and multi-currency infrastructure.
Supply Chain Analysis
Correspondent banking relationships rest on New York clearing banks, Singapore financial infrastructure, and London-based settlement systems for cross-currency liquidity. SWIFT messaging protocols, real-time gross settlement systems, and API-driven fintech rails constitute the core operational inputs. Single-source vulnerability concentrates in dollar clearing access, exposing non-US operators to de-risking pressures and account termination. Distribution runs through agent networks in cash-dependent corridors, mobile wallet interoperability in smartphone-dense markets, and direct bank-to-bank rails under open banking frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into compliance infrastructure and last-mile disbursement networks determines competitive survival, with players racing to capture API-native rails and mobile wallet interoperability before regulatory frameworks crystallize.
For Market Incumbents: Hedge correspondent banking dependency by building direct central bank digital currency integration and mobile wallet API partnerships before CBDC pilots mature in India and UAE. Acquire licensed fintech specialists in high-frequency Gulf-South Asian corridors to offset agent network erosion. Defensive consolidation must prioritize compliance automation that reduces per-transaction overhead below fintech-native cost structures. For New Entrants and Emerging Players: Enter via white-label embedded finance partnerships with Gulf-based labor recruitment platforms and Southeast Asian payroll aggregators, capturing origination volume without building licensed money transmitter infrastructure. Student disbursement programs in Canada and Australia represent the most penetrable vertical, with lower fraud incidence and institutional procurement pathways. Go-to-market execution should prioritize university-sponsored onboarding workflows over consumer marketing spend. For Investors and Strategic Acquirers: UAE central bank digital currency pilot expansion is the leading indicator that correspondent banking disintermediation will accelerate in dirham-rupee corridors, compressing legacy operator valuations. Long-term viability favors API-first infrastructure owners with modular compliance and settlement components over agent-dependent network models. Acquisition target archetype: fintechs with white-label embedded finance deployments and direct mobile wallet interoperability in Bangladesh, Kenya, and Nigeria.| Strategic Initiative | Industry Significance |
|---|---|
| CBDC Integration Partnership | Direct central bank settlement bypasses correspondent banking concentration in Gulf-rupee corridors. |
| Mobile Wallet API Acquisition | Interoperability with bKash and MFS Africa captures last-mile disbursement in Bangladesh and Nigeria. |
| Embedded Finance White-Label Launch | Payroll platform integration enables sub-1 percent pricing in high-frequency worker corridors. |
| Compliance Infrastructure Buildout | Automated sanctions screening reduces FinCEN-mandated overhead per transaction below fintech-native levels. |
| Student Vertical Institutional Partnership | University-sponsored disbursement programs in Canada and Australia capture concentrated low-fraud volume. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with money transfer operator executives, central bank regulatory affairs leads, mobile wallet platform engineers, and labor recruitment platform operators. RBI Liberalised Remittance Scheme documentation, Bangko Sentral ng Pilipinas licensing records, and UAE central bank CBDC pilot disclosures supplemented corridor-specific volume analysis. Bottom-up transaction flow modeling triangulated against top-down macroeconomic remittance estimates across the analysis window.
Segmentation granularity operated at transfer method, sender type, receiver purpose, and service provider dimensions, with corridor-specific pricing tiers modeled separately for Gulf-rupee, Gulf-peso, and US-Mexico channels. CAGRs derived from volume trajectory analysis against smartphone penetration curves and open banking regulatory adoption timelines. CBDC pilot progression and mobile wallet interoperability expansion served as key demand-side forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under capital control tightening in Philippines or Mexico, or accelerated CBDC deployment disintermediating correspondent banking entirely. Assumptions reflect current regulatory trajectories and technology adoption curves. A small set of named triggers—RBI remittance limit adjustments, UAE CBDC live deployment, and FinCEN compliance requirement changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United Kingdom Payment Gateway Market
Payments
Japan Credit Cards Market
Payments
Contactless Payment Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Latin America Payment Gateway Market
Payments
India POS Terminals Market
Payments
Thailand Mobile Payments Market
Payments
South Korea Mobile Payment Market
Payments
Electronic Cash Register Market
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
B2B Payments Market
Payments
Germany Payment Gateway Market
Payments
Latin America Mobile Payment Market
Payments
Smart POS System Market
Payments
Social Media Payment Solution Market
Payments
Malta POS Terminal Market