
 Malaysia Payments Market | 2026-2036
Malaysia Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Payments Market Foresight
Buyer concentration among Malaysia's merchant base is shifting as micro-enterprises and street vendors fragment the acceptance landscape alongside consolidated retail chains. Touch 'n Go leverages its transit-linked ecosystem to dominate daily-use payment frequency. GrabPay anchors its position through super-app integration across ride-hailing, food delivery, and financial services. Maybank sustains institutional trust among corporate treasurers seeking secure cross-border settlement rails.
Payments encompass the electronic transfer of monetary value between transacting parties, executed through tokenized credentials, real-time gross settlement protocols, or blockchain-anchored ledgers with sub-second confirmation latency. The primary commercial purpose centers on replacing physical currency with traceable, programmable value movement that reduces counterparty risk and accelerates reconciliation cycles. E-wallet penetration among retail consumers leads transaction volume growth, while QR payments capture margin pools through low-cost merchant onboarding. Digital banking licenses issued by Bank Negara Malaysia are displacing traditional account-based dominance among tech-native freelancers and gig workers. Contactless payments at point of sale retain maturity in urban retail corridors but face saturation as NFC terminal deployment nears completion.
Bank Negara Malaysia enforces the Financial Sector Blueprint and Payment Card Reform standards that mandate real-time fund availability and cap merchant discount rates, directly compressing interchange revenue pools while expanding acceptance infrastructure. The Personal Data Protection Act and Payment Systems Act shape product architecture by requiring localized data residency and tiered customer due diligence. Stakeholders must monitor how open API mandates under the Financial Sector Blueprint redistribute competitive advantage between incumbent banks and licensed e-money issuers.
Market Dynamics
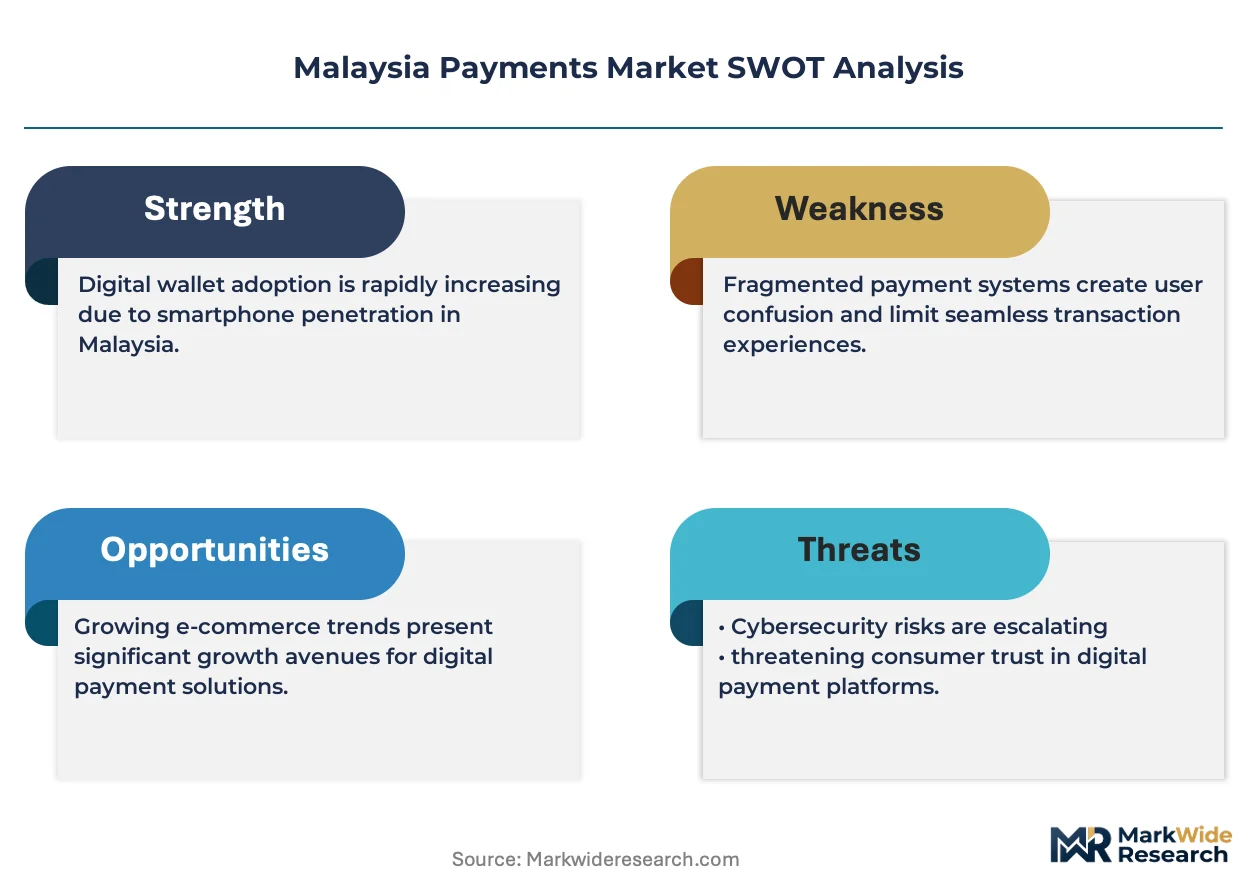
Bank Negara Malaysia's interoperability mandates and open API standards are compressing margins while forcing incumbent banks and e-money issuers into direct platform competition.
Growth Catalysts
- Financial Sector Blueprint:The central bank's mandate for real-time fund availability and standardized QR acceptance is expanding merchant onboarding velocity across street vendors and micro-enterprises.
- Transit-linked ecosystems:Daily-use payment frequency accelerates as transportation networks integrate stored-value credentials with retail acceptance networks.
- Klang Valley corridor:Merchant density and smartphone penetration peaks in Kuala Lumpur and Selangor concentrate transaction volume and infrastructure investment.
Market Restraints
- Merchant discount rate caps:Bank Negara Malaysia's Payment Card Reform compresses interchange revenue pools, squeezing issuer profitability on card-present transactions.
- Data localization requirements:The Personal Data Protection Act mandates localized data residency, raising infrastructure costs for foreign payment platforms seeking market entry.
- NFC terminal saturation:Contactless point-of-sale deployment nears completion in urban retail corridors, removing hardware upgrade cycles as a growth driver.
Strategic Opportunities
- Digital banking licenses:Bank Negara Malaysia's licensing regime creates white space for tech-native platforms to displace traditional account-based relationships among gig workers and freelancers.
- Cross-border settlement rails:Corporate treasurers seek secure ASEAN-linked payment corridors, opening institutional-grade infrastructure opportunities.
- Super-app convergence:Ride-hailing, food delivery, and financial services unbundle into integrated payment ecosystems, capturing sticky daily transaction flows.
Industry Challenges
- Legacy core banking integration:Incumbent institutions face technical debt and API fragmentation when connecting decades-old settlement systems to real-time payment rails.
- Tiered customer due diligence:The Payment Systems Act requires differentiated KYC protocols across transaction thresholds, complicating product architecture and user onboarding flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Payments Market |
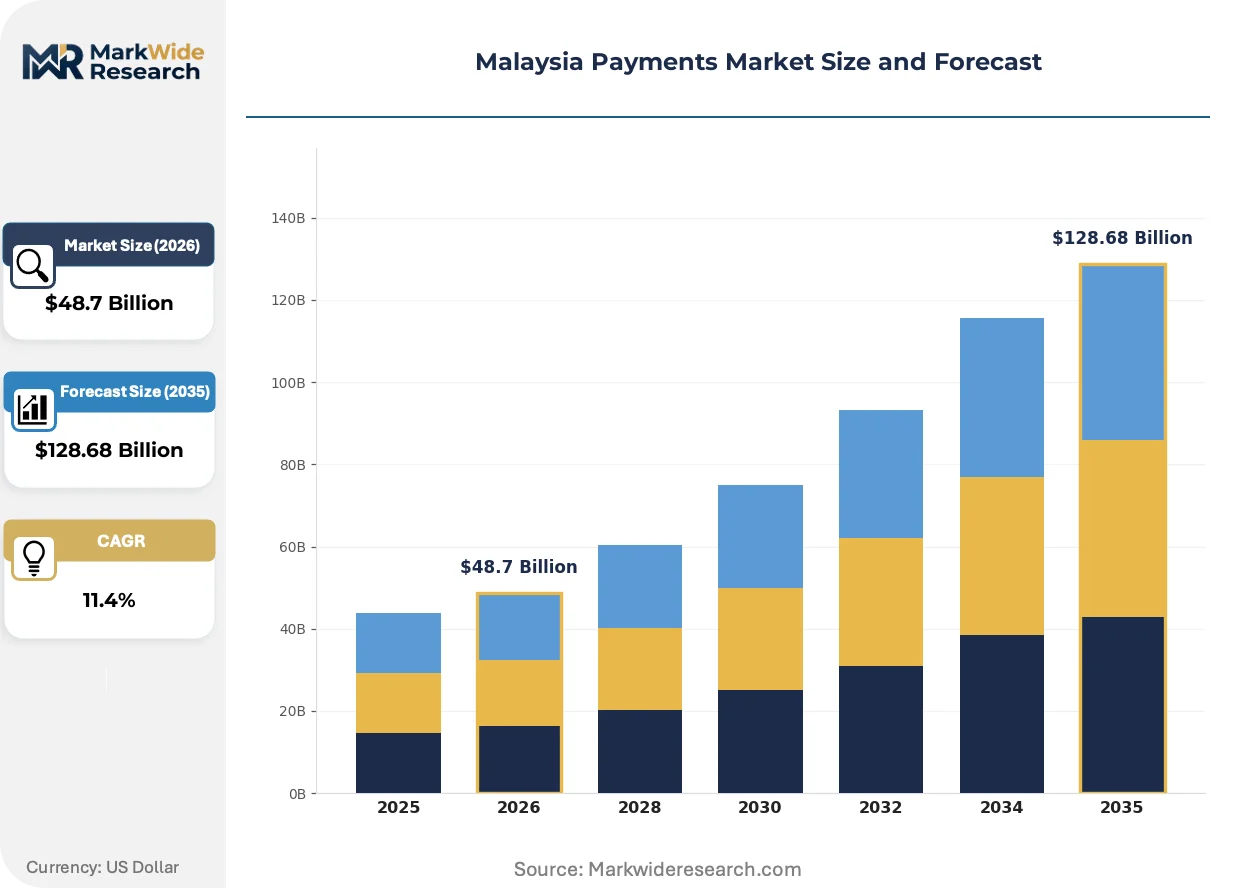
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Transaction Type: Domestic, International, Online, Point of Sale Customer Type: Retail Consumers, SMEs, Corporates, Freelancers Technology: Mobile Payments, Contactless Payments, QR Payments, Digital Banking |
| Companies Covered | Touch 'n Go, GrabPay, Boost, ShopeePay, Maybank, CIMB, Public Bank Berhad, RHB Bank, AmBank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Payments Market Shifts & Advancements
Malaysia's payment architecture is pivoting from card-centric infrastructure toward credential-agnostic, real-time settlement layers that embed financial services into non-financial platforms.
Biometric authentication is converging with tokenized credential issuance to eliminate friction at checkout. Retail merchants and transit operators are adopting palm-vein and facial recognition for sub-second verification. This convergence is compressing the traditional three-party card model into direct account-to-account rails that bypass interchange entirely.
Bank Negara Malaysia's open API mandates under the Financial Sector Blueprint are forcing standardized data exchange protocols across the banking sector. Incumbent institutions must expose customer-permissioned data to licensed third parties. E-money issuers and digital banks are capturing disintermediated relationships previously held by traditional deposit-taking institutions.
Micro-enterprise payment acceptance is fragmenting merchant acquisition strategies. Street vendors and night-market operators now demand instant settlement and zero hardware onboarding. Aggregator platforms and simplified QR solutions are displacing traditional merchant services relationships that required lengthy underwriting and terminal deployment cycles.
Malaysia Payments Market Segmentation
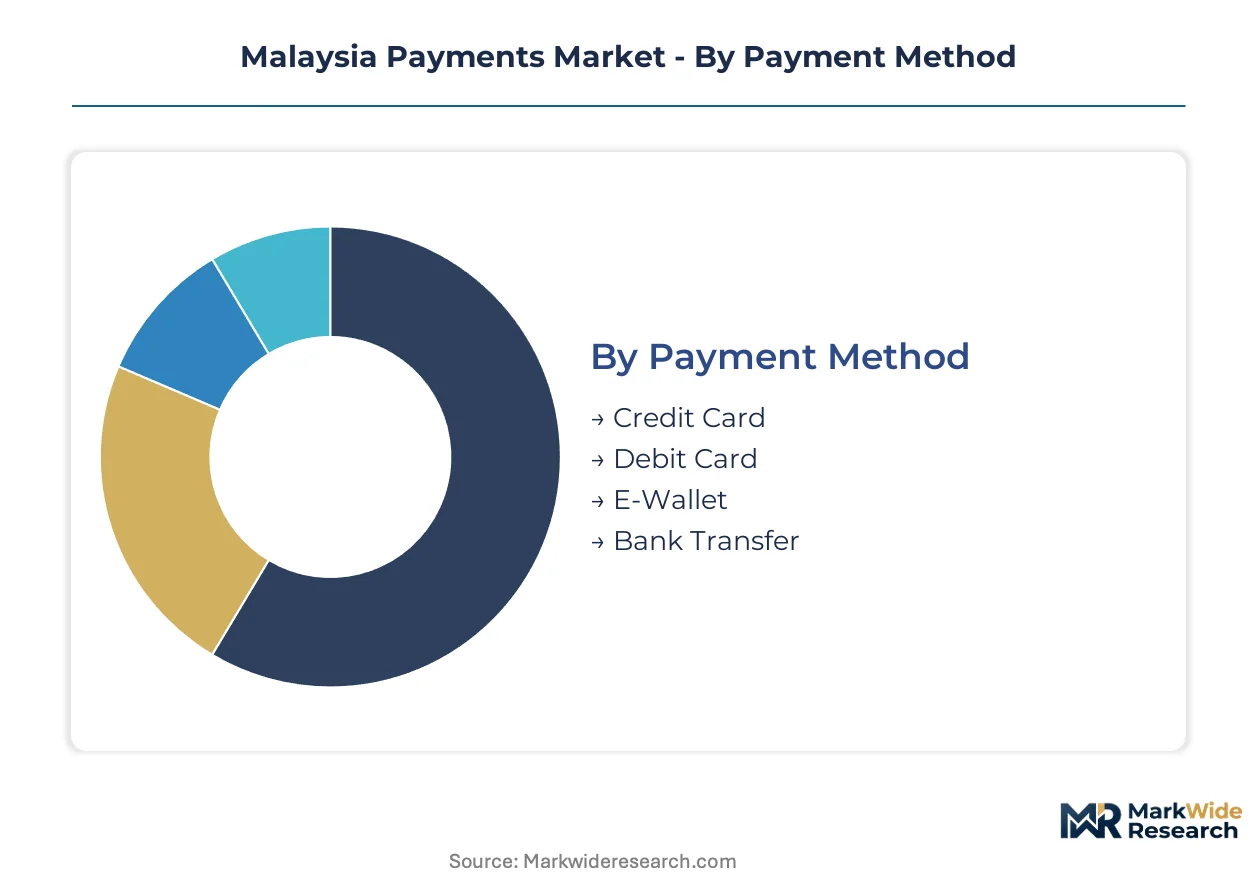
Malaysia's payments landscape fragments across four critical dimensions that determine infrastructure requirements, margin structures, and regulatory exposure. Each segmentation axis reveals distinct buyer priorities: transaction velocity for transit-linked e-wallets, settlement certainty for corporate treasuries, and onboarding friction for micro-merchants.
Payment Method:
Cost tolerance and settlement speed separate buyers across this category.
- E-Wallet:Stored-value credentials execute through tokenized mobile applications with sub-second authorization. Demand concentrates among Klang Valley retail consumers seeking transit-integrated daily payment frequency, driven by Touch 'n Go's transportation network lock-in and GrabPay's super-app ecosystem bundling.
- Credit Card:Revolving credit instruments leverage EMV chip and tokenized credential protocols for deferred settlement. Corporate card programs and affluent retail segments in Kuala Lumpur sustain volume, though Bank Negara Malaysia's merchant discount rate caps compress interchange margins and constrain issuer profitability.
- Debit Card:Direct account-linked instruments with real-time fund deduction through ATM networks and point-of-sale terminals. Maybank and CIMB dominate issuance among salary-credited retail consumers.
- Bank Transfer:Account-to-account rails through Real-Time Retail Payment Platform (RPP) and DuitNow protocols. SMEs and corporates favor this method for B2B settlement certainty and reduced counterparty exposure.
Volume sits with Credit Card legacy infrastructure; growth tilts toward E-Wallet credential proliferation among smartphone-native demographics.
Transaction Type:
Geographic scope and channel integration determine infrastructure investment priorities for acquirers.
- Point of Sale:Physical terminal-present transactions through NFC, chip, or magnetic stripe authentication. Merchant density in Selangor shopping corridors and urban retail districts sustains hardware deployment, though NFC terminal saturation removes upgrade cycle momentum.
- Online:Card-not-present and account-based e-commerce transactions through secure checkout gateways. Cross-border merchant acceptance and marketplace platform integration drive acquirer competition for checkout button placement.
- Domestic:Ringgit-denominated transactions within Malaysia's monetary jurisdiction. Bank Negara Malaysia's interoperability mandates standardize QR acceptance across domestic rails.
- International:Cross-border settlement through SWIFT, card network, or ASEAN payment corridor integration. Corporate treasurers in Kuala Lumpur seek secure multi-currency rails for regional trade settlement.
Point of Sale captures transaction frequency; Online exhibits the steepest expansion trajectory as e-commerce penetration deepens.
Customer Type:
Transaction scale and relationship complexity shape product architecture across buyer segments.
- Retail Consumers:Individual transactors executing low-value, high-frequency purchases. Smartphone penetration above ninety percent in urban Malaysia enables e-wallet and contactless adoption.
- SMEs:Small and medium enterprises requiring payment acceptance with simplified onboarding and instant settlement. Street vendors and night-market operators in Penang and Johor Bahru fragment the merchant acquisition landscape.
- Corporates:Large enterprises with treasury management needs spanning liquidity optimization and cross-border hedging. Institutional trust in incumbent banks persists for high-value settlement.
- Freelancers:Independent contractors and gig workers receiving disbursements through digital banking platforms. Bank Negara Malaysia's digital banking licenses create white space for tech-native account relationships displacing traditional deposit products.
Retail Consumers dominate transaction count; SMEs are gaining share fastest as micro-enterprise digitization accelerates.
Technology:
Hardware dependency and credential form factor determine deployment economics and user friction.
- QR Payments:Static and dynamic quick-response codes enabling merchant-present transactions without terminal infrastructure. Zero-hardware onboarding attracts street vendors and micro-merchants across night markets and hawker centers.
- Mobile Payments:Smartphone-executed transactions through application-based credential storage. Biometric authentication convergence with tokenized issuance eliminates checkout friction.
- Contactless Payments:NFC-enabled tap-to-pay through cards and wearable devices. Urban retail corridors in Kuala Lumpur achieve near-complete terminal deployment.
- Digital Banking:Licensed deposit-taking and payment services through native-digital platforms without branch infrastructure. Freelancers and gig workers displace traditional account relationships.
Contactless Payments retain maturity concentration; QR Payments climb the fastest as simplified onboarding penetrates micro-merchant segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's payment demand clusters disproportionately within the Klang Valley corridor, where merchant density and smartphone penetration create transaction volume gravity that outstrips secondary urban centers by significant multiples.
Klang Valley
Kuala Lumpur and Selangor generate the majority of Malaysia's digital transaction throughput through concentrated retail corridors and transit-integrated payment ecosystems. Bank Negara Malaysia's interoperability mandates standardize QR acceptance across this metropolitan cluster. Bukit Bintang shopping districts and KL Sentral transit hubs anchor merchant acquisition velocity for e-wallet providers.
Penang
Georgetown's UNESCO heritage tourism economy drives contactless payment adoption among hospitality merchants and street food vendors. The state's tech manufacturing base generates corporate treasury demand for cross-border settlement infrastructure. Bayan Lepas industrial zones sustain B2B payment digitization among electronics exporters.
Johor Bahru
Cross-border commerce with Singapore accelerates real-time payment rail development for retail and remittance flows. Iskandar Malaysia's special economic zone status attracts fintech infrastructure investment. City Square and Komtar JB shopping complexes concentrate merchant terminal deployment.
Sarawak
Kuching's emerging digital banking adoption lags Peninsular Malaysia but accelerates through mobile-first financial inclusion programs. The state's rural geography favors simplified QR onboarding over terminal-dependent infrastructure. Petronas-linked energy payments drive corporate banking digitization in Miri.
Malaysia Payments Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue super-app convergence and transit-linked ecosystem dominance. The market structures around three distinct player tiers: incumbent banks with institutional trust, e-money issuers with daily-use frequency, and platform-native wallets with merchant network effects. Strategic archetypes include transit-integrated credential providers, ride-hailing anchored super-apps, and traditional deposit-taking institutions. Competitive moves concentrate on API interoperability compliance and micro-merchant acquisition velocity.
Within the e-money tier, Touch 'n Go and GrabPay exemplify divergent ecosystem anchoring strategies—transit infrastructure versus super-app bundling. Maybank represents the incumbent banking archetype sustaining corporate treasury relationships. These three entities occupy positions that illustrate how Bank Negara Malaysia's open API mandates redistribute competitive advantage between legacy institutions and licensed digital platforms.
| Leading Market Players |
|---|
| Touch 'n Go |
| GrabPay |
| Boost |
| ShopeePay |
| Maybank |
| CIMB |
| Public Bank Berhad |
| RHB Bank |
| AmBank |
| Others |
Supply & Pricing Matrix
Sovereign wealth-backed infrastructure investors and private-equity rolled-up merchant acquirers now dominate Malaysia's payment processing layer, concentrating pricing power among platforms with captive transit networks and super-app ecosystems while compressing margins for independent terminal deployers.
Pricing Analysis
Volume concentrates in low-margin QR rails while premium pricing persists in cross-border corporate settlement. Three-tier pricing structure across premium, standard, and economy levels separates institutional treasury services from SME aggregator platforms and micro-merchant zero-hardware onboarding. Cost compression in domestic card-present transactions is intensifying because Bank Negara Malaysia's merchant discount rate caps squeeze interchange pools. SMEs exhibit highest price sensitivity, while corporate treasurers prioritize settlement certainty over transaction cost.
Supply Chain Analysis
Regional distribution centers in Singapore, Hong Kong, and Shenzhen anchor hardware terminal procurement for Malaysian acquirers. Chip modules and NFC antennae draw from Taiwan and South Korea fabrication facilities. Single-source vulnerability in EMV chip supply creates exposure to geopolitical logistics chokepoints. Distribution runs through hub-and-spoke patterns with Kuala Lumpur as the central node for terminal deployment and Klang Valley as the primary consumption cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bank Negara Malaysia's Financial Sector Blueprint functions as a cost-of-compliance moat, elevating capital requirements and API standardization burdens that filter out undercapitalized entrants while rewarding licensed institutions with regulatory endorsement.
For Market Incumbents: Lock in merchant acquisition velocity through zero-hardware QR onboarding before terminal-dependent competitors recover. Prioritize API interoperability certification to maintain data access privileges under open banking mandates. Vertical integration into real-time settlement rails defends against e-wallet disintermediation of core deposit relationships. For New Entrants and Emerging Players: Embedded finance partnerships with ride-hailing and food delivery platforms offer the lowest-friction entry path. Sarawak and secondary Peninsular corridors present underpenetrated white space where simplified KYC protocols reduce onboarding friction. Target gig worker disbursement flows as the anchor use case for digital banking license applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed merchant acquirer portfolios in Johor Bahru where Singapore cross-border commerce sustains transaction volume. Long-term viability hinges on regulatory license scarcity rather than technology differentiation. Watch Bank Negara Malaysia's digital banking license renewal schedule as the primary inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Certification | Bank Negara Malaysia's open API mandates force standardized data exchange that determines competitive access. |
| Transit Network Integration | Touch 'n Go's transportation credential lock-in creates daily-use payment frequency that rivals cannot replicate. |
| Micro-Merchant QR Onboarding | Zero-hardware deployment captures street vendor volume that terminal-dependent acquirers cannot economically serve. |
| Cross-Border Settlement Infrastructure | ASEAN-linked rails address corporate treasurer demand for secure multi-currency B2B payment corridors. |
| Digital Banking License Acquisition | Licensed deposit-taking privileges displace traditional account relationships among tech-native freelancers. |
Research Methodology
Independent corroboration across payment platform executives, merchant acquisition directors, and Bank Negara Malaysia regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from central bank policy circulars, Financial Sector Blueprint implementation schedules, and DuitNow transaction volume disclosures. Bottom-up triangulation across e-wallet issuer metrics and top-down reconciliation against national payment system aggregates anchors the sizing framework.
Comparable historical periods spanning pre-pandemic baseline, accelerated digitization phase, and interoperability mandate implementation anchor the forecast window. Segmentation models incorporate payment method, transaction type, customer archetype, and technology form factor dimensions across the projection horizon. CAGRs derive from regression analysis against smartphone penetration curves, merchant onboarding velocity, and regulatory enforcement intensity.
The model holds under continued Bank Negara Malaysia policy enforcement and stable ASEAN trade corridors; deviation in license moratoriums or cross-border remittance restrictions would shift trajectory. Forecasts reflect stated assumptions regarding infrastructure deployment timelines and merchant behavior adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
GCC Payment Gateway Market
Payments
Direct Carrier Billing Platform Market
Payments
Cross-Border Payment Platform Market
Payments
Electronic Payment Processing Software Market
Payments
Contactless Payment Market
Payments
Uganda Mobile Money Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Africa Virtual Cards Market
Payments
Smart Payment Market
Payments
Cryptocurrency Payment Apps Market
Payments
Europe Fuel Cards Market
Payments
Belgium Payments Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
United States Real Time Payments Market
Payments
Europe Digital Transaction Management (DTM) Market