
 Buy Now Pay Later Market | 2026-2036
Buy Now Pay Later Market Size, Share, and Industry Trends Forecast 2026-2036
Buy Now Pay Later Market Analysis
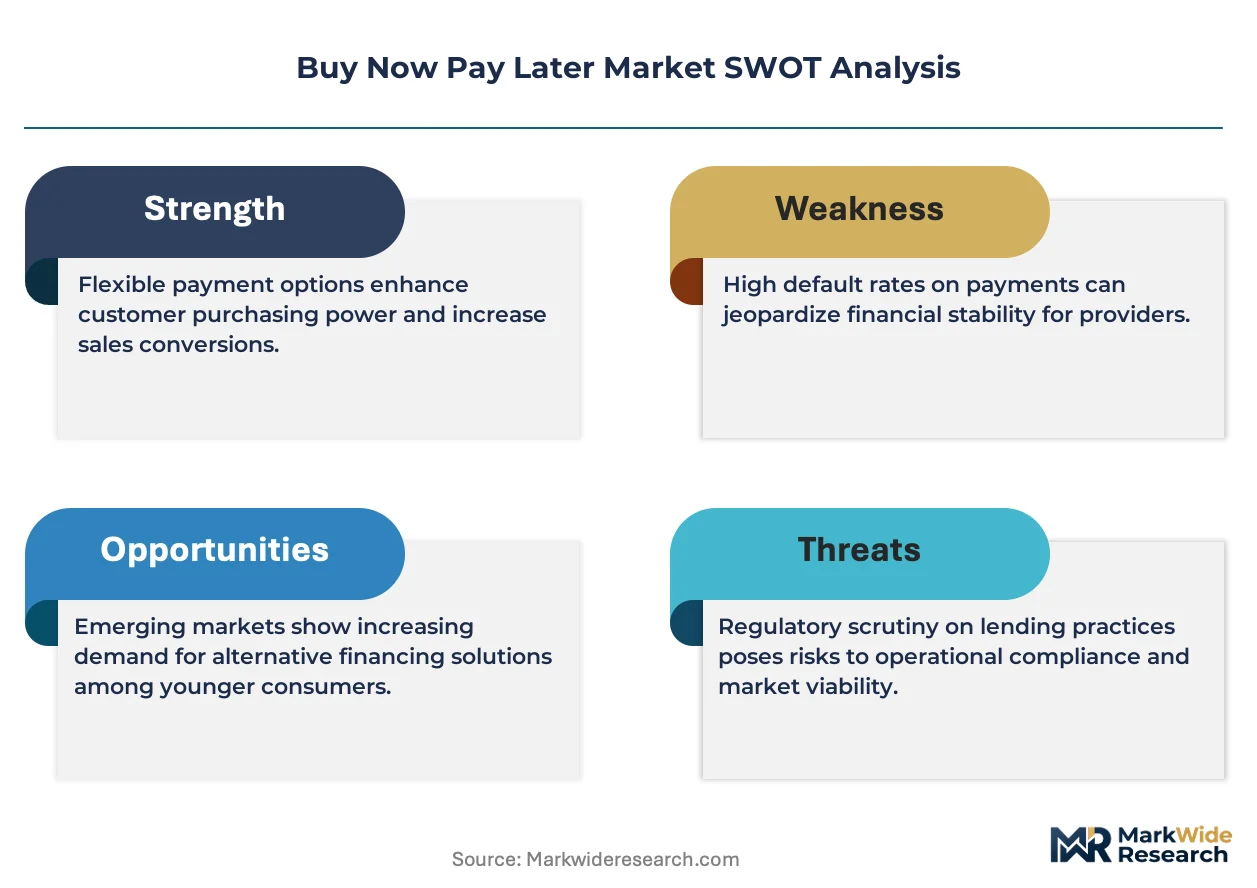
The EU AI Act is shifting how European BNPL providers deploy algorithmic underwriting models, forcing recalibration of automated credit scoring systems. Klarna AB leverages its banking license to sustain lower funding costs across Nordic and German markets. Affirm Holdings Inc. anchors its position through direct merchant integrations with large-ticket retailers. Afterpay Ltd (Block Inc.) competes by embedding its pay-in-four product within Cash App's existing user base.
Buy now pay later denotes a short-term installment lending product that splits retail purchases into equal payments, typically four biweekly amounts, with merchant-funded interchange fees replacing traditional interest revenue. The model relies on real-time API connections to bank accounts, soft credit checks, and proprietary risk engines assessing transaction-level rather than bureau-centric data. E-commerce channels dominate transaction flow due to checkout-embedded APIs that reduce cart abandonment, while Gen Z cohorts represent the fastest-growing customer segment as thin-file borrowers bypass conventional credit cards. Small-ticket transactions constitute the volume base, though large-ticket verticals such as travel and healthcare generate disproportionate margin contribution per transaction.
The Consumer Financial Protection Bureau in the United States, the Financial Conduct Authority in the United Kingdom, and ASIC in Australia each impose distinct disclosure and affordability verification requirements that fragment compliance architecture across operating geographies. The EU's forthcoming Consumer Credit Directive revision will extend APR disclosure obligations to zero-interest BNPL products, compressing merchant fee structures. Stakeholders must monitor regulatory divergence between disclosure-light and full-fitness regimes to determine geographic prioritization and product standardization investments.
Market Dynamics
Embedded finance APIs are collapsing the traditional boundaries between retail checkout and credit origination, forcing BNPL providers to compete on latency and merchant integration depth rather than standalone brand recognition. This infrastructure shift rewards platforms with direct banking licenses and penalizes thinly capitalized intermediaries.
Growth Catalysts
- EU AI Act compliance frameworks:Algorithmic transparency mandates are accelerating consolidation among providers capable of explainable credit scoring, filtering out undercapitalized entrants.
- Healthcare vertical penetration:Elective medical procedures and dental services are adopting BNPL at checkout, converting uninsured out-of-pocket expenses into installment workflows.
- Real-time payment rails:Open banking infrastructure in Australia and the United Kingdom enables instant income verification, reducing default rates and funding costs.
Market Restraints
- Wholesale funding concentration:Securitization markets for consumer installment debt remain shallow outside the United States, elevating refinancing risk for European and Asia-Pacific operators.
- Interchange fee compression:Merchant-funded revenue models face pressure from large retailers negotiating direct bilateral agreements, squeezing per-transaction economics.
- Bureau data fragmentation:Thin-file borrowers lack centralized credit histories in emerging markets, forcing reliance on costly alternative data partnerships.
Strategic Opportunities
- Brazilian regulatory sandbox:The country's central bank is licensing non-bank installment lenders, creating first-mover advantages for platforms with existing Latin American merchant relationships.
- Travel sector recovery:Airlines and online travel agencies are embedding BNPL for high-aspiration purchases, capturing margin from deferred payment premiums.
- Payroll-integrated lending:Employer-sponsored earned wage access platforms are converging with retail BNPL, enabling repayment through salary deduction.
Industry Challenges
- Affordability assessment talent:Regulatory scrutiny of automated underwriting is outstripping the supply of data scientists trained in fair-lending compliance.
- Legacy core banking integration:Partnerships with chartered banks require months-long API harmonization, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buy Now Pay Later Market |
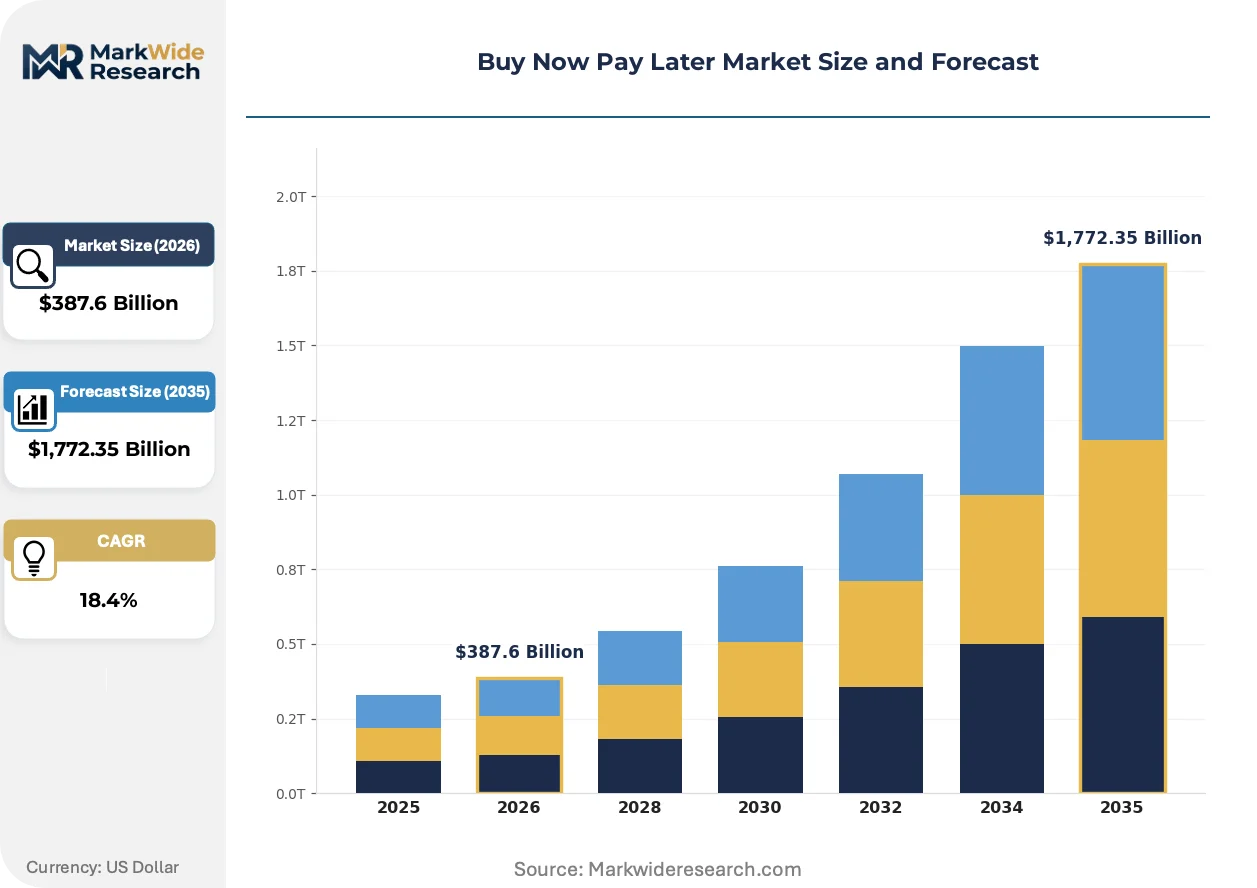
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,772.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Bank Transfer, Digital Wallet, Debit Card Customer Type: Millennials, Gen Z, Young Professionals, Parents Retail Sector: E-Commerce, Retail Stores, Travel Services, Health & Beauty Transaction Size: Small Tickets, Medium Tickets, Large Tickets, Subscription Payments |
| Companies Covered | PayPal Holdings Inc., Afterpay Ltd (Block Inc.), Affirm Holdings Inc., Klarna AB, Zip Co Ltd, Sezzle Inc., Splitit Payments Ltd, Openpay Group Ltd, Tabby FZ-LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buy Now Pay Later Market Emerging Trajectories
Real-time transaction data is displacing static credit scores as the primary underwriting input, enabling dynamic limit adjustments that respond to income volatility rather than historical delinquency patterns.
Machine-learning risk engines is expanding into employment verification by analyzing deposit patterns and gig-platform payment flows. Thin-file Gen Z borrowers in the United States and United Kingdom are adopting these models fastest, bypassing traditional card applications. The technology is compressing approval times from minutes to seconds, eliminating cart abandonment at merchant checkout.
The EU AI Act's algorithmic impact assessment requirements are forcing BNPL providers to document credit decision logic and audit for discriminatory outcomes. Providers serving French and German markets must maintain technical documentation and human oversight protocols. Small-ticket, high-volume operators face disproportionate compliance costs relative to their revenue base.
Merchant self-provision of installment credit is displacing third-party BNPL platforms at large retail chains. Department stores and electronics retailers in Australia are building proprietary pay-in-four products, retaining customer data and fee revenue. This vertical integration is most advanced where merchant scale justifies dedicated technology investment.
Buy Now Pay Later Market Segmentation
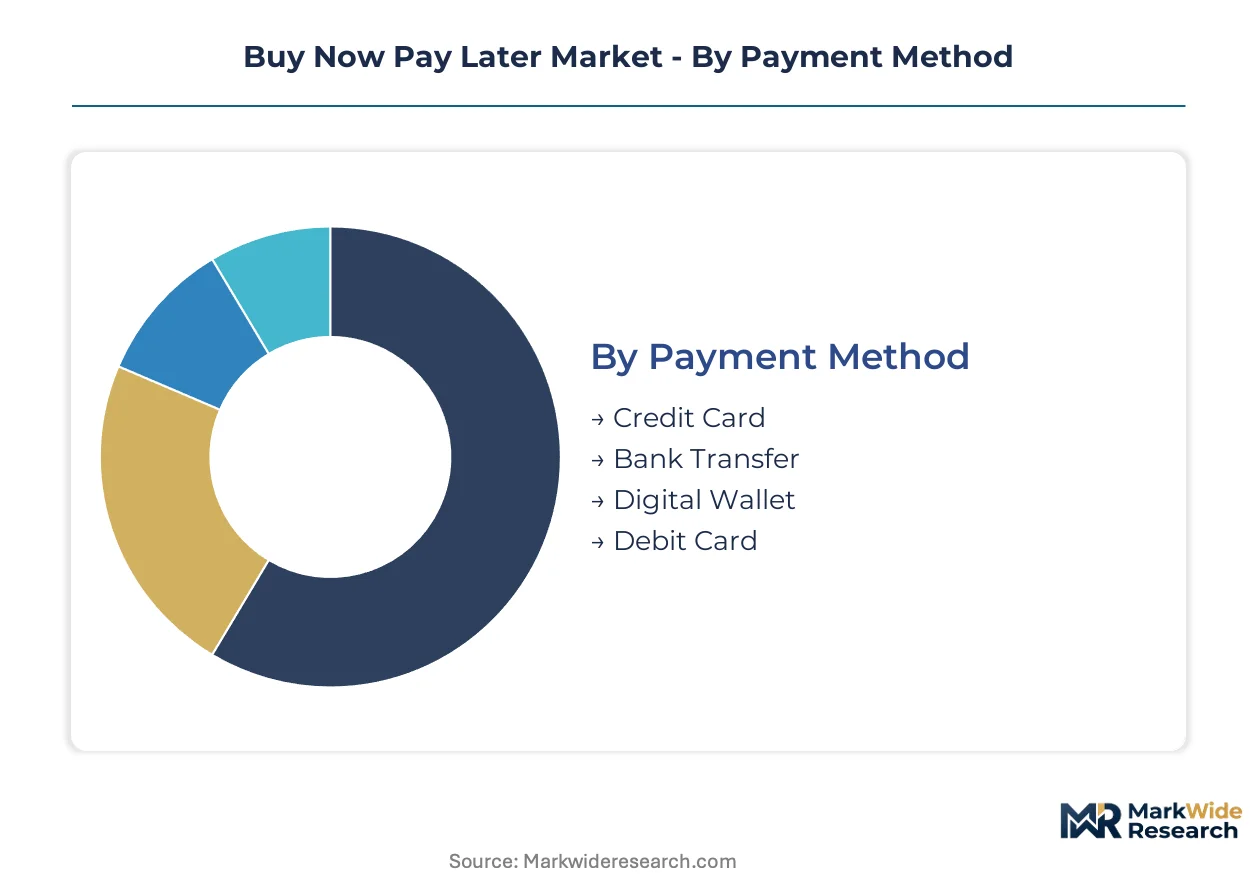
BNPL providers configure their underwriting engines, merchant fee structures, and repayment schedules around distinct payment rails, demographic cohorts, and purchase contexts. Segmentation discipline separates thin-margin mass-market operators from specialists capturing premium economics in high-aspiration verticals.
Payment Method:
Standardization dominates credit card and debit card rails, while digital wallets and open banking transfers enable customization of repayment timing and funding sources.
- Credit Card:Traditional revolving credit products compete directly with BNPL at checkout, with issuers now embedding installment features natively. Demand concentrates in the United States where credit card interchange economics fund merchant subsidies. Regulatory scrutiny from the Consumer Financial Protection Bureau on retroactive interest charges constrains product design flexibility.
- Digital Wallet:Mobile-first platforms integrate BNPL as a default payment option, leveraging stored credentials and biometric authentication. Expansion is steepest in Australia where real-time payment rails enable instant settlement. The Reserve Bank of Australia's open banking mandates reduce friction for income verification.
- Bank Transfer:Direct account-to-account payments bypass card networks entirely, lowering merchant acceptance costs. Adoption tracks open banking maturity in the United Kingdom and Germany.
- Debit Card:Pull-based repayment from checking accounts reduces default risk for thin-file borrowers. Gen Z cohorts in the United States favor this method for budget control.
Most installed capacity flows through Credit Card. Expansion is steepest in Digital Wallet.
Customer Type:
Acquisition cost and lifetime value diverge sharply across generational cohorts, with employment status and household composition dictating credit limit algorithms.
- Gen Z:First-time credit seekers with thin bureau files drive demand for alternative data underwriting. Concentration is highest in the United Kingdom where open banking enables employment verification through deposit pattern analysis. The Financial Conduct Authority's affordability rules limit credit exposure for borrowers under 21.
- Young Professionals:Salaried workers with volatile cash flows use BNPL to smooth lumpy expenses. Travel and electronics purchases dominate this segment in Australia.
- Millennials:Established earners with existing credit relationships compare BNPL against rewards cards for large-ticket items. Parents in this cohort favor installment plans for back-to-school and holiday spending.
- Parents:Household budget managers prioritize predictable repayment schedules over revolving credit flexibility. Health and beauty verticals capture disproportionate share.
Gen Z is gaining share fastest. Young Professionals contribute the highest revenue per user.
Retail Sector:
Channel integration depth and merchant scale determine whether providers capture checkout economics or cede ground to proprietary solutions.
- E-Commerce:API-embedded checkout experiences reduce cart abandonment through single-click enrollment. Volume concentrates in the United States where platform consolidation enables standardized integration kits. The sector faces margin pressure from large marketplace operators negotiating direct bilateral agreements.
- Travel Services:Airlines and online travel agencies embed BNPL for high-aspiration purchases with deferred departure dates. Expansion is steepest in Australia as international route recovery accelerates. Regulatory capital requirements for advance payment protection influence provider selection.
- Retail Stores:In-person POS financing relies on QR codes and tap-to-pay integration at staffed checkout lanes. Department stores in the United Kingdom are building proprietary solutions.
- Health & Beauty:Elective procedures and cosmetic services convert uninsured out-of-pocket expenses into installment workflows. Dental and vision verticals show particular traction.
E-Commerce processes the highest transaction volume. Travel Services is climbing the fastest.
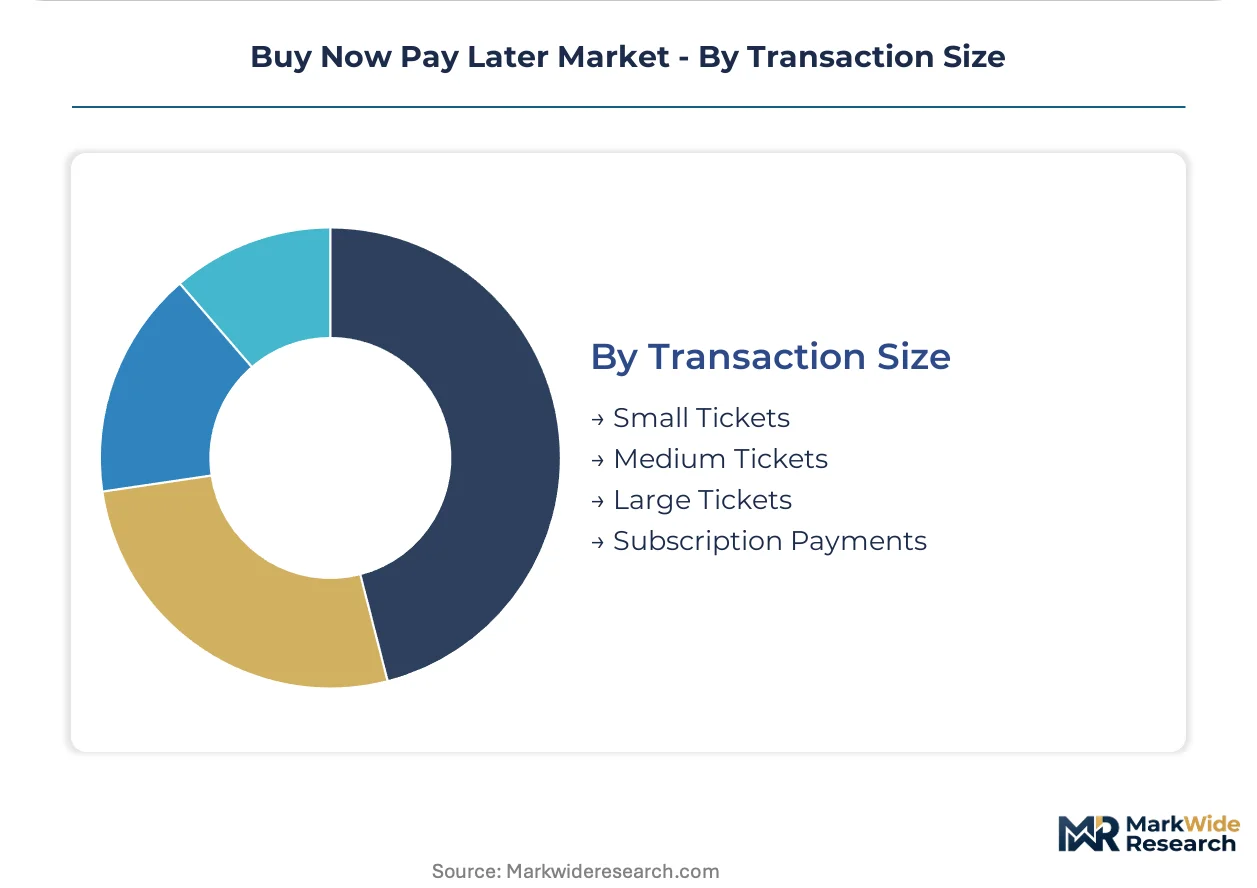
Transaction Size:
Unit economics and default risk profiles vary nonlinearly with ticket size, forcing providers to segment underwriting models and merchant fee schedules.
- Small Tickets:Sub-hundred-dollar purchases constitute volume base with merchant-funded interchange fees replacing interest revenue. Concentration is highest in the United States where app-based repeat usage drives engagement metrics. Regulatory disclosure exemptions for low-value credit reduce compliance overhead.
- Large Tickets:Thousand-plus-dollar purchases in furniture, electronics, and healthcare generate disproportionate margin contribution per transaction. Expansion is steepest in the United Kingdom where elective medical procedures adopt BNPL at point of care. The EU's forthcoming Consumer Credit Directive revision will extend APR disclosure obligations, compressing fee structures.
- Medium Tickets:Mid-range apparel and appliance purchases balance approval velocity with fraud prevention. Seasonal demand spikes strain capital allocation.
- Subscription Payments:Recurring installment plans for SaaS and membership services convert annual contracts into monthly cash flows. Churn management requires distinct retention algorithms.
Small Tickets anchor transaction volume. Large Tickets is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data science talent clusters in London, San Francisco, and Stockholm anchor algorithmic underwriting development for BNPL platforms. Regulatory divergence across jurisdictions fragments compliance architecture and shapes geographic prioritization decisions.
United States
Young professionals in Austin and Miami drive demand for travel and electronics installment plans. The Consumer Financial Protection Bureau enforces disclosure requirements for zero-interest products. Silicon Valley hosts the densest concentration of machine-learning risk engineering teams.
United Kingdom
Gen Z borrowers in London and Manchester adopt pay-in-four products for fashion and beauty purchases. The Financial Conduct Authority mandates affordability verification through open banking. Edinburgh's fintech cluster specializes in real-time income verification APIs.
Germany
Young professionals in Berlin and Hamburg use BNPL for furniture and electronics. The EU AI Act requires algorithmic impact assessments for automated credit decisions. Munich hosts engineering teams developing explainable underwriting models.
Australia
Travel sector recovery in Sydney and Melbourne accelerates large-ticket BNPL adoption. The Reserve Bank of Australia's open banking mandates reduce friction for instant settlement. Melbourne's fintech corridor concentrates merchant integration specialists.
Brazil
Thin-file borrowers in São Paulo and Rio de Janeiro bypass traditional credit cards for retail installment plans. The central bank's regulatory sandbox licenses non-bank installment lenders. São Paulo's financial district anchors Latin American expansion headquarters.
Buy Now Pay Later Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the BNPL value chain. Banking license holders fund balance sheets at lower cost than securitization-dependent intermediaries. Three archetypes dominate: licensed banks with captive funding, technology platforms with merchant network effects, and specialized installment lenders with vertical focus. Consolidation accelerates through M&A and direct banking license acquisitions.
Within the banking-licensed tier, Klarna AB and PayPal Holdings Inc. occupy positions that exemplify divergent funding strategies. Klarna AB leverages its European banking authorization to sustain compressed cost of capital across Nordic and German markets. PayPal Holdings Inc. anchors a position through embedded checkout infrastructure and existing merchant relationships. Afterpay Ltd (Block Inc.) represents the platform-network archetype, embedding installment products within broader consumer finance ecosystems.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Afterpay Ltd (Block Inc.) |
| Affirm Holdings Inc. |
| Klarna AB |
| Zip Co Ltd |
| Sezzle Inc. |
| Splitit Payments Ltd |
| Openpay Group Ltd |
| Tabby FZ-LLC |
| Others |
Supply Flow & Price Mechanics
Machine-learning risk engineering talent clustering in San Francisco and London drives labor-cost differentials that widen pricing-tier spreads between premium algorithmic underwriting providers and commoditized checkout-embedded offerings.
Pricing Analysis
Merchant-funded interchange fee structures dominate revenue capture, with pricing stratifying across premium licensed-bank tiers, standard platform-intermediary tiers, and economy thin-capitalized fintech tiers. Price differentiation hinges on funding cost advantages from banking licenses and real-time payment rail access. Cost compression in the economy tier intensifies as large retailers negotiate direct bilateral agreements bypassing platform markups. Small merchants remain most price-sensitive, while enterprise retailers with dedicated technology budgets exhibit lowest fee elasticity.
Supply Chain Analysis
Returns and refund processing flows create reverse-logistics complexity as BNPL providers manage merchant chargeback exposure and consumer dispute resolution across distributed transaction networks. Capital concentration sits in the United States, United Kingdom, and Australia where securitization markets for consumer installment debt reach adequate depth. Funding draws from wholesale credit lines, securitized receivables pools, and deposit-backed banking balance sheets. Single-source vulnerability concentrates in shallow European securitization markets outside core jurisdictions. Distribution runs through API-embedded checkout integrations at e-commerce platforms and in-person POS terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on algorithmic underwriting efficiency gains and premium-tier migration toward healthcare and travel verticals with superior per-transaction economics.
For Market Incumbents: Extend banking license coverage into additional European jurisdictions before EU AI Act compliance costs harden competitive moats. Acquire specialized income-verification API providers in Australia and the United Kingdom to deepen open banking integration. Consolidate merchant relationships through exclusive large-ticket vertical partnerships in travel and elective medical services. For New Entrants and Emerging Players: Launch via employer-sponsored earned wage access platforms converging with retail BNPL through payroll deduction repayment rails. Target Brazilian regulatory sandbox licensing for first-mover positioning in Latin American installment lending. White-space concentration sits in healthcare point-of-care financing for uninsured out-of-pocket expenses. For Investors and Strategic Acquirers: Banking license holders with proprietary risk engines are the most active acquirer in this space, consolidating thinly capitalized intermediaries facing EU AI Act compliance burdens. Long-term viability favors platforms with direct funding access and vertical specialization in high-aspiration purchase categories. Monitor regulatory divergence between disclosure-light and full-fitness regimes as inflection indicator for geographic portfolio reweighting.| Strategic Initiative | Industry Significance |
|---|---|
| Banking License Acquisition | Compresses funding costs below securitization-dependent competitors in European markets. |
| Healthcare Vertical Integration | Captures premium economics from elective medical procedures at point-of-care checkout. |
| Open Banking API Development | Enables real-time income verification through Reserve Bank of Australia mandated data sharing. |
| Merchant Self-Provision Deflection | Retains large retail relationships against proprietary installment product displacement. |
| Algorithmic Explainability Investment | Satisfies EU AI Act documentation requirements for automated credit decision audit trails. |
Methodological Framework
Bottom-up merchant integration modeling reconciled against top-down funding source tracking forms the analytical core of this study. Primary interviews with chief risk officers, merchant partnership leads, open banking infrastructure providers, and regulatory compliance directors combined with secondary validation from central bank regulatory filings, securitization prospectuses, and open banking adoption statistics. Triangulation across stakeholder perspectives and data sources ensures segment-level precision.
Input-output matrices map transaction volume flows across payment rails, customer cohorts, retail sectors, and transaction size tiers throughout the forecast period. Segmentation dimensions modeled include payment method, generational cohort, retail channel, and ticket size bracket. CAGRs derive from regression analysis of merchant adoption curves and funding cost trajectories. Industry-specific forecast inputs incorporate EU AI Act implementation timelines and open banking penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration scenarios or securitization market dislocation. Practitioners should monitor central bank sandbox licensing announcements and merchant bilateral agreement disclosures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Japan Virtual Cards Market
Payments
Ghana Mobile Money Market
Payments
Gift Card and Incentive Card Market
Payments
Crypto Payment Gateway Market
Payments
China Virtual Cards Market
Payments
EMV Card Market
Payments
Indonesia Mobile Payments Market
Payments
South Korea Mobile Payment Market
Payments
Electronic Payment Processing Software Market
Payments
Digital Debit Market
Payments
Telecom Cloud Billing Market
Payments
LAMEA Payment Gateway Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Southeast Asia POS Terminal Market
Payments
Mexico Digital Wallet Market
Payments
Europe Accounts Payable Automation Market