
 Clearing Houses and Settlements Market | 2026-2036
Clearing Houses and Settlements Market Size, Share, and Industry Trends Forecast 2026-2036
Clearing Houses and Settlements Market Analysis
Institutional-grade clearing infrastructure is rotating toward real-time risk monitoring and sub-second settlement finality. DTCC sustains its dominance through captive connectivity to US broker-dealers and asset managers. LCH Group differentiates via multi-asset class coverage across interest rate swaps and commodities. JP Morgan Clearing Corp leverages its balance sheet depth to anchor prime brokerage clearing relationships.
Clearing houses and settlements are financial intermediaries that guarantee trade completion by assuming counterparty risk, maintaining margin deposits, and enforcing delivery-versus-payment protocols with T+1 or T+0 settlement cycles. Their primary commercial purpose is to eliminate settlement failure and systemic contagion across capital markets. Payment processing and risk management command the deepest margin pools as regulatory capital requirements intensify. Blockchain and distributed ledger segments are expanding fastest as custodians pilot atomic settlement, though centralized systems still process the vast majority of transaction value due to proven throughput and recovery protocols.
US regulators including the SEC, CFTC, and OCC enforce margin segregation and default waterfall standards that directly determine infrastructure investment priorities. EU frameworks such as EMIR and CSDR mandate interoperability and shorter settlement cycles, forcing cross-border operators to maintain dual-compliance architectures. Stakeholders must weigh the capital efficiency of distributed ledger pilots against the operational resilience of proven centralized rails when allocating technology budgets.
Market Dynamics
Real-time gross settlement mandates from EU regulators are compressing settlement cycles from T+2 toward T+0, forcing clearing houses to rebuild core infrastructure for sub-second finality while maintaining systemic resilience.
Growth Catalysts
- EMIR Refit mandates:European Market Infrastructure Regulation amendments require enhanced interoperability between central counterparties, driving infrastructure consolidation investments across Frankfurt, Paris, and London clearing nodes.
- Tokenized securities pilots:Custodians and asset managers are testing atomic settlement on distributed ledger rails, creating demand for hybrid clearing architectures that bridge traditional and digital asset workflows.
- Derivatives volume concentration:Interest rate swap clearing continues migrating toward regulated CCPs as buy-side firms unwind bilateral arrangements to reduce capital charges under Basel III.
Market Restraints
- Regulatory capital intensity:Default fund contributions and liquidity requirements under CFTC and EMIR rules consume balance sheet capacity, constraining smaller clearing members from expanding into multi-asset coverage.
- Technical throughput ceilings:Legacy mainframe architectures at established clearing houses face hard scaling limits when processing real-time margin calculations across correlated portfolios.
- Geographic licensing fragmentation:National regulators in Singapore, Hong Kong, and Switzerland maintain divergent recognition frameworks, fragmenting cross-border clearing access for global asset managers.
Strategic Opportunities
- Carbon derivatives clearing:Compliance-grade emissions futures and voluntary carbon credit contracts represent underdeveloped asset classes where specialized CCPs can establish first-mover positioning ahead of regulatory standardization.
- Private fund servicing:Private equity and hedge fund administrators seek integrated post-trade utilities that combine fund accounting, custody, and settlement on unified platforms.
- AI-driven risk surveillance:Machine learning models for intraday liquidity stress testing can differentiate clearing infrastructure by reducing margin buffer requirements for qualifying members.
Industry Challenges
- Distributed systems talent scarcity:Blockchain protocol engineering and smart contract auditing skills remain concentrated among fintech specialists, complicating legacy institution recruitment for DLT integration programs.
- Interoperability testing complexity:Linking proprietary risk engines across CCPs for portfolio margining requires multi-year certification cycles that delay revenue capture from cross-margining services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clearing Houses and Settlements Market |
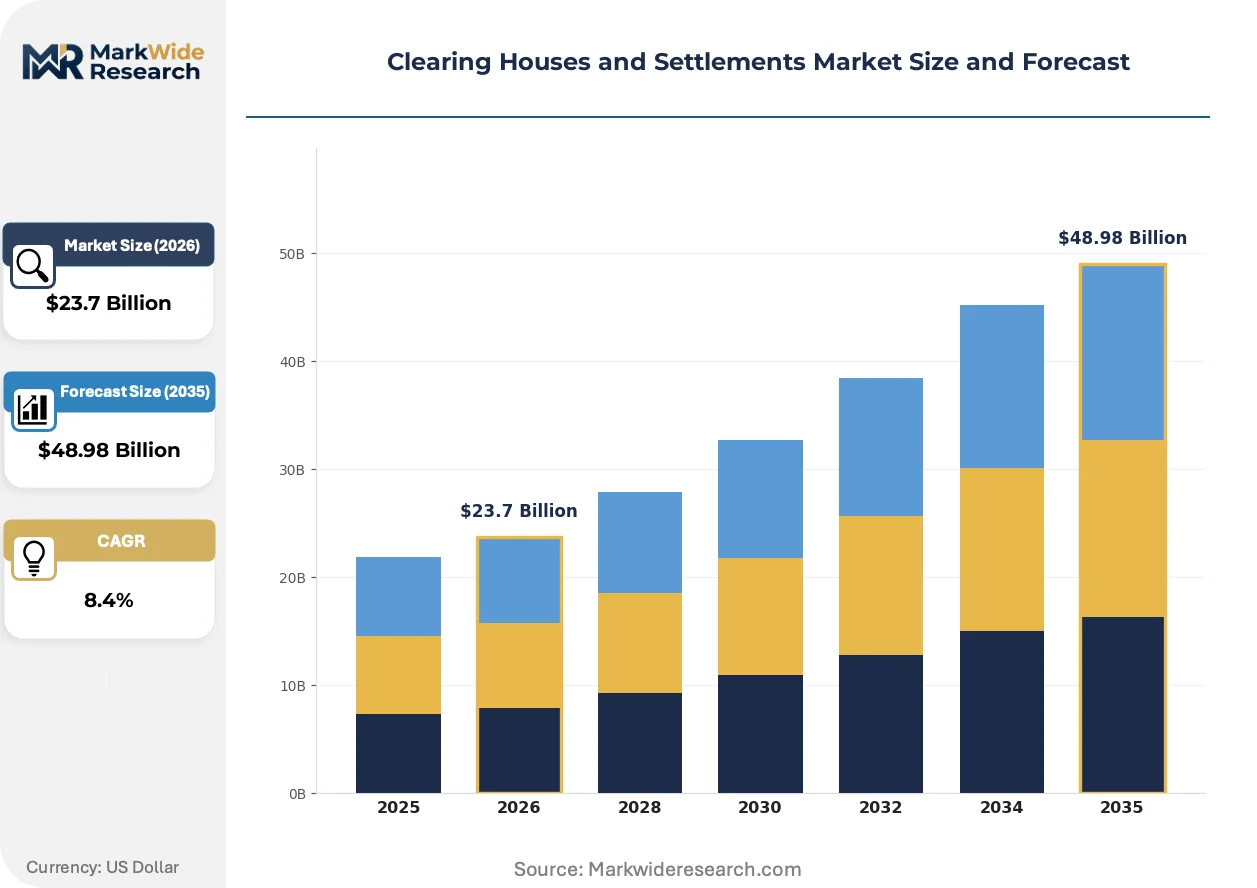
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Reconciliation Services, Risk Management, Trade Confirmation Technology: Blockchain, Centralized Systems, Distributed Ledger, Automated Clearing Transaction Type: Equity Settlements, Commodity Settlements, Foreign Exchange, Derivative Settlements Client Type: Banks, Brokers, Asset Managers, Hedge Funds |
| Companies Covered | DTCC (Depository Trust Clearing Corporation), Bank of America Merrill Lynch, JP Morgan Clearing Corp, Goldman Sachs Execution and Clearing LP, LCH Group, Eurex Clearing, Apex Clearing, National Securities Clearing Corporation (NSCC), Options Clearing Corporation (OCC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clearing Houses and Settlements Market Emerging Trajectories
Settlement infrastructure is bifurcating between centralized utility models optimized for throughput and experimental distributed systems promising atomic execution, with regulatory pressure accelerating both tracks simultaneously.
Blockchain-based settlement rails are fragmenting the post-trade landscape as custodians pilot tokenized securities platforms that compress multi-day settlement cycles into single-block confirmation. Asset servicers at sovereign wealth funds and pension managers are allocating experimental budgets to DLT proofs-of-concept, though production volumes remain marginal against centralized alternatives. The structural consequence is a two-tier market where incumbent clearing houses defend connectivity advantages while consortia-built networks capture greenfield digital asset flows.
EU Central Securities Depositories Regulation amendments are shortening settlement cycles to T+1 by late 2027, compelling US and European operators to synchronize system upgrades across jurisdictions. The industrial consequence is a coordinated infrastructure investment wave as CSDs and CCPs rebuild matching engines and custody interfaces for compressed timelines. Buy-side firms in London and Dublin are restructuring operational workflows to accommodate earlier trade affirmation cutoffs.
Buy-side concentration is reshaping counterparty selection criteria as the largest asset managers consolidate clearing relationships with providers offering integrated data analytics and regulatory reporting bundles. Smaller broker-dealers are losing direct clearing access as minimum volume thresholds rise, forcing migration to sponsored clearing arrangements. This pattern is most pronounced in New York and Boston, where the top ten institutional investors now direct the majority of equity and fixed-income flow.
Clearing Houses and Settlements Market Segmentation
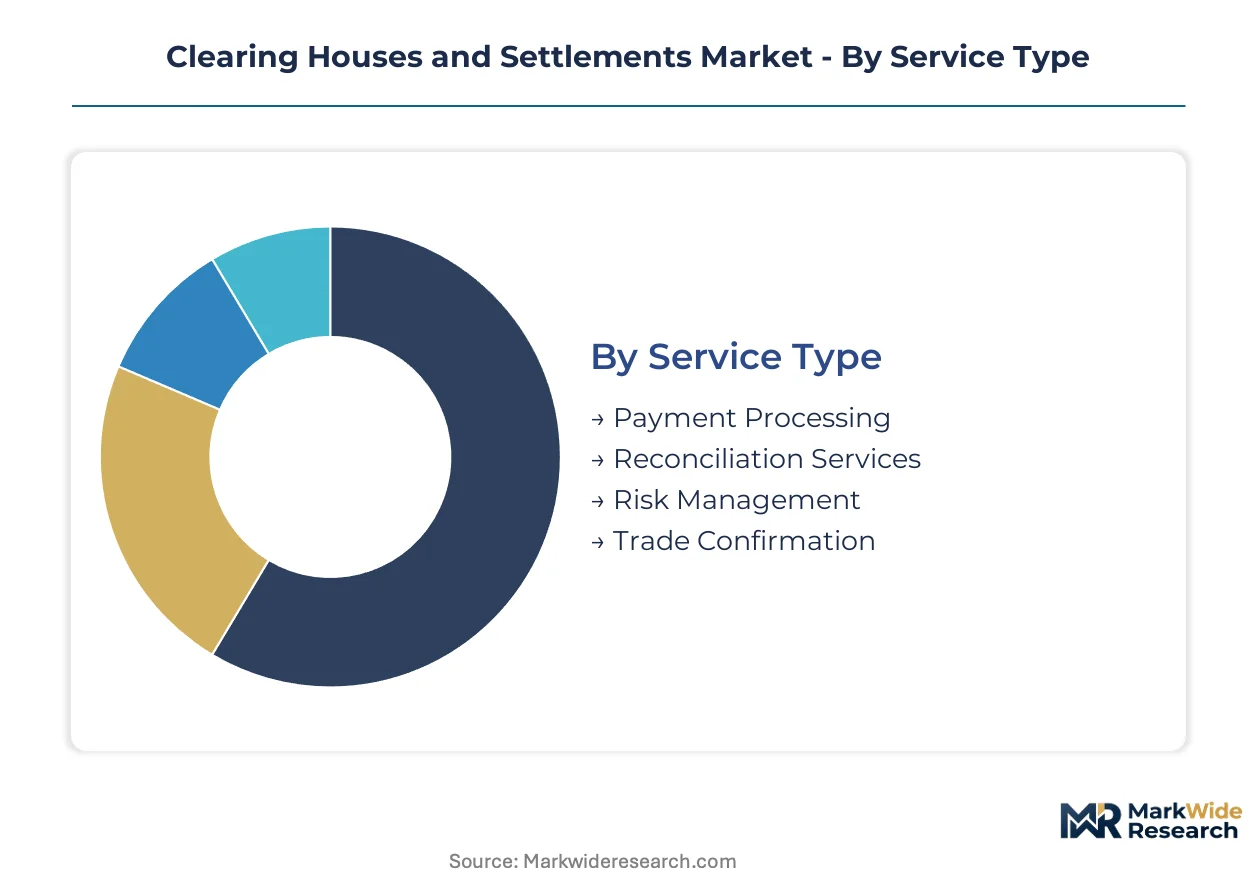
Clearing infrastructure investment decisions pivot on how service tiers, technology maturity, and client sophistication intersect with regulatory capital requirements. Segmentation reveals where margin pools concentrate and which technology transitions command the largest infrastructure budgets.
Service Type:
EMIR and CFTC rules differentiate capital treatment across service categories, directing investment toward functions with the most intensive compliance burdens.
- Payment Processing:Handles final fund transfers through delivery-versus-payment protocols, integrating with central bank money settlement systems. DTCC and Euroclear deploy the deepest liquidity pools here, driven by T+1 compression mandates from the SEC and EU Central Securities Depositories Regulation.
- Risk Management:Encompasses real-time margin calculation, stress testing, and default waterfall administration. LCH Group and CME Clearing anchor demand concentration in London and Chicago as Basel III capital charges push derivatives toward central clearing.
- Reconciliation Services:Matches trade details across counterparties before settlement finality. Custodians in Dublin and Luxembourg prioritize automated affirmation platforms to meet compressed EU settlement deadlines.
- Trade Confirmation:Generates legally binding contract records between clearing members. Broker-dealers in New York and Frankfurt rely on SWIFT messaging and proprietary matching engines for regulatory audit trails.
Payment Processing handles the majority of throughput; Risk Management is expanding most quickly on share as derivatives volumes concentrate at regulated CCPs.
Technology:
Cost tiers separate proven centralized infrastructure from experimental distributed architectures with unproven recovery protocols.
- Centralized Systems:Mainframe-based clearing engines with decades of operational history, processing millions of transactions daily through redundant data centers. DTCC's trade information warehouse exemplifies this tier, dominating US equity and fixed-income settlement volumes.
- Blockchain:Permissioned ledger networks enabling atomic settlement without intermediary novation. Custodians at Singapore sovereign wealth funds and Swiss private banks pilot tokenized securities platforms, though production throughput remains marginal against centralized alternatives.
- Distributed Ledger:Hybrid architectures linking multiple nodes across clearing members for shared reference data. Euroclear's D-Fund initiative in Brussels demonstrates demand concentration for fund record-keeping modernization.
- Automated Clearing:Rules-based processing engines replacing manual intervention in standardizable workflows. ACH networks in the United States process retail payment batches, distinct from real-time gross settlement systems.
Centralized Systems anchor current revenue; Blockchain captures the steepest expansion trajectory among experimental budgets.
Transaction Type:
Volume concentration varies dramatically by asset class liquidity and regulatory clearing mandates.
- Equity Settlements:Standardized share transfers with T+1 finality in the United States and advancing T+1 deadlines in Europe. DTCC's National Securities Clearing Corporation processes the dominant share of US equity volume.
- Derivative Settlements:Complex instrument novation requiring portfolio-level margin calculation across correlated positions. LCH SwapClear in London clears the majority of interest rate swap notional as buy-side firms exit bilateral arrangements.
- Foreign Exchange:Spot and forward currency settlement through CLS Bank's multilateral netting system. Daily settlement values in London and New York exceed other asset classes by order of magnitude.
- Commodity Settlements:Physical delivery coordination for energy and agricultural contracts. CME Clearing and ICE Clear US anchor demand in Chicago and Atlanta, with regulatory divergence between CFTC position limits and EU MiFID II rules.
Equity Settlements generates the largest transaction counts; Derivative Settlements claims the fastest share gain from regulatory migration.
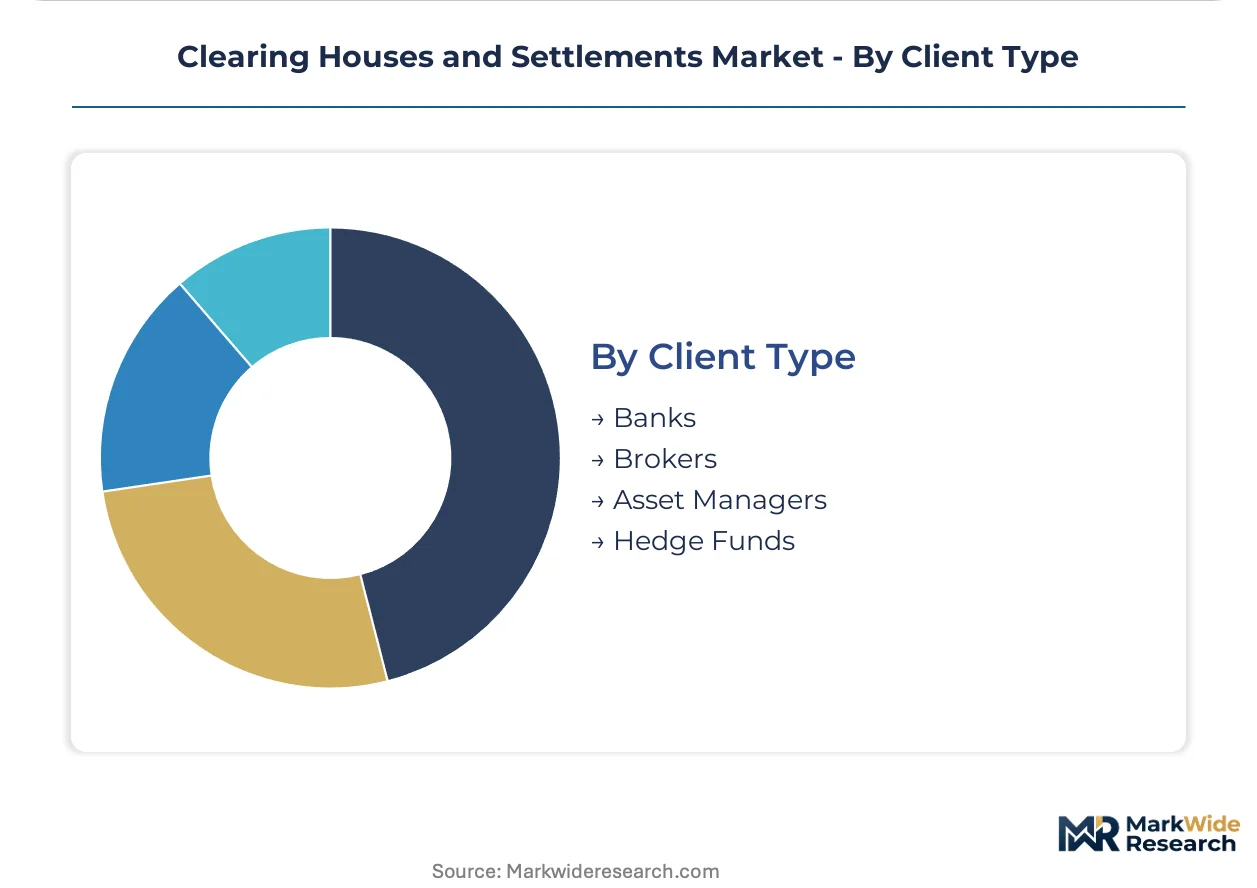
Client Type:
Customer sophistication determines service bundling depth and pricing tier access.
- Banks:Direct clearing members with default fund contributions and proprietary risk system integration. JPMorgan and Goldman Sachs maintain the deepest relationships with DTCC and OCC in New York.
- Asset Managers:Institutional investors consolidating relationships with integrated data and reporting bundles. BlackRock and Vanguard in Boston and Malvern direct the largest equity and fixed-income flows.
- Brokers:Intermediaries facing rising minimum volume thresholds that force migration to sponsored clearing. Regional broker-dealers in Chicago and San Francisco increasingly access CCPs through prime brokerage arrangements.
- Hedge Funds:Leveraged counterparties with concentrated portfolios requiring specialized margin treatment. Citadel and Millennium in Miami and New York negotiate bespoke risk arrangements with clearing providers.
Banks retain the dominant share of direct membership; Asset Managers are gaining influence fastest through flow concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in clearing services exports, while European and Asian financial centers compete for cross-border derivatives flow through regulatory recognition frameworks. Settlement infrastructure investment clusters where capital markets depth intersects with CCP licensing density.
United States
DTCC and OCC process the dominant share of global equity and equity derivatives volumes from New York and Chicago hubs. SEC T+1 mandates and CFTC margin segregation rules force continuous infrastructure refresh cycles. The Tri-State area anchors prime brokerage clearing relationships for hedge funds and asset managers.
United Kingdom
LCH Group in London clears the majority of interest rate swap notional as Basel III capital charges displace bilateral arrangements. EMIR recognition frameworks and Bank of England CCP supervision standards determine access for EU-facing clients. The City of London concentrates euro-denominated derivatives clearing despite post-Brexit relocation pressures.
Germany
Eurex Clearing in Frankfurt leverages EU CSDR compliance mandates to capture bond and repo settlement flows from continental asset managers. BaFin oversight and ECB settlement account integration anchor its infrastructure position. The Rhine-Main metropolitan region houses the technical operations for T+1 compression upgrades.
Singapore
Monetary Authority of Singapore CCP licensing attracts regional derivatives clearing for Asian currency and commodity contracts. MAS recognition frameworks compete with Hong Kong for Australian and Japanese asset manager flow. The Marina Bay financial district hosts data center infrastructure for sub-second margin calculation.
Japan
JSCC in Tokyo processes domestic equity and interest rate derivatives under FSA CCP supervision standards. JFSA margin rules and BoJ settlement account integration determine infrastructure investment priorities. The Nihonbashi financial district concentrates post-trade utilities for regional cross-border settlement.
Clearing Houses and Settlements Market Vendor Landscape
Concentration sits with utility-scale central counterparties that control captive connectivity to national broker-dealer networks. Three archetypes dominate: incumbent clearing houses with decades of operational history, bank-owned clearing subsidiaries leveraging balance sheet depth, and technology-anchored challengers automating post-trade workflows. Competitive moves center on M&A consolidation of regional CCPs and strategic partnerships bridging traditional and distributed ledger rails.
Among incumbent utility operators, DTCC and LCH Group exemplify the infrastructure-scale archetype through captive market position in their respective jurisdictions. JP Morgan Clearing Corp occupies a position within the bank-owned tier, anchoring prime brokerage relationships through balance sheet capacity. Apex Clearing represents the technology-driven challenger model, automating custody and settlement workflows for digital-native broker-dealers.
| Leading Market Players |
|---|
| DTCC (Depository Trust Clearing Corporation) |
| Bank of America Merrill Lynch |
| JP Morgan Clearing Corp |
| Goldman Sachs Execution and Clearing LP |
| LCH Group |
| Eurex Clearing |
| Apex Clearing |
| National Securities Clearing Corporation (NSCC) |
| Options Clearing Corporation (OCC) |
| Others |
Supply Flow & Price Mechanics
EMIR Refit compliance mandates gate both infrastructure qualification and service tier differentiation simultaneously, forcing clearing houses to embed regulatory certification costs into base pricing while segmenting premium connectivity bundles for buy-side firms with compressed settlement deadlines.
Pricing Analysis
Asset managers anchor clearing fee structures through volume-commitment contracts that bundle payment processing, risk management, and regulatory reporting into unified service tiers. Price differentiation rests on margin calculation latency and cross-margining eligibility across correlated portfolios. Cost compression in standard settlement tiers is intensifying because legacy mainframe depreciation cycles extend while real-time infrastructure demands accelerate. Regional broker-dealers exhibit the highest price sensitivity as sponsored clearing arrangements erode direct negotiation leverage.
Supply Chain Analysis
Hardware procurement lead times for sub-second matching engines now stretch eighteen to twenty-four months, constraining infrastructure expansion timelines for CCPs facing T+1 mandates. Supply concentration centers on the United States, the United Kingdom, and Germany where DTCC, LCH Group, and Eurex Clearing anchor core processing capacity. Specialized semiconductor components and redundant data center real estate feed from captive vendor relationships with limited second-source alternatives. Single-source vulnerability in critical path hardware exposes clearing houses to delivery disruption. Distribution runs through direct long-term service contracts with broker-dealers and asset managers rather than intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed ledger integration and real-time settlement mandates constitute a dual technological-regulatory inflection that will bifurcate winners from obsolete infrastructure over the next decade.
For Market Incumbents: Consolidate captive connectivity advantages by acquiring specialized carbon derivatives CCPs before regulatory standardization commoditizes first-mover positioning. Deepen vertical integration into AI-driven risk surveillance tooling to reduce qualifying members' margin buffer requirements and lock in flow concentration.
For New Entrants and Emerging Players: EMIR recognition fast-tracks for Frankfurt and Paris clearing nodes create entry pathways for hybrid DLT-centralized architectures serving euro-denominated derivatives. Carbon credit and private fund servicing segments offer the most penetrable white-space with minimal incumbent saturation. Lead with atomic settlement pilots for tokenized securities to differentiate from legacy T+1 workflows.
For Investors and Strategic Acquirers: T+0 settlement mandates reshape the acquisition landscape toward infrastructure-scale CCPs with proven recovery protocols and captive broker-dealer networks. Mid-cap clearing utilities with multi-asset class coverage and EMIR/CFTC dual compliance architectures represent the optimal target archetype. Monitor DLT pilot production volume thresholds as the critical inflection signal for technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Infrastructure Modernization | Sub-second matching engine deployment satisfies SEC and EU CSDR compression mandates for T+1 finality. |
| DLT Bridge Architecture Development | Hybrid ledger-centralized systems connect tokenized securities workflows to proven custody rails. |
| Carbon Derivatives CCP Launch | Specialized clearing for emissions futures captures pre-standardization positioning in compliance markets. |
| AI Risk Surveillance Integration | Machine learning margin models differentiate service tiers by reducing buffer requirements for qualifying members. |
| Cross-Border Recognition Expansion | MAS and JFSA licensing extensions unlock Asian derivatives flow for global asset manager clients. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with clearing house operations executives, CCP risk officers, asset manager treasury leads, and broker-dealer compliance directors; and secondary validation against DTCC volume disclosures, EMIR trade repository data, SEC regulatory filings, and Bank for International Settlements CCP quantitative disclosures. Bottom-up transaction flow modeling and top-down infrastructure capacity assessment were triangulated against regulatory mandate implementation timelines.
Across the projection horizon, the analytical framework modeled value expansion across service type, technology maturity, transaction asset class, and client sophistication segments. CAGRs were derived from infrastructure investment cycle analysis and derivatives volume migration patterns under Basel III capital charge regimes. Forecast inputs incorporated CSDR amendment implementation schedules and DLT pilot production scaling assumptions.
Decision-makers should treat outputs as directional under sustained regulatory compression toward T+0 finality and gradual DLT adoption curves; material deviation in either assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Israel Credit Cards Market
Payments
Remote Mobile Payment Market
Payments
North America POS Terminal Market
Payments
Payment Instruments Market
Payments
China Virtual Cards Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Global Telecom Billing Market
Payments
France POS Terminal Market
Payments
Europe Real Time Payments Market
Payments
South Korea POS Terminals Market
Payments
Mobile Payment Market
Payments
India Gift Card and Incentive Card Market
Payments
Proximity Payment Market
Payments
Third Party Payment Market
Payments
Canada Payment Gateway Market
Payments
M Commerce Payment Market