
 Online Charging System (OCS) Market | 2026-2036
Online Charging System (OCS) Market Size, Share, and Industry Trends Forecast 2026-2036
Online Charging System (OCS) Market Analytics
Enterprise and MVNO buyer archetypes are gaining share as telecom operator procurement is bifurcating between legacy refresh cycles and greenfield 5G deployments. Nokia leverages its end-to-end portfolio to anchor large-scale operator contracts across Europe and Asia. Huawei Technologies competes aggressively on price-performance in cloud-native OCS stacks, though its geographic reach faces headwinds in certain Western markets. Amdocs differentiates through managed services bundling that extends beyond software licensing into operational support.
An Online Charging System is a real-time transaction processing engine that authorizes and charges for network services using subscriber balance management, rating algorithms, and session control protocols operating at sub-second latency. Its primary commercial purpose is enabling telecom service providers to monetize voice, data, and digital services through instantaneous credit checking and policy enforcement. Cloud-based deployment models are capturing the fastest expansion as operators seek elastic capacity for traffic spikes during peak usage periods. Prepaid and hybrid solution types retain dominant share in emerging markets where subscriber liquidity constraints favor pay-as-you-go structures. Real-time charging technology sits at the margin center as 5G network slicing and IoT metering demand granular, event-driven billing architectures.
The Federal Communications Commission shapes US market access through net neutrality and spectrum auction rules that indirectly mandate flexible charging infrastructures. ETSI and 3GPP standards bodies in Europe enforce interoperability requirements that OCS vendors must satisfy for operator certification. China's Ministry of Industry and Information Technology drives domestic substitution policies affecting vendor selection criteria for state-owned carriers. Stakeholders must monitor how sovereign data localization mandates and open RAN interoperability specifications reshape procurement criteria across major telecom markets.
Market Dynamics
5G network slicing is fragmenting charging architectures into microservices that demand sub-100 millisecond latency for session authorization, forcing operators to retire monolithic OCS stacks accumulated over two decades of 3G/4G deployments.
Growth Catalysts
- 3GPP Release 17:The standards body mandates converged charging for 5G standalone networks, compelling operators to upgrade billing infrastructure before spectrum license renewal deadlines in Germany and Japan.
- IoT metering granularity:Connected vehicle platforms and industrial sensors require event-driven rating engines that traditional offline billing cannot support, creating pull from automotive OEMs and manufacturing clusters in the United States.
- Prepaid liquidity constraints:Subscriber payment behavior in emerging markets favors real-time balance management over post-paid invoicing cycles, sustaining deployment momentum across Southeast Asian operator networks.
Market Restraints
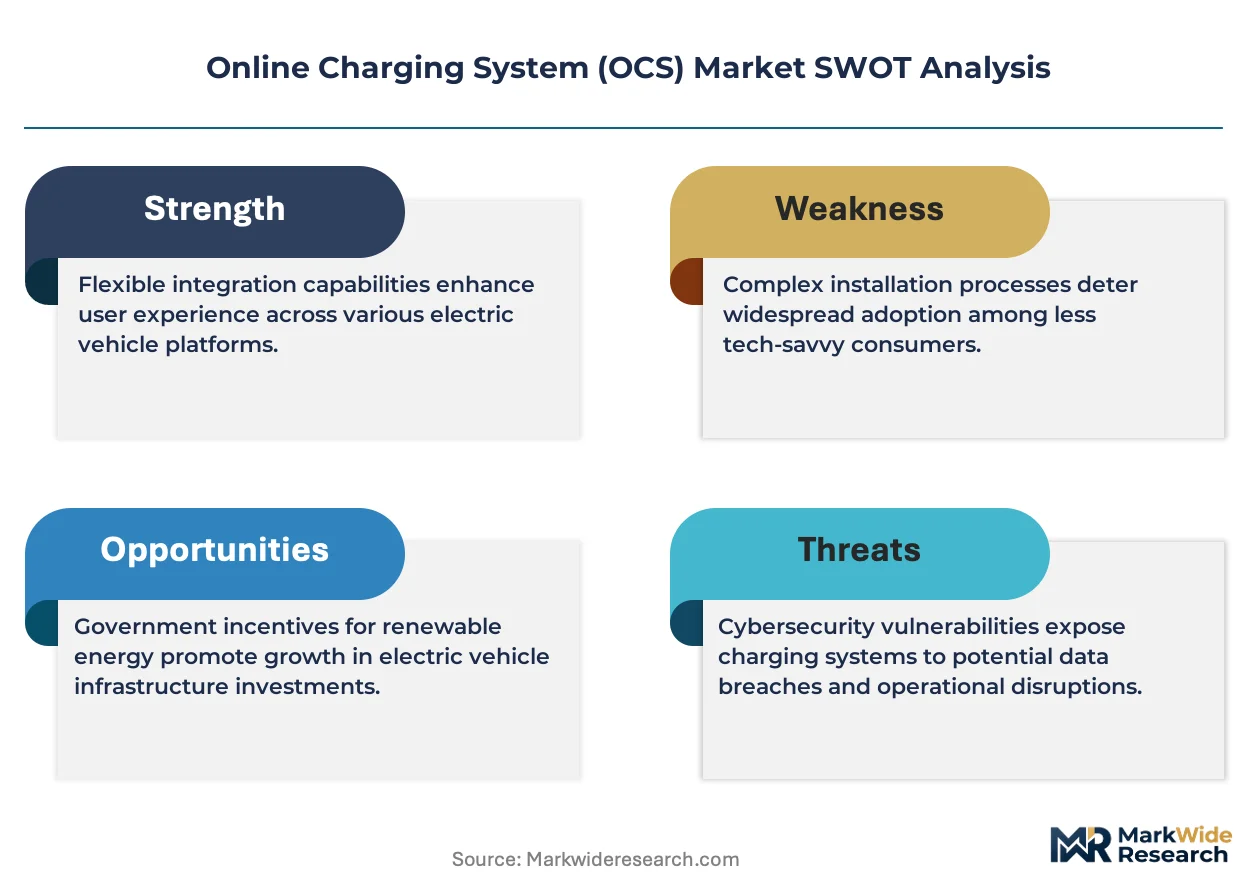
- Semiconductor supply concentration:Specialized ASICs for packet inspection and policy enforcement originate from fabrication facilities concentrated in Taiwan, exposing OCS hardware vendors to geopolitical disruption risk.
- Legacy system entrenchment:Operator IT estates carry technical debt from 1990s-era IN-based charging platforms that resist API-native integration without expensive mediation layers.
- Data localization mandates:Brazil's Lei Geral de Proteção de Dados and India's draft data protection rules impose jurisdictional boundaries on subscriber profile storage, complicating cloud-native OCS architectures that assume centralized data lakes.
Strategic Opportunities
- Open RAN interoperability:The O-RAN Alliance specifications create entry points for software-only charging vendors to displace integrated hardware-software incumbents in European operator RFPs.
- Private 5G networks:Manufacturing campuses and port authorities in the United States are procuring dedicated charging engines for captive network slices, bypassing traditional operator procurement channels.
- Carbon accounting integration:The EU Corporate Sustainability Reporting Directive will require telecom operators to attribute energy consumption per subscriber session, creating demand for charging systems that embed emissions data into rating records.
Industry Challenges
- Converged billing talent scarcity:Engineers proficient in both telco protocol stacks (Diameter, Gy, Sy) and cloud-native Kubernetes orchestration command premium compensation that vendor margins struggle to absorb.
- Multi-vendor integration complexity:Operators deploying best-of-breed policy control alongside OCS components from separate vendors encounter session state synchronization failures that degrade customer experience during peak traffic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Charging System (OCS) Market |
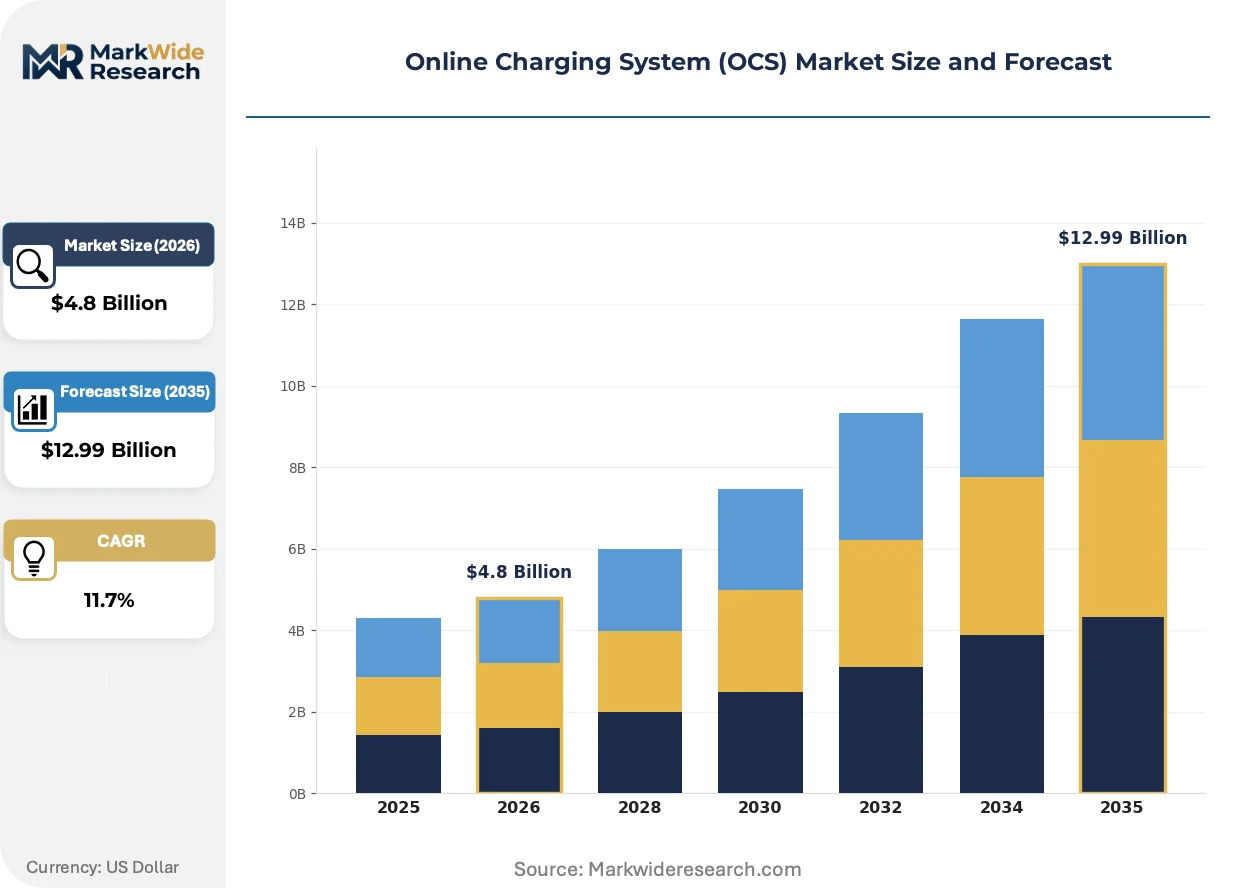
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Prepaid, Postpaid, Hybrid, Real-time Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Virtualized End User: Telecom Operators, Managed Service Providers, Enterprises, MVNOs Technology: 5G, LTE, VoLTE, Wi-Fi |
| Companies Covered | Nokia, CSG International, Amdocs, Openet, Cerillion, Ericsson, Oracle, Optiva, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Charging System (OCS) Market Evolving Landscape
Containerized deployment models are collapsing the boundary between charging and policy functions, enabling elastic scaling that aligns infrastructure costs with actual transaction volumes rather than peak-provisioned capacity.
Cloud-native OCS architectures built on microservices are decomposing the traditional three-tier charging stack into independently scalable functions for rating, balance management, and session control. Tier-1 operators in Germany and Japan are migrating production traffic to these disaggregated platforms. The structural consequence is compressing vendor maintenance revenue streams as operators replace perpetual licenses with consumption-based SaaS contracts.
The Federal Communications Commission's spectrum auction conditions now incorporate flexible service rules that implicitly require dynamic charging capabilities for priority access and quality-of-service tiers. Equipment vendors must demonstrate real-time policy enforcement to secure operator certification for C-band and mmWave deployments. US mobile network operators are responding by embedding OCS procurement timelines into their 5G core modernization roadmaps.
Enterprise procurement of charging capabilities is bypassing traditional operator channels as private network deployers seek direct relationships with software vendors. Manufacturing conglomerates and logistics operators are licensing OCS modules for captive 5G installations rather than reselling operator services. This pattern is most visible in the United States, where port authorities and automotive assembly plants are issuing standalone RFPs for converged charging and policy control.
Online Charging System (OCS) Market Segmentation
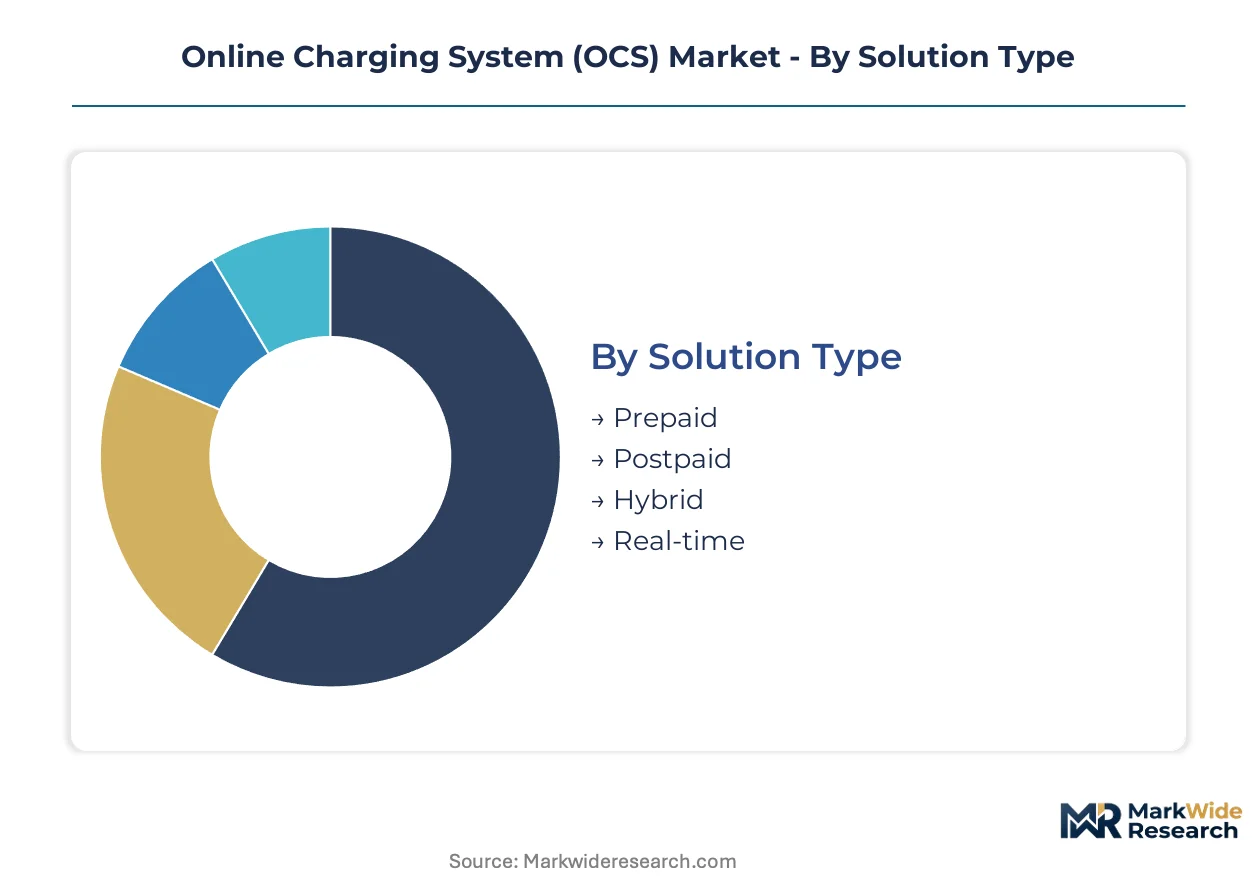
OCS procurement patterns diverge sharply across solution architectures and buyer categories. Deployment choices reflect operator maturity, regulatory exposure, and traffic volatility requirements.
Solution Type:
Prepaid architectures dominate emerging market installations where subscriber liquidity constraints favor real-time balance management. Postpaid and hybrid models concentrate in developed economies with established credit infrastructures.
- Prepaid:Session-based authorization engines enforce immediate credit checks against subscriber wallets. Demand clusters in Southeast Asian and African operator networks where pay-as-you-go structures mitigate payment default risk.
- Postpaid:Periodic billing cycles aggregate usage for invoice generation, requiring robust mediation and rating pipelines. German and Japanese operators maintain postpaid dominance in consumer segments, though 5G slicing is forcing convergence toward real-time architectures.
- Hybrid:Unified platforms process both prepaid and postpaid traffic through shared rating engines. This architecture appeals to operators managing mixed subscriber bases across prepaid-heavy emerging markets and postpaid corporate accounts.
- Real-time:Sub-100 millisecond authorization engines support event-driven IoT metering and network slice monetization. Automotive OEMs in the United States are procuring these engines for connected vehicle platforms.
Prepaid commands the established base. The steepest expansion runs through Real-time.
Deployment Model:
Cloud migration intensity varies by data sovereignty exposure and traffic predictability. Operators in jurisdictions with strict localization mandates retain on-premises footprints for subscriber profile storage.
- Cloud-Based:Elastic Kubernetes-orchestrated deployments scale transaction capacity dynamically. Tier-1 operators in Germany and Japan are migrating production traffic to these platforms, compressing vendor maintenance revenue into consumption-based SaaS contracts.
- Hybrid Cloud:Sensitive subscriber data resides on-premises while rating engines burst to public cloud during peak traffic. Brazilian operators favor this architecture to satisfy Lei Geral de Proteção de Dados localization requirements without sacrificing elasticity.
- On-Premises:Dedicated hardware installations persist where regulatory mandates prohibit cross-border data flows. State-owned carriers in China maintain fully captive infrastructure under MIIT substitution policies.
- Virtualized:NFV-based deployments abstract charging functions from proprietary hardware onto commodity servers. European operators pursuing O-RAN interoperability specifications favor this model for vendor disaggregation.
On-Premises retains the installed base. Cloud-Based is climbing the fastest.
End User:
Procurement authority is fragmenting as private network deployers bypass traditional operator channels. Enterprise direct licensing is reshaping vendor go-to-market strategies.
- Telecom Operators:Incumbent mobile network operators drive volume procurement for consumer and enterprise service monetization. Their 5G core modernization roadmaps in the United States embed OCS replacement timelines tied to FCC spectrum auction conditions.
- Enterprises:Manufacturing campuses and port authorities license captive charging engines for private 5G networks. US automotive assembly plants and logistics operators now issue standalone RFPs for converged charging and policy control.
- MVNOs:Mobile virtual network operators rely on hosted charging platforms with limited customization. Their procurement prioritizes rapid service launch over deep rating flexibility.
- Managed Service Providers:Outsourced operations vendors bundle OCS administration with broader network management. Amdocs and similar vendors capture this segment through operational support contracts extending beyond software licensing.
Telecom Operators anchor current revenue. Enterprises are gaining share fastest.
Technology:
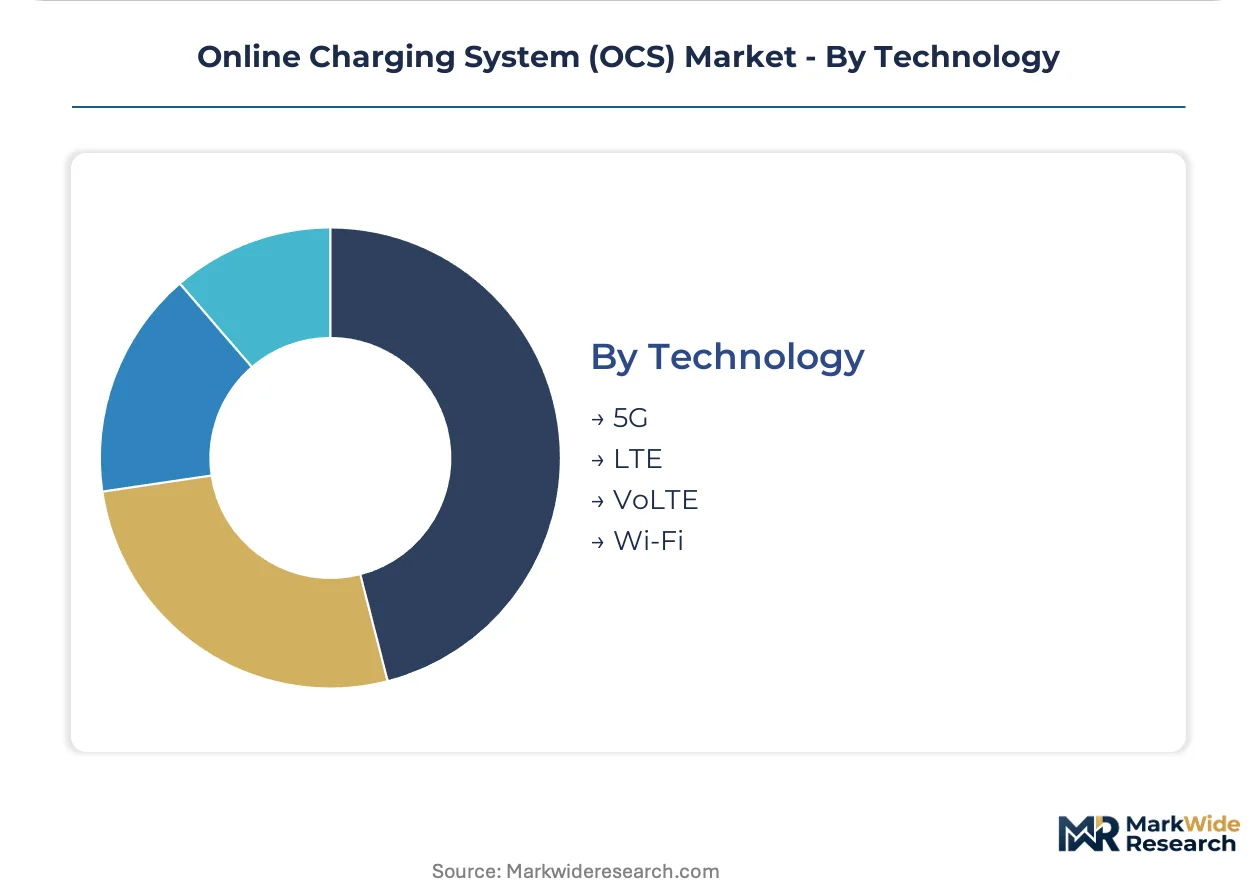
Network generation determines protocol requirements and latency tolerances. 5G standalone deployments are forcing retirement of Diameter-based charging stacks accumulated over two decades.
- 5G:Service-based architecture charging functions (CHF) replace traditional OCS nodes with stateless microservices. 3GPP Release 17 mandates converged charging for standalone networks, compelling German and Japanese operators to upgrade before license renewal deadlines.
- LTE:Diameter Gy and Gz interfaces persist in 4G core networks undergoing phased replacement. Hybrid operators maintain LTE charging capacity for fallback traffic during 5G coverage gaps.
- VoLTE:Voice-over-LTE implementations require integrated charging for IMS session control. This technology segment is contracting as operators migrate voice traffic to 5G VoNR architectures.
- Wi-Fi:Hotspot and carrier Wi-Fi offloading demand lightweight charging integration with cellular policy control. Venue owners and cable operators deploy these solutions for neutral host monetization.
LTE holds the legacy base. 5G shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations at Fortaleza and Santos anchor Brazil's position as a data transit hub for South American OCS traffic, while the Trans-Pacific fiber links through Japan's Chikura and Maruyama stations underpin real-time charging latency requirements for Asia-Pacific 5G networks.
United States
Private 5G deployments at the Port of Los Angeles and automotive assembly plants in Detroit are driving direct enterprise procurement of charging engines outside traditional operator channels. The FCC's C-band auction conditions mandate dynamic service tiers that require sub-second policy enforcement. Dallas-Fort Worth hosts the densest concentration of cloud-native OCS development labs serving North American operators.
Germany
Industrial IoT metering for connected manufacturing in Baden-Württemberg is accelerating demand for event-driven rating architectures. The national telecom regulator enforces strict data localization requirements that favor hybrid cloud deployments over centralized SaaS models. Munich and Stuttgart anchor the highest density of 5G standalone network slicing trials requiring converged charging function upgrades.
Japan
Connected vehicle platforms from Nagoya's automotive engineering corridor are pulling real-time charging engines for usage-based insurance and infotainment monetization. METI's spectrum allocation policies tie license renewals to 3GPP Release 17 compliance deadlines. The Tokyo-Yokohama corridor concentrates vendor R&D partnerships focused on sub-100 millisecond session authorization.
China
State-owned carrier procurement under MIIT substitution policies favors domestically developed charging stacks for core network infrastructure. The Yangtze River Delta manufacturing belt is deploying private 5G networks with captive charging engines for industrial automation. Shenzhen and Beijing host the primary development centers for cloud-native OCS microservices targeting state-mandated technology independence.
India
Prepaid subscriber liquidity constraints across Maharashtra and Karnataka are sustaining deployment momentum for real-time balance management systems. TRAI's draft data protection rules impose jurisdictional boundaries on subscriber profile storage that complicate centralized cloud architectures. The Delhi-NCR corridor hosts the primary integration centers for hybrid prepaid-postpaid platforms serving mixed subscriber bases.
Online Charging System (OCS) Market Competitive Landscape
Concentration sits with end-to-end network equipment vendors who bundle charging functions with broader 5G core modernization contracts. The vendor landscape organizes around three strategic archetypes: integrated hardware-software providers, cloud-native software specialists, and managed services bundlers. Competitive positioning hinges on geographic certification breadth and API-native integration capabilities. Primary competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into policy control functions.
Within the integrated equipment tier, Nokia and Ericsson anchor large-scale operator procurement across European and Asian markets. Amdocs occupies a distinct position through operational support contracts that extend beyond software licensing into managed charging administration. Huawei Technologies exemplifies the price-performance competitive vector in cloud-native stacks, though its market access faces constraints in Western jurisdictions. These three company representations illustrate how vendor selection criteria diverge between operators prioritizing end-to-end accountability versus those seeking disaggregated best-of-breed procurement.
| Leading Market Players |
|---|
| Nokia |
| CSG International |
| Amdocs |
| Openet |
| Cerillion |
| Ericsson |
| Oracle |
| Optiva |
| Huawei Technologies |
| Others |
Value Network & Pricing Analysis
Perpetual-to-SaaS migration clauses in operator contracts lock in multi-year revenue visibility while compressing vendor margins through consumption-based pricing. German and Japanese carriers negotiate these structures to align OCS costs with actual transaction volumes rather than peak-provisioned capacity.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale operators from MVNOs and mid-tier deployers. Pricing stratifies across premium certified stacks, standard virtualized deployments, and economy-grade hosted platforms. Cost compression in the economy tier is intensifying because Huawei Technologies and domestic Chinese vendors compete aggressively on price-performance. MVNOs exhibit the highest price sensitivity due to thin margins and limited customization requirements, while Tier-1 operators prioritize certification breadth over unit cost.
Supply Chain Analysis
Taiwan Strait transit risk exposes OCS hardware vendors to disruption of specialized ASIC fabrication for packet inspection engines. Supply concentrates in Taiwan for semiconductor fabrication, China for server assembly, and Germany for precision engineering components. Raw material dependencies include silicon wafers, rare earth elements for magnetic components, and high-grade copper for interconnects. Single-source vulnerability in Taiwanese foundries threatens production continuity. Distribution runs through direct vendor-operator relationships with hyperscale cloud provider partnerships gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native microservices architectures threaten incumbent integrated hardware-software providers with disaggregation and margin compression. Incumbents must navigate this substitution by anchoring customer relationships beyond pure technology delivery.
For Market Incumbents: Consolidate end-to-end accountability advantages by bundling charging functions with policy control and 5G core modernization. Deepen certification investments in FCC, ETSI, and 3GPP compliance to maintain operator procurement preference. Acquire Kubernetes orchestration talent to close the cloud-native capability gap against software-only entrants.
For New Entrants and Emerging Players: Managed services gaps in operational support and charging administration present white-space opportunities where Amdocs-style bundling remains underdeveloped. Private 5G network deployers at US manufacturing campuses and port authorities represent the most penetrable segment. Pursue direct enterprise licensing models that bypass traditional operator procurement channels entirely.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native software specialists with demonstrated 3GPP Release 17 compliance and API-native integration capabilities. Long-term viability hinges on vendor ability to transition from perpetual license revenue to recurring SaaS streams. Monitor 5G standalone network slicing deployment velocity at German and Japanese operators as the inflection indicator for converged charging function upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Enables elastic scaling that aligns infrastructure costs with actual transaction volumes rather than peak capacity. |
| 3GPP Release 17 Compliance Investment | Secures operator certification for 5G standalone deployments in Germany and Japan before license renewal deadlines. |
| Private 5G Enterprise Direct Licensing | Bypasses traditional operator channels to capture manufacturing campus and port authority procurement in the United States. |
| Operational Support Bundling | Extends vendor relationships beyond software licensing into managed charging administration and lifecycle services. |
| Open RAN Interoperability Certification | Creates entry points for software-only vendors to displace integrated incumbents in European operator RFPs. |
Research Methodology
A spread of perspectives from telecom network architects, charging system procurement officers, cloud infrastructure engineers, and regulatory compliance leads converged on the working assumptions. Primary interviews combined with secondary validation from 3GPP standards documentation, FCC spectrum auction filings, ETSI interoperability specifications, and operator capex disclosures. Bottom-up transaction volume modeling triangulated against top-down market sizing from infrastructure deployment announcements.
Segmentation dimensions modeled include deployment architecture, solution type, end-user category, and network generation protocol. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon. Forecast inputs incorporated 5G standalone rollout timelines, IoT metering granularity requirements, and data localization mandate enforcement patterns.
Forecasts assume regulatory continuity in FCC spectrum auction conditions, ETSI interoperability requirements, and MIIT substitution policies; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as sovereign data localization mandates and open RAN specification maturity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
LAMEA Payment Gateway Market
Payments
APAC Mobile Payments Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Mpos Terminals Market
Payments
3D Secure Pay Authentication Market
Payments
US Virtual Cards Market
Payments
Hungary POS Terminal Market
Payments
Spain Real Time Payments Market
Payments
In Vehicles Payment Market
Payments
Denmark Payments Market
Payments
Contactless Payment Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Wearable Payments Market
Payments
North America Payment Gateway Market
Payments
Southeast Asia POS Terminal Market