
 Japan Credit Cards Market | 2026-2036
Japan Credit Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Credit Cards Market Insights
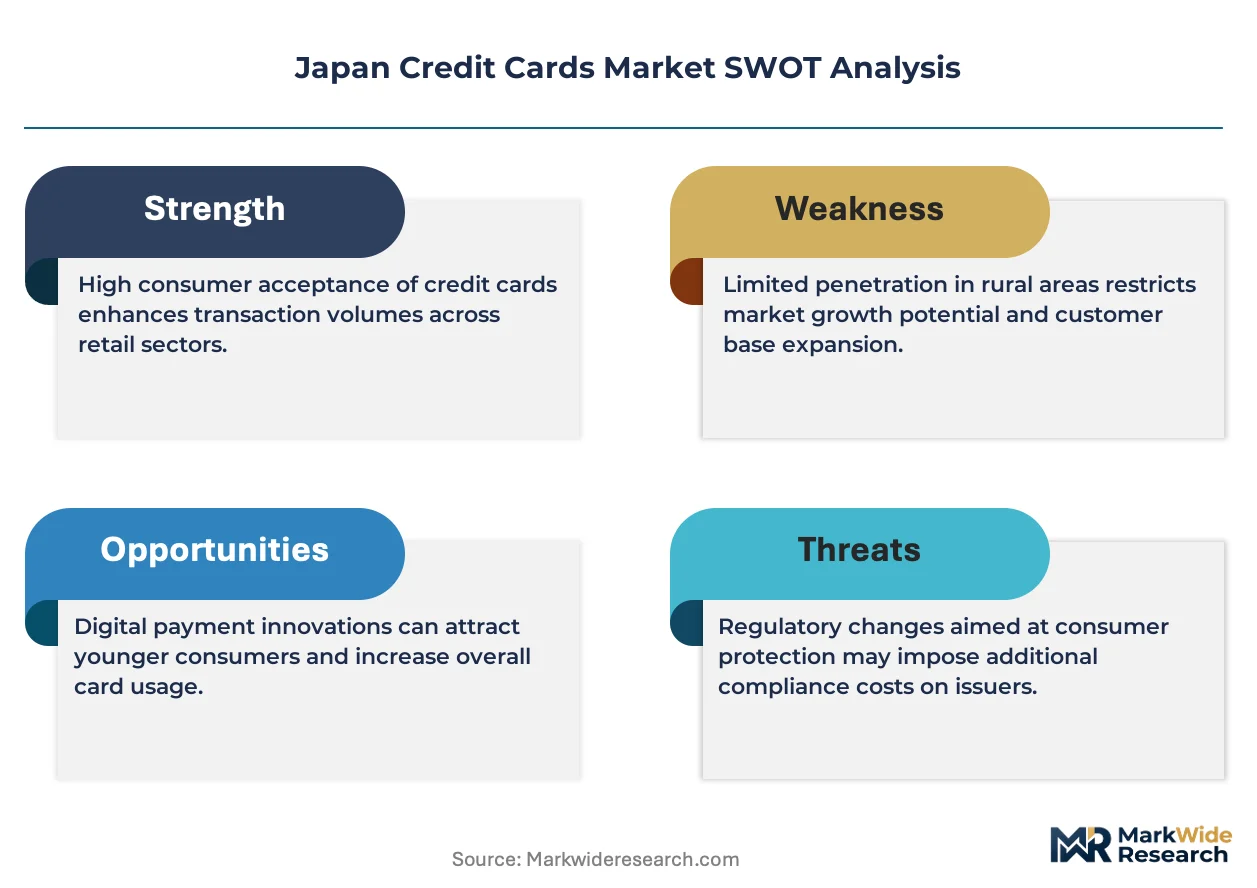
The Act on the Protection of Personal Information is expanding compliance burdens for card issuers processing biometric and transaction data, forcing smaller players to outsource core infrastructure. Mitsubishi UFJ NICOS Co., Ltd. leverages its banking parentage to sustain low-cost deposit funding for revolving credit portfolios. Rakuten Card Co., Ltd. anchors its position through ecosystem lock-in, bundling card rewards with e-commerce and travel platforms. Sumitomo Mitsui Card Co., Ltd. competes via premium travel corridors, occupying the airport lounge and international hotel partnership tier.
Japan credit cards constitute revolving payment instruments issued under three-party or four-party network schemes, typically embedding EMV chip technology and contactless NFC interfaces for settlement authorization. These instruments facilitate deferred consumer and commercial expenditure while generating interchange and interest income for issuing institutions. Co-branded cards dominate transaction volume through retail and airline partnership density, while premium tier products capture disproportionate fee-based revenue per account. Business cards represent the fastest-expanding segment as sole proprietorships and small enterprises formalize expense separation from personal accounts.
METI's cashless vision framework and JFSA prudential guidelines jointly shape issuer capital requirements and merchant subsidy allocation, constraining pricing freedom while expanding acceptance infrastructure. The Personal Information Protection Commission enforces data localization standards that elevate domestic cloud and processing costs relative to regional peers. Stakeholders must monitor whether open banking API mandates under amended Banking Act provisions fragment card-centric payment relationships or reinforce them through enriched data services.
Market Dynamics
The convergence of METI's cashless rebate program with transit-integrated payment ecosystems is compressing merchant resistance while accelerating consumer habit formation around contactless settlement instruments.
Growth Catalysts
- METI Cashless Vision Framework:Government-subsidized merchant fee reductions are expanding electronic acceptance infrastructure into traditional cash-dominated retail corridors.
- Digital Salary Disbursement:Corporate payroll digitization is normalizing card-linked wage accounts among working professionals, creating embedded payment relationships.
- Transit-Integrated Wallets:Suica and Pasmo ecosystem penetration is absorbing daily commuter expenditure into contactless card rails.
Market Restraints
- Deposit Funding Concentration:Revolving credit portfolios depend on parent bank deposit bases, constraining independent issuer cost structures.
- Data Localization Mandates:Personal Information Protection Commission requirements elevate domestic cloud processing costs relative to regional peers.
- Interchange Rate Compression:Merchant subsidy programs are constraining issuer pricing freedom on transaction fee revenue.
Strategic Opportunities
- Business Card Formalization:Sole proprietorships and small enterprises are separating expense accounts, creating white space in commercial payment instruments.
- Open Banking API Convergence:Amended Banking Act provisions enable enriched data services that could reinforce card-centric relationships.
- Premium Travel Corridors:Airport lounge and international hotel partnership tiers remain underpenetrated relative to outbound tourism recovery.
Industry Challenges
- Biometric Compliance Complexity:Act on the Protection of Personal Information expansion is forcing smaller issuers to outsource core infrastructure.
- Legacy System Integration:EMV chip migration and contactless NFC overlay requirements create technical debt in established processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Credit Cards Market |
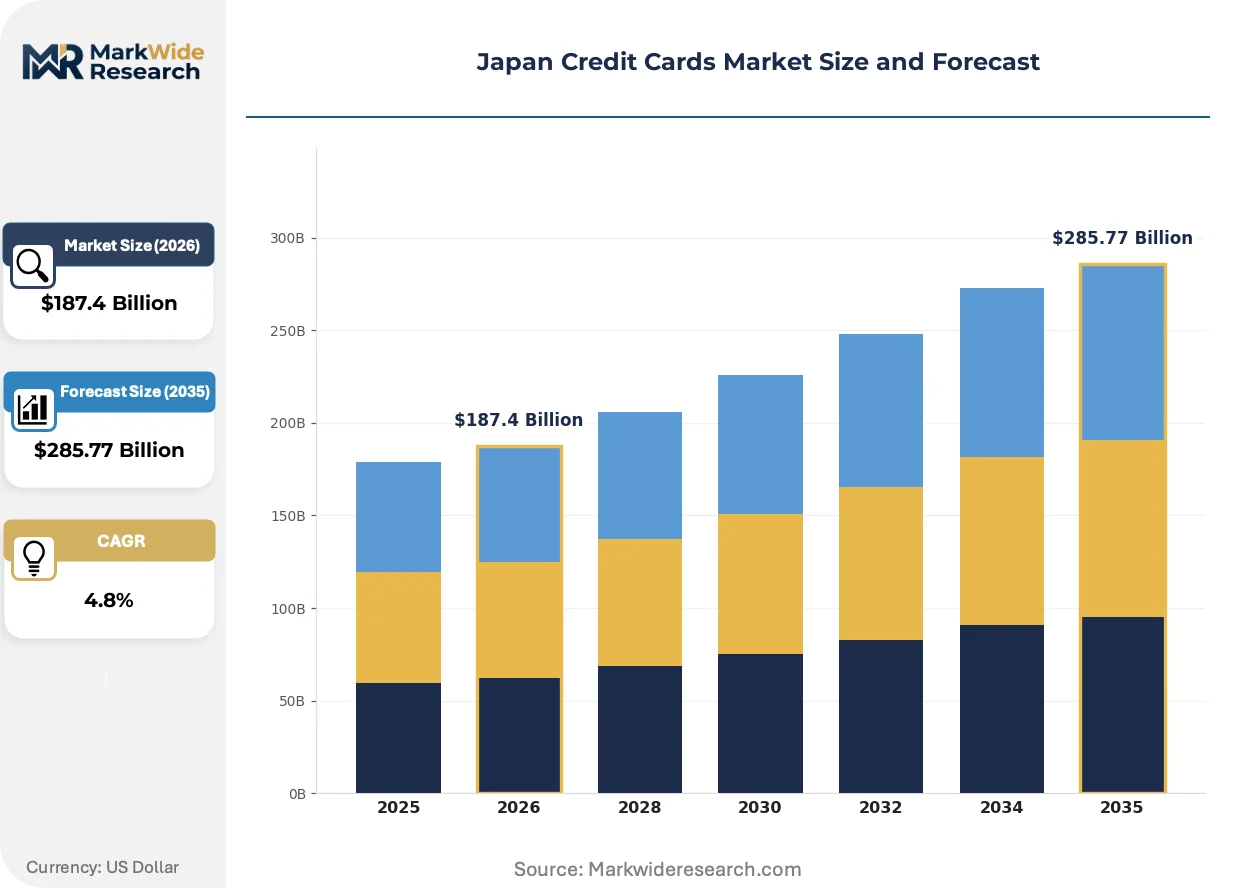
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Standard, Premium, Business, Co-branded Customer Type: Students, Working Professionals, Retirees, Small Business Owners Usage Occasion: Everyday Purchases, Travel, Online Shopping, Special Events Loyalty Program: Cashback, Travel Rewards, Points-based, Exclusive Discounts |
| Companies Covered | JCB Co. Ltd., Mitsubishi UFJ NICOS Co., Ltd., Sumitomo Mitsui Card Co., Ltd., Rakuten Card Co., Ltd., AEON Credit Service Co., Ltd., Credit Saison Co., Ltd., Orico (Orient Corporation), Seven Card Service Co., Ltd., PayPay Card Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Credit Cards Market Trends and Innovations
Payment infrastructure in Japan is undergoing a fundamental reconfiguration as regulatory incentives, biometric authentication, and transit ecosystem lock-in reshape how consumers and merchants interact with deferred settlement instruments.
Biometric authentication is absorbing transaction authorization workflows across premium card tiers. Issuers are embedding fingerprint and facial recognition into EMV chip interfaces for high-value purchases. Business travelers and affluent consumers are adopting these instruments fastest, compressing fraud-related chargeback costs while raising compliance burdens under data protection frameworks.
METI's phased rebate program is mandating merchant terminal upgrades while subsidizing interchange fee absorption. Small retailers in the Greater Tokyo corridor are deploying contactless readers to capture government-matched consumer incentives. Traditional cash-heavy sectors including hospitality and personal services are responding by formalizing electronic settlement relationships.
Working professionals are consolidating daily expenditure onto transit-linked payment instruments. Commuter behavior in dense metropolitan networks is displacing single-purpose cash transactions with multi-modal wallet usage. This pattern concentrates most visibly in the Tokyo-Osaka corridor where rail operator payment ecosystems overlap with retail acceptance density.
Japan Credit Cards Market Segmentation
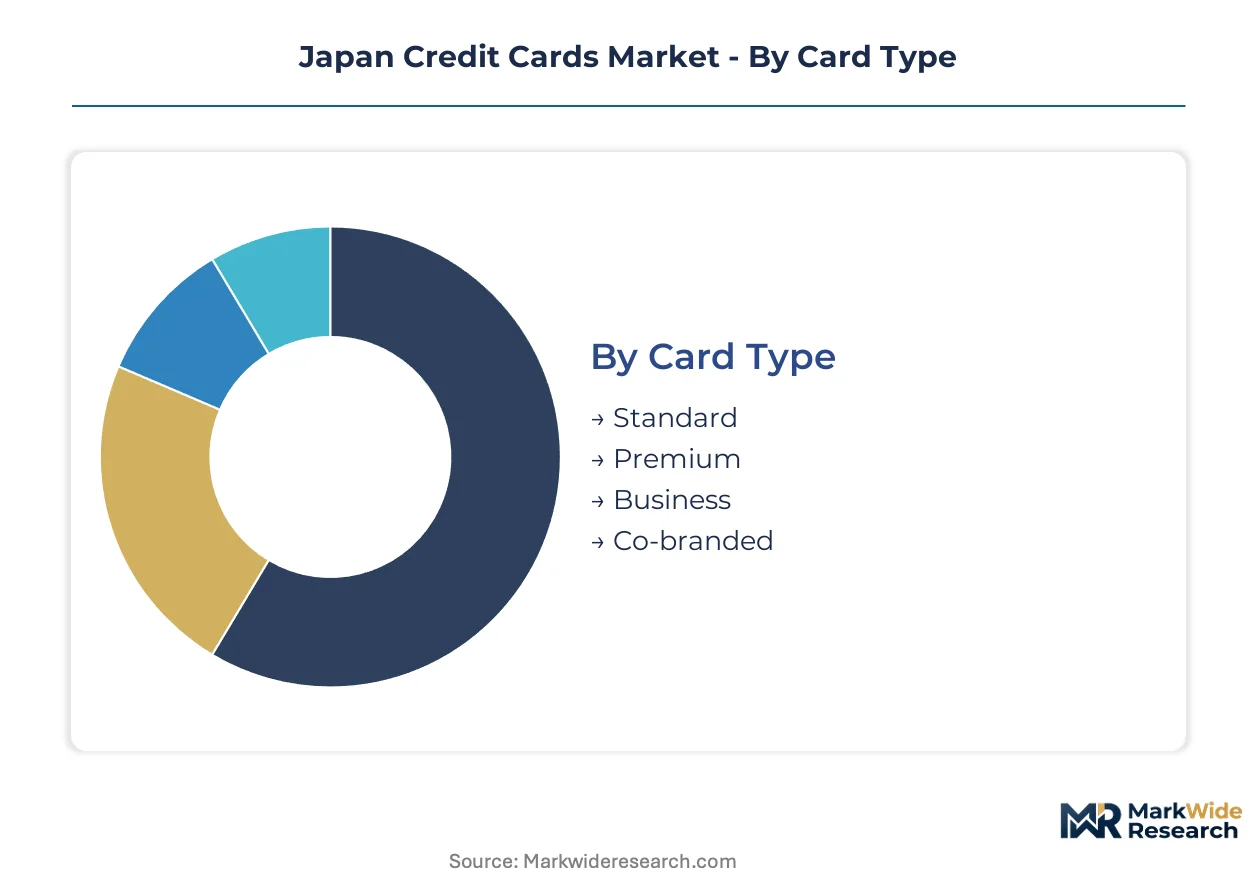
Japan's credit card landscape fragments across payment behavior, customer life stage, and reward architecture. Issuers calibrate product design against these dimensions to capture interchange volume while managing acquisition costs and portfolio risk.
Card Type:
Volume concentration rests with mass-market products, while premium tiers generate disproportionate fee-based yield per account.
- Standard:Basic revolving instruments with EMV chip and contactless NFC interfaces. Demand concentrates among working professionals in the Greater Tokyo corridor where transit-integrated payment ecosystems normalize daily contactless usage. METI's cashless rebate program accelerates merchant acceptance infrastructure for this tier.
- Premium:High-annual-fee products embedding biometric authentication and airport lounge access. Deployment clusters among affluent consumers in Osaka and Nagoya metropolitan zones where international travel recovery drives corridor-specific partnership investments. JFSA prudential guidelines constrain pricing freedom on interest spreads.
- Business:Expense separation instruments for sole proprietorships and small enterprises. Demand is expanding most quickly as formal enterprise structures displace personal account commingling.
- Co-branded:Retail and airline partnership cards dominating transaction volume through ecosystem lock-in. Deployment concentrates where rail operator payment networks overlap with retail acceptance density.
Mature deployment sits with Standard products. Newer deployment is concentrated in Business cards.
Customer Type:
Acquisition economics vary sharply across life stage and income stability profiles.
- Working Professionals:Salaried employees with card-linked wage accounts through digital payroll disbursement. Demand concentrates in dense metropolitan networks where commuter behavior absorbs daily expenditure into multi-modal wallet usage. Digital salary normalization accelerates embedded payment relationships.
- Small Business Owners:Sole proprietors formalizing expense separation from personal accounts. Deployment clusters in commercial corridors where METI cashless vision framework subsidies reduce merchant terminal upgrade costs. This segment is climbing the fastest as enterprise formalization advances.
- Students:Limited-credit-history applicants with parental guarantee structures. Demand concentrates in university towns with transit-linked campus retail ecosystems.
- Retirees:Fixed-income holders with conservative revolving patterns. Deployment favors established issuers with deposit-funded cost advantages.
Mature deployment sits with Retirees. Newer deployment is concentrated in Small Business Owners.
Usage Occasion:
Transaction context determines authorization infrastructure and fraud management requirements.
- Everyday Purchases:Transit-integrated contactless settlement for commuter and convenience retail expenditure. Demand concentrates in the Tokyo-Osaka corridor where Suica and Pasmo ecosystem penetration displaces single-purpose cash transactions.
- Travel:Cross-border transactions requiring dynamic currency conversion and lounge access authentication. Deployment clusters at international gateway airports where premium tier partnerships capture outbound tourism recovery.
- Online Shopping:E-commerce checkout with tokenized credentials and one-click enrollment. Demand is expanding most quickly as Rakuten and ecosystem-integrated platforms reinforce card-centric relationships.
- Special Events:High-value occasion spending with temporary credit limit adjustments. Deployment concentrates in hospitality corridors with seasonal demand spikes.
Mature deployment sits with Everyday Purchases. Newer deployment is concentrated in Online Shopping.
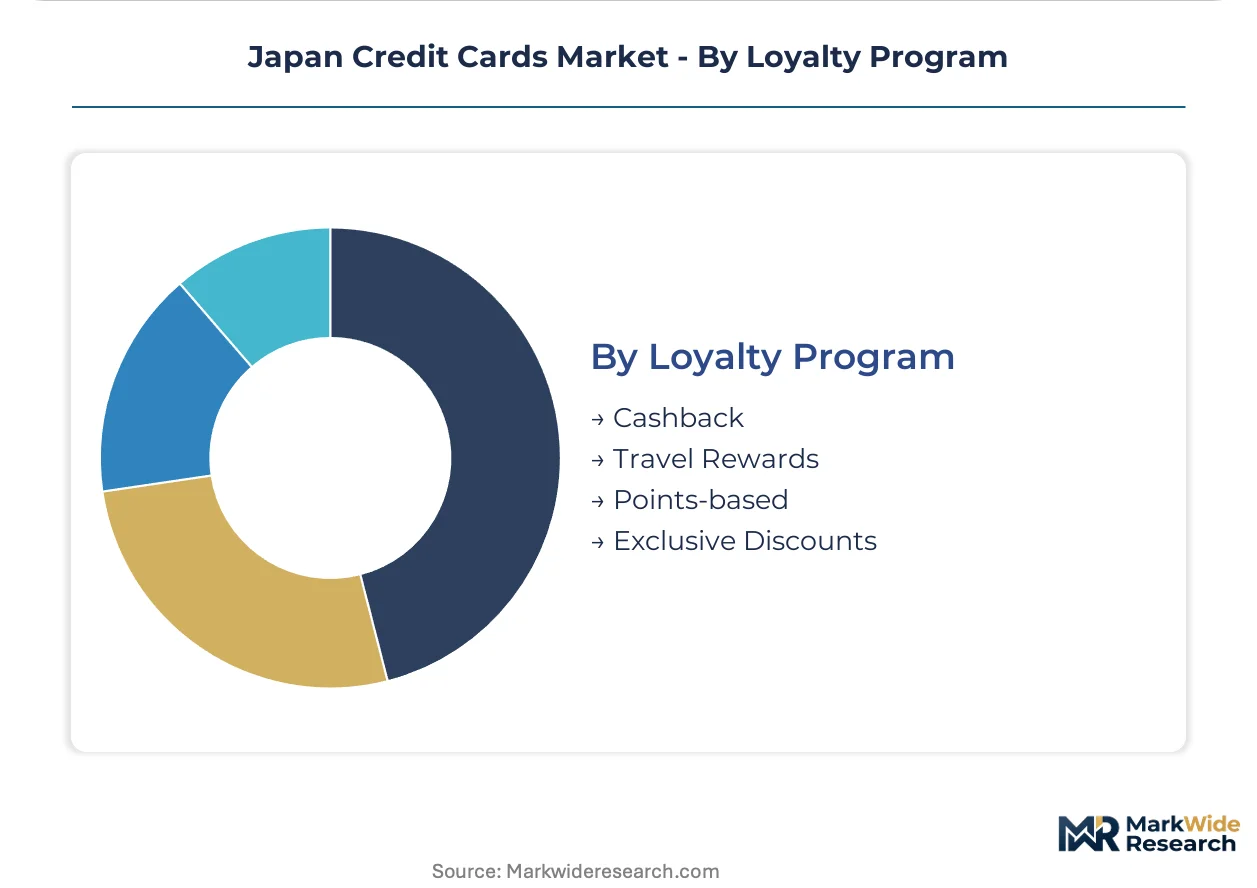
Loyalty Program:
Reward architecture determines customer lifetime value and portfolio switching costs.
- Points-based:Accumulation currencies redeemable across retail and travel networks. Demand concentrates where ecosystem-integrated issuers bundle card rewards with e-commerce and travel platforms.
- Cashback:Statement credit mechanisms with transparent earning rates. Deployment clusters among price-sensitive working professionals in metropolitan corridors with high transaction frequency.
- Travel Rewards:Airline mile accrual and hotel status matching. Demand is expanding most quickly as outbound tourism recovery accelerates premium corridor competition.
- Exclusive Discounts:Merchant-specific promotional rates and early access privileges. Deployment concentrates in co-branded retail partnerships with dense physical network presence.
Mature deployment sits with Points-based programs. Newer deployment is concentrated in Travel Rewards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Greater Tokyo metropolitan corridor, where transit-integrated payment ecosystems and dense retail networks create self-reinforcing card usage loops. Working professionals in this zone normalize daily contactless expenditure through Suica-linked wallets. Merchant acceptance infrastructure expands fastest where METI cashless subsidies overlap with commuter rail density.
Kanto/Tokyo
Working professionals with digital salary disbursement drive issuance volume through embedded bank partnerships. METI's phased rebate program mandates contactless terminal deployment across convenience retail and hospitality corridors. The Tokyo-Osaka Shinkansen corridor concentrates co-branded airline card acquisition at Narita and Haneda gateway airports.
Kansai/Osaka
Small business formalization accelerates commercial card demand among sole proprietorships separating expense accounts. JFSA prudential guidelines constrain independent issuer pricing freedom while expanding merchant subsidy eligibility. The Osaka-Nagoya industrial belt shows premium travel card recovery tied to outbound tourism corridor investments.
Chubu/Nagoya
Automotive sector wage digitization embeds card-linked payroll relationships among manufacturing professionals. The Personal Information Protection Commission enforces biometric data localization standards that elevate domestic processing costs. Nagoya's retail density supports transit-wallet penetration into traditional cash-dominated personal services sectors.
Kyushu
Regional bank consolidation shifts credit portfolio funding toward parent deposit bases in Fukuoka metropolitan clusters. METI cashless vision framework subsidies reduce merchant terminal upgrade barriers in hospitality corridors. Fukuoka's startup ecosystem experiments with open banking API convergence under amended Banking Act provisions.
Hokkaido
Seasonal tourism demand spikes create temporary credit limit adjustment patterns in Sapporo hospitality networks. Data localization mandates elevate cloud processing costs for issuers serving dispersed rural merchant acceptance points. Sapporo's retail concentration shows lagging contactless penetration relative to Honshu metropolitan benchmarks.
Japan Credit Cards Market Competitive Landscape
Tokyo-based banking conglomerates anchor one tier; Osaka and Nagoya specialists hold regional co-branding positions. The market structure reflects parent-bank deposit funding concentration alongside ecosystem-integrated platform competition. Three archetypes dominate: deposit-funded revolving credit issuers, transit-wallet ecosystem operators, and e-commerce platform bundlers. Competitive moves center on open banking API partnerships and biometric authentication infrastructure outsourcing.
Within the deposit-funded tier, Mitsubishi UFJ NICOS Co., Ltd. and Sumitomo Mitsui Card Co., Ltd. occupy positions shaped by parent bank balance sheet access. Rakuten Card Co., Ltd. represents the ecosystem-integrated archetype, bundling card rewards with platform commerce relationships. These three entities exemplify how funding structure and distribution channel ownership determine competitive positioning in a regulatory environment that constrains interchange pricing freedom.
| Leading Market Players |
|---|
| JCB Co. Ltd. |
| Mitsubishi UFJ NICOS Co., Ltd. |
| Sumitomo Mitsui Card Co., Ltd. |
| Rakuten Card Co., Ltd. |
| AEON Credit Service Co., Ltd. |
| Credit Saison Co., Ltd. |
| Orico (Orient Corporation) |
| Seven Card Service Co., Ltd. |
| PayPay Card Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive deposit funding through parent bank balance sheets anchors both cost structures and pricing power across Japan's credit card market. Mitsubishi UFJ NICOS and Sumitomo Mitsui Card leverage this vertical integration to sustain below-market revolving credit yields while smaller issuers face margin compression from outsourced processing costs.
Pricing Analysis
Volume concentration in standard-tier products subsidizes margin capture in premium and business segments. Pricing stratifies across biometric-enabled premium offerings, transit-linked standard instruments, and expense-separated commercial cards. Cost compression in the standard tier intensifies because METI's interchange subsidies constrain issuer pricing freedom. Small business owners exhibit highest price sensitivity; affluent travelers with lounge access demands show lowest.
Supply Chain Analysis
Workforce availability in domestic data centers and cloud processing facilities constrains infrastructure scaling across Tokyo, Osaka, and Fukuoka clusters. EMV chip manufacturing draws from Taiwan and South Korea; NFC antenna components source from China and Japan. Single-source vulnerability in biometric authentication modules elevates procurement risk. Distribution runs through bank branch networks, e-commerce platform integrations, and transit authority partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's credit card market sits in a contactless-transition phase as NFC-enabled instruments displace magnetic-stripe legacy infrastructure. Biometric authentication integration is accelerating this replacement cycle across premium product tiers.
For Market Incumbents: Acquire biometric authentication infrastructure capabilities to defend against fintech platform encroachment. Sumitomo Mitsui Card's premium travel corridor investments demonstrate how partnership density creates switching costs. Deposit-funded issuers should deepen captive processing control to offset data localization cost premiums imposed by Personal Information Protection Commission mandates.
For New Entrants and Emerging Players: Launch via open banking API partnerships to access transaction data streams without legacy infrastructure burdens. Business card formalization among sole proprietorships offers the most penetrable white space; METI merchant subsidies reduce terminal deployment friction in this segment. Target commercial corridors in Osaka and Nagoya where small enterprise density exceeds incumbent coverage intensity.
For Investors and Strategic Acquirers: Exit pathways concentrate in ecosystem-integrated platform acquisitions by banking conglomerates seeking deposit-linked payment relationships. Long-term viability favors issuers with parent-bank funding access and transit-wallet ecosystem penetration. Watch biometric compliance cost escalation as the signal for consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Infrastructure | Fingerprint and facial recognition deployment reduces fraud chargeback costs at Narita gateway corridors. |
| Open Banking API Partnership | Amended Banking Act provisions enable enriched data services reinforcing card-centric customer relationships. |
| Transit-Wallet Ecosystem Integration | Suica and Pasmo penetration absorbs daily commuter expenditure into contactless payment rails. |
| Business Card Product Launch | Expense separation instruments capture sole proprietorship formalization in Osaka commercial corridors. |
| Premium Travel Corridor Investment | Airport lounge partnerships capture outbound tourism recovery at Haneda and Narita international gateways. |
Research Methodology
Independent corroboration across card issuer product executives, transit authority payment specialists, and merchant acquiring managers underwrites the qualitative findings. Secondary validation sources include JFSA prudential guideline disclosures, METI cashless vision framework documentation, and Personal Information Protection Commission enforcement records. Bottom-up transaction volume modeling and top-down macroeconomic anchoring ensure analytical consistency.
Comparable-period anchoring to historical cashless rebate program phases structured the forecast window across the projection horizon. Segmentation dimensions modeled include card type tier, customer life stage, usage occasion context, and loyalty program architecture. CAGRs were derived from issuer portfolio growth trajectories and transit ecosystem penetration curves, with digital salary disbursement normalization and biometric authentication adoption rates as key forecast inputs.
Regulatory enforcement intensity, interchange subsidy program renewal, and biometric infrastructure cost trajectories are the dominant revision risks. Forecasts reflect assumptions about METI policy continuity and parent-bank funding stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Voice-Based Payments Market
Payments
B2B Payments Platform Market
Payments
South Korea POS Terminals Market
Payments
China Payment Gateway Market
Payments
Latin America Subscription and Billing Management Market
Payments
Clearing Houses and Settlements Market
Payments
GCC Payment Gateway Market
Payments
India Payment Gateway Market
Payments
Enterprise Payment Software Market
Payments
Canada Mobile Payments Market
Payments
Denmark Payments Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Transit Cards Market
Payments
Cross-Border Payment Platform Market
Payments
Bill Splitting Apps Market
Payments
Europe Gift Card and Incentive Card Market