
 United States Payments Market | 2026-2036
United States Payments Market Size, Share, and Industry Trends Forecast 2026-2036
United States Payments Market Analytics
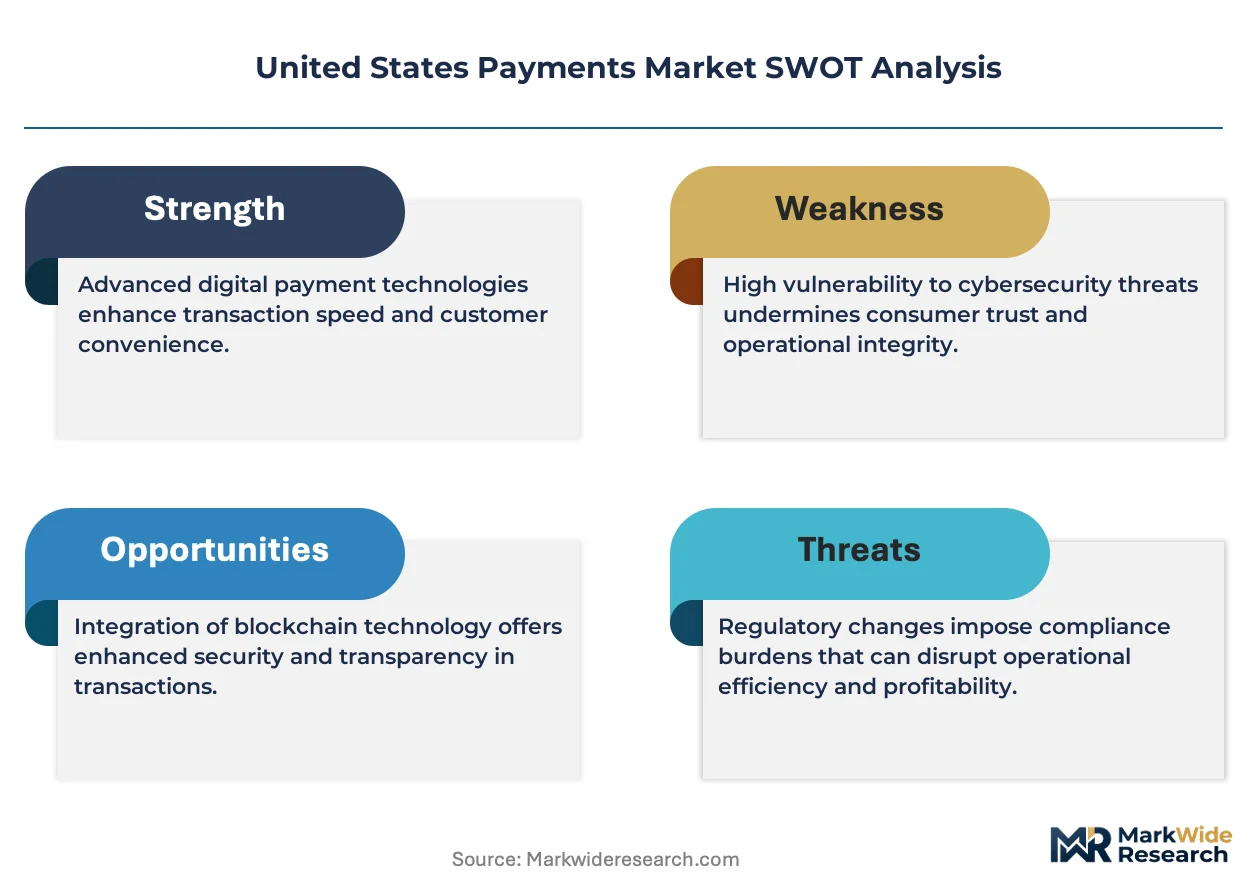
Embedded finance bundling is expanding across merchant services, payroll, and lending into unified platforms that reduce buyer procurement friction. Stripe leverages developer-first API architecture to anchor its position in software-integrated checkout flows. Mastercard sustains network dominance through tokenization standards that secure card-not-present transactions. Fiserv competes via banking core modernization that positions it as infrastructure for regional and community financial institutions.
Payments systems encompass the technological infrastructure, protocols, and intermediary networks that enable value transfer between transacting parties, operating through authorization, clearing, and settlement stages with sub-second latency requirements for real-time rails. These systems serve commercial purpose by replacing cash-based exchange with traceable, reversible, and programmatically accessible fund movements that underpin modern commerce. Credit cards and digital wallets capture the dominant share of consumer-facing transaction volume, while bank transfers gain ground in B2B and recurring billing contexts where lower interchange costs justify slower settlement. Contactless payment technology leads physical retail adoption, though mobile payment architectures are displacing card-present hardware in small merchant environments.
The Federal Reserve shapes market structure through FedNow pricing and participation rules that determine which institutions can offer instant settlement. The Consumer Financial Protection Bureau enforces disclosure and fairness standards that constrain fee architectures in consumer-directed products. The Office of the Comptroller of the Currency governs national bank charters for fintech entities seeking direct access to payment rails without sponsor bank dependency. Stakeholders must monitor how regulatory clarity on stablecoin classification and state money transmission licensing convergence will reshape competitive access costs.
Market Dynamics
FedNow's instant settlement infrastructure is compressing transaction timelines from days to seconds, forcing incumbents to rebuild core systems around real-time clearing expectations rather than batch processing.
Growth Catalysts
- Small business digitization:Merchant services platforms embed payment acceptance into accounting and payroll workflows, reducing friction for sole proprietors and micro-enterprises.
- CFPB disclosure mandates:Standardized fee presentations enable consumer comparison shopping, accelerating migration from high-cost legacy products to transparent alternatives.
- Contactless hardware deployment:NFC terminal penetration in physical retail removes checkout friction, driving tap-to-pay volume expansion across suburban and exurban markets.
Market Restraints
- Interchange cost compression:Durbin Amendment caps on debit swipe fees constrain issuer revenue models, limiting reinvestment in fraud prevention infrastructure.
- Sponsor bank dependency:Fintechs without direct OCC charters rely on partner banks for rail access, creating concentration risk and operational friction.
- Cash substitution ceiling:Rural and unbanked populations in Appalachia and the Deep South retain paper-based preferences, capping digital penetration rates.
Strategic Opportunities
- B2B instant settlement:FedNow adoption by regional banks unlocks working capital optimization for manufacturing and logistics supply chains.
- Payroll-integrated lending:Earned wage access products embed repayment through direct deposit routing, reducing default risk.
- State licensing harmonization:Convergence of money transmission requirements across California, Texas, and New York reduces compliance overhead for national deployment.
Industry Challenges
- Core system modernization:Regional banks face multi-year COBOL migration timelines to connect real-time rails without service interruption.
- Fraud model recalibration:Instant settlement eliminates chargeback windows, requiring behavioral analytics investment to replace delayed verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Payments Market |
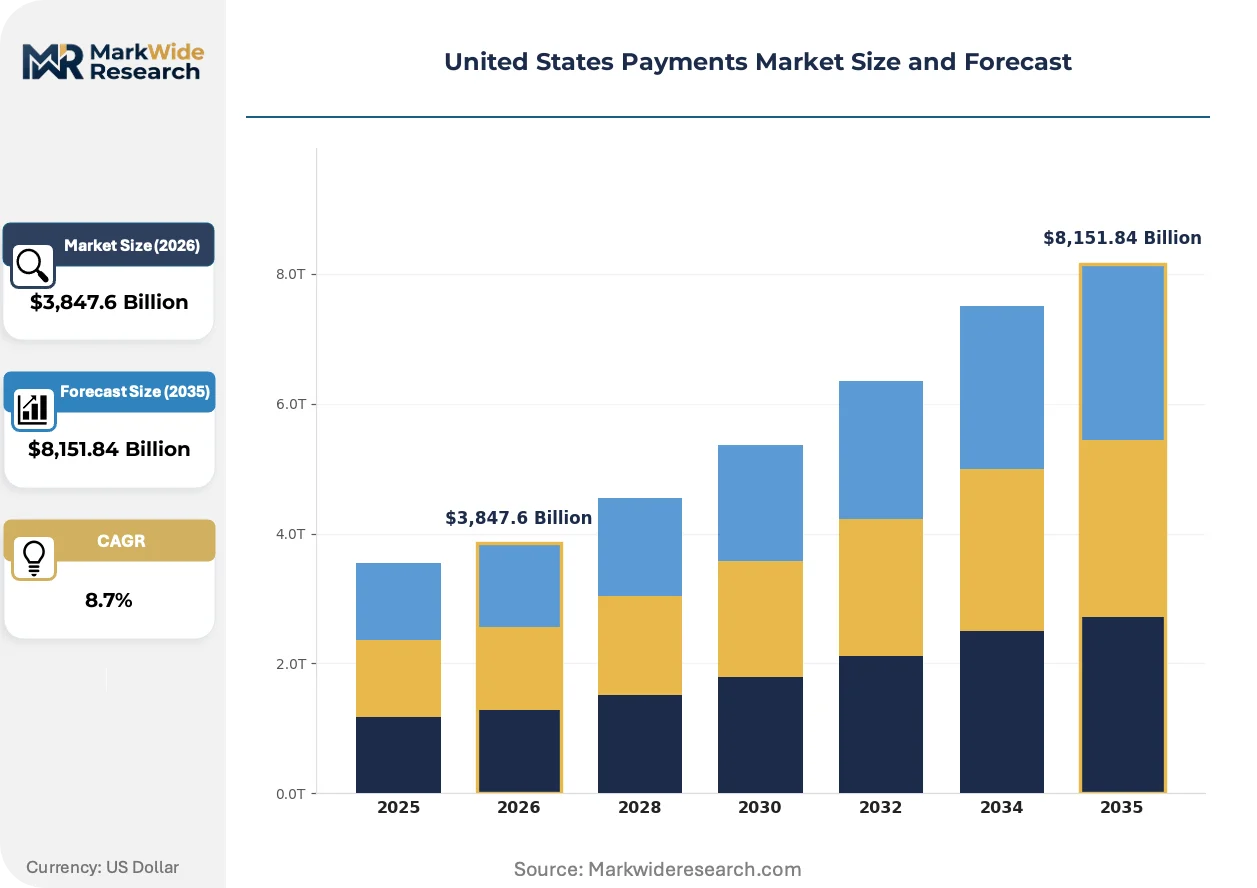
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $8,151.84 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Digital Wallets, Bank Transfers Transaction Size: Microtransactions, Small Transactions, Medium Transactions, Large Transactions Customer Type: Consumers, Merchants, Corporates, Government Agencies Technology: Contactless Payment, Mobile Payment, E-commerce Payment, In-store Payment |
| Companies Covered | Mastercard, Fiserv, Stripe, Plaid, Rapyd Financial Network, PayPal, Adyen, Nium, Block (Square), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Payments Market Evolving Landscape
Real-time infrastructure investment is reshaping product architecture across issuing, acquiring, and treasury services, with velocity replacing float as the primary value driver.
Artificial intelligence in transaction monitoring is automating anomaly detection at authorization endpoints. Large issuers deploy machine learning models that score risk in milliseconds, reducing false declines while maintaining fraud loss ratios. This compression of decision windows is automating the shift from rules-based to behavioral scoring across card-not-present environments.
The Federal Reserve's FedNow pricing framework determines which institutions can offer instant settlement at viable unit economics. Community banks and credit unions face participation thresholds that favor larger balance-sheet institutions. Smaller depositories are responding through correspondent arrangements and core processor partnerships to access real-time rails without direct FedNow connectivity.
Buyer expectations for seamless fund availability are reshaping vendor selection criteria in payroll and accounts payable. Corporate treasurers now prioritize same-day settlement over float optimization, displacing traditional wire and ACH scheduling. This preference shift is most visible in technology and professional services verticals concentrated in Austin and Seattle metropolitan clusters.
United States Payments Market Segmentation
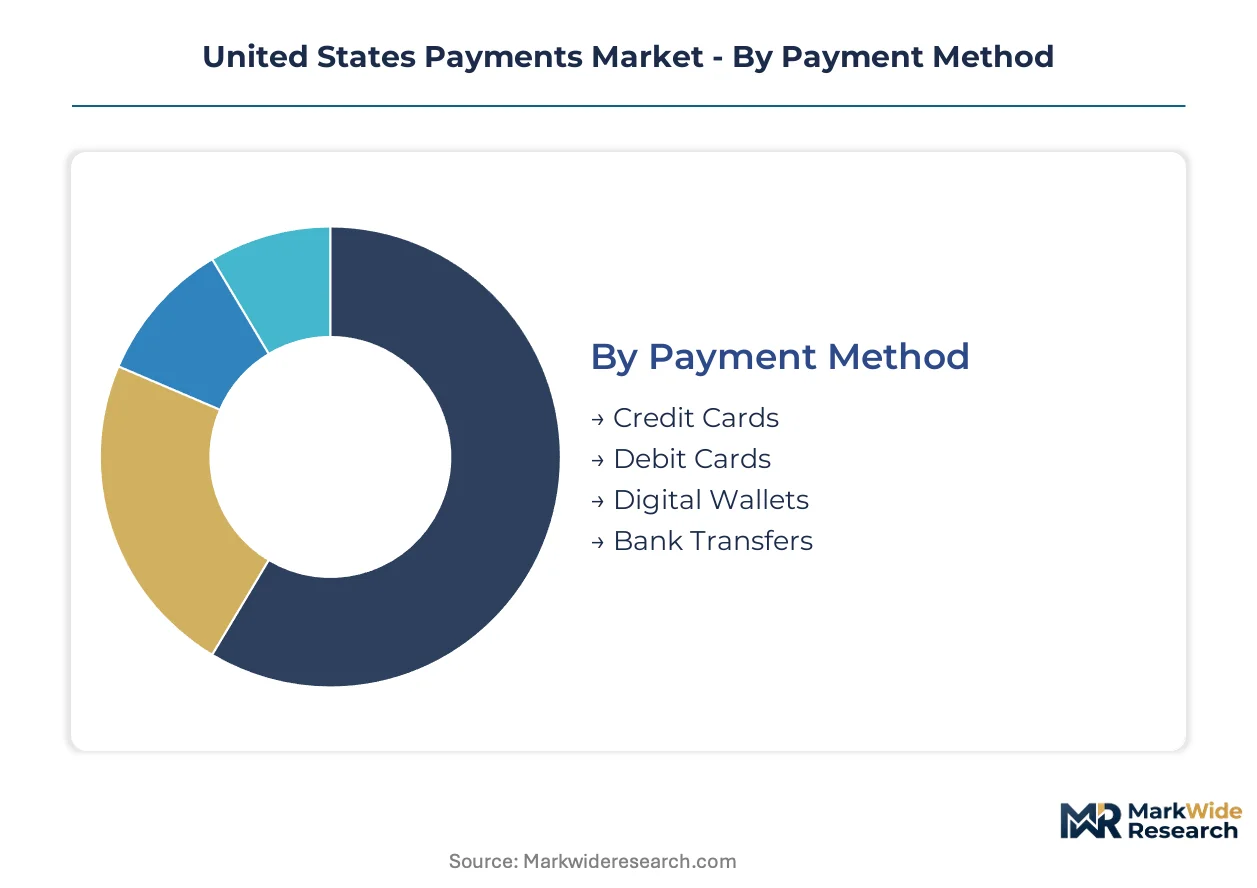
Payment method diversity creates distinct infrastructure requirements, fraud model architectures, and interchange economics across the United States. Transaction velocity expectations and settlement timelines vary sharply by segment, forcing platform providers to modularize their technology stacks.
Payment Method:
Buyer differentiation hinges on credit appetite, reward sensitivity, and access to banking infrastructure.
- Credit Cards:Revolving credit instruments with interchange-funded reward programs dominate discretionary consumer spending. Demand concentrates in travel, hospitality, and premium retail verticals where cardholders chase point multipliers and lounge access benefits.
- Digital Wallets:Tokenized credential storage with biometric authentication enables one-click checkout across merchant environments. California's technology corridor and New York's financial district anchor adoption, driven by transit integration and split-payment features among younger demographics.
- Debit Cards:Direct checking account access with Durbin-capped interchange constrains issuer profitability. Demand clusters in grocery, fuel, and essential retail where budget-conscious households avoid credit utilization.
- Bank Transfers:ACH and wire rails deliver lower-cost settlement for B2B invoices and recurring billing. Manufacturing supply chains in the Midwest and logistics operations across Texas favor this method for working capital preservation.
Volume sits with credit cards; growth tilts toward digital wallets.
Transaction Size:
Settlement risk tolerance and authentication rigor scale inversely with transaction magnitude.
- Microtransactions:Sub-dollar payments for digital content, parking meters, and vending machines demand minimal friction. Gaming platforms and transit authorities in Seattle and Austin deploy these for impulse purchases where card-present overhead is prohibitive.
- Large Transactions:Corporate treasury movements, real estate closings, and capital equipment purchases require multi-factor verification and delayed settlement windows. Commercial banking relationships in Chicago and Boston anchor this segment.
- Small Transactions:Everyday retail purchases between ten and one hundred dollars represent the volume backbone of merchant acquiring.
- Medium Transactions:B2B services, professional fees, and wholesale procurement occupy the interchange optimization zone.
Authentication intensity rises with transaction size; instant settlement demand concentrates at the micro end.
Customer Type:
Payment acceptance infrastructure investment and working capital sensitivity separate commercial participants.
- Merchants:Small businesses and retail chains prioritize interchange cost reduction and chargeback protection. Suburban and exurban markets outside Atlanta and Phoenix drive contactless terminal deployment for checkout speed.
- Corporates:Treasury departments demand API-integrated payables automation and real-time cash position visibility. Technology and professional services firms in Austin and Seattle metropolitan clusters lead FedNow adoption for supplier payments.
- Consumers:Individual payers balance convenience against privacy concerns and reward optimization.
- Government Agencies:Federal, state, and municipal entities require certified procurement systems with audit trails and compliance documentation.
Merchant transaction volume dominates; corporate instant settlement adoption is climbing fastest.
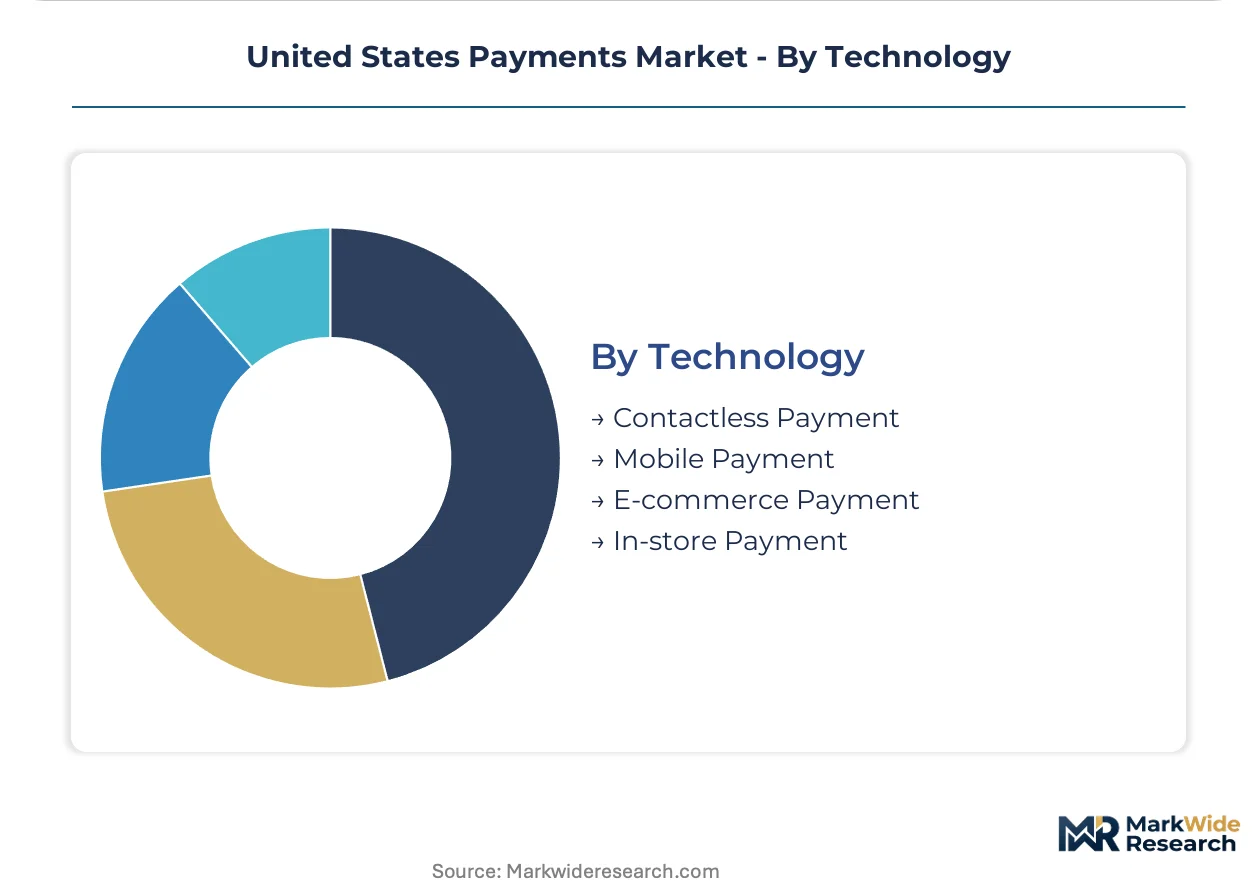
Technology:
Hardware presence versus software-native architecture determines deployment capital requirements and merchant onboarding friction.
- Mobile Payment:Smartphone-based NFC and QR code acceptance eliminates dedicated terminal investment for micro-merchants. Food trucks, farmers markets, and solo practitioners across Portland and Nashville favor this for zero upfront hardware cost.
- Contactless Payment:Tap-to-pay cards and wearable devices deliver sub-second authorization at physical point-of-sale. Suburban retail corridors in Florida and Texas show the steepest terminal penetration curves.
- E-commerce Payment:Browser and app-based checkout flows with tokenized credential storage.
- In-store Payment:Traditional card-present transactions with chip and magnetic stripe fallback.
Contactless captures current volume; mobile payment infrastructure is expanding most quickly among new merchant entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure investment concentrates on the coasts while adoption velocity spreads inland. Production of fintech platforms and developer tools clusters in specific metropolitan corridors. Consumption of merchant services and consumer payment products distributes more broadly across suburban and rural markets.
California
Software-integrated checkout flows and developer-first API architectures dominate demand in the San Francisco Bay Area and Los Angeles basin. The California Department of Financial Protection and Innovation enforces money transmission licensing that shapes fintech market entry costs. Stripe anchors its headquarters in San Francisco, while venture-backed payment startups cluster in Palo Alto and Santa Monica.
New York
Tokenization standards and card-not-present security protocols drive institutional procurement in Manhattan's financial district. The New York State Department of Financial Services administers BitLicense and money transmitter regulations that constrain stablecoin and digital asset payment integration. JPMorgan Chase and Mastercard maintain extensive payment technology operations in the New York metro area.
Texas
Banking core modernization and regional bank technology procurement concentrate demand in Dallas and Houston. The Texas Department of Banking governs state-chartered bank partnerships that enable fintech rail access without direct federal chartering. Fiserv competes aggressively for community bank contracts across the Dallas-Fort Worth corridor.
Illinois
Commercial treasury services and B2B instant settlement adoption accelerate among Chicago-headquartered manufacturers and logistics operators. The Illinois Department of Financial and Professional Regulation oversees state-level money transmission compliance that affects payroll-integrated lending products. The Chicago metropolitan area anchors corporate payment automation demand across the Midwest.
Washington
Mobile payment architecture and contactless terminal deployment spread rapidly among Seattle's technology workforce and small merchant base. The Washington State Department of Financial Institutions enforces consumer protection standards that constrain earned wage access product fee structures. Amazon's headquarters presence drives innovation in one-click checkout and biometric authentication adoption.
United States Payments Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across network infrastructure, merchant acquiring, and software-integrated payments. The market exhibits tiered concentration where card networks and core processors occupy consolidated positions while fintech infrastructure remains fragmented. Three archetypes dominate: developer-first platform providers, legacy banking core modernizers, and network tokenization standard-setters. Strategic moves center on API ecosystem expansion and sponsor bank partnership consolidation to reduce rail access friction.
Within the developer-first platform tier, Stripe exemplifies software-integrated checkout specialization. Among legacy infrastructure providers, Fiserv anchors community and regional bank modernization. On the network standards vector, Mastercard occupies the tokenization and card-not-present security position. These three represent distinct competitive approaches to capturing merchant and institutional payment flows.
| Leading Market Players |
|---|
| Mastercard |
| Fiserv |
| Stripe |
| Plaid |
| Rapyd Financial Network |
| PayPal |
| Adyen |
| Nium |
| Block (Square) |
| Others |
Value Network & Pricing Analysis
Developer-first platform premiums versus legacy core-processor commoditization bifurcates the United States payments landscape, with API-integrated checkout flows commanding subscription-based pricing while batch-processing infrastructure faces per-transaction compression. This divergence manifests in supply chain configurations where cloud-native orchestration layers draw from hyperscaler data centers, whereas regional bank core systems remain tethered to on-premise COBOL maintenance networks.
Pricing Analysis
Margin tightening in merchant acquiring reflects Durbin Amendment interchange caps and sponsor bank fee compression. Three-tier pricing structure across premium API access, standard gateway services, and economy acquiring separates Stripe's developer-centric subscriptions from Fiserv's per-transaction legacy models. Price differentiation hinges on integration speed and fraud prevention sophistication. Small merchants exhibit acute price sensitivity to hardware costs, while enterprise treasurers prioritize settlement velocity over unit economics.
Supply Chain Analysis
Logistics and freight costs are negligible in digital payment infrastructure, shifting supply chain risk to data center concentration and fiber latency. Cloud computing capacity concentrates in Northern Virginia, Oregon, and Iowa hyperscaler campuses. Critical dependencies include NVIDIA GPU clusters for fraud analytics, tokenization hardware security modules, and FedNow rail connectivity. Single-source vulnerability rests on AWS and Azure dominance for payment orchestration. Distribution runs through API marketplaces and direct enterprise sales channels rather than physical logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States payments market sits in a technology-transition phase where FedNow instant settlement rails are displacing legacy ACH batch infrastructure. Real-time clearing protocols now define competitive viability across issuing, acquiring, and treasury services.
For Market Incumbents: Anticipate core system obsolescence by accelerating COBOL migration timelines and embedding behavioral analytics for instant-settlement fraud prevention. Sponsor bank consolidation threatens fintech-dependent revenue streams; direct OCC charter pursuit or correspondent partnership deepening represent critical defensive levers. Regional banks must prioritize FedNow connectivity through core processor alliances. For New Entrants and Emerging Players: Enter via earned wage access and payroll-integrated lending products where regulatory clarity remains nascent and incumbent coverage is sparse. Community banks and credit unions facing FedNow participation thresholds represent the most penetrable client segment. A white-label banking-as-a-service go-to-market angle bypasses direct rail access requirements. For Investors and Strategic Acquirers: Re-rating potential sits with developer-first platform specialists given API ecosystem expansion and software-integrated checkout penetration. Long-term viability over the coming decade hinges on real-time infrastructure ownership rather than intermediary positioning. Monitor state money transmission licensing harmonization progress as the decisive inflection signal for national deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Rail Integration | Unlocks instant settlement capabilities for regional banks competing against money-center institutions. |
| API Ecosystem Expansion | Deepens developer lock-in through embedded finance bundling across payroll and lending workflows. |
| Core System Modernization | Replaces COBOL infrastructure with cloud-native architectures enabling real-time transaction processing. |
| Behavioral Analytics Investment | Substitutes chargeback windows with millisecond-risk scoring for instant-settlement environments. |
| Sponsor Bank Partnership Consolidation | Reduces operational friction and concentration risk for fintechs lacking direct OCC charters. |
Research Methodology
SEC 10-K filings, FedNow participation disclosures, and CFPB regulatory dockets formed the secondary backbone for market sizing and competitive positioning. Primary interviews with payment technology CTOs, regional bank treasury officers, merchant acquiring sales directors, and fintech compliance leads validated infrastructure adoption timelines and pricing dynamics. Bottom-up transaction volume modeling triangulated against top-down Federal Reserve payment system statistics.
Historical trendline analysis across payment method migration, real-time rail adoption curves, and interchange rate evolution informed the projection framework. Segmentation dimensions modeled include payment method, transaction size tier, customer archetype, and technology deployment mode. CAGRs were derived from velocity-adjusted adoption curves incorporating FedNow pricing elasticity and merchant digitization rates. Industry-specific inputs encompassed Durbin Amendment compliance costs and sponsor bank concentration indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory delays in stablecoin classification and state licensing harmonization failures. Forecasts reflect documented assumptions regarding FedNow participation thresholds and real-time fraud model maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Smart Bands Payments Market
Payments
Latin America Retail Cash Management Market
Payments
Payment Processing Solutions Market
Payments
South Korea Digital Payments Market
Payments
India POS Terminals Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
GCC Payment Gateway Market
Payments
Germany Payments Market
Payments
South Korea Mobile Payment Market
Payments
Europe Payment Analytics Software Market
Payments
Smart Home Payments Market
Payments
P2P Payment Market
Payments
Mobile Payment Security Software Market
Payments
Singapore Remittance Market
Payments
Hong Kong Credit Cards Market