
 Indonesia Life and Non-Life Insurance Market | 2026-2036
Indonesia Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Life and Non-Life Insurance Market Foresight
Digital-first policy tiers is rotating Indonesia's insurance market upward as mobile-enabled products replace paper-heavy traditional offerings. PT Prudential Life Assurance leverages its extensive agent network to sustain rural penetration while competing aggressively in urban centers. PT AIA Financial anchors the bancassurance channel through partnerships with major Indonesian banks. PT Asuransi Jiwa Sinarmas MSIG Tbk differentiates via sharia-compliant product lines that occupy a growing niche among Muslim policyholders.
Indonesia life and non-life insurance encompasses risk-pooling financial contracts where insurers collect premiums to cover mortality, morbidity, property damage, and liability exposures, with capital reserves regulated under risk-based solvency frameworks. The primary purpose centers on household financial protection and corporate risk transfer against catastrophic losses. Term life products lead the product type dimension due to lower premium barriers for first-time buyers, while health insurance within coverage type records the fastest expansion as medical cost inflation outpaces wage growth. Bancassurance dominates distribution channel economics, though direct sales is accelerating fastest among digitally native urban consumers.
OJK, Indonesia's financial services authority, enforces risk-based capital requirements and consumer protection standards that shape product design and market access for domestic and foreign insurers. BIS technical standards on data security and the country's national digital identity infrastructure influence insurer technology procurement and customer verification workflows. Stakeholders must monitor how OJK's sandbox regulations for insurtech entrants reshape competitive dynamics between established carriers and digital-native distributors.
Market Dynamics
OJK's digital transformation mandates are compressing product development cycles while forcing legacy insurers to rebuild core systems around mobile-first architectures. This regulatory pressure is fragmenting traditional distribution hierarchies and accelerating capital flows toward insurtech infrastructure.
Growth Catalysts
- Sharia-Compliant Product Expansion:Indonesia's Financial Services Authority (OJK) has streamlined takaful licensing frameworks, enabling faster product approval cycles for sharia-compliant life and health offerings that serve the country's majority Muslim population.
- Bancassurance Channel Deepening:Major Indonesian banks are embedding insurance products into retail lending and deposit workflows, creating embedded distribution touchpoints that reduce customer acquisition costs for participating carriers.
- Mobile Penetration:Smartphone adoption across Java and emerging urban centers is enabling direct-to-consumer policy issuance, bypassing traditional agent networks for simplified term life and micro-insurance products.
Market Restraints
- Actuarial Talent Scarcity:Indonesia produces insufficient qualified actuaries relative to carrier expansion plans, creating underwriting capacity bottlenecks and forcing reliance on foreign consulting arrangements.
- Claims Reserving Volatility:Medical cost inflation in Jakarta and Surabaya outpaces premium adjustment cycles, compressing health insurance margins and requiring more frequent repricing.
- Rural Distribution Economics:Agent commission structures designed for dense urban markets prove economically unworkable in outer island provinces, leaving significant population segments underserved.
Strategic Opportunities
- Micro-Insurance Penetration:Agricultural and informal sector workers in Sumatra and Sulawesi remain dramatically underpenetrated, creating white space for parametric weather and accident products distributed through mobile wallets.
- Insurtech Sandbox Participation:OJK's regulatory sandbox allows digital-native distributors to test AI-driven underwriting models with relaxed capital requirements during pilot phases.
- Telemedicine Integration:Convergence of health insurance with remote diagnostic platforms enables preventive care riders that reduce claims frequency while differentiating product offerings.
Industry Challenges
- Legacy Core System Migration:Established carriers face multi-year integration timelines when replacing policy administration platforms, creating operational risk during parallel system operation.
- Fraud Detection Capability Gaps:Synthetic identity schemes and staged accident claims outpace rule-based detection systems, requiring investment in machine learning infrastructure that strains IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Life and Non-Life Insurance Market |
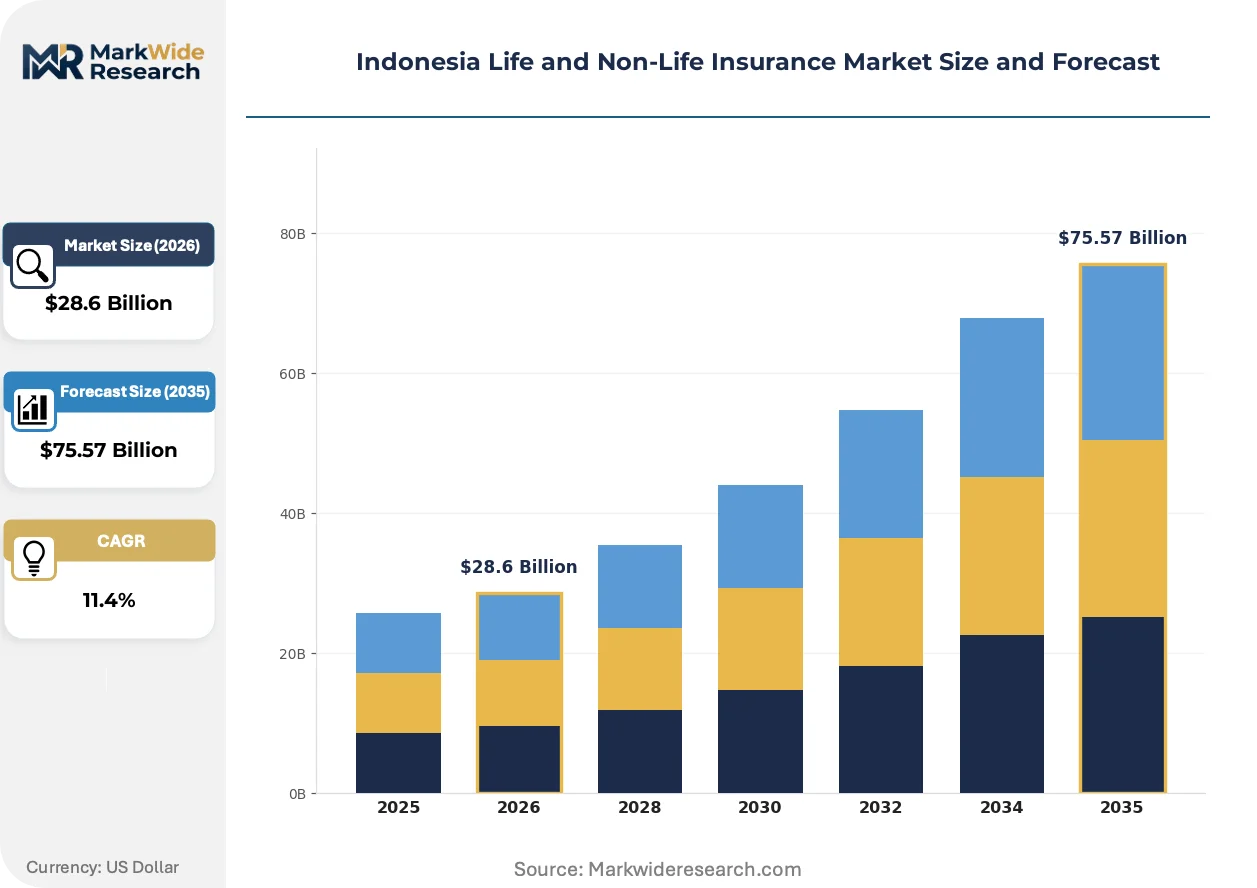
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Universal Life, Endowment Plan Coverage Type: Health Insurance, Property Insurance, Liability Insurance, Motor Insurance Distribution Channel: Bancassurance, Direct Sales, Agents, Brokers Policyholder Type: Individual, Corporate, SMEs, Government, Non-Profit |
| Companies Covered | PT Allianz Life Indonesia, PT Panin Financial Tbk, PT Prudential Life Assurance, PT Asuransi Tugu Pratama Indonesia Tbk, Asuransi Astra, PT AIA Financial, PT Asuransi Jiwa Sinarmas MSIG Tbk, BNI Life Insurance, PT Manulife Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Life and Non-Life Insurance Market Shifts & Advancements
Indonesia's insurance sector is experiencing a platform-level restructuring as digital distribution models disintermediate traditional agent hierarchies. Technology investments now concentrate on real-time data integration rather than back-office automation.
Artificial intelligence-driven underwriting engines are fragmenting risk assessment workflows across Indonesia's life insurance segment. Mid-tier carriers in Jakarta are deploying these systems to compress policy issuance from weeks to minutes for standardized term products. The structural consequence is fragmenting the traditional underwriter role into algorithmic decision layers and exception-handling specialists.
OJK's risk-based capital framework revisions are tightening liquidity reserve requirements for health and credit insurance lines. Domestic carriers must now hold additional capital against medical inflation exposure, particularly for group policies sold to corporate employers. The health segment is responding by accelerating reinsurance placement with regional partners to optimize capital efficiency.
Younger policyholders in Surabaya and Bandung are bypassing agent-mediated sales for direct digital comparison platforms. Aggregator sites now capture significant share of term life and motor insurance inquiries, compressing carrier control over pricing presentation. This channel shift is most visible among digitally native professionals purchasing supplemental health coverage outside employer-sponsored plans.
Indonesia Life and Non-Life Insurance Market Segmentation
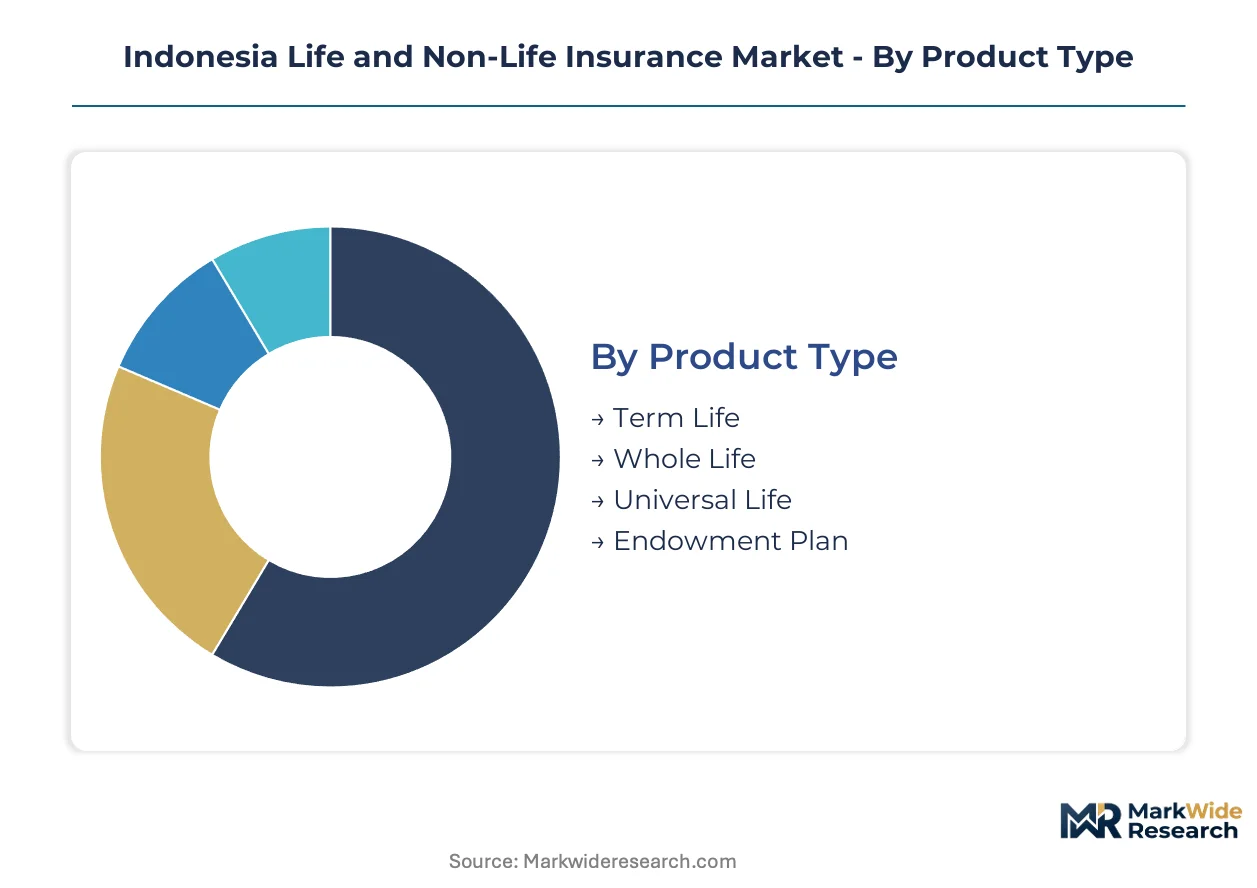
Segmentation in Indonesia's insurance market reveals how product design, channel economics, and policyholder risk profiles intersect. Each dimension shapes capital allocation, regulatory compliance requirements, and technology investment priorities for carriers operating across Java and the outer islands.
Product Type:
Channel-mix dynamics vary sharply across life insurance products, with bancassurance dominating endowment and whole life sales while direct digital channels capture term life volume.
- Term Life:Pure mortality coverage with fixed duration and no cash value accumulation. Demand concentrates among first-time buyers in Jakarta and Surabaya where digital comparison platforms reduce search costs and accelerate policy issuance.
- Whole Life:Permanent coverage combining guaranteed death benefit with conservative cash value growth. Bancassurance partnerships with state-owned banks drive penetration among middle-class households seeking forced savings mechanisms.
- Universal Life:Flexible premium and adjustable death benefit structures with market-linked cash value components. Agent networks in Bandung and Medan push these products for affluent clients requiring estate planning tools.
- Endowment Plan:Savings-linked contracts paying lump sums at maturity or death. Takaful-compliant variants gain traction through Islamic bank distribution channels serving Muslim policyholders in East Java.
Term life dominates installed base. Endowment plans are where expansion concentrates.
Coverage Type:
Premium tiers and claim frequency patterns differentiate non-life segments, with health and motor commanding distinct capital reserve treatments under OJK solvency rules.
- Health Insurance:Medical expense reimbursement and cashless hospitalization coverage. Claims frequency in Jakarta private hospitals outpaces premium adjustment cycles, compressing margins and forcing annual repricing.
- Property Insurance:Fire, natural catastrophe, and industrial asset coverage. Sumatra manufacturing corridors and Sulawesi mining operations generate commercial demand for parametric flood and earthquake riders.
- Liability Insurance:Professional indemnity and product liability protection. Corporate procurement in Surabaya's port logistics sector drives group policy uptake among shipping and warehousing operators.
- Motor Insurance:Own-damage and third-party liability for private and commercial vehicles. Smartphone-enabled claims submission accelerates adoption among ride-hailing drivers in Greater Jakarta.
Motor insurance dominates installed base. Health coverage is climbing the fastest.
Distribution Channel:
Customer acquisition economics and technology infrastructure requirements fragment Indonesia's insurance distribution landscape across legacy and emerging models.
- Bancassurance:Insurance products embedded within banking relationships through teller referrals and loan packaging. Mandiri and BCA partnerships anchor this channel, capturing salary-account holders with minimal marginal marketing spend.
- Direct Sales:Carrier-controlled digital platforms and call centers bypassing intermediaries. Urban millennials in Bandung and Yogyakarta prefer this channel for term life and micro-insurance purchases.
- Agents:Commission-compensated individual producers maintaining personal client relationships. Rural penetration in Kalimantan and Papua depends on this channel despite high training and supervision costs.
- Brokers:Independent intermediaries serving corporate accounts with complex risk placement needs. Large manufacturing and infrastructure projects in Batam and Banten rely on broker expertise for international reinsurance access.
Agents dominate installed base. Direct sales is gaining share fastest.
Policyholder Type:
Risk pooling characteristics and contract customization depth vary across policyholder categories, shaping product development roadmaps and service delivery investments.
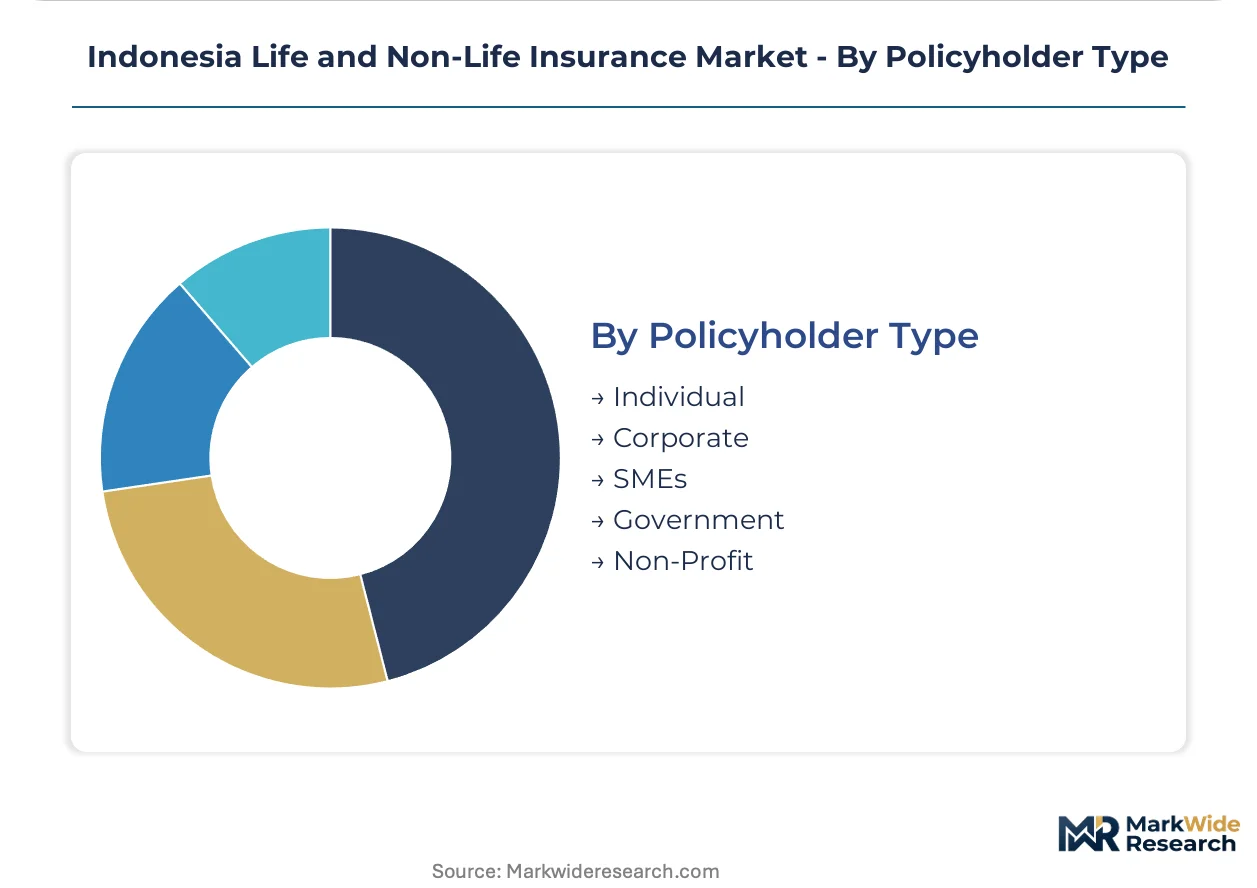
- Individual:Retail consumers purchasing single-life or family coverage through all channels. Middle-class expansion in secondary cities like Semarang and Malang drives term life and health rider uptake.
- Corporate:Large employers sponsoring group life, health, and pension arrangements. Mining and plantation conglomerates in Riau and Central Kalimantan negotiate experience-rated policies with captive retention structures.
- SMEs:Small and medium enterprises requiring bundled property, liability, and key-person coverage. Trade associations in Surabaya and Denpasar aggregate purchasing power for standardized product tiers.
- Government:State-owned enterprises and public sector entities with mandated coverage requirements. Infrastructure project financiers increasingly require contractor all-risk policies as loan covenants.
- Non-Profit:Religious organizations, educational institutions, and social enterprises with constrained budgets. Micro-insurance partnerships with Islamic cooperatives extend coverage to community health and funeral expense pools.
Individual policyholders dominate installed base. SME segment is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance carrier headquarters and policyholder density concentrate in Java, while OJK's regulatory harmonization efforts extend capital requirements and digital infrastructure standards across Indonesia's archipelago. Regional performance varies sharply between established urban markets and emerging outer island territories.
Jakarta Metropolitan Area
Bancassurance partnerships with state-owned banks drive premium volume in Jakarta, where salary-account holders purchase endowment and whole life products through embedded banking channels. OJK's risk-based capital framework mandates higher liquidity reserves for health insurers operating in Jakarta's private hospital networks. The Greater Jakarta corridor hosts the country's densest concentration of carrier headquarters and reinsurance broker operations.
East Java (Surabaya and Malang)
Sharia-compliant takaful products gain traction in Surabaya through Islamic cooperative distribution networks serving Muslim manufacturing workers. OJK's streamlined takaful licensing enables faster product approval cycles for carriers targeting East Java's religious institutions. Surabaya's port logistics sector generates corporate demand for liability and marine cargo coverage among shipping operators.
West Java (Bandung and Bekasi)
Direct digital sales channels capture term life volume among Bandung's millennial professionals purchasing supplemental health coverage outside employer plans. OJK's digital transformation mandates accelerate mobile-first policy issuance platforms in this urban corridor. Bekasi's manufacturing zones sustain group policy uptake among automotive and electronics assembly workers.
North Sumatra (Medan)
Palm oil plantation conglomerates in Medan negotiate experience-rated group life and health policies with captive retention structures for estate worker populations. OJK's consumer protection standards shape claims handling procedures for agricultural sector coverage. Agent networks maintain rural penetration in outer Sumatran districts despite high commission and supervision costs.
Sulawesi and Eastern Indonesia
Parametric weather and accident micro-insurance products target agricultural and informal sector workers in Sulawesi through mobile wallet distribution partnerships. OJK's regulatory sandbox allows insurtech pilots with relaxed capital requirements in underpenetrated outer island markets. Makassar anchors insurance operations for the eastern archipelago, though agent economics remain challenging across dispersed island populations.
Indonesia Life and Non-Life Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Indonesia's insurance sector. The market structure consolidates around established carriers with extensive agent networks while fragmenting at the digital distribution edge. Three archetypes dominate: multinational life insurers with bancassurance depth, domestic conglomerate-affiliated carriers with sharia specialization, and emerging insurtech distributors leveraging OJK sandbox access. Competitive moves concentrate on strategic partnerships with banking networks and portfolio diversification into micro-insurance tiers.
Among multinational carriers operating in Indonesia, PT Prudential Life Assurance, PT AIA Financial, and PT Manulife Indonesia occupy positions exemplifying the bancassurance-anchored archetype. These entities leverage partnerships with major Indonesian banks to embed insurance products within retail lending and deposit workflows. Domestic players such as PT Asuransi Jiwa Sinarmas MSIG Tbk and BNI Life Insurance represent the conglomerate-affiliated tier, with the former differentiating through sharia-compliant product lines. PT Allianz Life Indonesia anchors the generalist multinational position across both life and non-life segments.
| Leading Market Players |
|---|
| PT Allianz Life Indonesia |
| PT Panin Financial Tbk |
| PT Prudential Life Assurance |
| PT Asuransi Tugu Pratama Indonesia Tbk |
| Asuransi Astra |
| PT AIA Financial |
| PT Asuransi Jiwa Sinarmas MSIG Tbk |
| BNI Life Insurance |
| PT Manulife Indonesia |
| Others |
Supply & Pricing Matrix
Mobile-first policy issuance platforms replacing paper-heavy traditional workflows simultaneously concentrate technology procurement in Jakarta and Surabaya while compressing premium pricing power for legacy carriers burdened by legacy system maintenance costs. This substitution dynamic redistributes value capture toward digitally native distributors with leaner cost structures.
Pricing Analysis
OJK's risk-based capital framework dictates the pricing tier structure across Indonesia's insurance sector, mandating differentiated reserve requirements that stratify premiums across product lines. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive whole life products from streamlined term coverage and micro-insurance tiers. Pricing pressure stems from medical cost inflation in Jakarta private hospitals outpacing premium adjustment cycles. First-time buyers in secondary cities exhibit highest price sensitivity, while corporate group policy sponsors in mining and plantation sectors demonstrate lowest sensitivity due to captive retention structures.
Supply Chain Analysis
Port congestion at Tanjung Priok and container availability constraints on the Singapore-Jakarta trade lane elevate inbound logistics costs for technology hardware essential to core system modernization. Technology procurement draws from Singapore, China, and Malaysia for cloud infrastructure and data center equipment. Reinsurance capacity rests on placements with regional partners in Singapore and Hong Kong. Single-source vulnerability concentrates in legacy policy administration software vendors. Distribution runs through bancassurance partnerships with state-owned banks, direct digital platforms, and agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OJK's digital transformation mandates constitute a regulatory inflection compressing product development cycles from months to weeks, creating asymmetric opportunity for technology-enabled carriers against legacy competitors burdened by core system migration timelines.
For Market Incumbents: Consolidate agent network control in Java's secondary cities while accelerating cloud-native core system replacement to counter insurtech sandbox entrants. Lock in bancassurance exclusivity extensions with Mandiri and BCA before digital distributors capture salary-account holder relationships. Prioritize sharia-compliant product certification to defend against domestic conglomerate-affiliated carriers with established Islamic banking channels.
For New Entrants and Emerging Players: Differentiate on parametric micro-insurance distribution through mobile wallet partnerships targeting Sulawesi agricultural workers and Sumatra plantation laborers. Penetrate the SME segment in Surabaya and Denpasar through trade association aggregation models. Deploy AI-driven underwriting engines via OJK regulatory sandbox access to compress policy issuance timelines below incumbent capabilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic conglomerate-affiliated carriers possessing sharia specialization but limited digital infrastructure. Long-term viability hinges on successful technology modernization execution within a five-to-ten year window. Monitor OJK sandbox graduation rates as inflection indicator for which digital-native distributors warrant strategic positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Core System Cloud Migration | Reduces policy issuance timelines from weeks to minutes for PT Prudential and PT AIA. |
| Sharia Certification Investment | Unlocks takaful distribution through Islamic cooperatives in East Java for Sinarmas MSIG. |
| Mobile Wallet Partnership | Extends parametric micro-insurance reach to Sulawesi agricultural workers via GoPay and OVO. |
| Telemedicine Platform Integration | Enables preventive care riders reducing claims frequency for health insurers in Jakarta. |
| Bancassurance Exclusivity Extension | Secures embedded distribution touchpoints with Mandiri and BCA salary-account holders. |
Research Methodology
A standing panel of actuarial directors, bancassurance channel heads, OJK regulatory affairs specialists, and insurtech founders provided ongoing calibration throughout the study. Primary interviews with carrier technology officers and reinsurance brokers in Jakarta and Singapore combined with secondary validation against OJK regulatory filings, BIS technical standards documentation, and Indonesia's national digital identity infrastructure disclosures. Bottom-up policy volume estimates triangulated against top-down premium flow analysis across the analysis window.
Consistency checks validated volume and value outputs against OJK-published industry aggregate data and regional reinsurance placement trends. Segmentation modeling incorporated product type, coverage type, distribution channel, and policyholder category dimensions across the projection horizon. CAGRs derived from regression analysis of historical premium growth patterns adjusted for OJK capital requirement revisions and medical inflation differentials between Jakarta and outer island markets.
The analysis sits within stated boundaries; outcomes outside sustained OJK regulatory enforcement, stable bancassurance partnership structures, or continued mobile penetration growth would require recalibration. Forecasts reflect documented assumptions regarding technology adoption curves and sharia product licensing timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market