
 India Electronic Gadget Insurance Market | 2026-2036
India Electronic Gadget Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Electronic Gadget Insurance Market Foresight
India is tilting toward gadget insurance penetration as smartphone ownership crosses into tier-2 and tier-3 cities. Policybazaar leverages its digital aggregator platform to simplify comparison and purchase workflows for first-time buyers. HDFC Ergo anchors its position through partnerships with electronics retailers and OEMs at point-of-sale. Acko General Insurance competes via app-native claims processing that eliminates documentation friction.
Electronic gadget insurance constitutes a specialized non-life product covering repair, replacement, and liability costs for portable electronic devices against named perils. Policies typically specify deductible thresholds, depreciation schedules, and authorized service network requirements to determine claim settlements. Smartphone coverage dominates premium volumes given India's status as the second-largest mobile market globally. Screen damage and accidental damage segments carry the highest claim frequencies, compressing margins and forcing insurers toward preventive risk assessment tools. Corporate customer pools offer lower loss ratios but require customized fleet administration platforms.
The Insurance Regulatory and Development Authority of India mandates solvency margins and digital disclosure standards that shape product design and distribution transparency. BIS certification requirements for refurbished replacement devices influence claims fulfillment costs and partner network selection. Stakeholders must monitor how embedded insurance integrations at OEM checkout pages reshape traditional distribution economics and customer acquisition structures.
Market Dynamics
Embedded insurance integrations at OEM checkout pages are compressing traditional distribution economics and forcing insurers to rebuild customer acquisition architectures around point-of-sale touchpoints.
Growth Catalysts
- IRDAI digital-first guidelines:The Insurance Regulatory and Development Authority of India's paperless policy issuance mandates slash onboarding friction for smartphone-native buyers in Maharashtra and Karnataka.
- Refurbished device certification:BIS certification requirements for replacement units create standardized claims fulfillment pathways that reduce insurer partner vetting costs.
- Tier-2 city penetration:Device ownership spreads beyond Delhi NCR into Indore, Lucknow, and Coimbatore, expanding addressable premium pools for regional distributors.
Market Restraints
- Screen damage claim frequency:High-frequency accidental damage segments compress margins and force capital allocation toward preventive risk assessment tools rather than pure indemnity.
- Authorized service network concentration:Claims fulfillment depends on OEM-captive repair chains in Bengaluru and Mumbai, creating single-point fulfillment bottlenecks.
- Depreciation schedule rigidity:Fixed asset-value decay tables misalign with actual secondary market resale prices for mid-tier smartphones, generating policyholder disputes.
Strategic Opportunities
- Corporate fleet administration:Customized platforms for enterprise device pools offer lower loss ratios than retail segments and lock in multi-year premium commitments.
- Point-of-sale embedding:Checkout-page insurance attachments at electronics retailers capture zero-friction enrollment before buyer remorse sets in.
- Telematics convergence:Device health monitoring APIs from OEMs enable dynamic pricing that rewards protective case usage and software update compliance.
Industry Challenges
- Legacy claims system integration:Insurers must bridge core policy administration platforms with real-time OEM diagnostic feeds without disrupting existing workflow architectures.
- Documentation standardization:BIS, CDSCO, and TRAI each impose distinct digital disclosure formats that complicate unified compliance dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electronic Gadget Insurance Market |
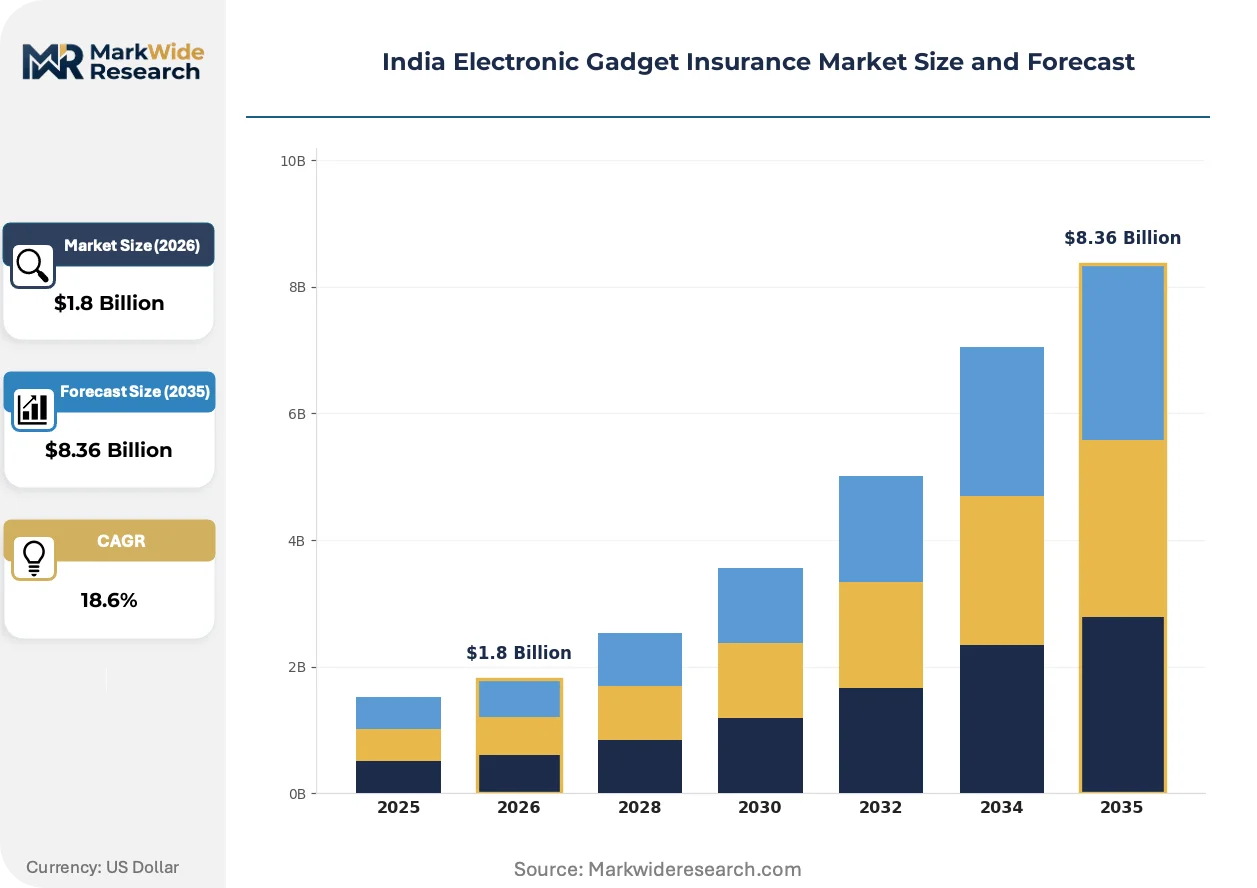
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables Coverage Type: Theft, Accidental Damage, Liquid Damage, Screen Damage Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Telecom Providers Customer Type: Individuals, Corporates, Students, Professionals |
| Companies Covered | National Insurance Co., HDFC Ergo, New India Assurance, Policybazaar, Acko General Insurance, Bajaj Allianz, ICICI Lombard, OneAssist, Oriental Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electronic Gadget Insurance Market Shifts & Advancements
Real-time device telemetry and automated damage assessment are collapsing the traditional claims cycle from days to minutes, reshaping customer retention economics for digital-native insurers.
AI-powered visual damage assessment is digitizing the claims validation workflow. Smartphone-toting Gen Z policyholders in Delhi NCR and Pune submit cracked-screen photos through native apps. Insurers compress loss-adjustment expenses while accelerating settlement velocity.
IRDAI's digital disclosure standards mandate machine-readable policy documents and real-time solvency reporting. Product design teams in Mumbai restructure benefit schedules for algorithmic transparency. Distribution platforms embed compliance checkpoints directly into comparison workflows.
Subscription-based protection plans displace annual policies among millennial professionals. Electronics retailers in Bengaluru and Hyderabad bundle rolling coverage with device upgrade programs. Corporate procurement teams negotiate enterprise-wide device protection as a managed service rather than transactional insurance.
India Electronic Gadget Insurance Market Segmentation
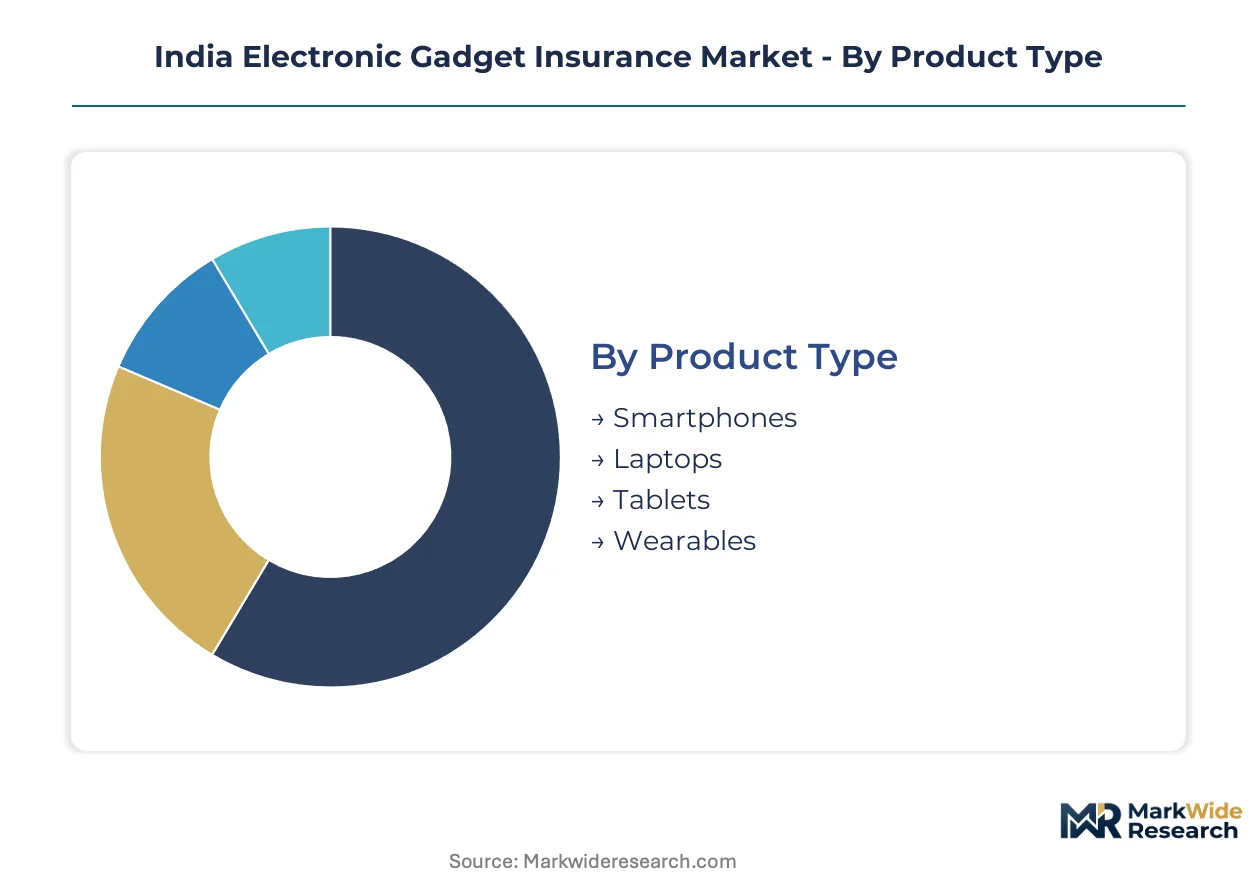
Segmentation in India's electronic gadget insurance market reveals distinct risk profiles and distribution economics across device categories, coverage tiers, and customer pools. Product type and coverage combinations determine claim frequency, while distribution channel selection shapes customer acquisition costs in tier-2 city expansion.
Product Type:
Mature segments dominate premium volumes, while emerging categories reshape loss ratio assumptions through novel risk characteristics.
- Smartphones:Policies cover repair and replacement costs for India's second-largest mobile market, with screen damage and accidental damage driving highest claim frequencies. Maharashtra and Karnataka generate concentrated premium pools where e-commerce integration runs deepest.
- Laptops:Higher average insured values and corporate fleet administration opportunities compress loss ratios below retail smartphone benchmarks. Enterprise procurement teams in Delhi NCR negotiate multi-year protection as managed services.
- Tablets:Hybrid work adoption sustains demand among professionals and students seeking portable productivity coverage.
- Wearables:Compact form factors and water exposure risks create specialized underwriting challenges for fitness trackers and smartwatches.
Smartphones handle the majority of throughput; wearables are expanding most quickly on share as device penetration spreads beyond metros.
Coverage Type:
Cost tier stratification separates high-frequency low-severity perils from catastrophic loss events with divergent capital allocation requirements.
- Theft:Comprehensive protection against device loss requiring police documentation and IMEI blacklisting verification. Mumbai and Bengaluru theft claims concentrate in high-density transit corridors.
- Accidental Damage:Physical impact coverage generates margin compression through elevated claim frequencies, forcing insurers toward preventive risk assessment tools. Tier-2 cities show rising enrollment as first-time buyers enter the market.
- Liquid Damage:Corrosion and circuitry failure coverage carries higher repair cost variability than screen-only policies.
- Screen Damage:Most purchased add-on coverage with standardized repair networks and fastest claims settlement cycles.
Accidental damage handles the majority of throughput; screen damage is gaining share fastest as OEM checkout-page bundling simplifies enrollment.
Distribution Channel:
Customer type concentration varies sharply across physical and digital touchpoints, with point-of-sale embedding capturing zero-friction enrollment.
- Retail Stores:Electronics retailers in Bengaluru and Hyderabad bundle coverage at checkout before buyer remorse sets in. Staff-assisted explanations overcome first-time buyer hesitation in tier-3 expansion.
- Online Platforms:Digital aggregators simplify comparison workflows for smartphone-native millennials and Gen Z professionals. IRDAI paperless mandates accelerate policy issuance without documentation friction.
- Direct Sales:Insurer-owned channels target corporate fleet administrators with customized administration platforms.
- Telecom Providers:Mobile network operators embed protection into postpaid plan upgrades with recurring billing integration.
Online platforms handle the majority of throughput; retail stores are climbing the fastest as tier-2 city device ownership spreads.
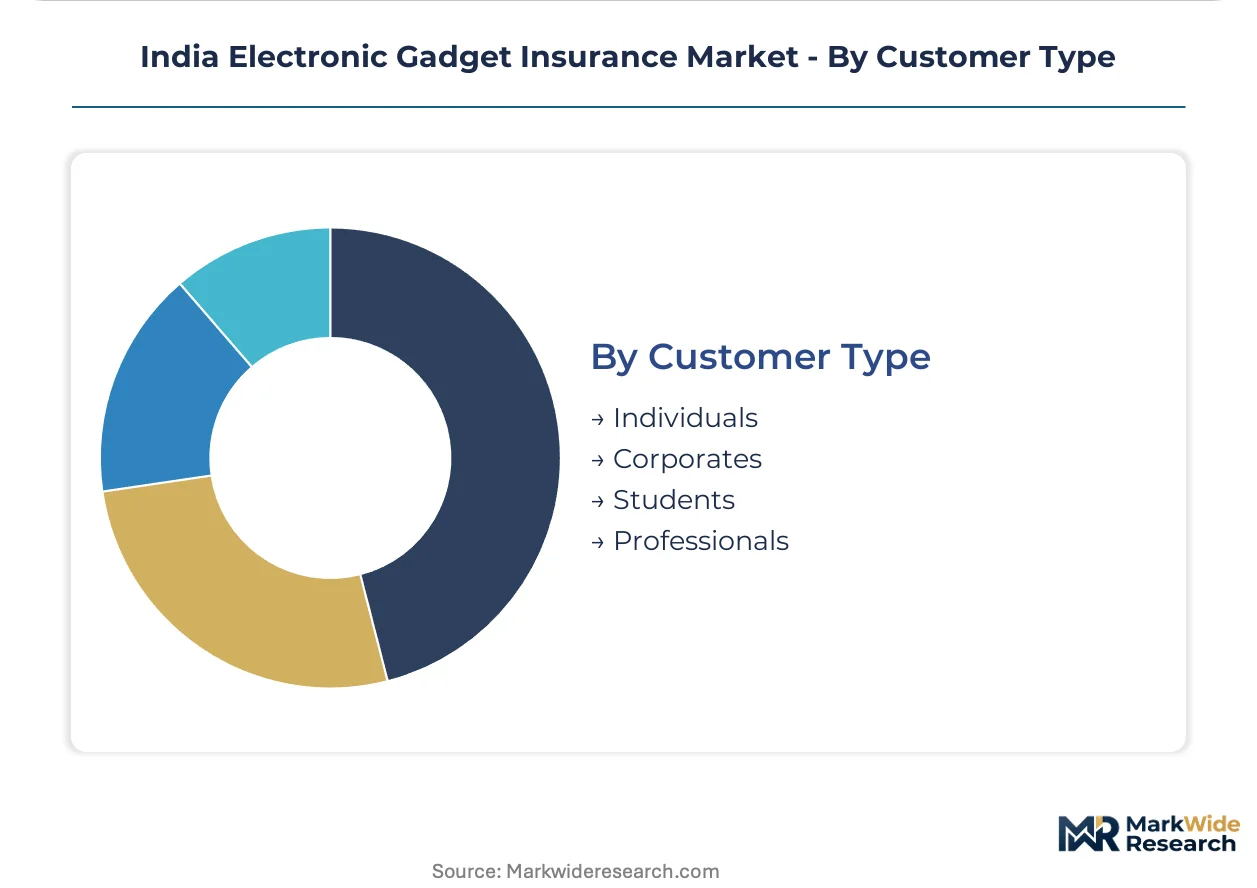
Customer Type:
Volume scale and margin profile diverge between individual policyholders and institutional purchasers with divergent servicing infrastructure needs.
- Individuals:Retail policyholders in Delhi NCR and Pune drive screen damage claim volumes through smartphone-native usage patterns. Policybazaar's comparison engine captures this segment through simplified purchase workflows.
- Corporates:Enterprise device pools offer lower loss ratios and lock in multi-year premium commitments through customized fleet administration platforms. Procurement teams negotiate managed service structures rather than transactional coverage.
- Students:Price-sensitive segment gravitating toward subscription-based protection plans bundled with device upgrade programs.
- Professionals:Millennial workforce demands rolling coverage aligned with frequent device refresh cycles and hybrid work portability needs.
Individuals handle the majority of throughput; corporates are the fastest mover on share as enterprise digitization accelerates device fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor freight rail network underwrites Maharashtra's dominance in gadget insurance distribution, connecting electronics manufacturing clusters to financial services hubs across western India.
Maharashtra
Mumbai's dense smartphone penetration and e-commerce integration generate concentrated premium volumes for digital-first insurers. IRDAI's paperless policy mandates accelerate onboarding for smartphone-native buyers across the Mumbai-Pune belt. Electronics retailers in Thane and Navi Mumbai embed point-of-sale coverage at checkout counters.
Karnataka
Bengaluru's OEM-captive repair chains and technology workforce sustain high-frequency screen damage claim volumes. BIS certification requirements for refurbished replacement devices standardize claims fulfillment pathways. Insurers partner with authorized service networks in Whitefield and Electronic City to resolve fulfillment bottlenecks.
Delhi NCR
The region's corporate procurement teams negotiate enterprise device protection as managed services rather than transactional coverage. TRAI's digital disclosure standards mandate machine-readable policy documents for algorithmic transparency. Gurugram and Noida host customized fleet administration platforms serving multi-year premium commitments.
Telangana
Hyderabad's tier-2 city expansion spreads device ownership into price-sensitive first-time buyer segments. CDSCO's medical device regulatory framework indirectly shapes wearable insurance underwriting standards. Electronics retailers in Secunderabad bundle subscription-based protection with device upgrade programs.
Tamil Nadu
Coimbatore and Chennai manufacturing corridors feed replacement device supply chains for pan-India claims fulfillment. The state's electronics policy incentives attract OEM assembly operations that enable embedded checkout-page insurance. Insurers leverage Coimbatore's secondary market resale data to recalibrate depreciation schedules.
India Electronic Gadget Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in risk assessment and claims fulfillment. The market structures around three tiers: digital aggregators capturing comparison-driven enrollment, incumbent insurers anchoring retail partnerships, and insurtech natives collapsing claims cycles through API integration. Consolidation pressures favor players with captive repair networks and OEM data feeds. Strategic moves cluster on embedded checkout integrations and telematics-based dynamic pricing.
Within the digital-native tier, Acko General Insurance and Policybazaar exemplify platform-first distribution architectures. HDFC Ergo anchors the incumbent-insurer archetype through retail partnership density. These three players occupy positions across the spectrum from pure aggregator to balance-sheet underwriter, reflecting the market's migration toward point-of-sale embedding and real-time claims automation.
| Leading Market Players |
|---|
| National Insurance Co. |
| HDFC Ergo |
| New India Assurance |
| Policybazaar |
| Acko General Insurance |
| Bajaj Allianz |
| ICICI Lombard |
| OneAssist |
| Oriental Insurance Company |
| Others |
Supply & Pricing Matrix
BIS certification requirements for refurbished replacement devices concentrate quality control costs in Tamil Nadu and Karnataka assembly corridors, compressing margin pools for insurers without captive repair networks while elevating pricing power for players with authorized service partnerships.
Pricing Analysis
IRDAI digital disclosure standards dictate the pricing tier structure across the market. Premium-mid-economy pricing differentiation separates comprehensive coverage with zero-deductible claims from screen-only policies with depreciation schedules. Cost compression in the economy tier is intensifying because high-frequency accidental damage claims erode loss ratios. Individual retail policyholders in tier-2 cities exhibit highest price sensitivity, while corporate fleet administrators negotiate volume-based managed service rates with lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability in OEM-captive repair chains dominates supply chain risk for claims fulfillment. Authorized service networks concentrate in India, China, and Vietnam for component sourcing and device refurbishment. Spare parts procurement draws from Shenzhen electronics corridors and Bengaluru semiconductor assembly zones. Distribution runs through electronics retailers in Maharashtra and Karnataka, direct insurer app channels, and telecom provider billing integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time claims automation capabilities remain scarce across the competitive landscape, creating asymmetric advantage for insurers that bridge legacy policy administration systems with OEM diagnostic APIs.
For Market Incumbents: Insulate core margin pools by deepening captive repair network ownership in Bengaluru and Hyderabad, and accelerate certification investment for BIS-compliant refurbishment facilities. Embedded checkout integrations at electronics retailers threaten traditional aggregator-driven acquisition economics; channel control through exclusive retail partnerships becomes the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in corporate fleet administration platforms serving Delhi NCR and Pune enterprise clusters, where multi-year premium commitments and lower loss ratios offer sustainable unit economics. Tier-2 city expansion into Indore and Lucknow presents the most penetrable geography for first-time buyer acquisition through simplified subscription-based protection plans. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telematics-enabled dynamic pricing infrastructure, favoring balance-sheet players over pure distribution aggregators. Acquisition targets should display captive OEM data partnerships and real-time claims API integration. The signal to watch is regulatory movement toward mandated device health monitoring disclosures.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance Integration | Checkout-page bundling at Croma and Vijay Sales captures zero-friction enrollment before buyer remorse. |
| Telematics Platform Development | Device health monitoring APIs from Samsung and Xiaomi enable usage-based premium adjustments. |
| Captive Repair Network Expansion | Authorized service partnerships in Whitefield and Electronic City resolve fulfillment bottlenecks. |
| Corporate Fleet Administration Buildout | Customized platforms for TCS and Infosys device pools lock in multi-year premium commitments. |
| AI-Powered Claims Automation | Visual damage assessment through native apps collapses settlement cycles from days to minutes. |
Research Methodology
Cross-validation between primary interviews with insurance product managers, claims operations directors, and electronics retail category heads anchors the qualitative findings against secondary validation from IRDAI circulars, BIS certification databases, and TRAI digital disclosure guidelines. Bottom-up triangulation across policy issuance volumes and top-down reconciliation against non-life insurance sector reports ensures methodological robustness.
Calibration against historical premium growth patterns and device penetration trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include device category, coverage tier, distribution channel, and customer archetype. CAGRs derive from trend extrapolation moderated by regulatory inflection points and technology adoption S-curves. Forecast inputs incorporate IRDAI solvency margin requirements and OEM checkout-page integration timelines.
Stress conditions across claim frequency volatility, depreciation schedule disputes, and partner network concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about digital adoption curves and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
North America Car Insurance Aggregators Market
Insurance
Insurance Claims Services Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Bancassurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Credit Insurance Market
Insurance
Financial Guarantee Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Specialty Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Auto Extended Warranty Market