
 Germany Real Time Payments Market | 2026-2036
Germany Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Real Time Payments Market Foresight
A shortage of API integration specialists is redrawing how payment infrastructure scales across German financial institutions. Deutsche Bank leverages its universal banking network to anchor enterprise-grade instant transfer services. Sparkassen competes through its dense branch footprint, while Adyen differentiates via unified platform architecture spanning online and in-person channels.
Germany real time payments denote funds transfer systems that clear and settle transactions within seconds, operating on ISO 20022 messaging standards and API-driven bank connectivity to enable immediate value exchange between payer and recipient accounts. The primary commercial purpose centers on eliminating settlement risk and improving liquidity velocity for businesses and consumers. Instant Credit Transfers capture dominant transaction volume as SEPA Instant penetration deepens, while API Integration represents the fastest-expanding technology layer as open banking mandates force infrastructure modernization. Digital Wallets attract concentrated development investment from retail-facing providers seeking to bypass traditional card rails.
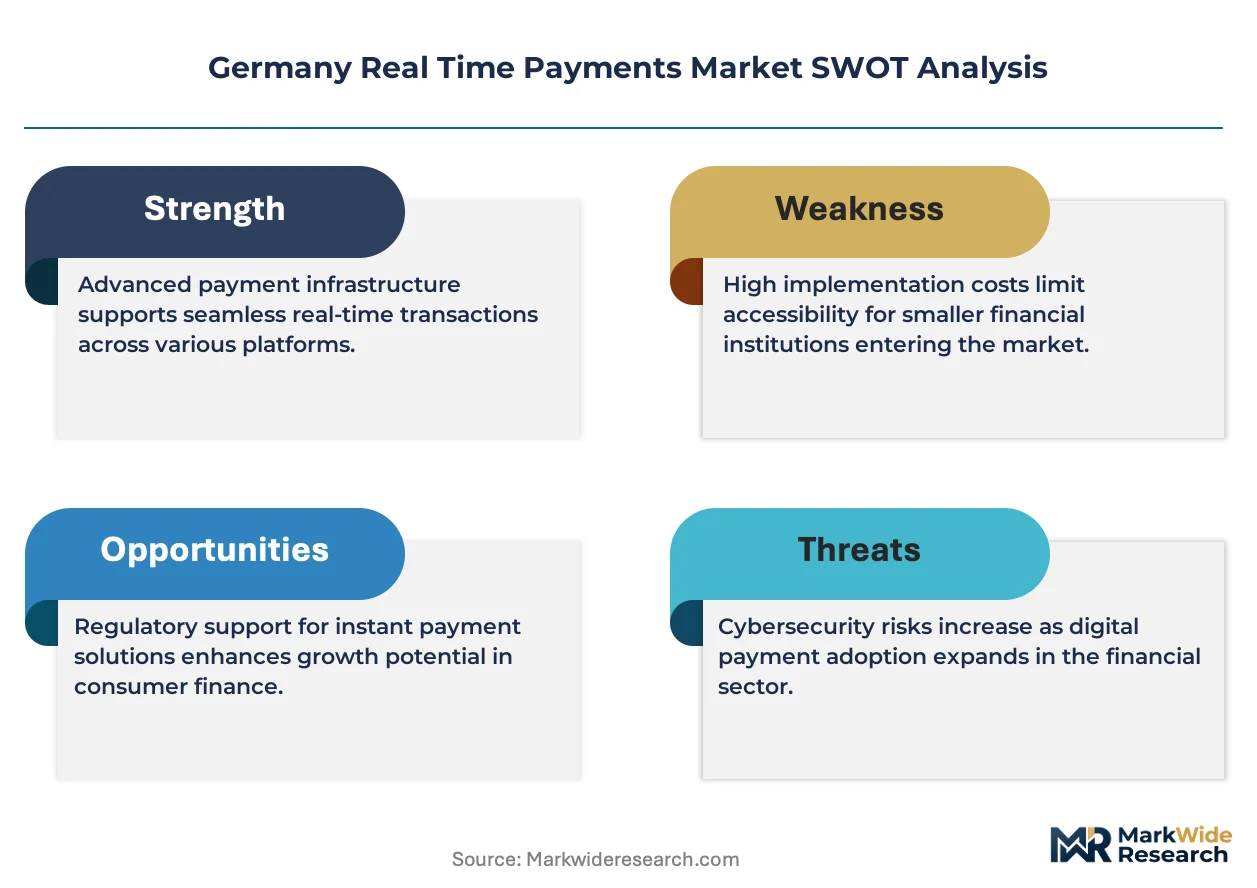
BaFin supervises payment service licensing and operational resilience standards, while PSD2 and the EU AI Act collectively shape authentication protocols and algorithmic fraud detection requirements. The European Banking Authority's SEPA Instant scheme rules further dictate interoperability obligations and maximum execution timelines. Stakeholders must monitor how forthcoming ECB retail digital euro specifications alter instant payment utility and fee structures.
Market Dynamics
SEPA Instant Credit Transfer mandates are forcing German banks to rebuild core infrastructure around ISO 20022 messaging and API-first architectures, compressing settlement windows from T+2 to sub-ten seconds.
Growth Catalysts
- PSD2 Strong Customer Authentication:Open banking mandates compel legacy institutions to expose payment initiation APIs, creating standardized entry points for fintech orchestration layers.
- Small business cash flow urgency:German Mittelstand exporters prioritize instant settlement to reduce working capital cycles locked in cross-border receivables.
- Request-to-Pay messaging:Structured invoice data embedded in real-time rails is displacing paper-based reconciliation processes across B2B procurement.
Market Restraints
- Core banking modernization costs:Tier-2 German banks face eight-figure euro investments to replace batch-oriented legacy platforms with real-time capable stacks.
- API specialist scarcity:Frankfurt and Berlin labor markets exhibit acute shortages of engineers fluent in ISO 20022 schema mapping and PSD2 compliance frameworks.
- Interbank fee compression:SEPA Instant's maximum 20-cent ceiling squeezes revenue models dependent on traditional wire transfer margins.
Strategic Opportunities
- Eastern German SME corridor:Saxony and Brandenburg manufacturing clusters remain underserved by instant payment infrastructure relative to western industrial zones.
- Embedded finance convergence:Automotive and industrial equipment OEMs are integrating real-time settlement into IoT-enabled usage-based billing platforms.
- ECB retail digital euro:Upcoming central bank digital currency specifications will force interoperability upgrades that favor first-mover API infrastructure providers.
Industry Challenges
- Fraud model recalibration:Sub-second settlement eliminates traditional chargeback windows, requiring German institutions to deploy machine-learning transaction scoring without latency degradation.
- Legacy stack fragmentation:Sparkassen and cooperative banking IT landscapes span three decades of accumulated middleware, complicating unified real-time deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Real Time Payments Market |
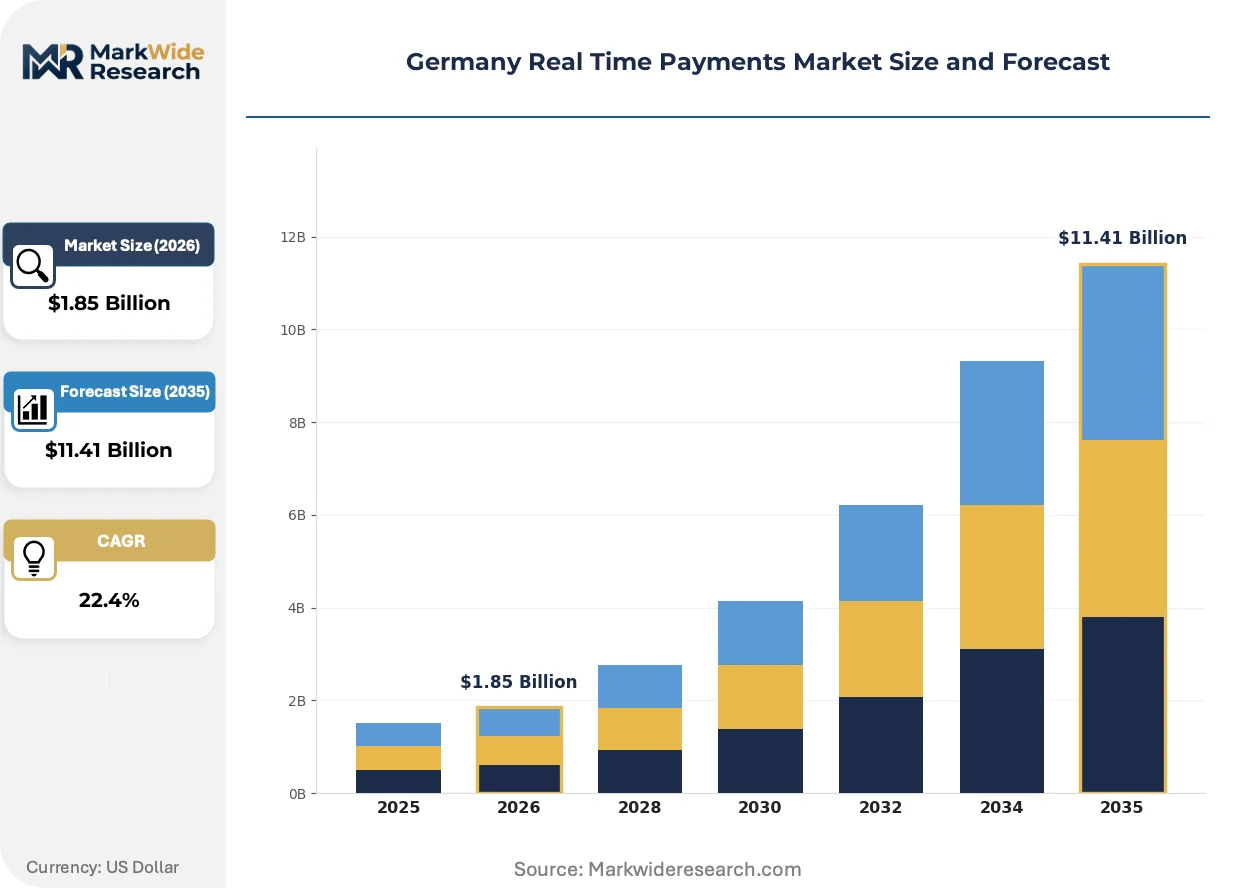
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $11.41 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Instant Credit Transfers, Digital Wallets, QR Code Payments, Contactless Payments Technology: Blockchain, Mobile Payment Platforms, API Integration, NFC Customer Segment: Retail Consumers, Small Businesses, Enterprises, Public Sector Service Type: Transaction Processing, Compliance Solutions, Fraud Detection, Technical Support |
| Companies Covered | Deutsche Bank, Commerzbank, Sparkassen, Volksbanken, ACI Worldwide, Mastercard, Visa, Adyen, Worldline, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Real Time Payments Market Shifts & Advancements
Payment infrastructure in Germany is fragmenting into specialized layers as open banking dissolves monolithic banking relationships into composable service stacks.
ISO 20022 messaging is decomposing traditional payment file formats into granular, machine-readable data elements. German corporate treasuries are adopting native XML remittance structures to automate reconciliation. This decomposition collapses the distinction between payment execution and financial messaging, enabling straight-through processing rates above ninety-five percent.
BaFin's operational resilience requirements under DORA are mandating sub-four-hour recovery objectives for critical payment systems. German credit institutions must re-architect disaster recovery sites to synchronous replication standards. Mid-tier banks lacking captive data center capacity are consolidating into shared service utilities to meet these thresholds.
German e-commerce merchants are unbundling checkout experiences from captive banking relationships. Marketplace sellers now route transactions through multi-provider orchestration layers that select optimal rails in real time. This behavior concentrates in fashion and electronics verticals where cart abandonment sensitivity drives latency optimization investments.
Germany Real Time Payments Market Segmentation
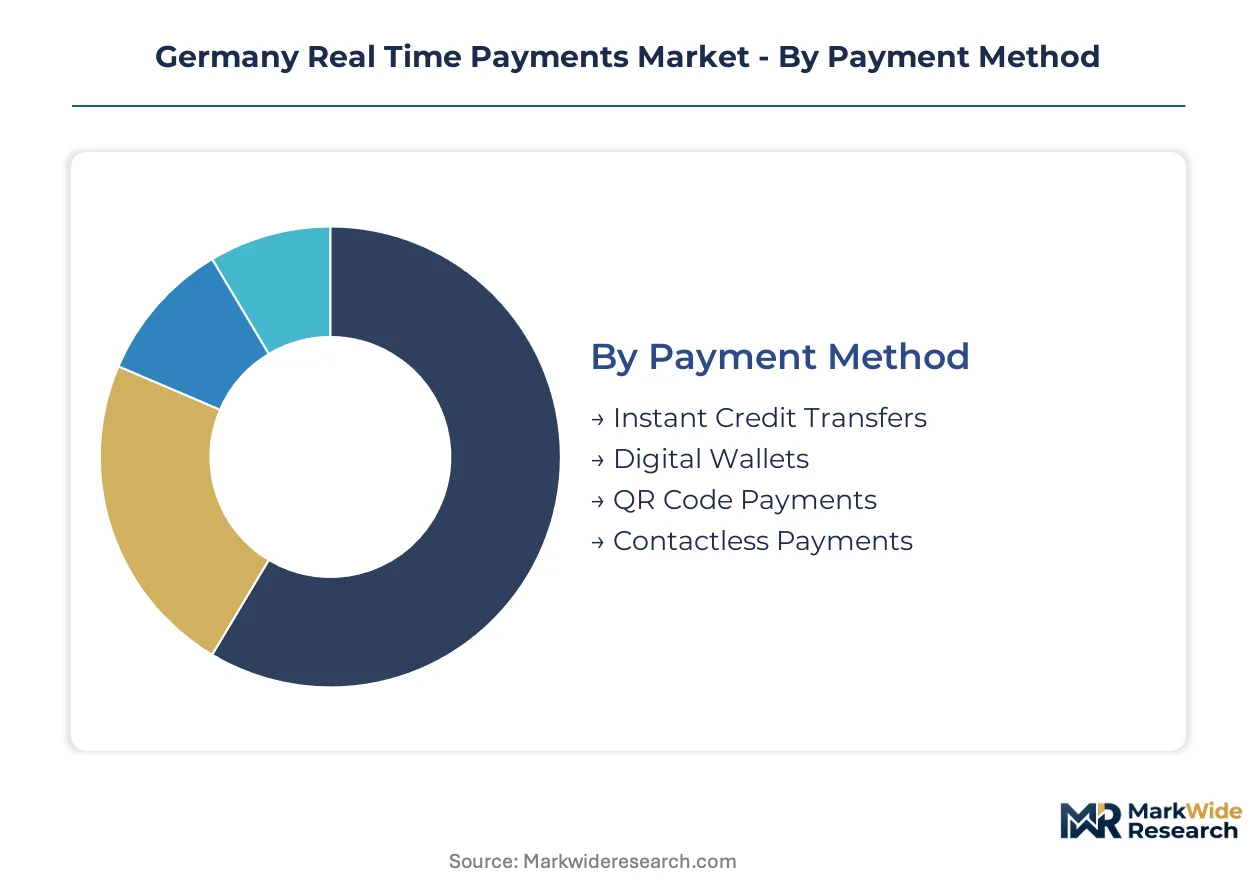
Payment infrastructure heterogeneity across German federal states creates divergent adoption curves that reward granular segment targeting. SEPA Instant penetration varies substantially between dense western banking corridors and eastern manufacturing clusters, forcing providers to calibrate channel strategies by both payment instrument and regional liquidity needs.
Payment Method:
Domestic retail adoption concentrates in western urban corridors, while export-oriented SMEs in Saxony and Brandenburg drive cross-border instant settlement demand.
- Instant Credit Transfers:SEPA Instant rails process euro-denominated transactions under ten seconds using ISO 20022 messaging. German Mittelstand exporters in Baden-Württemberg prioritize these rails for cross-border receivables compression, though BaFin operational resilience mandates force redundant infrastructure investments.
- Digital Wallets:Smartphone-aggregated payment credentials enable e-commerce checkout bypassing traditional card networks. Berlin and Munich retail corridors exhibit dense merchant acceptance, driven by cart abandonment sensitivity in fashion and electronics verticals.
- QR Code Payments:Static and dynamic matrix codes link mobile banking apps to merchant settlement endpoints without terminal hardware.
- Contactless Payments:NFC-enabled card and device taps at physical points of sale leverage existing terminal infrastructure.
Instant Credit Transfers command the established base. The steepest expansion runs through Digital Wallets.
Technology:
API-first architectures dominate western German banking hubs, while eastern institutions lag in core modernization cycles.
- API Integration:RESTful interfaces expose payment initiation and account information services per PSD2 mandates. Frankfurt-based universal banks deploy these layers to capture fintech orchestration traffic, though acute engineer scarcity in ISO 20022 schema mapping constrains rollout velocity.
- Blockchain:Distributed ledger prototypes target cross-border settlement efficiency for German automotive supply chains. BMW and Siemens pilot consortia explore programmable payments for IoT-enabled machine-to-machine transactions.
- Mobile Payment Platforms:Native iOS and Android SDKs embed banking services into merchant applications.
- NFC:Near-field communication protocols enable tap-to-pay interactions at physical terminals.
API Integration anchors current infrastructure investment. Blockchain experiments are climbing the fastest among technology layers.
Customer Segment:
Retail saturation in western cities contrasts with underserved SME corridors in eastern federal states.
- Small Businesses:German Mittelstand manufacturers with under 500 employees prioritize instant settlement to compress working capital cycles locked in 60-90 day receivables. Saxony and Thuringia industrial clusters remain penetration laggards relative to Rhineland benchmarks.
- Enterprises:Corporate treasuries at DAX-listed multinationals demand straight-through processing rates above ninety-five percent. Deutsche Bank and Commerzbank compete for primary banking relationships through dedicated API portals and native ISO 20022 remittance structures.
- Retail Consumers:Individual account holders adopt real-time rails for peer-to-peer transfers and e-commerce checkout.
- Public Sector:Municipal and federal payment systems modernize toward instant disbursement capabilities.
Enterprises command the established base. The steepest expansion runs through Small Businesses.
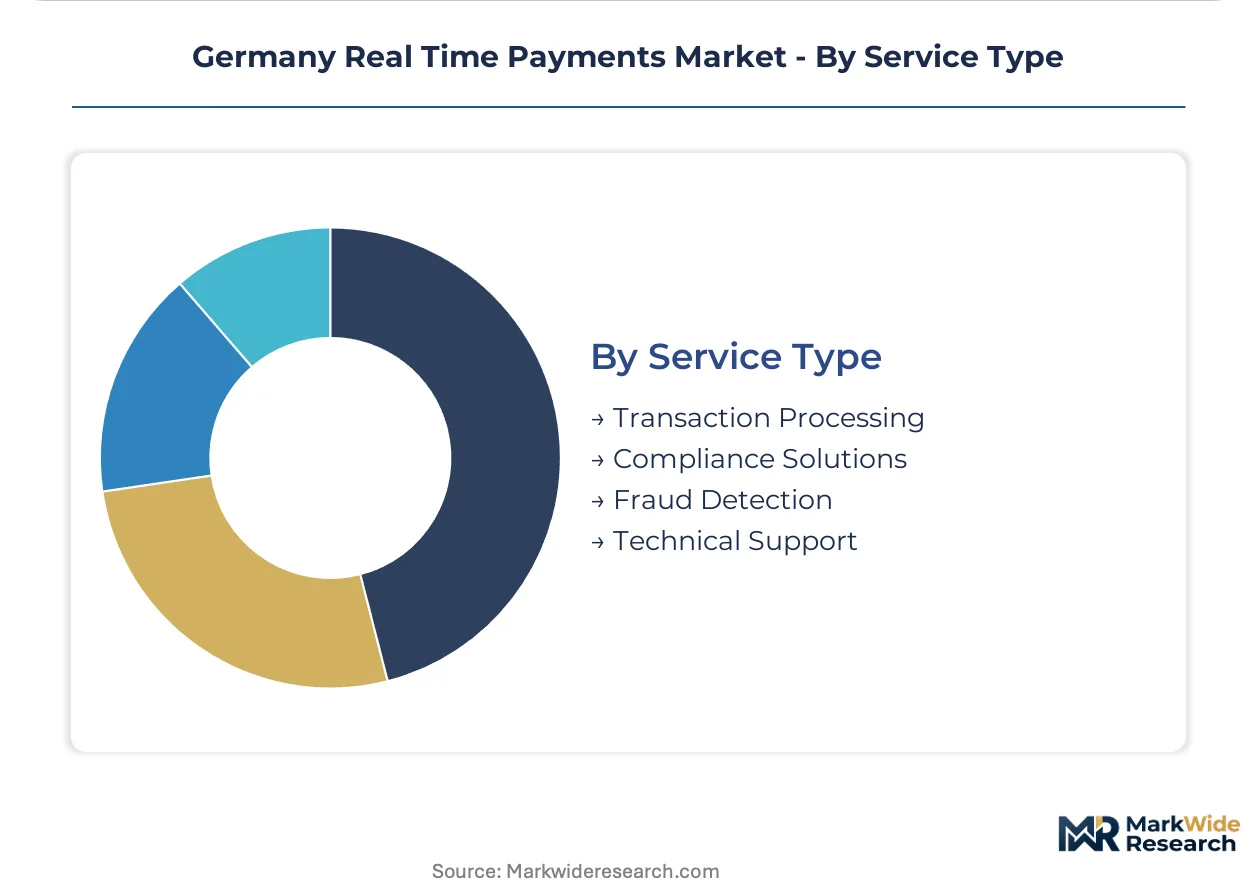
Service Type:
Compliance and fraud capabilities concentrate among Tier-1 institutions, while mid-tier banks outsource critical functions.
- Fraud Detection:Machine-learning transaction scoring models operate within sub-second latency windows to compensate for eliminated chargeback protections. German credit institutions recalibrate risk engines continuously as SEPA Instant volumes scale, with false-positive rates directly impacting merchant acceptance economics.
- Compliance Solutions:PSD2 Strong Customer Authentication and DORA operational resilience mandates force systematic infrastructure audits. Sparkassen and cooperative banks consolidate into shared service utilities to distribute BaFin supervision costs across pooled member institutions.
- Transaction Processing:Core clearing and settlement engine operations manage rail connectivity and message routing.
- Technical Support:Implementation and integration assistance for merchant onboarding and API troubleshooting.
Transaction Processing commands the established base. Fraud Detection is gaining share fastest among service categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German real-time payment adoption patterns diverge sharply between western urban financial centers and eastern industrial corridors, with infrastructure density and regulatory proximity to Frankfurt driving differential usage intensities across federal states.
North Rhine-Westphalia
Düsseldorf and Cologne corporate treasuries anchor SEPA Instant volume for cross-border Mittelstand receivables. BaFin operational resilience mandates under DORA force redundant infrastructure investments across the state's dense banking cluster. The Ruhr industrial belt exhibits accelerating API integration demand from mid-tier manufacturers modernizing procurement workflows.
Bavaria
Munich's technology and automotive sectors drive embedded finance convergence into IoT-enabled billing platforms. PSD2 Strong Customer Authentication requirements shape authentication protocol investments across Bavarian credit institutions. The Nuremberg-Erlangen manufacturing corridor concentrates Request-to-Pay messaging pilots for B2B supply chain automation.
Baden-Württemberg
Stuttgart automotive OEMs prioritize instant settlement for just-in-time supplier networks spanning SEPA jurisdictions. The European Banking Authority's SEPA Instant scheme rules dictate interoperability obligations for Landesbank Baden-Württemberg's corporate banking division. Karlsruhe's fintech density supports API-first orchestration layer development for merchant routing optimization.
Berlin-Brandenburg
Berlin e-commerce merchants exhibit dense digital wallet adoption driven by cart abandonment sensitivity in fashion and electronics verticals. The EU AI Act shapes algorithmic fraud detection requirements for payment service providers operating across the capital region. Brandenburg manufacturing clusters remain penetration laggards for instant payment infrastructure relative to western benchmarks.
Hesse
Frankfurt's universal banking headquarters anchor enterprise-grade instant transfer services for DAX-listed multinationals. ECB retail digital euro specifications under development in Frankfurt force interoperability upgrade planning among first-mover API infrastructure providers. The Rhine-Main metropolitan area concentrates ISO 20022 schema mapping specialist talent amid acute labor market shortages.
Germany Real Time Payments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in German real-time payments, with universal banks and global payment networks occupying distinct vertical positions. The upper tier consolidates around institutions possessing captive clearing infrastructure and regulatory licensing depth. Three archetypes dominate: legacy universal banks leveraging branch density, fintech orchestration platforms unifying multi-rail acceptance, and infrastructure technology vendors supplying core processing engines. Competitive dynamics center on API ecosystem partnerships and embedded finance integration capabilities rather than price-led displacement.
Among Germany-based banking groups, Deutsche Bank and Commerzbank occupy positions within the universal bank archetype, anchoring enterprise relationships through dedicated API portals. Sparkassen represents the cooperative banking tier, exemplifying branch-network-driven distribution models. Adyen sits within the platform-native archetype, illustrating unified architecture approaches spanning online and in-person channels. These three entities collectively map the competitive terrain without exhaustively cataloging market presence.
| Leading Market Players |
|---|
| Deutsche Bank |
| Commerzbank |
| Sparkassen |
| Volksbanken |
| ACI Worldwide |
| Mastercard |
| Visa |
| Adyen |
| Worldline |
| Others |
Supply & Pricing Matrix
BaFin operational resilience requirements under DORA gate both infrastructure qualification and price differentiation simultaneously, forcing Tier-2 German banks into shared service utilities that compress margins while elevating compliance-certified providers.
Pricing Analysis
Long-term offtake contracts dominate enterprise API infrastructure procurement, while mid-tier institutions rely on project-based implementation fees. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 20022 certification depth and disaster recovery redundancy. Cost compression in standard tiers intensifies because SEPA Instant's 20-cent fee ceiling squeezes transaction-based revenue models. Small businesses in eastern federal states exhibit highest price sensitivity, whereas DAX-listed multinationals prioritize latency guarantees over unit economics.
Supply Chain Analysis
Container availability constraints across Rotterdam-Frankfurt rail corridors elevate inbound logistics costs for server hardware and data center equipment. Core processing engine supply concentrates in Ireland, Netherlands, and Germany itself, with cloud infrastructure draws from hyperscaler regions in Frankfurt and Dublin. Single-source vulnerability runs through ISO 20022 schema mapping specialist labor pools concentrated in Hesse. Distribution runs through direct API marketplace integrations and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SEPA Instant Credit Transfer mandates have triggered a platform-economics inflection where API orchestration layers displace monolithic banking relationships, with interoperability specifications from the European Banking Authority determining competitive survival.
For Market Incumbents: Compound defensive positioning through captive ISO 20022 certification programs that lock enterprise clients into native remittance structures. Threat from fintech orchestration platforms demands urgent branch-network API portal deployment. Vertical integration into fraud-scoring engines anchored in machine-learning transaction scoring preserves merchant acceptance economics against sub-second settlement risks.
For New Entrants and Emerging Players: BaFin payment service licensing fast-tracks market entry for API-first infrastructure specialists lacking legacy stack fragmentation. White-space concentrates in Saxony and Brandenburg manufacturing corridors underserved by instant settlement infrastructure. Go-to-market should embed Request-to-Pay messaging into procurement workflow automation for Mittelstand exporters.
For Investors and Strategic Acquirers: ECB retail digital euro specifications reshape the acquisition landscape toward API infrastructure providers with proven interoperability upgrade capabilities. Long-term viability centers on first-mover positioning in central bank digital currency integration layers. Target acquisition archetype: mid-tier banks with shared service utility consolidation potential. Signal to watch is BaFin enforcement intensity on DORA sub-four-hour recovery objectives.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core Banking Migration | SEPA Instant compliance forces ISO 20022-native stack replacement across Tier-2 German institutions. |
| Embedded Finance Partnership | Automotive OEMs integrate real-time settlement into IoT-enabled usage-based billing platforms. |
| Fraud Scoring Engine Acquisition | Machine-learning transaction scoring capabilities determine merchant acceptance economics without chargeback windows. |
| Regional Expansion Corridor | Eastern German SME manufacturing clusters remain penetration laggards relative to western benchmarks. |
| Shared Service Utility Consolidation | Sparkassen and cooperative banks pool BaFin supervision costs through pooled infrastructure investments. |
Research Methodology
Operator-level perspectives from payment infrastructure architects, core banking platform engineers, BaFin supervision specialists, and merchant treasury managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against ECB payment statistics, BaFin regulatory disclosures, SEPA Instant scheme rule updates, and European Banking Authority technical standards. Bottom-up transaction volume modeling triangulated against top-down banking sector capex allocations.
Sensitivity analysis tested forecast robustness across PSD2 compliance cost scenarios and API specialist labor market tightness assumptions over the projection horizon. Segmentation dimensions modeled include payment instrument type, technology layer, customer segment by employee count, and service category. CAGRs derived from S-curve adoption modeling calibrated to SEPA Instant penetration trajectories in comparable European markets, with inputs from ISO 20022 migration timelines and open banking API call volume growth patterns.
Decision-makers should treat outputs as directional under assumptions of continued PSD2 enforcement and stable ECB monetary policy; material deviation would warrant model refresh. Specific risk factors include abrupt BaFin operational resilience deadline acceleration and wholesale merchant migration to non-bank payment orchestration platforms. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Social Media Payment Solution Market
Payments
New Zealand Payments Market
Payments
Convergent Billing Market
Payments
Mobile Payment Market
Payments
Italy Gift Cards Market
Payments
India Mobile Payments Market
Payments
Germany POS Terminal Market
Payments
Egypt Mobile Payments Market
Payments
China Prepaid Cards Market
Payments
South Korea Payments Market
Payments
Thailand Mobile Payments Market
Payments
Digital Remittance Service Market
Payments
Global Financial Cards and Payments Market
Payments
Croatia POS Terminals Market
Payments
Italy POS Terminals Market
Payments
India Payment Gateway Market