
 Canada Payments Market | 2026-2036
Canada Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Payments Market Outlook
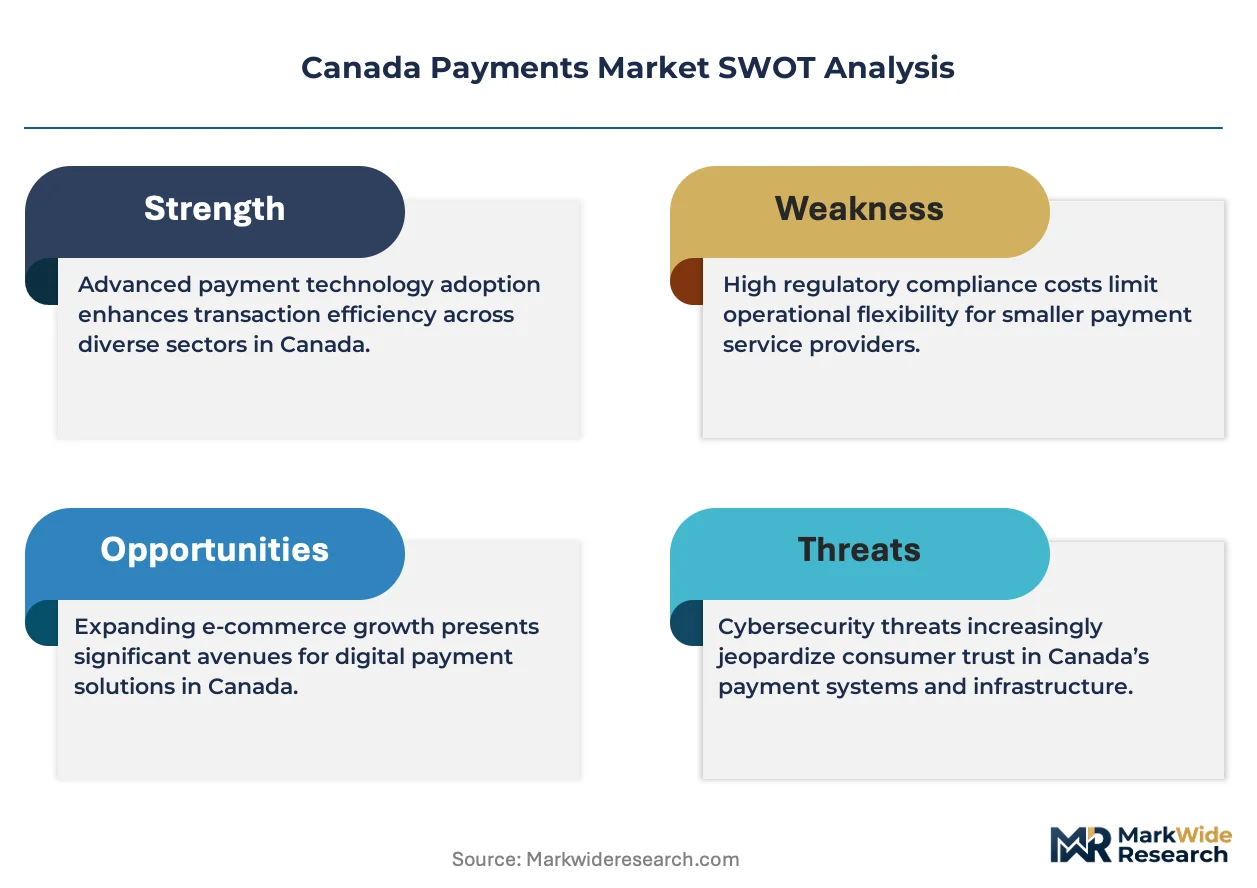
Payment engineering talent scarcity is bifurcating the competitive landscape between firms that can build proprietary clearing infrastructure and those dependent on third-party rails. Shopify anchors its merchant services ecosystem through deep integration of in-house payment processing, reducing reliance on external acquirers. Interac dominates domestic debit network access, sustaining near-universal Canadian bank account connectivity that foreign entrants struggle to replicate.
Canada Payments encompass electronic funds transfer systems, card networks, and digital wallet architectures that enable value exchange between consumers, businesses, and financial institutions through standardized messaging protocols and real-time gross settlement mechanisms. These systems process transactions denominated in Canadian dollars through centralized clearinghouses and distributed payment nodes, with primary commercial purpose of reducing friction in domestic and cross-border commerce. Mobile payments and contactless transaction methods are capturing disproportionate growth momentum as tap-to-pay limits rise and smartphone penetration deepens across Canadian demographics. Credit card and debit card payment types retain the largest share of processed volume, though margin compression in traditional interchange is pushing providers toward analytics and fraud prevention service types for sustainable returns.
Bank of Canada oversight under the Retail Payment Activities Act, alongside OSFI prudential standards for payment service provider risk management, establishes compliance thresholds that filter market access and elevate operational resilience requirements. FINTRAC anti-money laundering reporting obligations further shape product design, particularly for e-wallet and mobile payment platforms handling peer-to-peer transfers. Stakeholders must monitor how open banking framework implementation alters data portability rules and whether domestic clearing infrastructure investments keep pace with real-time payment expectations from commercial users.
Market Dynamics
The Retail Payment Activities Act is compressing operational margins for payment service providers by mandating Bank of Canada oversight, segregated funds protection, and operational risk management frameworks that favor scaled infrastructure operators over emerging entrants.
Growth Catalysts
- Real-time rail modernization:Payments Canada's Real-Time Rail infrastructure enables instant settlement for small businesses in Ontario's retail corridors, reducing cash flow friction for merchants previously dependent on batch processing cycles.
- Contactless limit escalation:Interac and Visa Canada raised tap-to-pay thresholds, accelerating merchant adoption of NFC-enabled terminals across Vancouver and Montreal transit networks.
- Open banking framework progression:The federal government's consumer-directed finance policies are unlocking account data portability, enabling fintechs to build payment initiation services that bypass traditional card rails.
Market Restraints
- Clearing infrastructure concentration:Interac's dominance in domestic debit routing creates single-point-of-failure risk for payment service providers dependent on its network for universal bank account access.
- Compliance cost escalation:The Retail Payment Activities Act registration requirements and ongoing Bank of Canada supervision impose fixed operational costs that disproportionately burden sub-scale payment facilitators.
- Cross-border interchange compression:International card scheme fee structures limit margin expansion for Canadian acquirers processing foreign-issued card transactions at domestic merchants.
Strategic Opportunities
- Underpenetrated Prairie merchant segments:Saskatchewan and Manitoba small businesses show lower digital payment acceptance rates than Ontario or British Columbia, creating whitespace for terminal deployment and software-integrated acquiring services.
- Embedded finance convergence:Vertical SaaS platforms in Canadian construction and professional services are integrating payment acceptance into workflow tools, displacing standalone merchant accounts.
- QR code payment rails:Alternative payment methods using standardized QR protocols are gaining traction among Toronto-area food delivery aggregators seeking lower-cost alternatives to card networks.
Industry Challenges
- Payment engineering talent scarcity:Specialized expertise in real-time gross settlement systems and cryptographic security protocols commands premium compensation, constraining in-house infrastructure development for mid-tier providers.
- Legacy core banking integration:Established Canadian financial institutions operate on decades-old transaction processing architectures, complicating API connectivity for fintech payment initiators.
- FINTRAC compliance latency:Anti-money laundering reporting obligations for peer-to-peer transfer platforms require transaction monitoring system investments that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Payments Market |
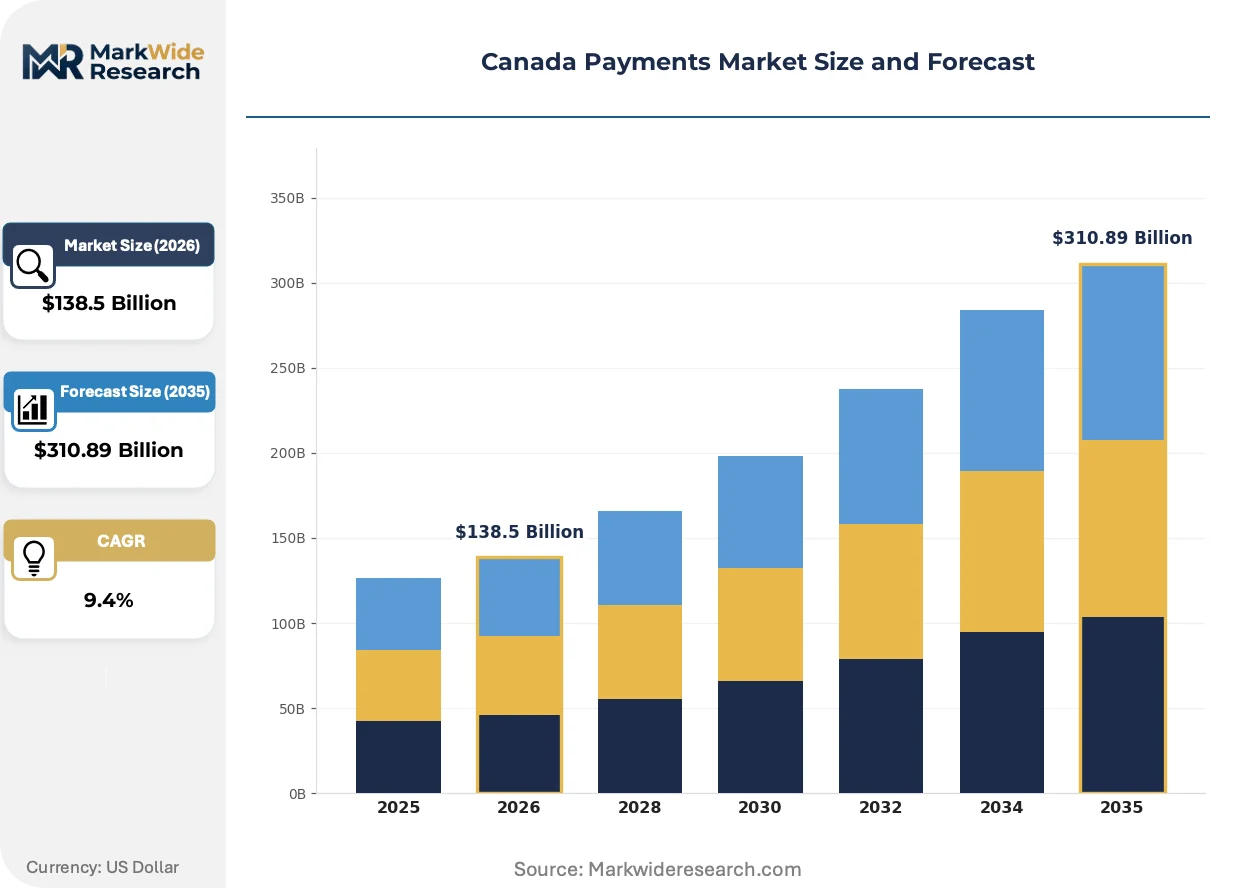
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $310.89 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Payments, E-Wallets Transaction Method: Online, In-Store, Contactless, Bank Transfer End User: Consumers, Small Businesses, Large Enterprises, Non-Profits Service Type: Payment Processing, Fraud Prevention, Settlement Services, Analytics |
| Companies Covered | PayPal Holdings Inc., Apple Inc., Visa Inc., Shopify Inc., American Express Company, Mastercard Inc., Stripe Inc., Google LLC, Interac Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Payments Market Strategic Shifts
Payment infrastructure in Canada is undergoing platform unbundling as merchant demands shift from pure transaction processing toward integrated financial services embedded within business operations.
Real-time payment messaging based on ISO 20022 standards is fragmenting legacy batch-based settlement architectures. Mid-market enterprises in Calgary's energy sector and Ottawa's government contracting ecosystem are adopting request-to-pay functionalities that bypass traditional invoice-and-wait cycles. This fragmentation is compressing working capital timelines for suppliers while forcing acquirers to rebuild core processing engines around instant confirmation protocols.
The Retail Payment Activities Act and associated Bank of Canada supervisory guidelines are mandating operational resilience testing and incident reporting thresholds for payment service providers. Fintechs holding end-user funds must now maintain segregated trust accounts and demonstrate recovery capabilities under stress scenarios. Small and medium payment facilitators are responding by outsourcing compliance infrastructure to specialized regtech vendors rather than building internal governance functions.
Merchant procurement of payment acceptance is migrating from standalone terminal contracts toward unified commerce platforms. Restaurant and retail operators in Montreal and Vancouver are consolidating point-of-sale, inventory management, and payment processing under single-vendor relationships. This consolidation is most visible among multi-location quick-service brands seeking centralized reconciliation across franchise networks.
Canada Payments Market Segmentation
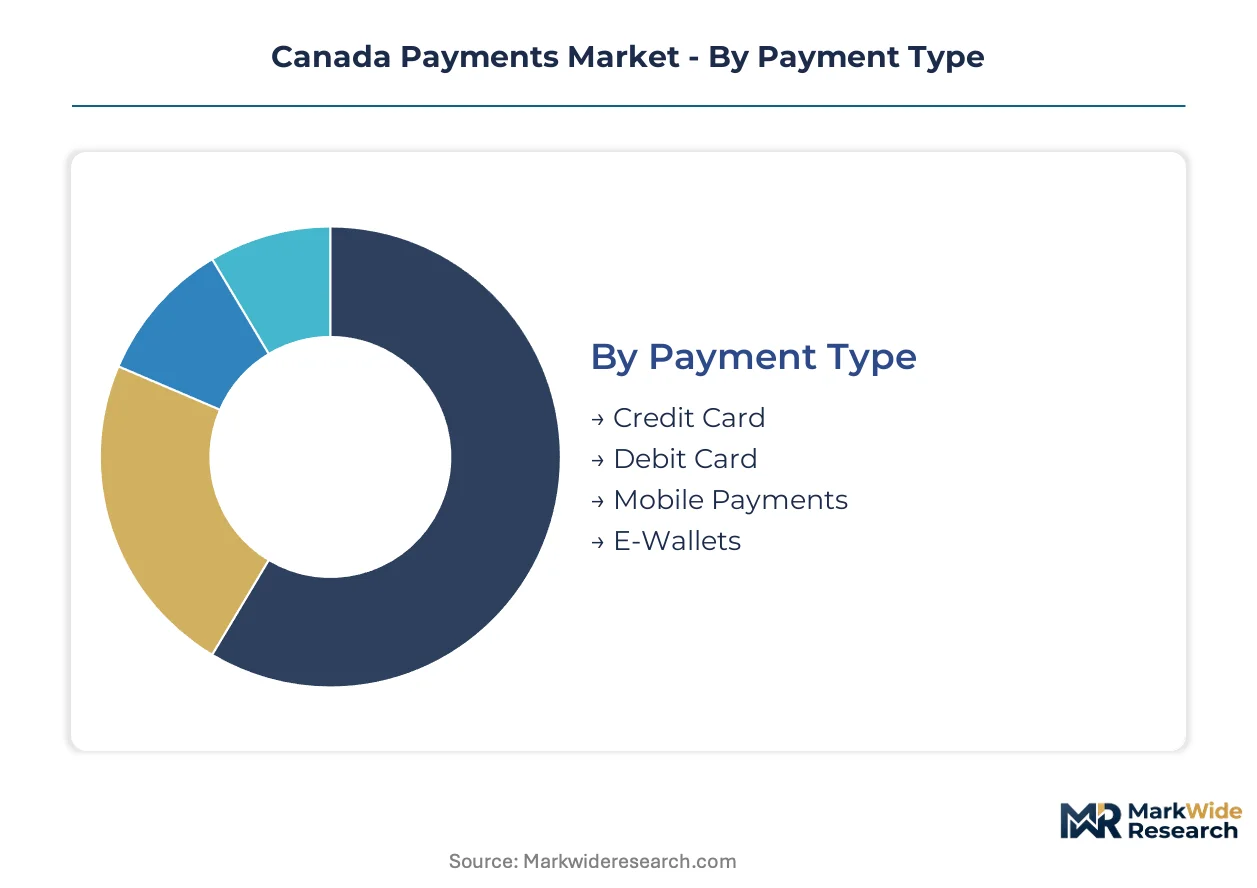
Payment infrastructure in Canada fragments across four operational dimensions that determine routing economics, compliance burden, and technology investment priorities. Understanding these segment boundaries clarifies where Interac's domestic rails retain advantage versus where open banking protocols are displacing legacy card networks.
Payment Type:
Domestic transaction volume concentrates in bank-issued instruments, while mobile and wallet-based methods draw disproportionate fintech investment despite smaller current bases.
- Credit Card:Revolving credit instruments processed through Visa, Mastercard, and American Express networks dominate high-value Canadian retail purchases. Demand clusters in Ontario's Greater Toronto Area hospitality and travel sectors, where chargeback protection and rewards programs sustain merchant acceptance despite elevated interchange.
- Debit Card:Interac-branded direct-account-access products process the majority of routine Canadian consumer transactions. Near-universal bank account connectivity through this domestic network creates switching costs that foreign entrants struggle to overcome in Vancouver and Montreal retail corridors.
- Mobile Payments:Smartphone-based NFC and app-mediated transfers are gaining traction among Toronto-area food delivery aggregators seeking frictionless checkout.
- E-Wallets:Stored-value accounts and peer-to-peer transfer platforms face heightened FINTRAC compliance latency that extends product launch timelines.
Debit card rails command the established base. The steepest expansion runs through mobile payments.
Transaction Method:
Cost structures bifurcate sharply between card-present and card-not-present environments, with contactless methods compressing the traditional online-offline divide.
- Online:E-commerce transactions routed through payment gateways face elevated fraud exposure that demands 3D Secure authentication and tokenization investments. Calgary energy sector procurement platforms and Ottawa government contractors are adopting request-to-pay functionalities that bypass traditional invoice cycles.
- In-Store:Physical terminal acceptance remains concentrated in Ontario and British Columbia retail corridors, with Prairie provinces showing underpenetrated whitespace for terminal deployment.
- Contactless:NFC tap-to-pay methods captured disproportionate growth momentum after Interac and Visa Canada raised transaction limits, accelerating terminal refresh cycles across Vancouver and Montreal transit networks.
- Bank Transfer:Direct account-to-account mechanisms leveraging Payments Canada's Real-Time Rail infrastructure enable instant settlement for small businesses previously dependent on batch processing.
In-store methods anchor current volume. Contactless adoption is climbing the fastest as tap limits escalate and smartphone penetration deepens.
End User:
Procurement sophistication varies dramatically across entity size, with small business segments driving disproportionate platform innovation demand.
- Consumers:Individual payment initiators prioritize convenience and rewards accumulation, with mobile wallet adoption skewing toward younger demographics in urban centers.
- Small Businesses:Merchants with under 50 employees generate the majority of new terminal deployments and software-integrated acquiring service demand across Saskatchewan and Manitoba.
- Large Enterprises:Multi-location operators in Montreal and Vancouver are consolidating point-of-sale, inventory management, and payment processing under single-vendor unified commerce relationships.
- Non-Profits:Charitable and social service organizations face unique donor-data portability requirements under emerging open banking frameworks.
Large enterprises command the established base. Small business services are expanding most quickly as embedded finance converges with vertical SaaS platforms.
Service Type:
Margin compression in core transaction processing is pushing providers toward adjacent value-added services for sustainable returns.
- Payment Processing:Core authorization, clearing, and settlement functions face commoditization pressure from third-party rail dependence and interchange compression on cross-border transactions.
- Fraud Prevention:Transaction monitoring and authentication services command premium pricing as real-time payment messaging fragments legacy batch-based architectures.
- Settlement Services:Funds movement and reconciliation functions are consolidating toward Payments Canada's Real-Time Rail infrastructure.
- Analytics:Merchant transaction data monetization is emerging as a differentiation vector for acquirers with sufficient scale to justify data science investments.
Payment processing commands the established base. Fraud prevention is gaining share fastest as real-time rail modernization elevates security requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bank of Canada anchors payment infrastructure oversight through the Retail Payment Activities Act, with provincial economic clusters driving divergent adoption patterns across the country.
Ontario
Greater Toronto Area fintech density and merchant concentration create network effects for real-time settlement infrastructure. The Retail Payment Activities Act registration requirements filter market access for payment service providers operating in the province. Toronto's corridor accelerates small business adoption of digital payment acceptance through embedded finance convergence with vertical SaaS platforms.
Quebec
Montreal's multi-location quick-service brands consolidate point-of-sale, inventory management, and payment processing under single-vendor unified commerce relationships. FINTRAC anti-money laundering reporting obligations shape product design for e-wallet platforms handling peer-to-peer transfers. The city's transit networks accelerated terminal refresh cycles after Interac raised tap-to-pay thresholds.
British Columbia
Vancouver merchants captured disproportionate contactless growth momentum as NFC tap-to-pay methods expanded across retail corridors. The Bank of Canada operational resilience testing mandates elevate compliance thresholds for payment facilitators serving Pacific Coast enterprises. Victoria's government contracting ecosystem adopts request-to-pay functionalities that bypass traditional invoice cycles.
Alberta
Calgary's energy sector procurement platforms drive demand for real-time payment messaging based on ISO 20022 standards. OSFI prudential standards for payment service provider risk management establish compliance benchmarks for mid-market enterprises. The city's supplier networks compress working capital timelines through instant confirmation protocols replacing batch processing.
Prairie Provinces
Saskatchewan and Manitoba small businesses show lower digital payment acceptance rates than Ontario or British Columbia, creating whitespace for terminal deployment. The Retail Payment Activities Act imposes fixed operational costs that disproportionately burden sub-scale payment facilitators in these markets. Winnipeg and Regina merchant segments represent underpenetrated targets for software-integrated acquiring services.
Canada Payments Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Canadian payments ecosystem. Domestic network operators with proprietary clearing infrastructure command premium positioning, while third-party rail-dependent providers compete on merchant acquisition efficiency. Three archetypes dominate: domestic debit network incumbents, integrated commerce platform operators, and global card scheme affiliates. Competitive moves concentrate on embedded finance partnerships and real-time rail infrastructure investments.
Within the domestic network tier, Interac Corp. exemplifies universal bank account connectivity that foreign entrants struggle to replicate. Among integrated commerce platforms, Shopify Inc. anchors merchant services ecosystems through deep in-house payment processing integration. At the global scheme vector, Visa Inc. and Mastercard Inc. occupy positions in high-value retail purchases where chargeback protection and rewards programs sustain merchant acceptance despite elevated interchange.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Apple Inc. |
| Visa Inc. |
| Shopify Inc. |
| American Express Company |
| Mastercard Inc. |
| Stripe Inc. |
| Google LLC |
| Interac Corp. |
| Others |
Value Chain & Pricing Dynamics
Scale economies in real-time clearing infrastructure anchor pricing power for domestic network operators while compressing margins for third-party rail-dependent providers across Ontario and British Columbia. Payments Canada's Real-Time Rail investments concentrate operational leverage among scaled infrastructure owners, forcing sub-scale payment facilitators toward regtech outsourcing and compliance cost absorption.
Pricing Analysis
Ontario's Greater Toronto Area commands premium pricing for embedded finance integrations, while Prairie province merchants face elevated per-transaction costs due to lower terminal density and fragmented acquiring relationships. The market operates on hybrid SaaS-tiered and per-transactional models, with price differentiation resting on volume scale and certification tier under Bank of Canada oversight. Cost compression in core processing is intensifying because interchange compression on cross-border transactions limits margin expansion. Small businesses in Saskatchewan and Manitoba exhibit highest price sensitivity, while multi-location quick-service brands in Montreal prioritize unified commerce functionality over unit economics.
Supply Chain Analysis
Strategic stockpiling of engineering talent dominates inventory strategy, with payment service providers maintaining bench capacity in cryptographic security and ISO 20022 messaging expertise. Supply concentrates in Canada for domestic debit routing through Interac's infrastructure, with critical dependencies on US-based cloud infrastructure and Asian semiconductor fabrication for terminal hardware. Single-source vulnerability in domestic clearing rails creates systemic risk for providers lacking alternative settlement pathways. Distribution runs through direct sales teams targeting enterprise merchants and ISO partnerships penetrating small business segments in underpenetrated Prairie corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in real-time gross settlement systems commands premium compensation that constrains in-house development timelines for mid-tier providers. The market rewards firms that secure captive engineering capacity or outsource to specialized infrastructure vendors.
For Market Incumbents: Consolidate compliance infrastructure investments to capture operational resilience mandates under Bank of Canada supervision. Acquire regtech capabilities or build internal governance functions to reduce outsourcing dependency. Defend against open banking disintermediation by deepening ISO 20022 integration with legacy core banking architectures. Prioritize vertical integration into fraud prevention analytics as margin compression accelerates in core processing. For New Entrants and Emerging Players: Differentiate on embedded finance convergence with vertical SaaS platforms in Canadian construction and professional services. Target Saskatchewan and Manitoba small business segments where terminal deployment rates lag Ontario and British Columbia. Pursue QR code payment rails as lower-cost alternatives to card networks among Toronto-area food delivery aggregators. Lead with software-integrated acquiring services rather than standalone terminal contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated commerce platform operators with unified POS-payment-inventory relationships. Long-term viability hinges on proprietary clearing infrastructure or exclusive embedded finance partnerships that lock in merchant switching costs. Target acquisition archetypes include mid-tier payment facilitators with Bank of Canada registration compliance already operational. Watch for inflection when open banking framework implementation accelerates account data portability and payment initiation service adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rail Infrastructure Investment | Payments Canada's settlement modernization enables instant confirmation protocols that compress supplier working capital cycles. |
| Embedded Finance Partnership | Vertical SaaS integration in construction and professional services displaces standalone merchant account relationships. |
| Regulatory Compliance Outsourcing | Specialized regtech vendors capture Retail Payment Activities Act mandates that burden sub-scale payment facilitators. |
| Fraud Prevention Capability Buildout | Transaction monitoring investments command premium pricing as ISO 20022 messaging fragments legacy batch architectures. |
| Prairie Province Market Entry | Saskatchewan and Manitoba whitespace for terminal deployment and software-integrated acquiring services offers expansion runway. |
Study Parameters
Operator-level perspectives from payment engineering directors, merchant acquiring executives, Bank of Canada supervisory staff, and fintech product managers anchored the qualitative base. Primary interviews combined with secondary validation from Payments Canada infrastructure disclosures, FINTRAC regulatory filings, Interac network statistics, and OSFI prudential guidelines. Bottom-up merchant adoption modeling and top-down payment volume triangulation calibrated segmentation outputs.
Sensitivity analysis across interchange compression scenarios and open banking adoption curves shaped the analytical framework. Segmentation dimensions modeled include payment type, transaction method, end user scale, and service type across the projection horizon. CAGRs derived from volume trajectory analysis weighted by regional fintech density and merchant concentration patterns. Real-Time Rail deployment timelines and Retail Payment Activities Act compliance cost curves served as industry-specific forecast inputs.
Material uncertainties — regulatory framework acceleration, engineering talent availability, and legacy core banking integration friction — sit outside the modeled envelope. Forecasts reflect assumptions around merchant digital adoption continuity and domestic clearing infrastructure investment pacing. Revision becomes warranted when open banking data portability rules or Real-Time Rail interoperability standards cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Kenya Mobile Money Market
Payments
Germany Payment Gateway Market
Payments
Freight Audit and Payment Service Market
Payments
Brazil POS Terminal Market
Payments
Portugal Mobile Payments Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Global Digital Wallets Market
Payments
Accelerator Card Market
Payments
Forex Cards Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Singapore Remittance Market
Payments
Cyprus POS Terminals Market
Payments
3D Secure Pay Authentication Market
Payments
Wireless POS Terminals Market
Payments
United Kingdom Mobile Payments Market