
 Global Accounts Payable Software Market | 2026-2036
Global Accounts Payable Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accounts Payable Software Market Analysis
GDPR-aligned data-residency rules are decoupling European procurement decisions from legacy on-premise stacks. SAP SE anchors continental enterprise deployments through deep ERP integration. Oracle Corporation leverages autonomous-database features to sustain competitive positioning in financial-services accounts payable. Zoho Corporation Pvt. Ltd. competes aggressively on subscription economics for mid-market buyers across Asia-Pacific and Latin America.
Accounts payable software automates invoice receipt, matching, approval routing, and payment execution, typically integrating optical character recognition, machine-learning extraction, and API-first connectivity to enterprise resource planning systems. Cloud-based deployment leads segment composition by accessibility and scalability, while SaaS delivery captures the fastest expansion as vendors shift from perpetual licenses to recurring-revenue models. Large enterprises dominate end-user value pools, though SMB uptake accelerates where bundled accounting-platform integrations reduce implementation friction.
The EU AI Act, ISO 27001 certification requirements, and national tax-transparency mandates from Germany's BMF and India's CBDT reshape product roadmaps and cross-border market access. Compliance cost now functions as a segmentation mechanism, favoring vendors with pre-certified security frameworks and localized reporting modules. Stakeholders must monitor how real-time e-invoicing mandates proliferate beyond current European and Latin American adopters.
Market Dynamics
Real-time e-invoicing mandates across Germany, Italy, and Brazil are compressing implementation timelines for accounts payable platforms, forcing vendors to embed localized tax-reporting modules directly into core architectures rather than offering them as aftermarket add-ons.
Growth Catalysts
- Machine-learning invoice extraction:Healthcare systems in the United States deploy OCR-to-ERP pipelines to satisfy HIPAA audit-trail requirements while cutting manual processing hours.
- Germany's BMF e-invoicing mandate:Mid-market manufacturers accelerate cloud procurement to meet 2025 real-time reporting deadlines, expanding addressable market for API-first vendors.
- ISO 27001 certification thresholds:Financial-services buyers in the United Kingdom now require pre-certified security frameworks, filtering vendor pools and consolidating procurement toward compliant platforms.
Market Restraints
- Legacy ERP integration costs:On-premise SAP and Oracle installations in continental Europe demand expensive middleware development, slowing cloud migration for established enterprises.
- Talent concentration in Bangalore and Dublin:Engineering capacity for AI-driven matching algorithms clusters in two metropolitan hubs, creating wage pressure and delivery bottlenecks.
- Substitution by bundled accounting suites:QuickBooks and Xero embed basic AP functionality, capturing price-sensitive SMBs before specialized vendors can engage.
Strategic Opportunities
- India's CBDT e-invoicing expansion:The Goods and Services Tax Network mandates real-time invoice reporting, opening deployment opportunities for platforms with rupee-denominated pricing and local data centers.
- Blockchain-anchored payment rails:Convergence of distributed ledger technology with SWIFT gpi enables programmable settlement for cross-border supplier networks.
- Embedded finance partnerships:AP platforms integrate working capital advances at the point of invoice approval, capturing interest margin from cash-constrained suppliers in Latin America.
Industry Challenges
- Multi-jurisdiction tax-engine maintenance:Vendors must sustain parallel reporting modules for Brazil's Nota Fiscal, Italy's SDI, and Saudi Arabia's ZATCA, fragmenting R&D resources.
- API versioning complexity:ERP connectors require continuous recertification against quarterly SAP and Oracle updates, consuming engineering bandwidth that could advance core AI capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accounts Payable Software Market |
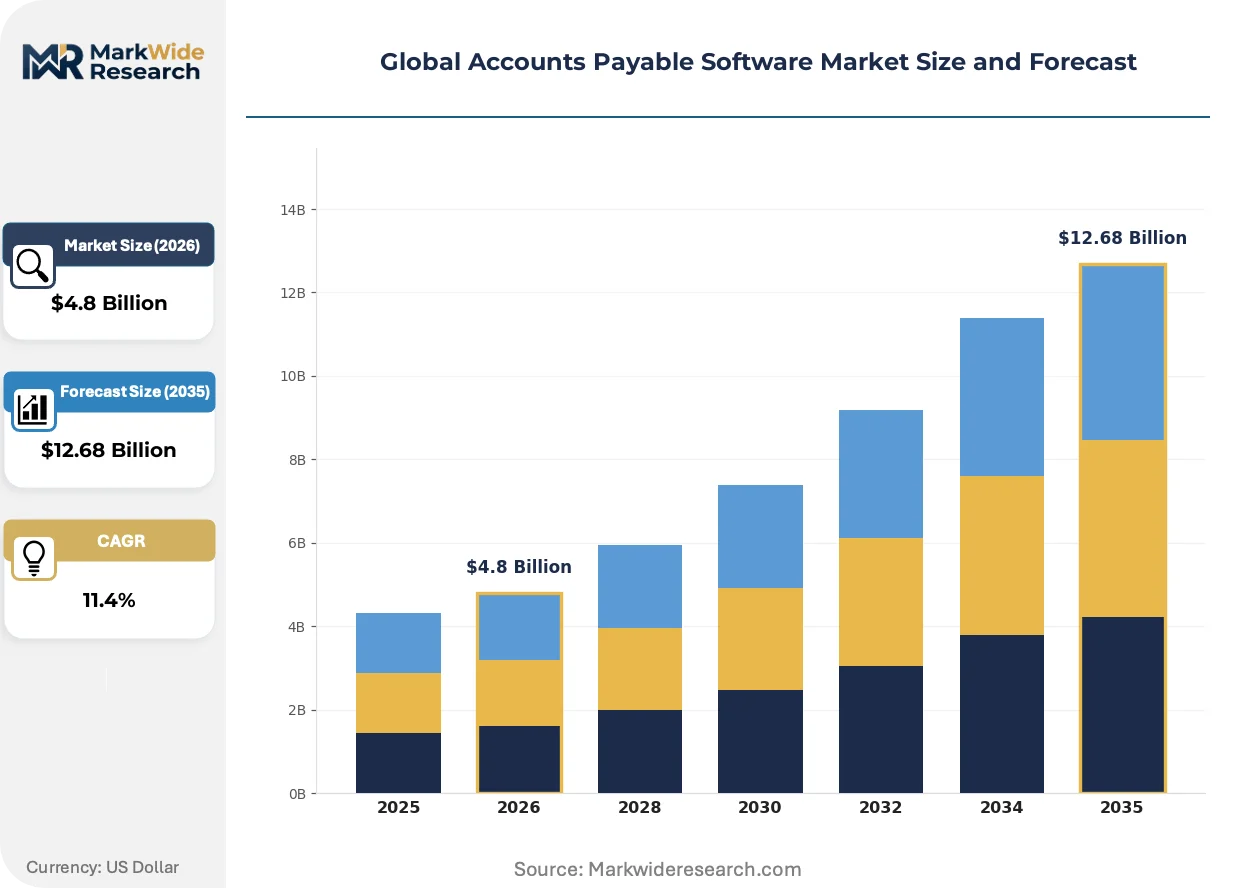
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: SMBs, Large Enterprises, Financial Institutions, Public Sector Deployment: Single Tenant, Multi-Tenant, Virtual Private Cloud, Local Server Service Type: Implementation, Maintenance, Training, Consulting |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, Intuit Inc., Sage Group Plc, Coupa Software Inc., AvidXchange, Tipalti Inc., Zoho Corporation Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accounts Payable Software Market Emerging Trajectories
Generative AI is penetrating accounts payable workflows through autonomous exception handling and natural-language supplier inquiries, compressing the traditional three-way match into near-real-time validation cycles.
Large language models trained on invoice corpora are rewriting how platforms handle non-standard document formats. Retail and logistics buyers in Germany deploy these systems to process handwritten delivery notes and fragmented PDFs without human intervention. The technology is rewriting competitive benchmarks for straight-through processing rates, forcing incumbent vendors to retrain extraction engines or cede mid-market share.
The EU AI Act's risk-classification framework now governs automated payment-approval workflows in European deployments. Systems making material disbursement decisions fall under high-risk algorithmic categories, triggering conformity assessment obligations and documentation standards. Financial-services institutions in France and the Netherlands are restructuring approval hierarchies to maintain human oversight checkpoints, adding implementation complexity but creating compliance-service revenue streams for advisory partners.
Subscription fatigue among CFOs is shortening software evaluation cycles and elevating integration speed as a primary selection criterion. Buyers in the United States increasingly demand pre-built connectors to NetSuite and Sage Intacct, displacing lengthy custom-deployment projects. Manufacturing verticals in the Midwest show the strongest preference for 30-day implementation guarantees, pressuring vendors to productize onboarding rather than treat each deployment as a professional-services engagement.
Global Accounts Payable Software Market Segmentation
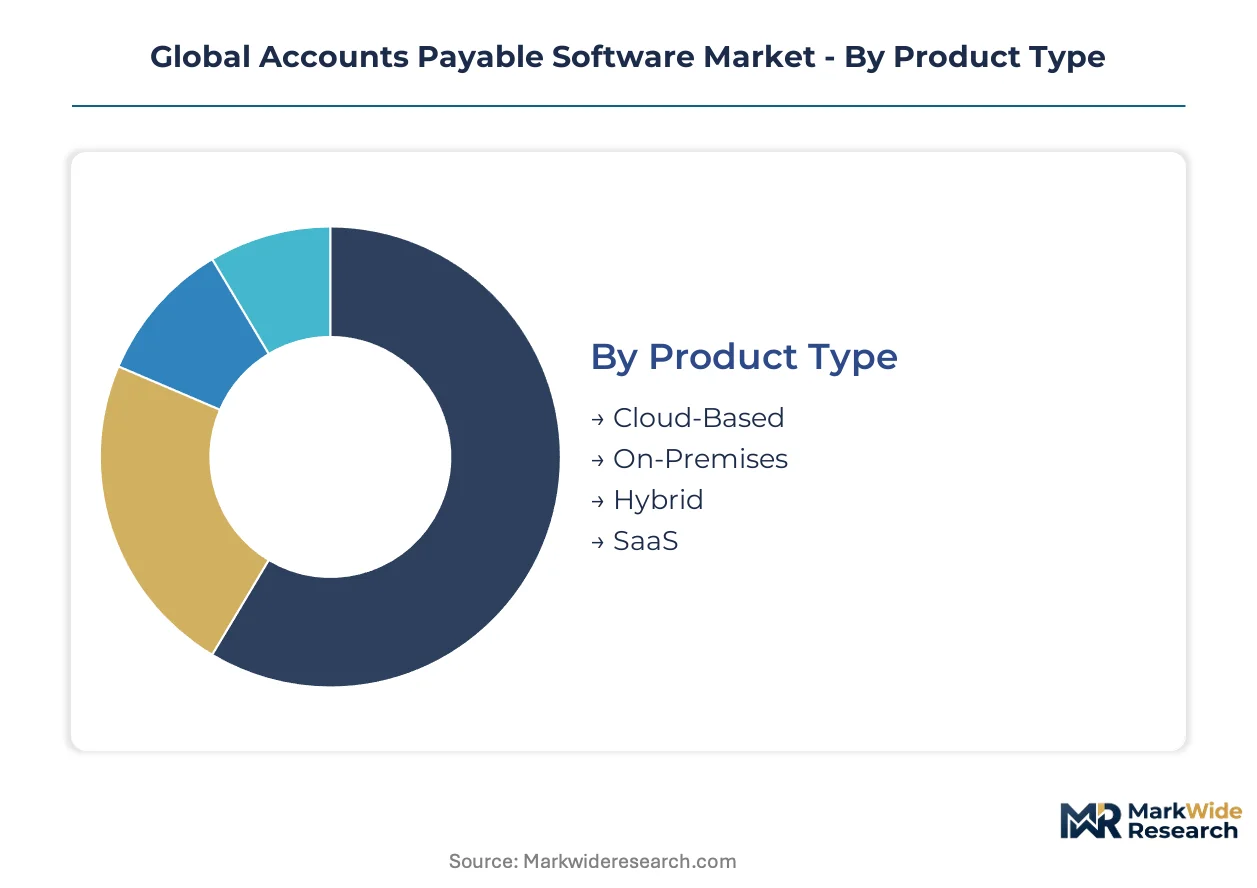
Segmentation in accounts payable software reveals how procurement priorities diverge across infrastructure requirements and organizational scale. Buyers select deployment architectures based on audit-trail mandates, data-residency obligations, and integration complexity with legacy ERP systems.
Product Type:
Cloud-based deployments demand minimal capital expenditure for hardware provisioning, while on-premises installations require substantial upfront investment in server infrastructure and security hardening.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning enable real-time scaling for seasonal invoice volumes. Healthcare systems in the United States prioritize these deployments to satisfy HIPAA audit-trail requirements without maintaining physical data centers.
- SaaS:Subscription delivery models eliminate perpetual license costs and accelerate procurement cycles through standardized API connectors. Mid-market manufacturers in Germany select SaaS platforms to meet BMF e-invoicing mandates with predictable operational expenditure.
- On-Premises:Dedicated hardware installations serving financial institutions with strict data-sovereignty requirements.
- Hybrid:Split architectures preserving sensitive payment data on local servers while routing routine processing to cloud instances.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
End User:
Procurement sophistication varies dramatically by organizational scale, with financial institutions demanding certified security frameworks that price out smaller competitors.
- Large Enterprises:Complex multi-entity structures requiring automated intercompany netting and consolidated cash forecasting. Manufacturing conglomerates across Germany, the United Kingdom, and the United States deploy these systems to harmonize supplier payment terms across dozens of operating subsidiaries.
- Financial Institutions:Regulatory-grade platforms with ISO 27001 certification and real-time fraud detection. Banks in the United Kingdom mandate pre-certified security frameworks that filter vendor pools toward compliant platforms.
- SMBs:Bundled accounting-platform integrations reducing implementation friction for resource-constrained finance teams.
- Public Sector:Procurement systems adhering to government-specific audit-trail and transparency requirements.
Large Enterprises command the deepest functionality requirements; Financial Institutions impose the steepest compliance barriers to entry.
Deployment:
Isolation requirements drive infrastructure decisions, with single-tenant configurations commanding premium pricing for dedicated resource allocation.
- Multi-Tenant:Shared infrastructure maximizing economies of scale for standardized invoice-processing workloads. Vendors serving Latin American mid-market buyers leverage these architectures to deliver rupee-denominated pricing and localized reporting modules.
- Virtual Private Cloud:Partitioned environments combining cloud elasticity with network isolation. Retail and logistics buyers in Germany deploy VPC configurations to process handwritten delivery notes through generative AI extraction while maintaining GDPR-aligned data residency.
- Single Tenant:Dedicated instances for organizations prohibiting resource sharing with external entities.
- Local Server:Physical hardware installations in jurisdictions with strict data-localization statutes.
Multi-Tenant dominates addressable volume; Virtual Private Cloud is climbing the fastest as GDPR-aligned rules decouple European procurement from legacy stacks.
Service Type:
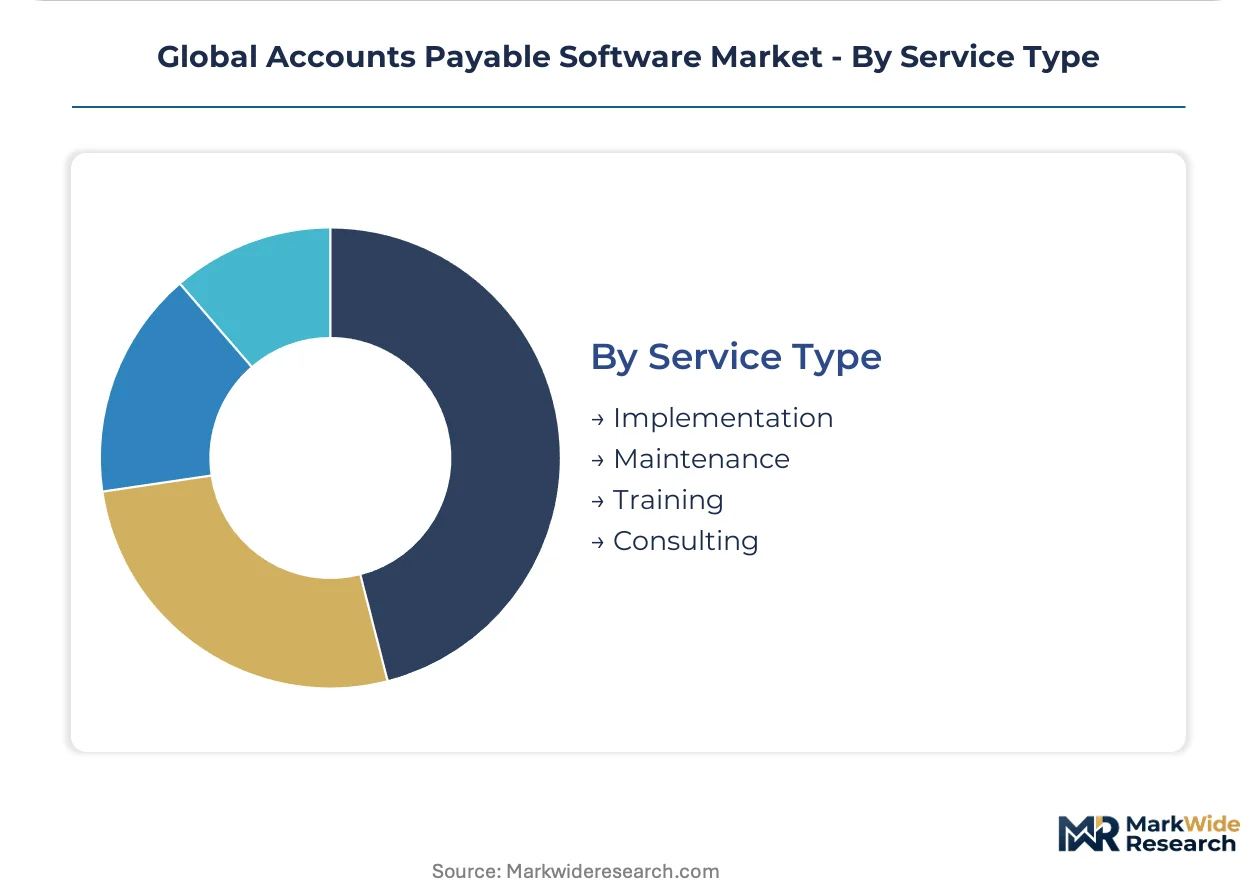
Professional services intensity correlates with deployment complexity, with implementation consuming the largest share of project budgets for customized ERP integrations.
- Implementation:System configuration, data migration, and connector development for SAP and Oracle ERP environments. On-premise installations in continental Europe demand expensive middleware development, slowing cloud migration timelines.
- Consulting:Workflow redesign and compliance advisory for multi-jurisdiction tax-engine maintenance. Vendors sustain parallel reporting modules for Brazil's Nota Fiscal, Italy's SDI, and Saudi Arabia's ZATCA, fragmenting advisory resources.
- Maintenance:Continuous recertification against quarterly SAP and Oracle API updates.
- Training:Change management programs accelerating user adoption of automated approval hierarchies.
Implementation captures the largest service contract values; Consulting is gaining share fastest as EU AI Act conformity assessments add implementation complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Dublin concentrate engineering talent for AI-driven matching algorithms, while Frankfurt's financial district and London's regulatory technology cluster anchor European demand for certified compliance frameworks.
United States
Healthcare systems deploy OCR-to-ERP pipelines to satisfy HIPAA audit-trail requirements while reducing manual processing hours. The FDA's data-integrity guidance shapes procurement specifications for pharmaceutical finance departments. Silicon Valley vendors and Chicago-based manufacturing conglomerates drive cloud-native platform adoption.
Germany
Mid-market manufacturers accelerate cloud procurement to meet BMF e-invoicing mandates with 2025 real-time reporting deadlines. The EU AI Act's risk-classification framework governs automated payment-approval workflows in Frankfurt's banking sector. Bavarian automotive suppliers and North Rhine-Westphalia industrial clusters demand API-first vendor architectures.
United Kingdom
Financial-services buyers mandate ISO 27001 pre-certified security frameworks that filter vendor pools toward compliant platforms. The Financial Conduct Authority's operational resilience requirements reshape procurement criteria for London-based institutions. Edinburgh's fintech corridor and Manchester's manufacturing belt show divergent deployment preferences.
India
The CBDT's Goods and Services Tax Network mandates real-time invoice reporting, opening deployment opportunities for platforms with rupee-denominated pricing. Bangalore's engineering talent concentration creates wage pressure for AI-driven matching algorithm development. Mumbai's financial district and Hyderabad's technology corridor anchor domestic vendor expansion.
Brazil
Nota Fiscal electronic invoicing requirements compress implementation timelines for accounts payable platforms serving Latin American supplier networks. ANVISA's traceability mandates extend to pharmaceutical supply chain finance operations. São Paulo's industrial belt and Rio de Janeiro's service economy drive divergent functional requirements.
Global Accounts Payable Software Market Vendor Landscape
United States producers anchor the scale-driven tier; German and British specialists hold compliance-certification advantages. The vendor base organizes around three strategic archetypes: ERP-integrated incumbents with deep enterprise connectivity, API-first challengers compressing implementation timelines, and vertical specialists embedding tax-reporting modules for jurisdiction-specific mandates. Consolidation pressure intensifies through strategic partnerships bridging legacy system integration with cloud-native delivery, while portfolio diversification into embedded finance captures interest-margin opportunities.
Within the ERP-integrated tier, SAP SE and Oracle Corporation represent entrenched positioning through deep system connectivity and autonomous-database features respectively. Zoho Corporation Pvt. Ltd. occupies a distinct position competing on subscription economics for mid-market buyers across Asia-Pacific and Latin America.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Intuit Inc. |
| Sage Group Plc |
| Coupa Software Inc. |
| AvidXchange |
| Tipalti Inc. |
| Zoho Corporation Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices from hyperscaler pricing benchmarks cascade through SaaS vendor cost structures, compressing margins for mid-tier platforms while concentrating pricing power among ERP-integrated incumbents with captive data-center capacity. This cost transmission splits procurement decisions between premium-certified deployments and economy-tier bundled offerings.
Pricing Analysis
Short lead-time implementation guarantees command 15-40% premiums over standard 90-day deployment cycles, particularly among Midwest manufacturing buyers demanding 30-day onboarding. The dominant pricing structure stratifies across premium, standard, and economy tiers tied to ISO 27001 certification grade and API connector depth. Cost compression in the mid-market tier is intensifying because QuickBooks and Xero embed basic AP functionality at subscription price points below specialized vendor entry levels. SMB finance teams exhibit the highest price sensitivity, while Frankfurt banking institutions and London financial-services buyers prioritize compliance certification over cost.
Supply Chain Analysis
ISO 27001 certification gates vendor participation in United Kingdom financial-services procurement, filtering supplier pools toward pre-certified platforms. Engineering capacity concentrates in India, Ireland, and Germany, with Bangalore and Dublin hubs anchoring AI-driven matching algorithm development. Software supply chains rest on cloud infrastructure from United States hyperscalers, specialized OCR training data from document processing vendors, and localized tax-reporting module development. Single-source vulnerability clusters around SAP and Oracle API versioning, where quarterly update recertification consumes disproportionate engineering bandwidth. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Talent scarcity in Bangalore and Dublin for AI-driven matching algorithms props pricing for certified engineering capacity, constraining vendor expansion velocity and sustaining incumbent advantages.
For Market Incumbents: To counter API-first challengers compressing implementation timelines, SAP SE and Oracle Corporation should deepen ERP connector certification programs while acquiring specialized tax-reporting module developers in Brazil and India. Capacity addition in Frankfurt's compliance-technology cluster reinforces positioning for EU AI Act conformity assessments. For New Entrants and Emerging Players: Generative AI extraction for handwritten delivery notes and fragmented PDFs offers a technology-first wedge into German retail and logistics verticals underserved by incumbent OCR engines. India's CBDT e-invoicing expansion presents the most penetrable geography, with rupee-denominated pricing and local data-center presence as the essential go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical specialists with pre-certified ISO 27001 frameworks in the United Kingdom and Germany, where regulatory complexity sustains acquisition premiums. Long-term viability across the analysis window hinges on embedded finance integration capabilities. The signal to watch is working capital advance penetration rates among Latin American supplier networks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built connectors to NetSuite and Sage Intacct displace custom-deployment projects for United States mid-market buyers. |
| Acquisition of Specialist Firm | Tax-reporting module developers in Brazil and India address Nota Fiscal and CBDT mandate complexity. |
| Strategic Partnership | Embedded finance alliances with regional banks capture interest margin from cash-constrained Latin American suppliers. |
| Geographic Expansion | Rupee-denominated pricing and Mumbai data centers unlock India's Goods and Services Tax Network mandates. |
| Product Launch | Generative AI exception-handling modules rewrite competitive benchmarks for straight-through processing rates in Germany. |
Methodological Framework
Document review covered SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory frameworks, complemented by interviews with CTOs, IT procurement officers, and integration specialists at healthcare systems and manufacturing conglomerates. Secondary validation drew from SAP and Oracle API documentation, ISO certification databases, and national tax-authority mandate publications. Bottom-up deployment estimates and top-down market sizing were triangulated against vendor-reported subscription metrics.
Market size and growth trajectory outputs were generated through segmentation across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from trend extrapolation of cloud migration velocity and real-time e-invoicing mandate implementation timelines. Forecast inputs incorporated HIPAA audit-trail requirement diffusion among United States healthcare systems and BMF deadline compliance pressure among German mid-market manufacturers.
Several conditions sit outside the modeled scope, including macroeconomic shocks to cloud infrastructure pricing, abrupt ERP vendor API policy changes, and unanticipated regulatory harmonization across European tax-transparency frameworks. Forecasts reflect documented assumptions about mandate implementation schedules and technology adoption curves. A model refresh is warranted upon material change in EU AI Act enforcement patterns or hyperscaler pricing benchmark movements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
New Zealand Payments Market
Payments
In Vehicles Payment Market
Payments
Finland Payments Market
Payments
Indonesia Payments Infrastructure Market
Payments
Digital Debit Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
India Forex Cards Market
Payments
Global Telecom Billing Market
Payments
India Payments Market
Payments
China Payments Market
Payments
Luxembourg POS Terminals Market
Payments
Mobile Money Market
Payments
Belgium POS Terminals Market
Payments
Retail Cash Management Market
Payments
Remote Mobile Payment Market
Payments
China POS Terminals Market