
 Telecom Cloud Billing Market | 2026-2036
Telecom Cloud Billing Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Cloud Billing Market Intelligence
The transition to real-time, convergent billing platforms is reorganizing how telecom operators manage revenue streams from complex digital services. Amdocs leverages its deep telecom domain expertise to provide end-to-end managed billing services for Tier-1 carriers. Oracle differentiates through the integration of its billing solutions with its comprehensive suite of enterprise resource planning and customer experience cloud applications. Meanwhile, Ericsson specializes in billing systems that are tightly coupled with its 5G network infrastructure and BSS offerings.
Telecom cloud billing refers to software platforms that automate the revenue management lifecycle for communications service providers on cloud infrastructure. These systems are engineered for high-volume transaction processing, enabling monetization of dynamic services like 5G, IoT, and content streaming. Usage-based and subscription billing types are displacing legacy flat-rate plans. The hybrid cloud deployment model is favored by operators seeking a balance of security for sensitive data and the agility of public cloud resources.
Data sovereignty and privacy regulations, including the EU's GDPR and national frameworks from bodies like the US FCC and Brazil's LGPD, impose strict rules on customer data handling. These compliance obligations directly influence architectural choices, often favoring hybrid cloud deployments to keep billing data within national borders. Ultimately, a vendor's success will be determined by its platform's ability to support complex, multi-partner B2B2X business models and diverse monetization strategies.
Market Dynamics
The monetization imperative for massive investments in 5G and IoT infrastructure is the central force shaping the telecom cloud billing market. This requires a fundamental architectural shift from rigid, legacy systems to agile, cloud-native platforms capable of managing complex revenue models.
Growth Catalysts
- 5G Network Slicing:This technology enables operators to offer customized network services with guaranteed quality, creating demand for sophisticated billing systems that can monetize these granular, value-added offerings for enterprise clients.
- B2B2X Business Models:The expansion into multi-partner ecosystems, where carriers bill on behalf of other service providers, necessitates convergent billing platforms that can manage complex revenue sharing and settlement arrangements.
- Digital Service Proliferation:Rapid introduction of new digital services, from content streaming to mobile finance, in high-growth markets like India and Brazil, requires agile and scalable billing solutions to support fast time-to-market.
Market Restraints
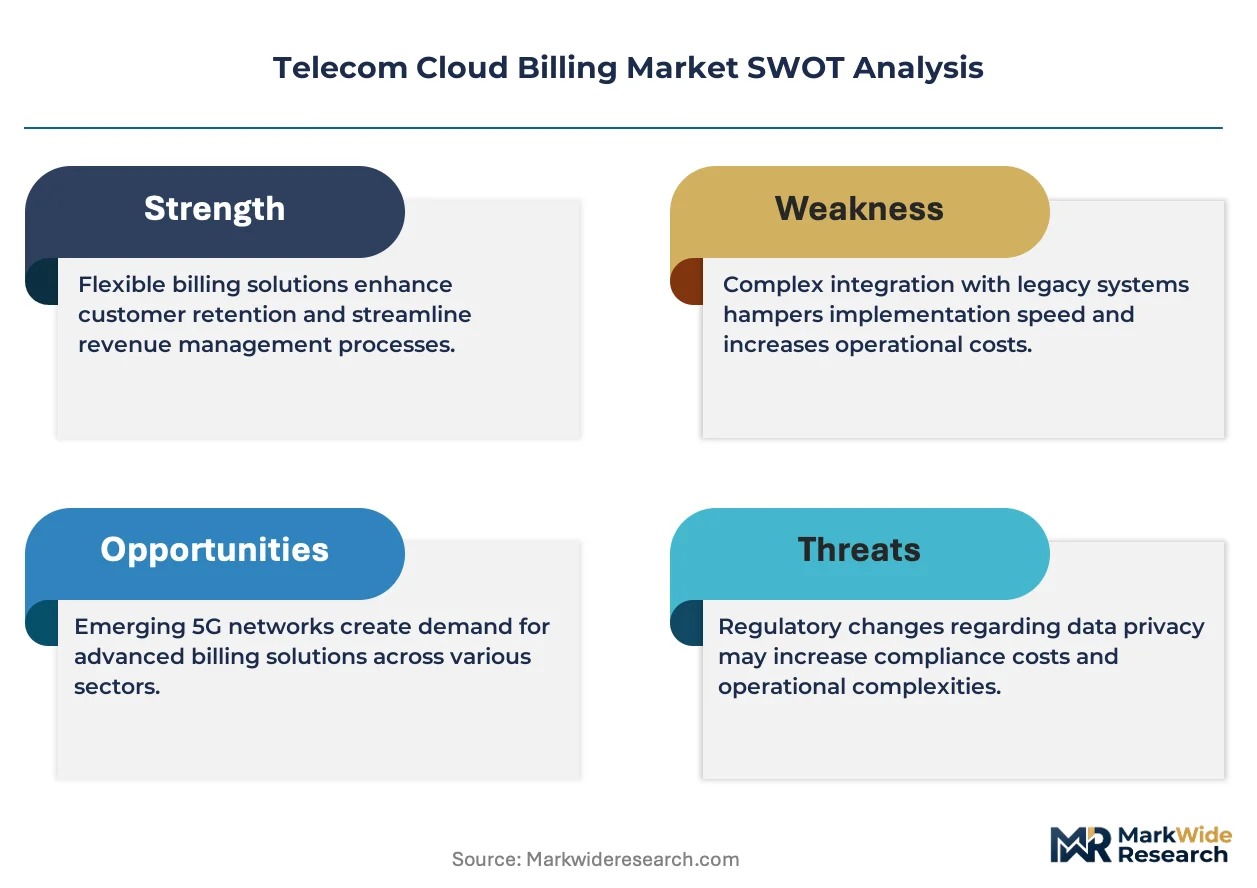
- Legacy System Migration:The significant cost, complexity, and operational risk associated with migrating decades of customer data and business logic from entrenched, monolithic billing systems to new cloud platforms is a major barrier for established operators.
- Data Sovereignty Regulations:Mandates such as the EU's GDPR and Brazil's LGPD impose strict rules on cross-border data flows, often forcing operators into more complex and costly hybrid cloud architectures to ensure compliance.
- Integration Complexity:The difficulty of integrating new cloud billing solutions with a diverse landscape of existing operational support systems (OSS), business support systems (BSS), and CRM platforms creates significant implementation friction.
Strategic Opportunities
- IoT and Edge Monetization:Developing specialized billing capabilities for the massive volume of micro-transactions generated by IoT devices and low-latency edge computing applications represents a significant new revenue stream for platform vendors.
- AI-Driven Billing Optimization:Integrating artificial intelligence and machine learning into billing platforms offers opportunities to provide value-added services like predictive churn analysis, real-time fraud detection, and personalized offer management.
- Targeting MVNOs:Mobile Virtual Network Operators require lightweight, flexible, and cost-effective billing solutions, creating a distinct market segment for vendors offering scalable, cloud-based Billing-as-a-Service platforms.
Industry Challenges
- Cloud-Native Skills Gap:A shortage of professionals with dual expertise in traditional telecom billing principles and modern cloud-native technologies like microservices and Kubernetes creates a significant talent bottleneck for both vendors and operators.
- Security and Compliance Burden:Protecting sensitive customer billing and payment data across distributed cloud environments against sophisticated cyber threats requires continuous investment in advanced security tools and adherence to evolving compliance standards.
- Interoperability Standards:The lack of universal standards for APIs and data models between different billing components and adjacent BSS/OSS functions complicates multi-vendor deployments and inhibits platform interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Cloud Billing Market |
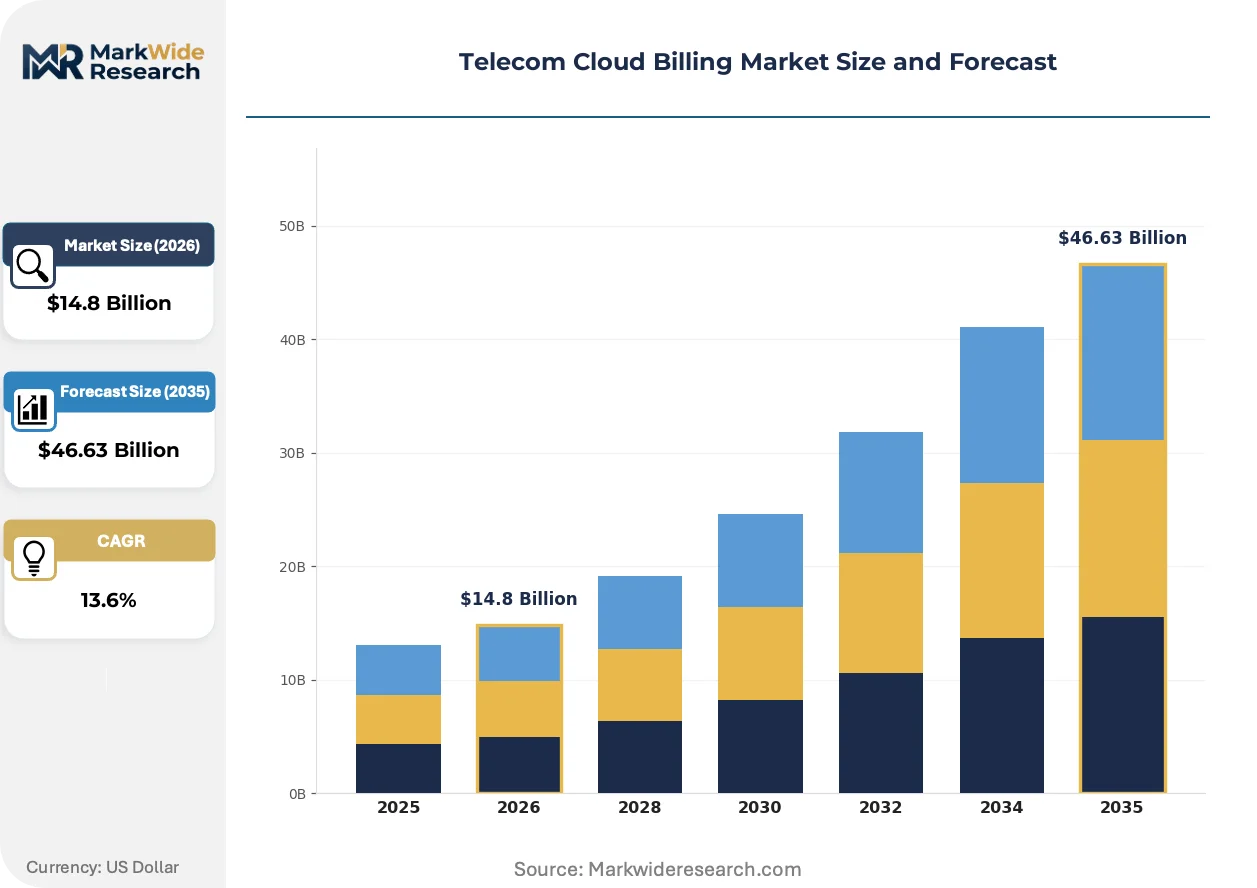
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Residential, SME, Large Enterprise, Government Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Billing Type: Usage-Based, Flat-Rate, Tiered, Subscription Solution Type: Invoicing, Payment Processing, Revenue Management, Subscriber Management |
| Companies Covered | Amdocs, Oracle, Ericsson, Nokia, Huawei Technologies, SAP, Netcracker Technology, CSG Systems International, CGI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Cloud Billing Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from static, product-centric billing functions to dynamic, software-defined monetization engines. This transformation enables communication service providers to capture value from a new generation of complex digital services.
Microservices architecture breaks down monolithic billing applications into a collection of small, independently deployable services. Communication service providers and large enterprises are adopting this model to accelerate the development and deployment of new pricing and charging rules. This architectural shift is fragmenting the traditional, all-in-one billing system, enabling operators to assemble best-of-breed solutions from multiple vendors.
Data privacy and sovereignty regulations, including the EU's GDPR, Brazil's LGPD, and rules from the US FCC, are directly influencing platform design. These frameworks impose strict controls on how customer data is stored, processed, and transferred, making compliance a primary architectural driver. The enterprise segment in regulated industries is responding by favoring hybrid cloud deployments that keep sensitive billing data within national borders.
A clear behavioral shift from fixed-rate subscriptions to dynamic, usage-based monetization is underway. This disrupts traditional billing cycles, which are being replaced by real-time convergent charging platforms that can process high volumes of variable service events. The trend is most prominent among operators launching complex B2B2X offerings, such as multi-partner IoT solutions and private 5G networks.
Telecom Cloud Billing Market Segmentation
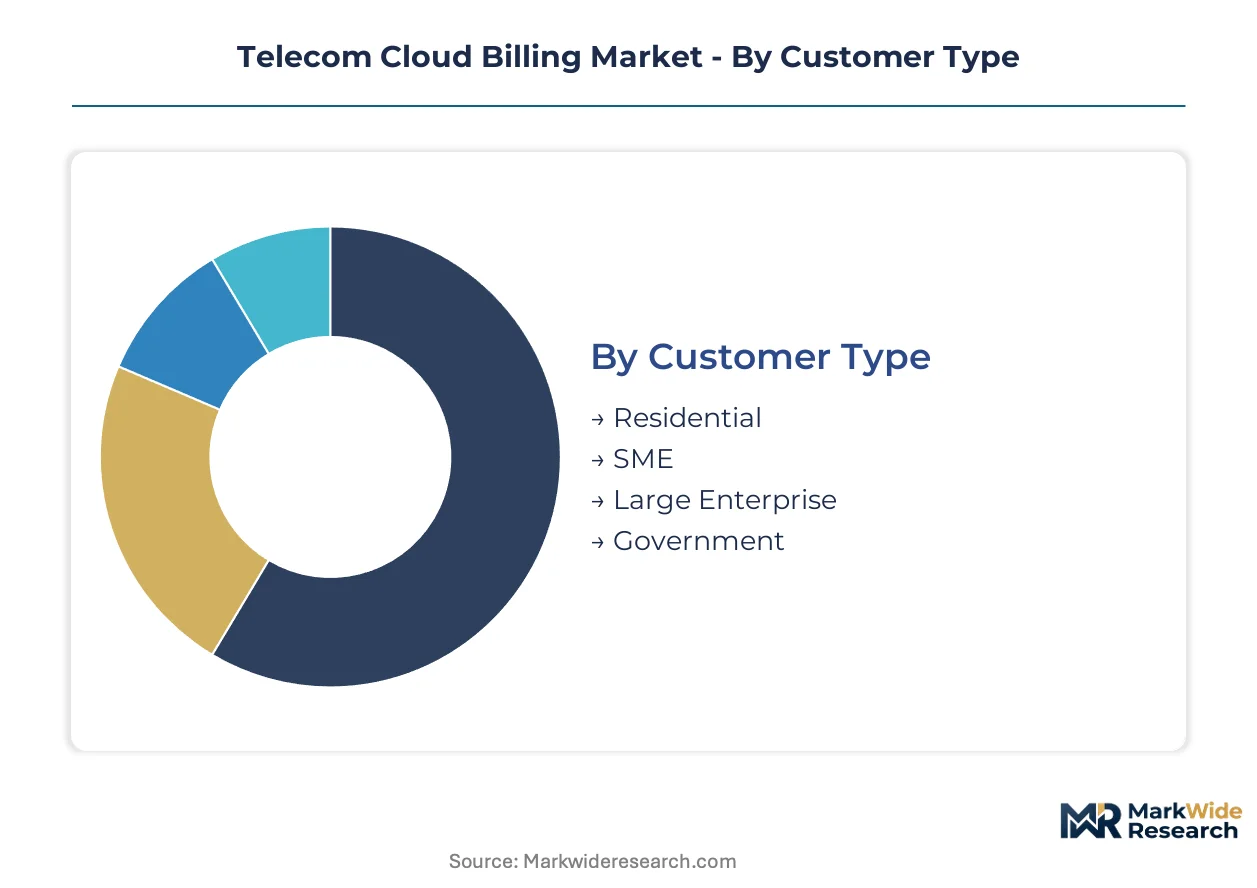
The telecom cloud billing market's intricate structure reflects diverse operator requirements and evolving service monetization strategies. Understanding these distinct segments is crucial for solution providers to align their offerings with specific customer needs and technological demands. Each category highlights unique challenges and opportunities across the digital service value chain.
Customer Type:
Margin pools within this customer category are heavily influenced by service complexity and average revenue per user. Enterprise clients typically generate higher margins due to bespoke service bundles and extensive network slicing requirements. Residential and SME segments rely on volume and standardized offerings for profitability.
- Large Enterprise:These clients demand sophisticated billing platforms to monetize complex 5G network slices, IoT solutions, and multi-partner B2B2X models. Demand is concentrating in technology-intensive industries across Germany and the United States, driven by the need for granular service level agreement billing.
- SME:Small and medium enterprises require flexible, scalable billing solutions for bundled communication services and cloud applications. Growth for these operators is significant in emerging digital economies like India and Brazil, where new businesses are rapidly adopting cloud-based tools.
- Residential:This segment focuses on high-volume, standardized subscription and usage-based billing for traditional mobile and broadband services.
- Government:Public sector entities require secure, compliant billing systems for internal communications and public services, often with stringent data sovereignty mandates.
The dominant share belongs to Residential customers due to sheer volume, while Large Enterprise is closing the gap fastest in terms of revenue contribution.
Deployment Model:
Operational expenditure and data security requirements define the cost tier for each deployment model within telecom cloud billing. Public cloud offers cost efficiency and scalability, while private and hybrid models prioritize data control and compliance. Community cloud models balance shared infrastructure with sector-specific needs.
- Hybrid Cloud:This model combines private and public cloud resources, enabling operators to maintain sensitive billing data within their private infrastructure while leveraging public cloud agility for less critical workloads. Data sovereignty regulations from the EU's GDPR and Brazil's LGPD drive its adoption.
- Public Cloud:Solutions deployed entirely on third-party cloud infrastructure offer maximum scalability, reduced operational overhead, and rapid deployment cycles. This model is gaining traction among Mobile Virtual Network Operators (MVNOs) and new digital service providers in Southeast Asia and Africa.
- Private Cloud:Operators host billing systems on their dedicated infrastructure, providing complete control over data security and compliance.
- Community Cloud:Multiple organizations with shared interests or regulatory requirements collaboratively manage billing platforms on a common infrastructure.
Hybrid Cloud deployments are currently gaining share most rapidly due to evolving regulatory landscapes and security concerns.
Billing Type:
The application of different billing types directly supports specific monetization strategies for telecom services. Usage-based and subscription models enable dynamic revenue generation from new digital offerings, while flat-rate and tiered structures address traditional service consumption. Each type caters to distinct customer behaviors and service delivery paradigms.
- Usage-Based:This type charges customers based on actual consumption of services, such as data volume, call duration, or API calls. It is essential for monetizing 5G network slicing and IoT micro-transactions in markets like Japan and the United States.
- Subscription:Customers pay a recurring fee for access to services, offering predictable revenue streams for operators. This model is expanding most quickly for content streaming and bundled service offerings across Europe and Latin America.
- Flat-Rate:A fixed charge for unlimited access to a service, simplifying billing for basic connectivity.
- Tiered:Pricing structures that offer different service levels or usage allowances at varying price points, providing customer choice.
Usage-Based billing is expanding most quickly, driven by the proliferation of dynamic digital services.
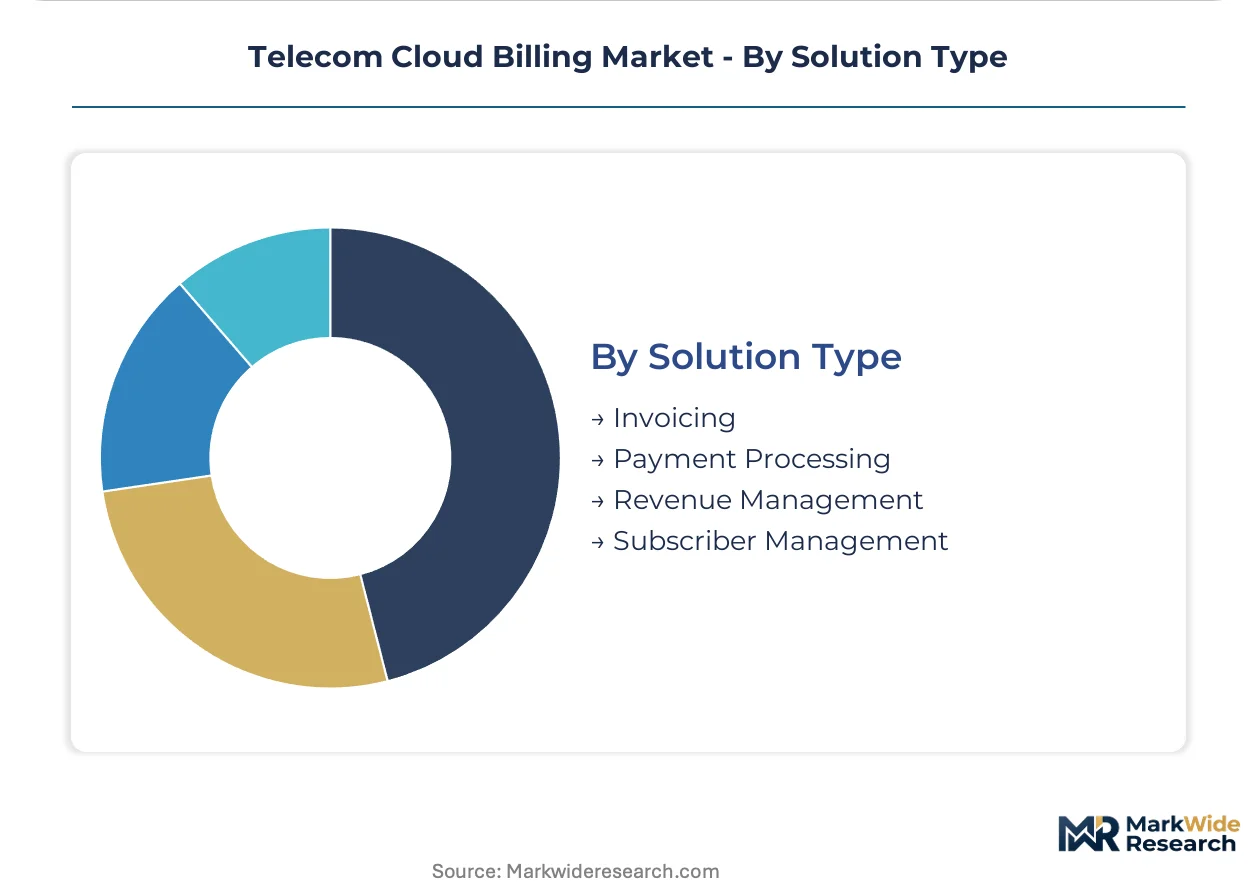
Solution Type:
The transaction scale and functional specialization characterize each solution type in the telecom cloud billing market. Revenue management platforms orchestrate the entire monetization lifecycle, while payment processing handles high-volume financial transactions. Subscriber management focuses on customer lifecycle events, and invoicing formalizes charges.
- Revenue Management:These comprehensive platforms manage the entire billing lifecycle, from rating and charging to invoicing and collections, for complex multi-partner ecosystems. Operators in markets like the United Kingdom and Australia leverage these systems to optimize monetization across diverse service portfolios.
- Payment Processing:This solution handles the secure and efficient collection of payments from subscribers, supporting various payment methods and currencies. Its importance grows with the rise of mobile payment integrations in countries like India and Indonesia.
- Invoicing:Generates detailed bills for services consumed, ensuring transparency and regulatory compliance.
- Subscriber Management:Manages customer accounts, service provisioning, and lifecycle events within the billing ecosystem.
Revenue Management solutions are climbing the fastest, reflecting the need for end-to-end monetization capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side capabilities for telecom cloud billing platforms are largely concentrated in regions with advanced digital infrastructure and significant investment in 5G networks. These areas also demonstrate robust regulatory frameworks influencing data handling and service monetization. Operators in these markets require sophisticated solutions for complex revenue streams.
United States
Demand for 5G network slicing and B2B2X models drives significant billing platform adoption among large enterprises. The US FCC mandates specific data retention and privacy standards for telecom operators. Major technology hubs like Silicon Valley and Seattle foster innovation in cloud-native billing solutions.
Germany
Enterprise demand for industrial IoT and private 5G networks fuels advanced billing system requirements. Strict GDPR regulations significantly influence hybrid cloud deployment choices for sensitive customer data. Munich and Berlin are emerging centers for telecom software development and integration.
India
Rapid proliferation of digital services and mobile finance applications creates immense demand for agile billing solutions. The country's upcoming data protection bill will impose stringent data sovereignty and privacy obligations. Bangalore and Hyderabad serve as key hubs for cloud billing software engineering.
Brazil
High-growth mobile markets and a surge in content streaming services necessitate scalable billing solutions. LGPD regulations dictate strict data privacy and cross-border data transfer rules for telecom providers. São Paulo and Rio de Janeiro are focal points for digital service expansion and monetization.
Japan
Monetization of 5G use cases, including ultra-low latency applications and IoT, drives usage-based billing innovation. METI encourages digital transformation while ensuring robust cybersecurity and data governance standards. Tokyo's dense urban environment fosters advanced mobile service deployment and complex billing needs.
Telecom Cloud Billing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the telecom cloud billing market. The market exhibits a tiered structure, with established vendors offering comprehensive suites alongside agile cloud-native specialists. Strategic archetypes include incumbent BSS providers, enterprise software giants, and focused cloud billing pure-plays. Dominant competitive moves involve strategic partnerships for ecosystem expansion and continuous portfolio diversification into new monetization areas.
Incumbent BSS providers like Amdocs exemplify deep telecom domain expertise, offering end-to-end managed billing services to Tier-1 carriers. Oracle, a global enterprise software giant, differentiates through the integration of its billing solutions with its comprehensive suite of enterprise resource planning and customer experience cloud applications. Ericsson, a Swedish multinational networking and telecommunications company, occupies a position specializing in billing systems tightly coupled with its 5G network infrastructure and BSS offerings.
| Leading Market Players |
|---|
| Amdocs |
| Oracle |
| Ericsson |
| Nokia |
| Huawei Technologies |
| SAP |
| Netcracker Technology |
| CSG Systems International |
| CGI Inc. |
| Others |
Cost & Logistics Intelligence
Cloud billing platform integration timelines, often extending over months due to complex system dependencies, directly influence vendor pricing power and the structural shape of the supply chain. Customized solutions command higher value, reflecting the intricate labor and specialized expertise required for deployment and ongoing management.
Pricing Analysis
GDPR dictates the pricing tier structure for data-sensitive cloud billing solutions, especially for European operators. Hybrid usage-based and subscription models dominate, enabling flexible monetization of dynamic services. Price differentiation stems from customization level and stringent data sovereignty compliance requirements. Pricing softness reflects intense competition among platform providers vying for large enterprise contracts. Mobile Virtual Network Operators (MVNOs) represent the most price-sensitive segment, while large enterprise clients prioritize feature sets and service level agreements.
Supply Chain Analysis
India and the United States anchor cloud-native software development and specialized billing module creation. The supply chain draws from skilled cloud-native developers and hyperscale public cloud infrastructure providers for core components. A significant supply chain risk is the cloud-native skills gap, which can constrain development and deployment velocity. Distribution runs through direct sales channels, strategic system integrators, and specialized managed service providers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecom cloud billing represents a platform-economics inflection, driven by the imperative to monetize complex 5G network slicing and B2B2X ecosystems.
For Market Incumbents: Shield core revenue streams by accelerating the transition of legacy billing systems to containerized, microservices-based architectures. Invest in continuous R&D for AI-driven billing optimization to counter agile cloud-native specialists. Leverage deep telecom domain expertise to expand end-to-end managed billing services, strengthening client lock-in against emerging threats.
For New Entrants and Emerging Players: MVNO-specific billing solutions present a service-layer gap, as incumbents often overlook this segment with overly complex offerings. Target emerging digital economies in Southeast Asia and Africa where new operators require lightweight, flexible, and cost-effective solutions. A go-to-market angle focusing on Billing-as-a-Service (BaaS) models can capture significant market share.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational infrastructure enablement play because cloud billing is critical for monetizing the next generation of digital services. Target specialized AI-driven billing optimization firms or cloud-native BSS pure-plays with strong intellectual property. The increasing M&A activity in cloud-native BSS solution providers serves as a key signal to watch for market consolidation and value creation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Modernization | Re-architecting legacy systems to microservices boosts agility and reduces operational costs for telecom operators. |
| AI/ML Integration | Embedding predictive analytics enhances fraud detection and offers personalized service recommendations to customers. |
| Ecosystem Partnerships | Collaborations with 5G and IoT solution providers enable comprehensive monetization of new digital services. |
| Geographic Expansion | Targeting high-growth mobile markets like India and Brazil captures demand from rapidly digitizing economies. |
| Managed Services Offering | Providing end-to-end billing operations allows operators to focus on core network services and customer experience. |
Research Approach
Operator-level perspectives from telecom CTOs, billing operations managers, network architects, and regulatory compliance officers anchored the qualitative base of this study. Primary interviews were triangulated with extensive secondary research, including SEC filings of major telecom vendors, operator annual reports, and publications from national regulatory bodies like the US FCC, India's TRAI, and Brazil's LGPD. This approach ensured a robust understanding of market dynamics from both supply and demand sides.
Sensitivity analysis informed the quantitative modeling, assessing potential impacts of various market scenarios across the analysis window. The analytical framework segmented the market by customer type, deployment model, billing type, and solution type, alongside granular regional adoption patterns and 5G/IoT use case maturity. Compound annual growth rates were derived from historical data trends and projected future adoption rates, integrating key forecast inputs such as 5G subscriber penetration and IoT device connectivity rates.
Forecasts assume regulatory continuity in EU, Brazil, and US regimes; material policy shifts would require re-modeling. The analysis reflects established market assumptions, but unforeseen technological disruptions or geopolitical trade tensions represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China POS Terminals Market
Payments
Mobile Payment Market
Payments
Global Prepaid Cards Market
Payments
POS Terminals Market
Payments
Denmark POS Terminals Market
Payments
United States Payment Gateways Market
Payments
Latin America Mobile Payment Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Italy Payments Market
Payments
Convergent Billing Market
Payments
Bus Card Reader Market
Payments
China Payments Market
Payments
Mobile Payment Security Software Market
Payments
France POS Terminal Market
Payments
Vietnam E-Wallet Market
Payments
Italy Gift Cards Market