
 APAC Mobile Payments Market | 2026-2036
APAC Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Mobile Payments Market Outlook
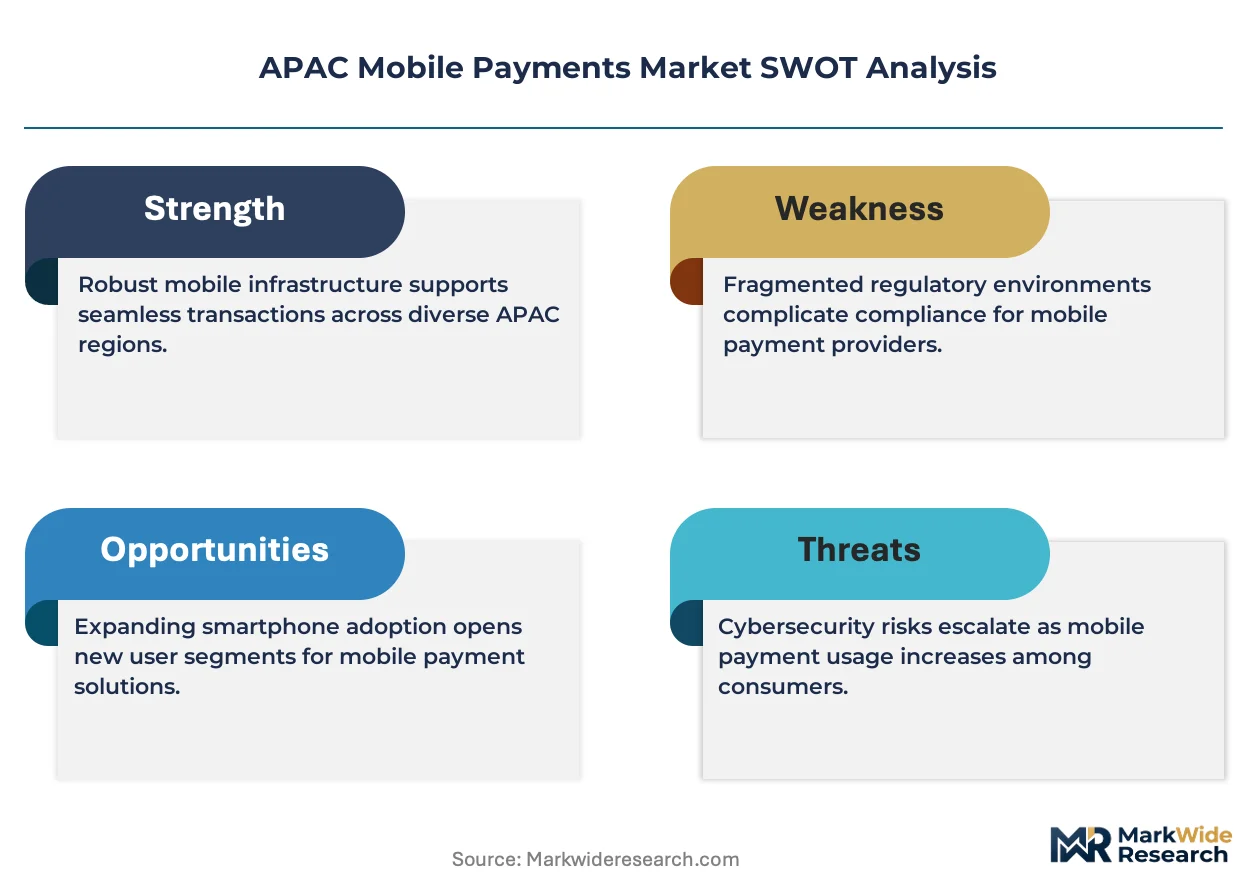
The gap between premium biometric-authenticated wallets and basic QR-code platforms is expanding across Southeast Asia. Ant Group leverages its super-app ecosystem to anchor merchant loyalty in tier-two Chinese cities. Tencent Holdings sustains transaction density through embedded mini-program commerce. Samsung Electronics competes on hardware-integrated tokenization for enterprise fleet deployments.
APAC mobile payments encompass digital fund transfers initiated through portable computing devices using cellular or wireless networks, typically employing tokenized credentials, 128-bit encryption protocols, and real-time authorization gateways to displace physical currency in commercial exchange. E-wallet penetration leads transaction volume across ASEAN informal economies, while NFC-enabled contactless terminals capture higher per-transaction value in Australian and South Korean transit corridors. QR-code infrastructure dominates micro-transaction frequency among retail customers, though cloud-based solutions are displacing on-premise acquiring systems for mid-market merchants seeking API interoperability.
China's SAMR enforces data-localization standards for payment processors, while India's RBI mandates two-factor authentication thresholds for wallet-to-bank transfers exceeding prescribed limits. Australia's ASIC coordinates with the ACCC on buy-now-pay-later disclosure standards affecting embedded credit products. Stakeholders must weigh compliance fragmentation against the cost of jurisdiction-specific infrastructure builds.
Market Dynamics
India's RBI two-factor authentication mandates and China's SAMR data-localization requirements are forcing platform operators to rebuild core architecture around jurisdiction-specific infrastructure rather than regional hubs.
Growth Catalysts
- Biometric authentication protocols:Fingerprint and facial recognition standards are reducing transaction friction in Indonesian street markets where smartphone penetration outpaces banking infrastructure.
- Indonesia's unbanked corridor expansion:QR-code interoperability between competing wallets is creating network effects among micro-merchants previously excluded from formal financial systems.
- RBI's UPI infrastructure:India's real-time payment rails are enabling wallet-to-bank transfers at zero merchant discount rates, accelerating merchant onboarding velocity.
Market Restraints
- Data-localization capex burden:China's MIIT mandates require separate server farms and compliance teams for each provincial jurisdiction, fragmenting platform economics.
- Hardware tokenization costs:Samsung Electronics and Apple dominate secure element manufacturing, concentrating supply leverage among two vendors for NFC-enabled enterprise deployments.
- Interoperability fragmentation:Vietnam's urban transit corridors operate on proprietary closed-loop systems that resist integration with open-wallet protocols.
Strategic Opportunities
- Vietnam's urban transit corridors:Contactless transit payments remain underpenetrated outside Ho Chi Minh City and Hanoi, creating first-mover advantages for integrated mobility-wallet platforms.
- API-first cloud acquiring:Mid-market merchants across Thailand and Malaysia are abandoning on-premise POS terminals for software-based solutions enabling real-time reconciliation.
- Australia's ASIC-AACC coordination:Embedded credit disclosure standards are creating compliant product templates that can be replicated across ASEAN buy-now-pay-later offerings.
Industry Challenges
- Legacy core banking integration:Indonesian rural banks operate on COBOL-based systems that resist API connectivity, forcing wallet operators to maintain expensive middleware layers.
- Certification timeline compression:India's CERT-In security audits now require 90-day re-certification cycles for payment apps, consuming engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Mobile Payments Market |
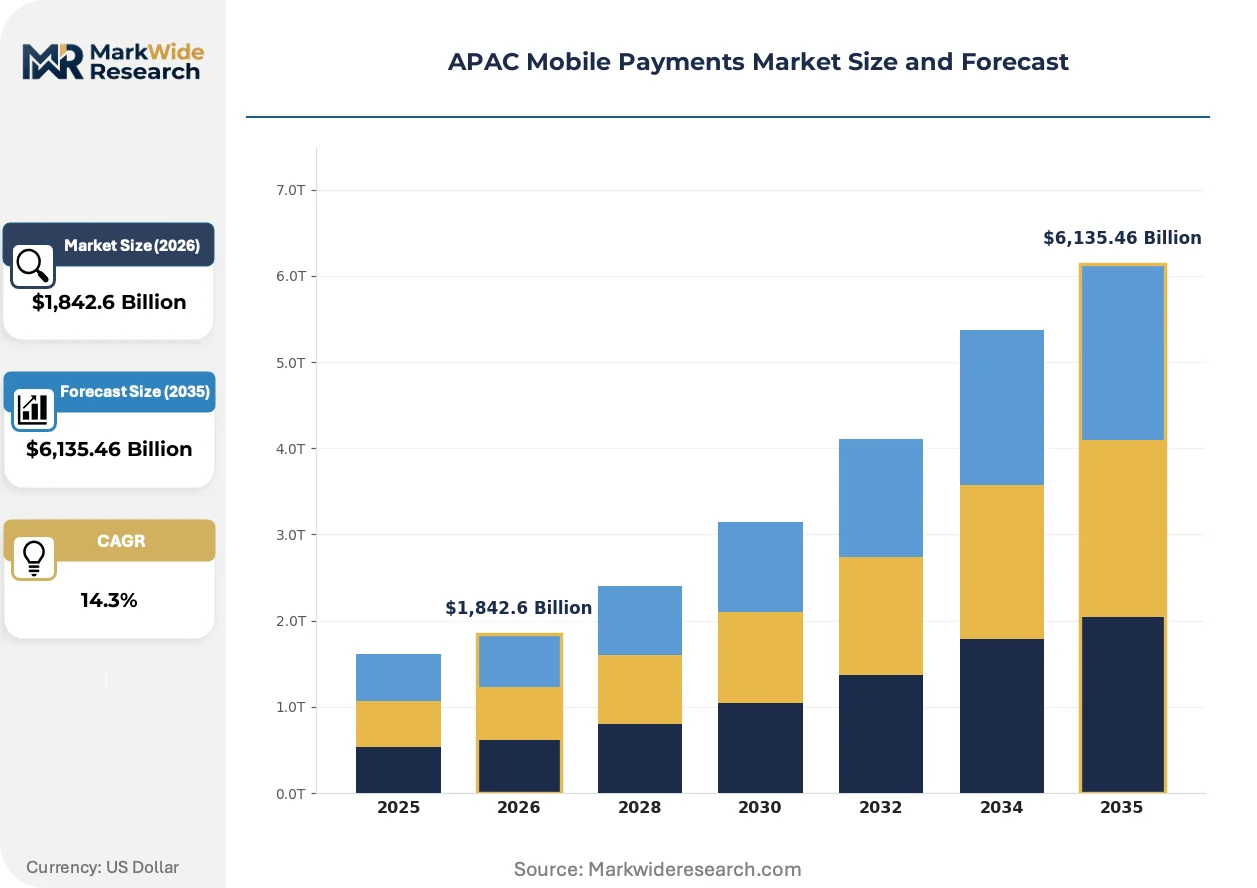
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $6,135.46 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions End User: Retail Customers, Businesses, Enterprises, Merchants Technology: NFC, QR Code, Mobile App, Cloud-Based Solutions |
| Companies Covered | Ant Group, Tencent Holdings, Google LLC, Apple Inc, Visa Inc, Mastercard Incorporated, PayPal Holdings Inc, Samsung Electronics Co., Ltd., Amazon.com Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Mobile Payments Market Strategic Shifts
Tokenized credential architectures and real-time authorization gateways are compressing settlement windows while expanding transaction velocity across informal economies previously dependent on cash.
Biometric-authenticated wallets are overtaking basic QR-code platforms as the default interface for high-frequency transactions. Tier-two Chinese cities are adopting facial recognition terminals at vegetable markets and convenience stores. Ant Group's merchant loyalty programs are anchoring adoption by linking payment history to credit-scoring algorithms.
China's SAMR data-localization standards now require payment processors to store transaction records within mainland server infrastructure. Foreign platforms must establish joint ventures with domestic technology partners to achieve compliance. Australian and South Korean operators are observing these requirements as potential templates for their own regulatory frameworks.
Merchant procurement of payment infrastructure is fragmenting across channel types. Street vendors in Jakarta and Manila now select wallets based on same-day settlement speed rather than brand recognition. E-wallet providers are responding with instant disbursement features that compress working capital cycles for micro-enterprises operating on thin margins.
APAC Mobile Payments Market Segmentation
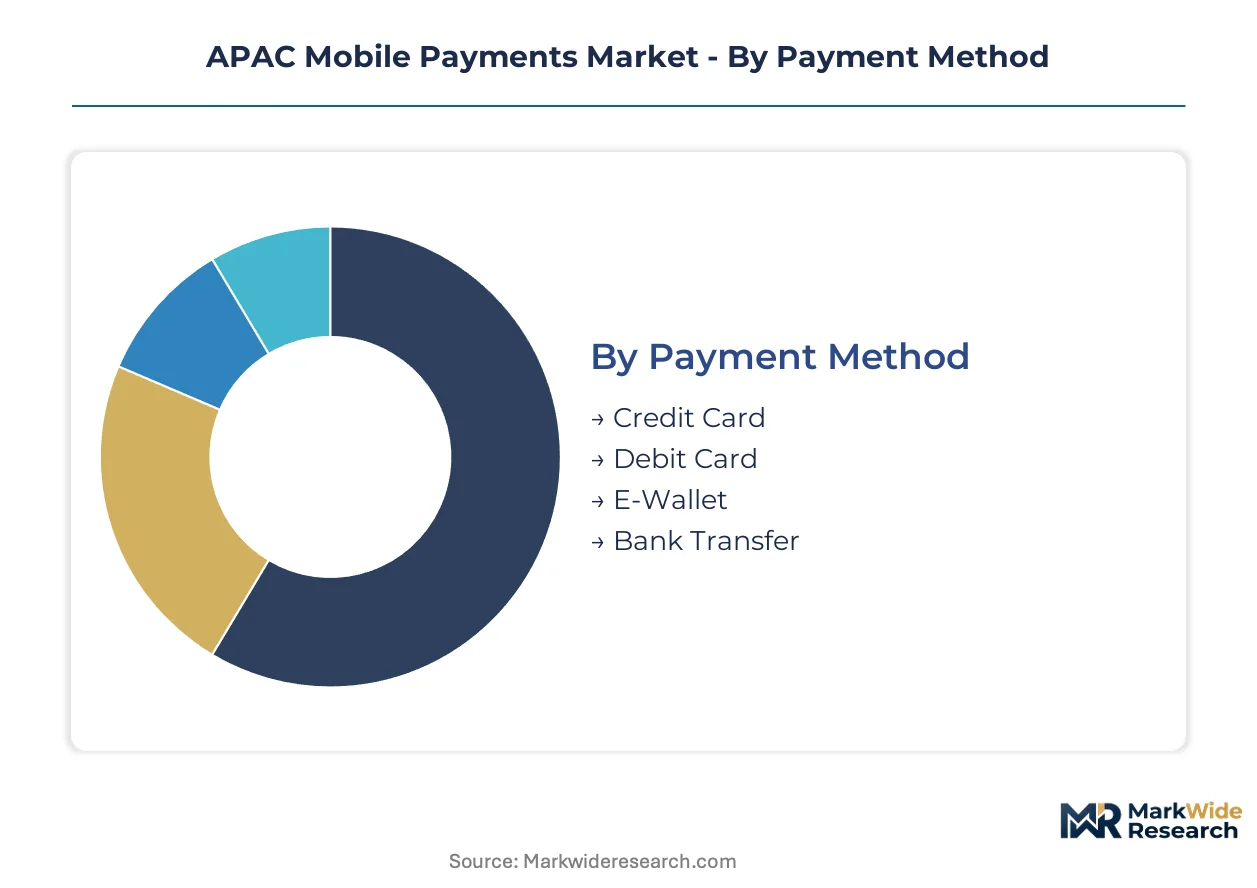
Payment modality fragmentation across APAC demands granular segmentation to capture divergent infrastructure requirements. Each category reveals distinct cost structures, regulatory exposure, and merchant adoption patterns that reshape platform economics.
Payment Method:
Technology sophistication and settlement velocity separate these instruments across informal and formal commerce corridors.
- E-Wallet:Cloud-hosted credential vaults enable real-time balance transfers without card network rails. Indonesian street vendors and Vietnamese motorbike taxi drivers favor these for same-day settlement cycles that compress working capital gaps.
- Credit Card:Tokenized 16-digit credentials routed through bank-sponsored schemes carry higher interchange fees but offer chargeback protection. Australian and South Korean transit authorities prefer these for high-velocity contactless corridors where transaction ceilings exceed wallet balance limits.
- Debit Card:Direct-linked demand deposit instruments bypass credit underwriting but require robust bank infrastructure. Indian UPI interoperability has compressed debit card growth in tier-three cities where real-time bank transfers displace card-present transactions.
- Bank Transfer:Account-to-account settlement via ACH or real-time gross settlement rails eliminates merchant discount rates entirely. China's SAMR mandates favor domestic bank rails for cross-border remittance corridors into Southeast Asian manufacturing hubs.
E-Wallet leads on scale; bank transfer leads on momentum.
Transaction Size:
Cost tier and authorization protocol intensity vary dramatically across value bands.
- Micro Transactions:Sub-dollar purchases at Jakarta food stalls and Manila sari-sari stores execute via static QR codes without real-time network verification. Margins collapse to fractional basis points, forcing volume-dependent revenue models.
- Small Transactions:Urban convenience purchases in Bangkok and Kuala Lumpur trigger biometric authentication thresholds under RBI and Bank of Thailand guidelines. Platform operators absorb higher fraud liability in exchange for merchant acquisition velocity.
- Medium Transactions:B2B procurement payments across ASEAN manufacturing supply chains require multi-factor approval workflows and API reconciliation hooks. Cloud acquiring platforms displace on-premise terminals in this band.
- Large Transactions:Cross-border trade settlements and enterprise fleet fuel purchases demand SWIFT-integrated escrow and FX hedging capabilities. Singapore and Hong Kong domiciled platforms dominate this thin-margin, high-compliance segment.
Micro transactions dominate absolute volume; medium transactions expand most quickly.
End User:
Customer type dictates interface complexity and support cost allocation.
- Merchants:Micro-enterprises in Indonesia's unbanked corridors select wallets based on settlement speed rather than brand, compressing platform differentiation to working capital terms.
- Retail Customers:Urban consumers across Vietnam's transit corridors demand seamless mobility-wallet integration, favoring platforms with embedded loyalty and credit-scoring algorithms.
- Enterprises:Fleet operators and regional retailers require tokenized credential management across multi-jurisdictional deployments, driving demand for Samsung and Apple hardware-integrated solutions.
- Businesses:Mid-market Thai and Malaysian merchants abandon legacy POS terminals for API-first cloud acquiring that enables real-time reconciliation with ERP systems.
Merchants anchor network effects; enterprises command premium pricing.
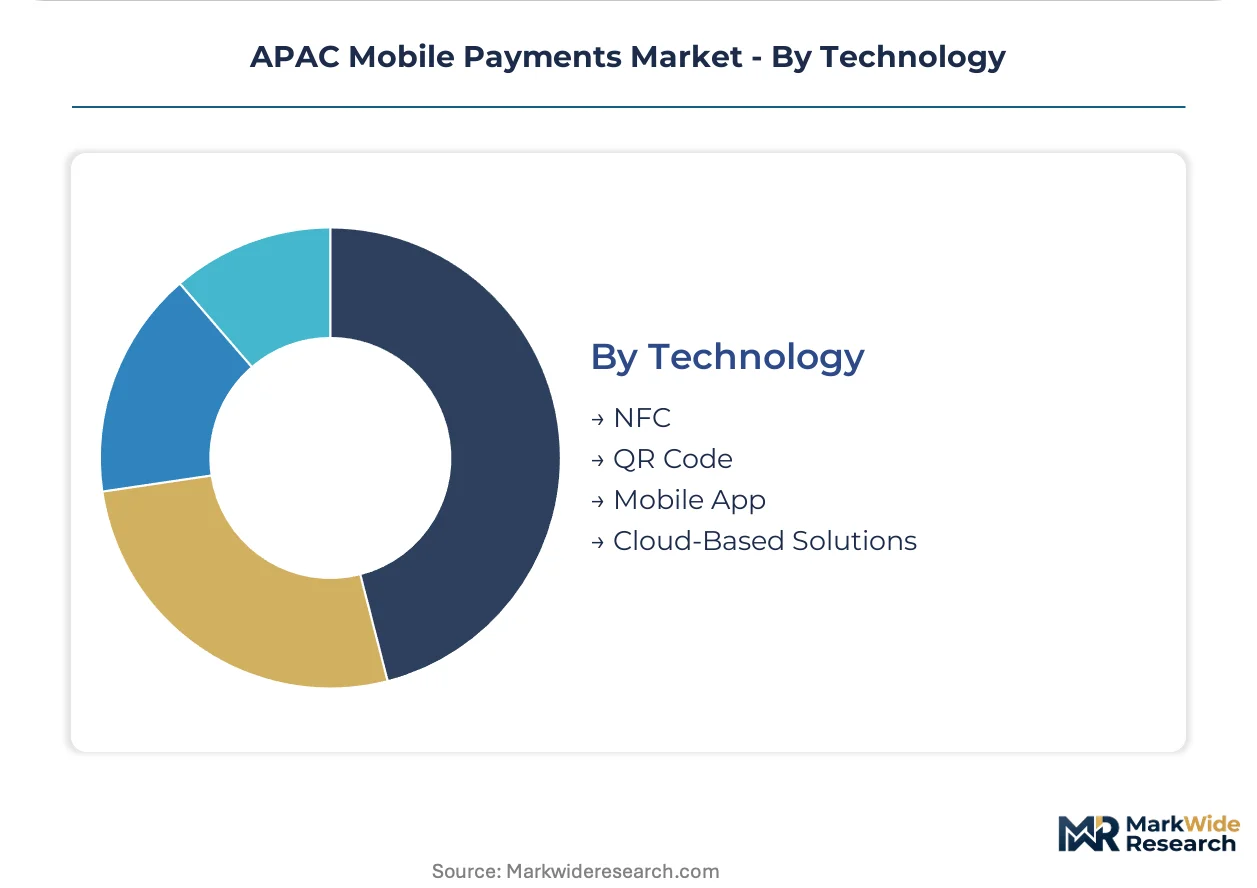
Technology:
Hardware dependency and interoperability standards fragment deployment economics.
- QR Code:Static and dynamic matrix codes dominate micro-transaction frequency across ASEAN informal economies due to zero terminal capex requirements for merchants.
- NFC:Secure element-based contactless protocols capture higher per-transaction value in Australian and South Korean transit corridors where transaction velocity demands sub-300ms authorization.
- Mobile App:Super-app embedded mini-programs sustain transaction density for Ant Group and Tencent Holdings in tier-two Chinese cities where facial recognition terminals displace physical interfaces.
- Cloud-Based Solutions:Software-defined acquiring platforms enable mid-market merchants across Thailand and Malaysia to abandon on-premise infrastructure for API interoperability and real-time settlement.
QR code leads on penetration breadth; cloud-based solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Bangalore, Shenzhen, and Singapore anchor platform development across the region. These concentrations support divergent regulatory frameworks and infrastructure maturity levels. National payment architectures now determine competitive positioning more than regional standardization efforts.
China
Facial recognition terminals and super-app ecosystems drive merchant adoption in tier-two cities like Chengdu and Xi'an. SAMR data-localization mandates force foreign platforms into joint venture structures with domestic technology partners. The Yangtze River Delta corridor concentrates hardware manufacturing for secure element production.
India
UPI real-time rails enable zero-merchant-discount-rate transfers that accelerate onboarding among micro-enterprises. RBI two-factor authentication thresholds and CERT-In 90-day re-certification cycles consume substantial engineering bandwidth. Mumbai and Bangalore host the primary engineering centers building wallet-to-bank interoperability layers.
Indonesia
QR-code interoperability between competing wallets creates network effects among street vendors in Jakarta and Surabaya. Same-day settlement speed has displaced brand recognition as the primary merchant selection criterion. The unbanked corridors of Central and East Java represent the highest-frequency micro-transaction growth zones.
Vietnam
Urban transit corridors in Ho Chi Minh City and Hanoi remain underpenetrated for contactless mobility-wallet integration. Proprietary closed-loop transit systems resist open-wallet protocol integration, fragmenting user experience. The State Bank of Vietnam's licensing framework for e-money issuers is tightening capital reserve requirements.
Australia
ASIC-ACCC coordination on buy-now-pay-later disclosure standards creates compliant product templates replicable across ASEAN markets. NFC-enabled contactless terminals capture higher per-transaction value in Sydney and Melbourne transit corridors. Cloud-based acquiring solutions displace legacy on-premise POS infrastructure among mid-market merchants.
APAC Mobile Payments Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light platform designers for merchant relationships and transaction volume. The market structure concentrates around three tiers: super-app ecosystems with embedded financial services, hardware-integrated tokenization specialists, and API-first cloud acquiring platforms. Strategic archetypes include ecosystem bundlers competing on user lock-in, compliance-first operators building jurisdiction-specific infrastructure, and interoperability enablers bridging closed-loop systems. Dominant competitive moves involve vertical integration into secure element manufacturing and geographic expansion through joint venture structures.
Within the ecosystem bundler tier, Ant Group and Tencent Holdings exemplify super-app strategies that anchor merchant loyalty through embedded mini-program commerce and credit-scoring algorithms. Samsung Electronics occupies a position among hardware-integrated specialists, leveraging secure element manufacturing relationships for enterprise fleet deployments. These three companies represent divergent approaches to the biometric authentication and data-localization requirements reshaping platform architecture across the region.
| Leading Market Players |
|---|
| Ant Group |
| Tencent Holdings |
| Google LLC |
| Apple Inc |
| Visa Inc |
| Mastercard Incorporated |
| PayPal Holdings Inc |
| Samsung Electronics Co., Ltd. |
| Amazon.com Inc |
| Others |
Value Chain & Pricing Dynamics
Captive server infrastructure across China's provincial jurisdictions anchors both compliance positioning and cost recovery mechanisms for payment processors confronting SAMR data-localization mandates. This integration pattern concentrates capex burdens among operators while fragmenting platform economics across jurisdiction-specific builds.
Pricing Analysis
The bundled-versus-unbundled service split separates platform economics across merchant tiers. Super-app ecosystems bundle payment rails with credit-scoring and loyalty algorithms, commanding premium merchant discount rates in tier-two Chinese cities. Unbundled QR-code platforms compete on transaction velocity alone, with settlement speed displacing brand as the primary selection criterion among Indonesian street vendors. Pricing pressure stems from zero-merchant-discount-rate UPI transfers in India compressing margins for wallet-to-bank interoperability providers. Micro-merchants exhibit highest price sensitivity; enterprise fleet operators demonstrate lowest sensitivity due to hardware-integrated security requirements.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul, and Singapore anchor hardware procurement patterns for secure element manufacturing. Taiwan and South Korea concentrate semiconductor fabrication for NFC-enabled contactless terminals. China dominates server assembly and cloud infrastructure components. Rare earth processing for magnetic components in secure elements hinges on Malaysian and Vietnamese refining capacity. Single-source vulnerability concentrates in Samsung Electronics and Apple secure element supply. Distribution runs through direct enterprise procurement for fleet deployments and aggregator networks for micro-merchant onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by merchant procurement shifting toward biometric-authenticated platforms with embedded credit-scoring capabilities over basic QR-code alternatives.
For Market Incumbents: Acquire cloud-acquiring API platforms to consolidate mid-market merchant relationships in Thailand and Malaysia. Defend position by deepening hardware-integrated tokenization partnerships with Samsung Electronics against software-only entrants. RBI two-factor authentication thresholds and CERT-In re-certification cycles consume engineering bandwidth that smaller competitors cannot match. For New Entrants and Emerging Players: Launch via API-first cloud acquiring targeting Thai and Malaysian mid-market merchants abandoning on-premise POS terminals. Vietnam's urban transit corridors outside Ho Chi Minh City and Hanoi represent the most penetrable white-space for integrated mobility-wallet platforms. Partner with domestic technology partners in China to achieve SAMR compliance through joint venture structures. For Investors and Strategic Acquirers: Roll-up economics work for API-first cloud acquiring platforms because mid-market merchant consolidation across ASEAN creates scalable infrastructure leverage. Five-to-ten year viability favors operators with jurisdiction-specific compliance architecture over regional hub models. Watch for CERT-In audit timeline compression as an inflection signal for engineering bandwidth scarcity among smaller wallet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Deployment | Facial recognition terminals in tier-two Chinese cities anchor merchant loyalty through friction reduction. |
| API-First Cloud Acquiring Expansion | Software-defined platforms displace on-premise POS terminals among Thai and Malaysian mid-market merchants. |
| Joint Venture Compliance Structuring | Foreign platforms partner with domestic technology partners to satisfy SAMR data-localization mandates. |
| Secure Element Manufacturing Partnership | Hardware-integrated tokenization partnerships with Samsung Electronics defend enterprise fleet deployments. |
| Transit Corridor Integration | Mobility-wallet platforms capture first-mover advantages in Vietnam's underpenetrated urban transit systems. |
Study Parameters
Multiple input streams — primary interviews with payment platform executives, regulatory affairs specialists, and merchant acquisition leads; secondary validation through RBI circulars, SAMR data-localization guidelines, and UPI transaction disclosures; plus customs records for secure element imports — were reconciled through bottom-up and top-down triangulation.
Historical transaction volume trajectories were cross-referenced against panel input from platform engineering directors and merchant onboarding specialists. The analytical framework modeled payment method, transaction size, end user, and technology segmentation dimensions across the analysis window. CAGRs derived from regression against smartphone penetration curves, banking infrastructure maturity indices, and regulatory implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt data-localization mandate expansion or biometric authentication standard fragmentation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mexico POS Terminals Market
Payments
Contactless Payment Market
Payments
UK Virtual Cards Market
Payments
Global Real-Time Payments Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Argentina Mobile Wallet Market
Payments
Freight Audit and Payment Service Market
Payments
Germany Payments Market
Payments
Buy Now Pay Later Market
Payments
Latin America Subscription and Billing Management Market
Payments
Digital Payment in Healthcare Market
Payments
Remittance Market
Payments
Ireland POS Terminals Market
Payments
India Forex Cards Market
Payments
US Gift Card and Incentive Card Market
Payments
Italy Payments Market