
 In Vitro Diagnostics (IVD) Quality Control Market | 2026-2036
In Vitro Diagnostics (IVD) Quality Control Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Diagnostics (IVD) Quality Control Market Intelligence
The integration of cloud-based quality control software with laboratory information systems is reshaping how diagnostic data integrity is managed and monitored across facilities. Bio-Rad Laboratories Inc. leverages its extensive portfolio of independent control materials to support this digital transition for diverse instrument platforms. Siemens Healthineers AG specializes in integrating its QC solutions directly with its own diagnostic instrumentation, creating a closed-loop ecosystem for its customers.
IVD quality control comprises materials, software, and protocols used to verify the accuracy and precision of diagnostic assays. These controls, containing known analyte concentrations, are processed alongside patient samples to ensure test systems perform within established tolerance limits, safeguarding the reliability of clinical results. Control Materials form the largest product segment, essential for routine checks in all testing environments. Within applications, molecular diagnostics represents the fastest-growing area, driven by the complexity of genomic assays.
Regulatory frameworks from the US FDA and under Europe's In Vitro Diagnostic Regulation (IVDR) mandate stringent quality control procedures for market access. Compliance with international standards such as ISO 15189 is becoming a prerequisite for laboratory accreditation, directly influencing procurement of certified QC products. Navigating the choice between third-party independent controls and instrument-specific solutions remains a critical strategic decision for laboratory managers and procurement teams.
Market Dynamics
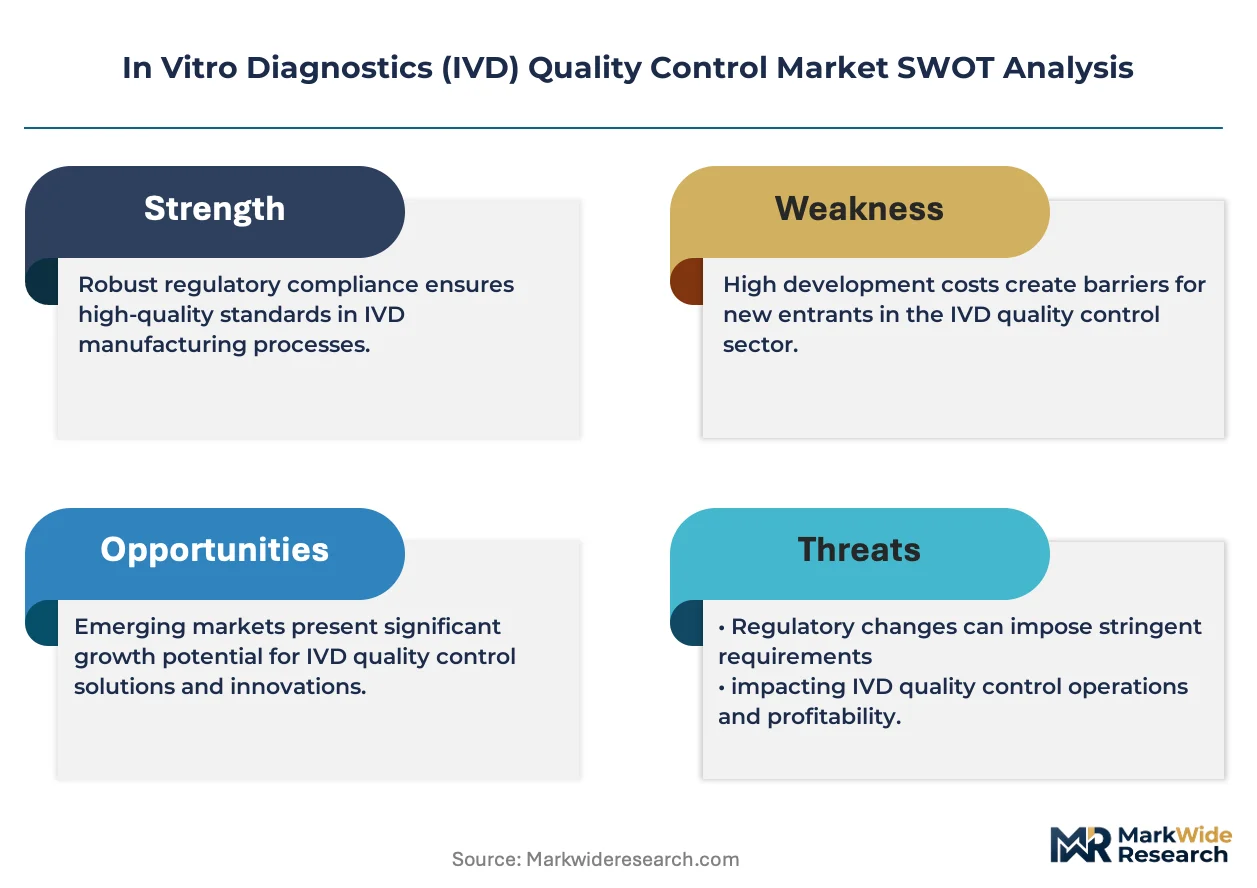
The global push for laboratory accreditation is the central force shaping the IVD quality control market. Mandatory compliance with standards like ISO 15189 elevates quality control from a best practice to a non-negotiable requirement for diagnostic service providers.
Growth Catalysts
- Regulatory Mandates:Europe's In Vitro Diagnostic Regulation (IVDR) intensifies the requirements for clinical evidence and post-market surveillance, compelling manufacturers and laboratories to adopt more rigorous and well-documented quality control systems to gain and maintain market access.
- Laboratory Modernization:Nations such as India and Brazil are undertaking significant upgrades to their clinical laboratory infrastructure, creating direct demand for certified QC products to support newly acquired, advanced diagnostic platforms and achieve international standards.
- Complex Assay Adoption:The expansion of molecular diagnostics, with its intricate and sensitive genomic assays, necessitates sophisticated, third-party quality controls to ensure the accuracy and reproducibility of results for oncology and infectious disease testing.
Market Restraints
- Cost Pressures:The high acquisition cost of commutable, multi-analyte third-party controls can be a significant barrier for smaller, independent laboratories or those in resource-constrained settings, limiting their ability to implement comprehensive QC programs.
- OEM-Specific Solutions:The availability of instrument-specific controls offered by diagnostic equipment manufacturers creates a substitution threat for independent QC vendors, as some laboratories prefer the closed-loop ecosystem provided by a single supplier.
- Novel Analyte Instability:Developing stable and reliable control materials for emerging and esoteric biomarkers, particularly in proteomics and cell-based assays, presents significant technical challenges related to material sourcing, formulation, and shelf-life.
Strategic Opportunities
- Point-of-Care QC:Expanding quality control solutions for the growing point-of-care testing (POCT) segment presents a major opportunity, especially for automated, connected QC systems that can manage compliance across decentralized testing sites.
- Predictive Analytics Software:Integrating artificial intelligence and machine learning algorithms with cloud-based QC data platforms allows for the development of predictive analytics tools that can identify potential instrument errors or reagent drift before they impact patient results.
- Emerging Market Digitalization:Providing scalable, cloud-based QC software solutions to laboratories in developing economies offers a significant growth pathway, enabling them to participate in international peer-group comparison programs and streamline accreditation efforts.
Industry Challenges
- LIS Integration Complexity:Ensuring seamless interoperability between third-party quality control software and a diverse landscape of legacy Laboratory Information Systems (LIS) remains a persistent operational hurdle, often requiring custom development and extensive validation.
- Data Management Skills Gap:Effective management of large QC datasets, particularly from multiplex assays and inter-laboratory comparison programs, requires specialized data analysis and statistical expertise that is often lacking within clinical laboratory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Diagnostics (IVD) Quality Control Market |
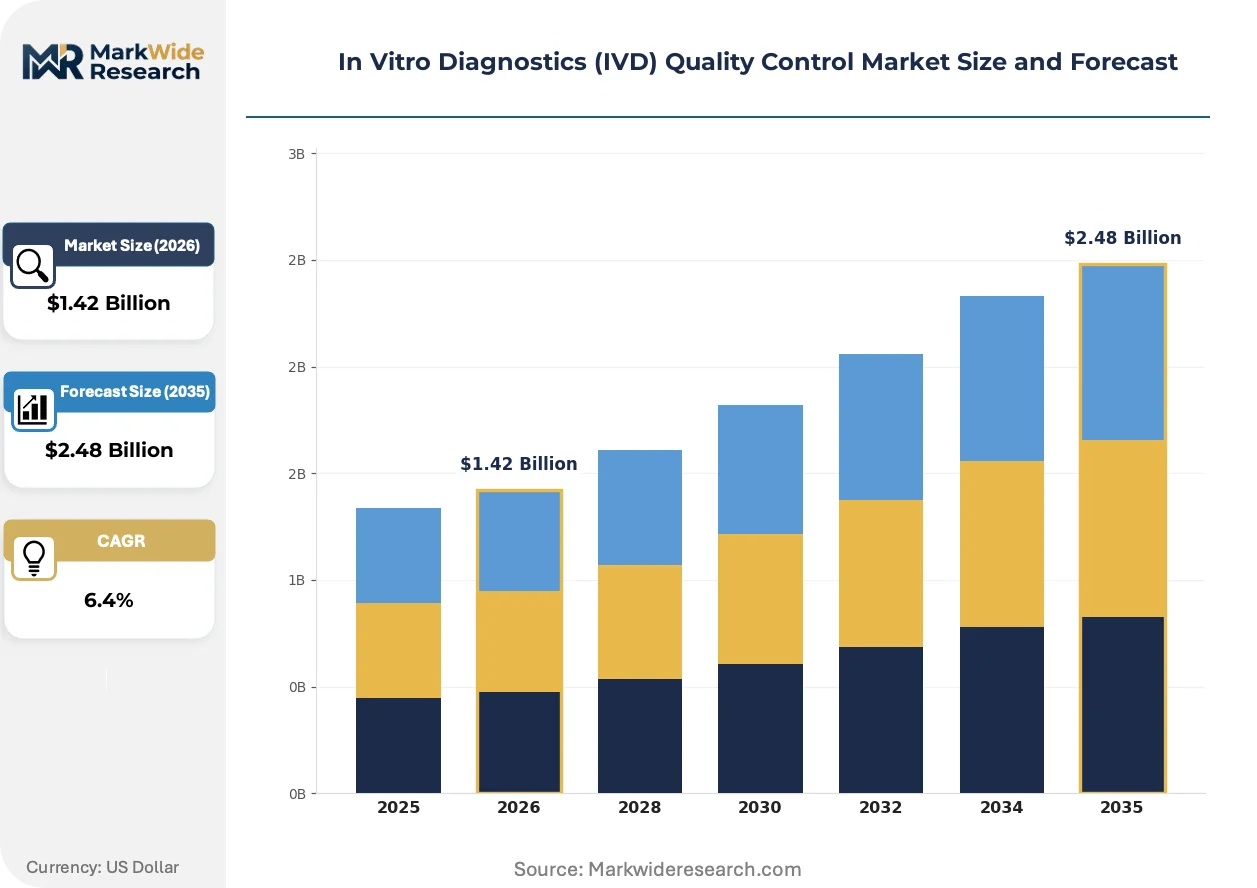
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Materials, Calibrators, Instrument Adjustors, Quality Control Software, Reference Standards Application: Clinical Chemistry, Immunoassay, Microbiology Testing, Molecular Diagnostics, Hematology End User: Diagnostic Laboratories, Research Institutions, Point-of-Care Testing Centers, Blood Banks, Pharmaceutical Companies Deployment: Cloud-Based Platforms, On-Premise Solutions, Hybrid Systems, Mobile Applications |
| Companies Covered | LGC Limited, Randox Laboratories, Bio-Rad Laboratories Inc., Danaher Corporation, Siemens Healthineers AG, Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., Sysmex Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Diagnostics (IVD) Quality Control Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from manual, retrospective quality checks to automated, real-time quality assurance. This shift is driven by the convergence of advanced data management software, improved control material chemistry, and stricter regulatory expectations for data integrity.
Liquid-stable, multi-analyte control materials offer a consolidated solution for routine QC. High-throughput clinical chemistry and immunoassay laboratories are rapidly adopting these products to streamline workflows. This technology is rendering obsolete the inefficient practice of preparing and running numerous individual, lyophilized controls, thereby reducing manual errors and saving technician time.
Europe's In Vitro Diagnostic Regulation (IVDR) establishes a more demanding legal framework for placing devices on the market. Its implementation forces manufacturers to provide more extensive performance data and conduct rigorous post-market surveillance for all products, including calibrators and controls. IVD manufacturers supplying the European market are most affected, facing longer development cycles and higher compliance costs to meet these stringent evidence requirements.
A distinct behavioral shift sees laboratories procuring QC data management services alongside physical control materials. The traditional transactional sale of control vials is being augmented by subscription-based access to peer-group comparison programs and analytical software. This trend is most visible in large, accredited hospital networks in the United States and Western Europe seeking to automate compliance reporting for ISO 15189.
In Vitro Diagnostics (IVD) Quality Control Market Segmentation
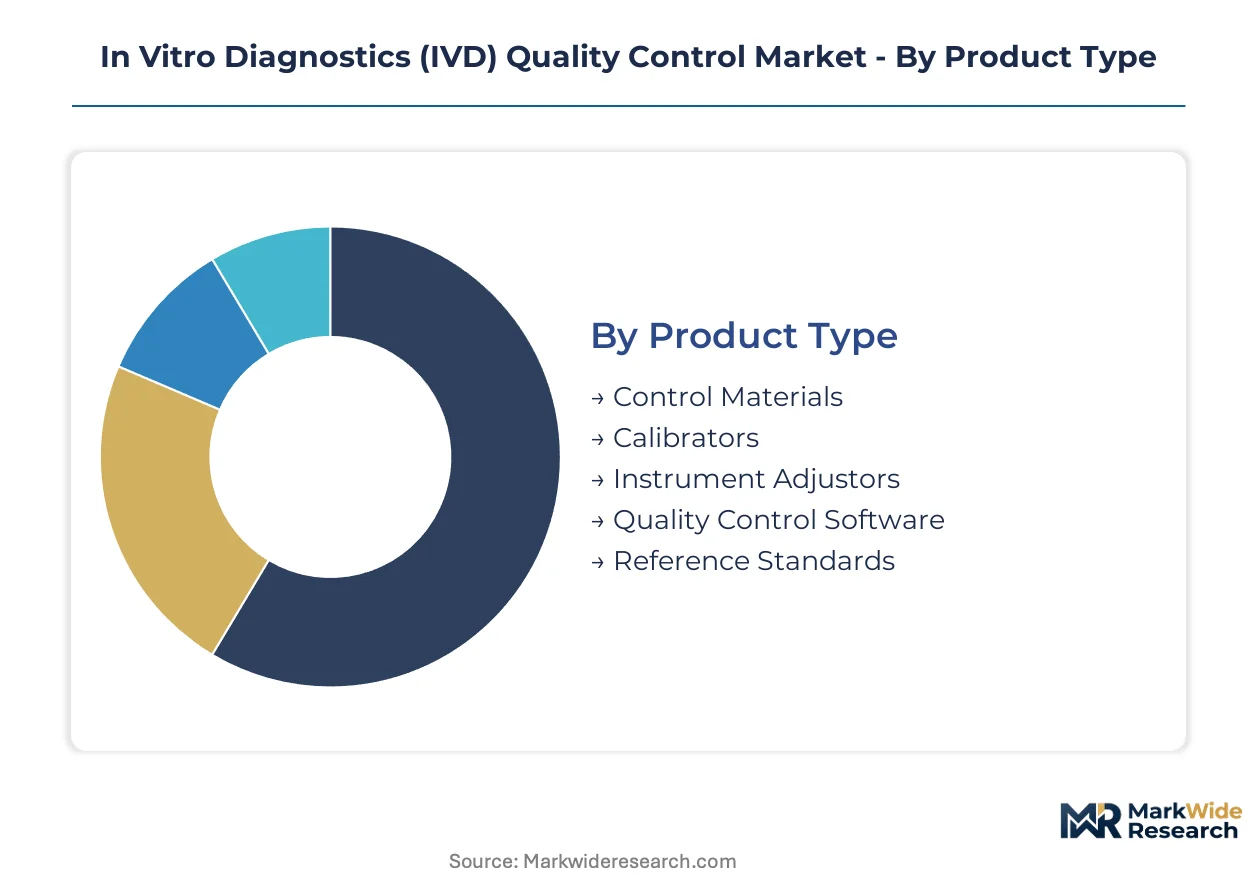
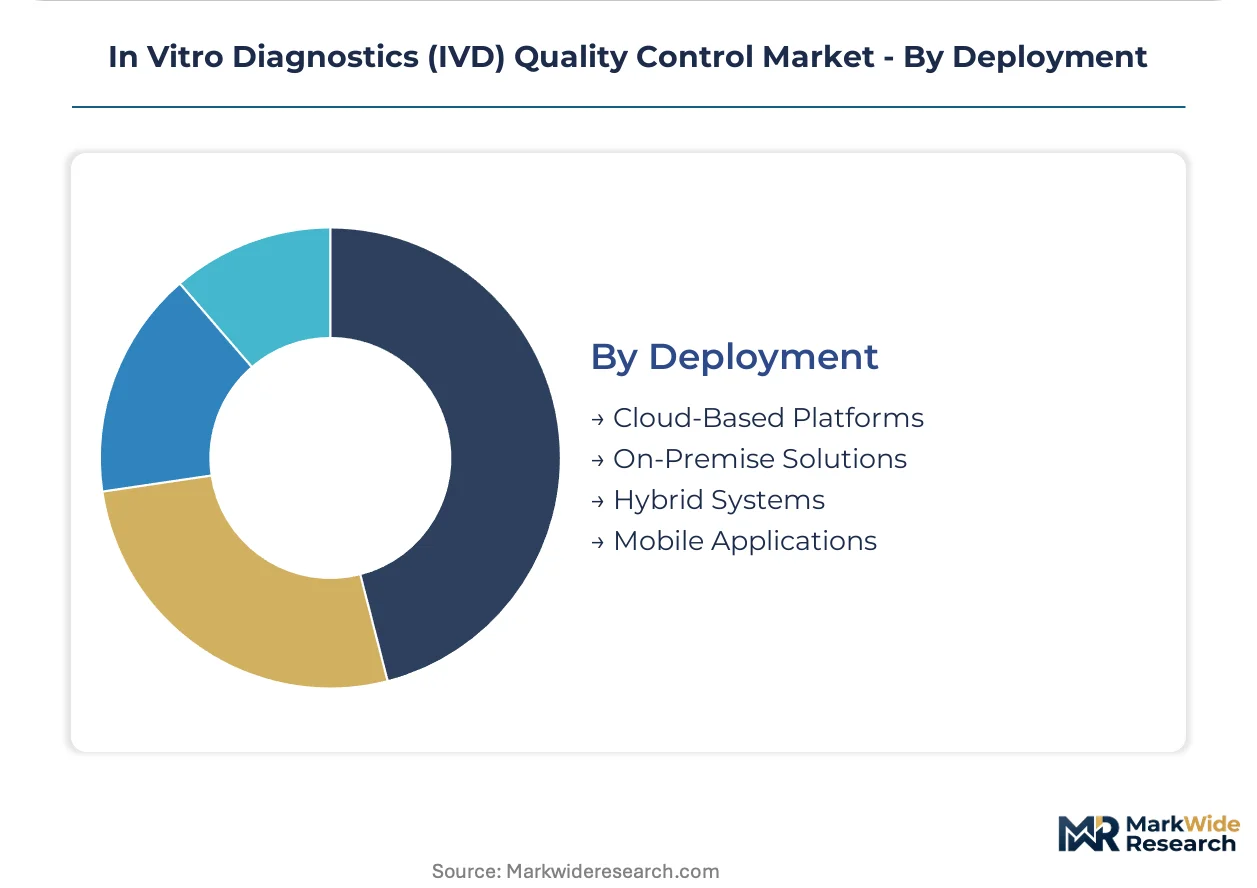
The In Vitro Diagnostics (IVD) quality control market segments by the nature of the product, the assays it supports, the operational settings, and its deployment architecture. Understanding these divisions allows laboratories and manufacturers to align their strategies with evolving regulatory demands and technological advancements.
Product Type:
The turnover rate for different product types varies significantly, with some materials requiring frequent replenishment while software solutions offer longer lifecycle value.
- Control Materials:These are substances with known analyte concentrations, processed alongside patient samples to monitor the accuracy and precision of diagnostic assays. Demand for liquid-stable, multi-analyte controls is high in high-throughput clinical chemistry laboratories across Germany and the United Kingdom, driven by efficiency gains.
- Quality Control Software:Digital platforms integrate with laboratory information systems, providing real-time data analysis, peer-group comparisons, and automated compliance reporting. The push for ISO 15189 accreditation in Australia and Canada necessitates advanced software for data integrity and audit trails.
- Calibrators:Specific materials used to establish the measurement scale of a diagnostic instrument or assay, ensuring accurate quantitative results.
- Instrument Adjustors:Products designed for fine-tuning the performance parameters of IVD instruments to maintain optimal operational specifications.
- Reference Standards:Highly characterized materials with assigned values, used to validate the accuracy of control materials and calibrators.
Control Materials dominates the installed base. Quality Control Software is where expansion concentrates.
Application:
The specific application areas influence the complexity and specificity required for quality control products, impacting their development cycles and market penetration.
- Molecular Diagnostics:This segment includes quality controls for nucleic acid amplification tests, sequencing, and genetic analysis, ensuring the accuracy of complex genomic assays. The expansion of oncology and infectious disease testing in the United States and China drives the need for highly specific molecular QC.
- Immunoassay:Quality controls for tests detecting antibodies, antigens, or other proteins, commonly used in endocrinology, infectious diseases, and oncology. High-volume immunoassay testing in large hospital networks across France and Italy requires robust and reliable QC solutions.
- Clinical Chemistry:Controls for a broad range of analytes in bodily fluids, including glucose, electrolytes, and enzymes, essential for routine health monitoring.
- Microbiology Testing:Quality control products for bacterial identification, antimicrobial susceptibility testing, and pathogen detection.
- Hematology:Controls used to verify the accuracy of blood cell counts, coagulation parameters, and other blood-related diagnostic tests.
The cost structure for quality control products varies significantly across different application areas, reflecting the complexity of assay development and material formulation.
End User:
The type of end-user dictates procurement patterns, volume requirements, and the level of technical support needed for IVD quality control solutions.
- Diagnostic Laboratories:These facilities perform a wide range of IVD tests, requiring comprehensive QC programs for accreditation and regulatory compliance. Large central laboratories in India and Brazil are making significant investments in certified QC products to support modernized infrastructure.
- Point-of-Care Testing Centers:Decentralized testing sites, often located outside traditional laboratories, demand user-friendly and automated QC solutions for rapid results. The growth of POCT in rural areas of South Africa and Mexico presents an opportunity for connected QC systems.
- Research Institutions:Academic and commercial research laboratories utilize IVD quality controls for assay development, validation, and clinical studies.
- Blood Banks:These entities rely on stringent quality control for blood typing, infectious disease screening, and cross-matching to ensure patient safety.
- Pharmaceutical Companies:Pharma firms use IVD quality controls in drug development, clinical trials, and companion diagnostics validation.
The volume of quality control materials consumed differs substantially among end-user segments, with large diagnostic laboratories representing the highest consumption.
Deployment:
The deployment model for quality control software and data management systems reflects the technological capabilities and infrastructure preferences of laboratories.
- Cloud-Based Platforms:These solutions offer remote access, centralized data management, and scalability, facilitating inter-laboratory comparisons and predictive analytics. Laboratories in the Nordic countries and Singapore favor cloud deployments for their flexibility and data security features.
- On-Premise Solutions:Software and systems installed directly on a laboratory's local servers, offering direct control over data and network security. Many established hospital laboratories in Japan and Canada maintain on-premise solutions due to existing IT infrastructure and data governance policies.
- Hybrid Systems:This approach combines elements of both cloud-based and on-premise deployments, balancing local control with remote accessibility.
- Mobile Applications:QC apps provide convenient access to data, alerts, and basic analysis on portable devices, supporting decentralized testing.
Customer preferences for deployment models are shifting, with cloud-based platforms gaining share fastest due to their scalability and accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large diagnostic laboratories and accredited hospital networks drive significant demand for IVD quality control products globally. These institutions prioritize robust QC protocols to meet stringent regulatory standards and ensure accurate patient results. The need for advanced quality control is particularly acute in regions undergoing rapid laboratory modernization.
United States
Demand for molecular diagnostics and complex genomic assays drives the US IVD QC market. The US FDA mandates rigorous quality control procedures for all diagnostic devices. Major university medical centers across the Northeast Corridor, including Boston and New York, actively integrate advanced QC software for compliance.
Germany
Germany's robust healthcare infrastructure demands high-quality IVD QC materials for clinical chemistry and immunoassay laboratories. Europe's IVDR significantly impacts manufacturers and laboratories within the country, requiring enhanced performance data. The medical technology cluster in Bavaria fosters innovation in control material chemistry and digital QC solutions.
India
India's expanding clinical laboratory infrastructure creates substantial demand for certified IVD quality control products. The Central Drugs Standard Control Organization (CDSCO) increasingly emphasizes quality assurance in diagnostic testing. Major diagnostic chains in metropolitan areas like Mumbai and Delhi are investing in cloud-based QC platforms.
China
The rapid expansion of oncology and infectious disease testing fuels the need for specialized molecular QC in China. The National Medical Products Administration (NMPA) enforces strict quality control standards for IVD products entering the market. Research hubs in the Yangtze River Delta actively develop novel control materials for emerging biomarkers.
Australia
Australia's push for ISO 15189 accreditation necessitates advanced quality control software for data integrity and audit trails. The Therapeutic Goods Administration (TGA) oversees the regulatory compliance of IVD devices and associated QC products. Large pathology networks in Sydney and Melbourne are rapidly adopting peer-group comparison programs.
In Vitro Diagnostics (IVD) Quality Control Market Key Industry Players
Channel-controlling players compete with product-specialist players in the IVD quality control market. The market exhibits a tiered structure, with large diagnostic instrument manufacturers offering integrated solutions alongside independent control material providers. Strategic archetypes include comprehensive portfolio providers, niche molecular QC specialists, and software-focused analytics firms. Companies are primarily engaged in portfolio diversification and strategic partnerships to expand their market reach.
Within the comprehensive portfolio provider archetype, Bio-Rad Laboratories Inc. represents a significant player, leveraging its extensive range of independent control materials across diverse instrument platforms and supporting digital transition. Siemens Healthineers AG exemplifies the integrated solution approach, specializing in QC solutions directly aligned with its own diagnostic instrumentation, creating a closed-loop ecosystem. Thermo Fisher Scientific Inc. also occupies a position as a broad-spectrum supplier, providing a wide array of control materials and related software for various diagnostic applications. These firms anchor the market by offering both physical controls and digital data management services to meet evolving laboratory needs.
| Leading Market Players |
|---|
| LGC Limited |
| Randox Laboratories |
| Bio-Rad Laboratories Inc. |
| Danaher Corporation |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| Sysmex Corporation |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Specialized biological reagents and certified reference materials, largely sourced from established manufacturers in Germany and the United States, underpin the cost structure for advanced IVD quality control products. These upstream concentrations directly influence margin pools available to downstream software and service providers.
Pricing Analysis
Cost-plus contract patterns with indexation to raw material costs often define pricing for high-volume control materials. Pricing stratifies across premium, standard, and economy tiers, reflecting certification levels and after-sales service bundles. Cost compression in the independent laboratory segment intensifies due to budget constraints, driving demand for more economical solutions. Large, accredited hospital networks exhibit lower price sensitivity, prioritizing comprehensive data management and compliance features.
Supply Chain Analysis
Export-control regimes for sensitive biological materials limit cross-border flows, influencing sourcing strategies for IVD quality control components. Geographic supply concentration for specialized chemicals and microfluidic components exists across Germany, the United States, and China. Raw material dependencies include highly purified human and animal matrices, alongside specific diagnostic reagents. Single-source vulnerability for niche, commutable control materials presents a structural risk. Downstream distribution typically involves direct sales to large diagnostic laboratories and extensive distributor networks for smaller, independent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IVD quality control market is experiencing a buyer-power shift, driven by the consolidation of large diagnostic laboratory networks and procurement groups in key regions.
For Market Incumbents: Entrench existing customer relationships by deepening integration with laboratory information systems and expanding cloud-based QC software offerings. This strategy mitigates the threat from OEM-specific solutions and cost pressures from smaller, independent laboratories. Invest in R&D for novel analyte stability and pursue comprehensive ISO 15189 certification to maintain a competitive edge.
For New Entrants and Emerging Players: Point-of-care testing QC solutions and predictive analytics software for data-driven quality assurance represent penetrable white-space opportunities. Developing economies, particularly in India and Brazil, offer significant market potential for scalable, cloud-based QC software. A subscription-based Software-as-a-Service (SaaS) model provides an accessible go-to-market angle for smaller laboratories.
For Investors and Strategic Acquirers: Capital is best deployed toward acquiring niche molecular QC specialists or cloud-based software firms with strong LIS integration capabilities. The long-term viability of this market is anchored in sustained demand for precision diagnostics and stringent regulatory compliance over the next 5-10 years. A signal to watch is the accelerated adoption rates of AI and machine learning algorithms within QC software platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cloud-Based QC Software | This initiative centralizes data management and streamlines compliance reporting for accredited laboratories. |
| Invest in Novel Analyte Stability | This improves the reliability and shelf-life of control materials for emerging and complex biomarkers. |
| Develop Predictive Analytics Tools | This enables early detection of instrument errors, preventing costly re-runs and improving patient safety. |
| Target Point-of-Care QC Solutions | This addresses the growing demand for automated quality control in decentralized testing environments. |
| Form Strategic Partnerships with LIS Vendors | This ensures seamless data flow and enhances interoperability across diverse laboratory systems. |
Research Approach
Operator-level perspectives from clinical laboratory directors, procurement managers, IVD manufacturers' R&D leads, and regulatory affairs specialists anchored the qualitative base of this analysis. Primary interviews were triangulated with secondary research, drawing from US FDA guidance documents, Europe's IVDR publications, ISO 15189 accreditation reports, and company annual reports. Both bottom-up and top-down approaches were employed for data synthesis.
Scenario-bracketing framed the analytical framework, projecting market trajectories across the analysis window. Segmentation dimensions modeled included product type, application, end user, deployment model, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market drivers, with diagnostic test volume growth and new biomarker discovery rates serving as key industry-specific forecast inputs.
Practitioners should monitor unforeseen regulatory changes, rapid technological obsolescence, and global supply chain disruptions for early signals of market shifts. Forecasts reflect assumptions documented at the time of publication. Material shifts in regulatory frameworks or diagnostic testing paradigms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
HIV Diagnostics Market