
 North America Non-Hodgkin Lymphoma Diagnostics Market | 2026-2036
North America Non-Hodgkin Lymphoma Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Hodgkin Lymphoma Diagnostics Market Analytics
Multi-source procurement of assay platforms and reagent kits is broadening across hospital laboratories and reference networks. NeoGenomics Laboratories leverages its specialized oncology focus to sustain high-complexity testing volumes. Thermo Fisher Scientific anchors the supply base through integrated instrument-reagent workflows. QIAGEN competes with differentiated sample preparation technologies that reduce turnaround times for lymphoma subtyping.
Non-Hodgkin lymphoma diagnostics encompasses laboratory and imaging methodologies that identify malignant lymphocyte proliferation through immunophenotyping, genetic analysis, and morphological examination, typically requiring fresh tissue specimens preserved in formalin-fixed paraffin-embedded blocks for downstream molecular interrogation. The primary purpose is accurate classification into WHO-defined subtypes to guide chemotherapy selection, targeted therapy eligibility, and clinical trial stratification. Flow cytometry dominates the product type landscape for initial immunophenotyping, while next-generation sequencing captures expanding margin pools as payers gradually reimburse comprehensive genomic profiling. Diagnostic laboratories represent the fastest-growing end user channel as health systems consolidate send-out testing to regional reference hubs.
FDA oversight of in vitro diagnostics and companion assay approvals shapes product development timelines and commercial launch pathways across the United States. CLIA certification requirements and CAP accreditation standards govern laboratory quality systems, directly influencing capital deployment decisions for test menu expansion. Health Canada and provincial health technology assessment bodies in Canada regulate market access and reimbursement for novel molecular diagnostics. Stakeholders must monitor evolving payer coverage policies for liquid biopsy applications and genomic profiling to align R&D portfolios with reimbursable test categories.
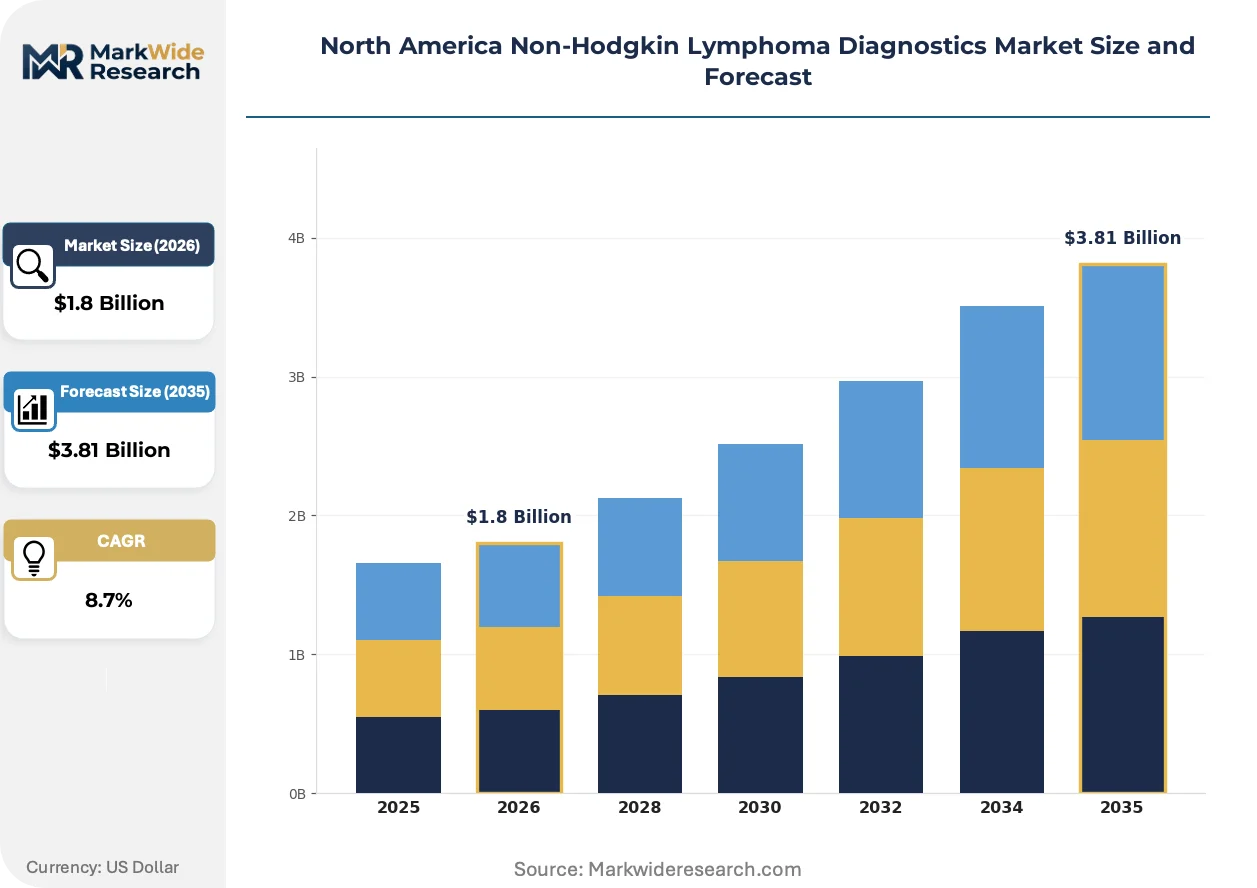
Market Dynamics
Consolidation of hospital laboratory networks into regional reference hubs is restructuring test volume flows across the United States and Canada, concentrating capital deployment decisions among fewer procurement entities and intensifying vendor consolidation pressures.
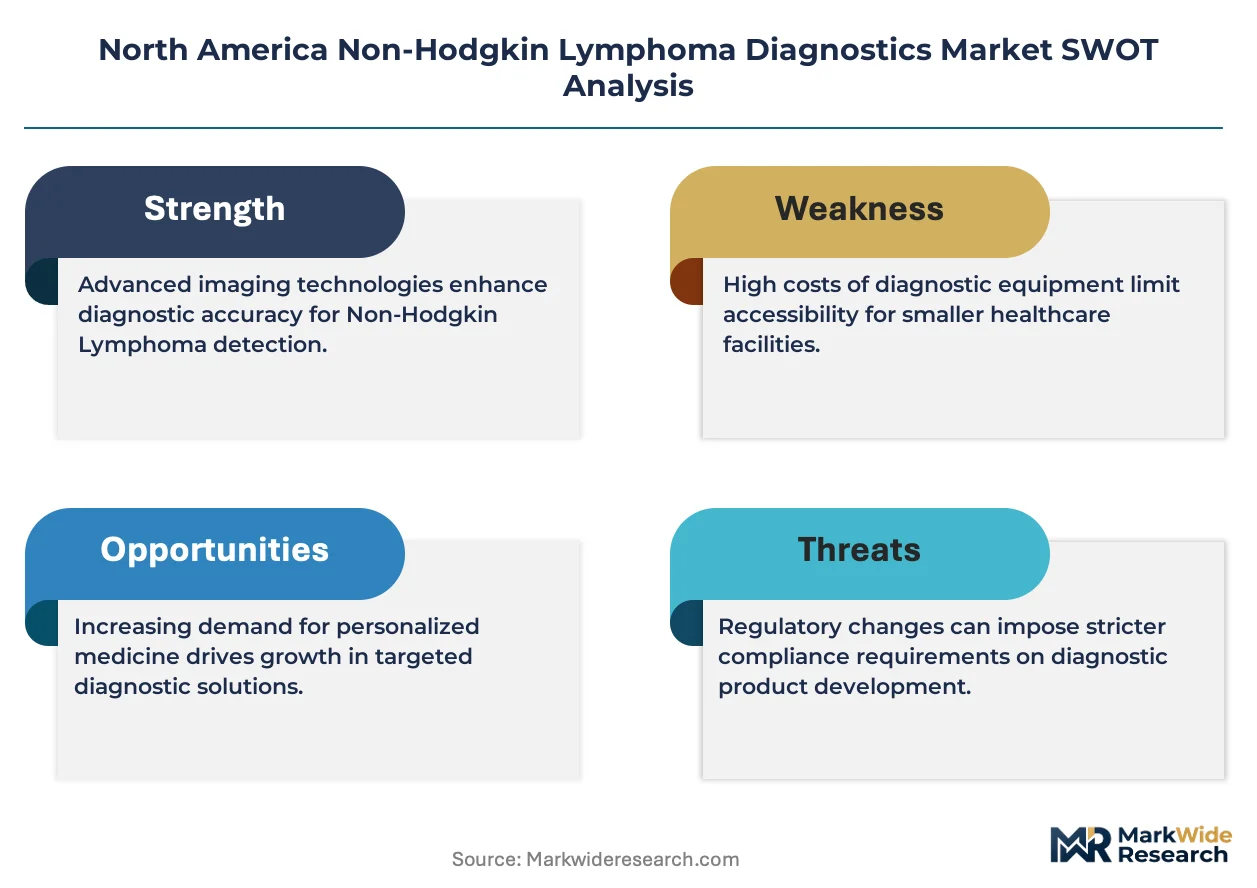
Growth Catalysts
- FDA Companion Diagnostic Pathway:Streamlined premarket review processes for lymphoma-associated biomarker assays are accelerating commercial launch timelines for multiplex immunohistochemistry panels.
- Flow Cytometry Standardization:CAP-accredited laboratories across Ontario and Quebec are adopting eight-color panel protocols, expanding reproducible immunophenotyping capacity for diffuse large B-cell lymphoma subtyping.
- Academic Medical Center Expansion:NCI-designated cancer centers in Texas, California, and New York are scaling next-generation sequencing infrastructure to support clinical trial enrollment.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction master mixes and fluorochrome-conjugated antibodies depend on concentrated manufacturing in Massachusetts and California, creating geographic vulnerability.
- Technical Limitation of FFPE DNA:Formalin fixation introduces cross-linking artifacts that degrade nucleic acid quality, constraining comprehensive genomic profiling success rates in community hospital settings.
- CLIA High-Complexity Certification Barriers:Personnel requirements and proficiency testing mandates limit laboratory expansion into molecular lymphoma diagnostics outside major metropolitan clusters.
Strategic Opportunities
- Liquid Biopsy Reimbursement Expansion:Emerging coverage determinations from Medicare Administrative Contractors in the United States are creating reimbursable categories for circulating tumor DNA monitoring in relapsed mantle cell lymphoma.
- Artificial Intelligence-Augmented Pathology:Integration of deep learning algorithms with whole-slide imaging is automating morphological pattern recognition for lymphoma classification.
- Provincial Network Investment:Health Canada and Alberta Health Services are funding specialized oncology diagnostic hubs to reduce send-out testing to United States reference laboratories.
Industry Challenges
- Molecular Pathologist Workforce Scarcity:Fellowship-trained hematopathologists capable of integrating genomic data with traditional morphology remain concentrated in coastal United States academic centers.
- Laboratory Information System Integration:Disparate data standards between legacy anatomic pathology systems and new molecular diagnostic platforms complicate workflow orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Hodgkin Lymphoma Diagnostics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunohistochemistry, Flow Cytometry, PCR, Cytogenetics End User: Hospitals, Diagnostic Laboratories, Research Institutes, Oncology Clinics Technology: Next-Gen Sequencing, Microarray, FISH, RT-PCR Test Type: Tissue Biopsy, Blood Test, Bone Marrow Aspiration, Lymph Node Excision |
| Companies Covered | Agilent Technologies, Inc., NeoGenomics Laboratories, Hologic, Inc., Labcorp Genetics Inc., PerkinElmer, QIAGEN, Thermo Fisher Scientific, Merit Medical Systems, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Hodgkin Lymphoma Diagnostics Market Evolving Landscape
Digital pathology infrastructure and artificial intelligence-assisted diagnostic workflows are compressing turnaround times for complex lymphoma subtyping while regulatory frameworks evolve to accommodate algorithm-augmented clinical decision support.
Multiplex immunofluorescence imaging systems are automating simultaneous detection of six to nine protein biomarkers on single tissue sections, enabling spatial phenotyping of tumor microenvironments. Regional reference laboratories in Illinois and Pennsylvania are deploying these platforms to support CAR-T therapy eligibility screening. This technology is automating manual sequential staining protocols that previously required multiple tissue sections and extended processing timelines.
Health Canada has issued guidance documents clarifying evidentiary requirements for in vitro diagnostic devices with machine learning components, establishing a pathway for algorithm-based lymphoma classification tools. The framework requires locked algorithm versions and prospective clinical validation studies. United States-based manufacturers are adapting submission strategies to align with these standards for parallel market entry.
Hospital systems are consolidating send-out molecular testing contracts with single-source reference partners, replacing fragmented laboratory service agreements. Academic medical centers in Michigan and North Carolina are negotiating exclusive multi-year partnerships that bundle flow cytometry, cytogenetics, and sequencing services. This concentration is most pronounced in the United States Midwest, where Catholic health system networks are standardizing diagnostic menus across twelve-state footprints.
North America Non-Hodgkin Lymphoma Diagnostics Market Segmentation
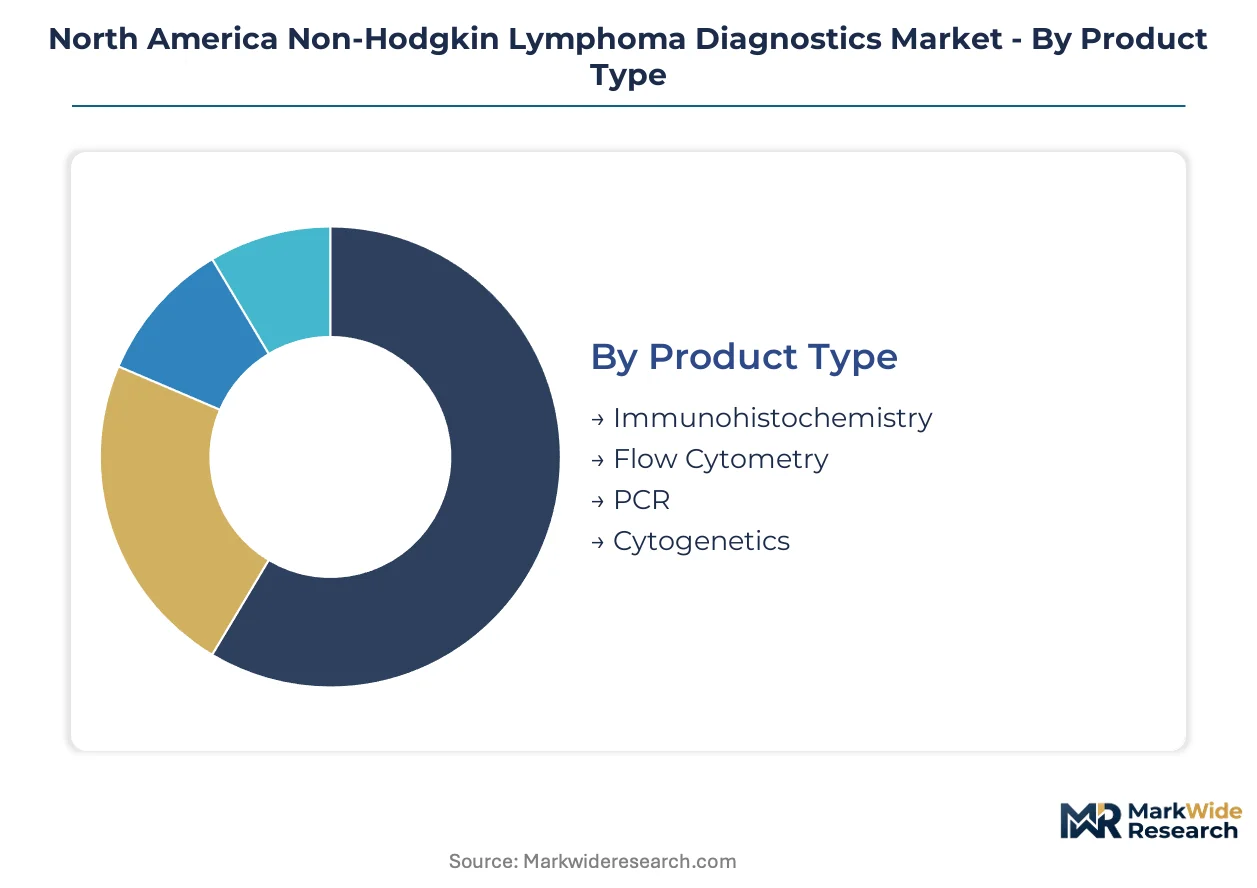
Diagnostic modality selection in lymphoma workups follows a staged algorithm where initial immunophenotyping determines downstream molecular interrogation depth. Procurement decisions across hospital systems increasingly bundle complementary technologies to minimize send-out testing and capture margin within integrated delivery networks.
Product Type:
Technology specifications governing sensitivity, multiplexing capacity, and specimen compatibility shape platform selection across reference laboratories and hospital-based pathology departments.
- Flow Cytometry:Eight-color panel protocols detect surface and intracellular protein expression on single-cell suspensions from blood, bone marrow, or fresh tissue. CAP-accredited laboratories across Ontario and Quebec are standardizing these panels for diffuse large B-cell lymphoma subtyping, with demand concentrating in academic medical centers managing high trial enrollment volumes.
- Immunohistochemistry:Chromogenic antibody staining on formalin-fixed paraffin-embedded sections enables morphological correlation with protein expression patterns. Community hospital laboratories in Texas and California are expanding automated IHC platforms to retain routine diagnostic work internally rather than referring to regional hubs.
- PCR:Polymerase chain reaction amplifies targeted DNA sequences for clonality assessment and translocation detection. Hospital laboratories in Michigan deploy these assays for B-cell and T-cell receptor gene rearrangement testing.
- Cytogenetics:Karyotyping and fluorescence in situ hybridization identify chromosomal abnormalities characteristic of specific lymphoma subtypes. Reference networks in Pennsylvania maintain specialized capacity for complex aberration profiling.
Mature deployment sits with Immunohistochemistry. Newer deployment is concentrated in Flow Cytometry.
End User:
Consolidation of testing volumes and capital deployment authority varies sharply across institutional types, with reimbursement mechanisms and regulatory certification requirements filtering market access.
- Diagnostic Laboratories:Regional reference hubs consolidate send-out testing from multiple hospital systems, achieving scale economies on high-complexity molecular assays. Health systems in the United States Midwest are negotiating exclusive multi-year partnerships that bundle flow cytometry, cytogenetics, and sequencing services with these entities.
- Hospitals:In-house pathology departments retain routine immunophenotyping and IHC staining, with expansion into molecular testing contingent on CLIA high-complexity certification. Hospital-based laboratories in New York and California are adding next-generation sequencing capacity to support precision oncology programs.
- Oncology Clinics:Community-based cancer centers depend on external reference laboratories for molecular diagnostic support, with procurement decisions influenced by payer contracting relationships.
- Research Institutes:NCI-designated cancer centers in Texas maintain specialized infrastructure for investigational assay development and clinical trial correlative science.
Volume concentration is heaviest in Diagnostic Laboratories. Margin capture is shifting toward Hospitals with integrated molecular platforms.
Technology:
Detection methodology determines analytical sensitivity, throughput, and compatibility with degraded nucleic acid specimens from archival tissue.
- Next-Gen Sequencing:Comprehensive genomic profiling interrogates hundreds of genes simultaneously to identify actionable mutations and resistance mechanisms. Academic medical centers in California and New York are scaling this infrastructure to support CAR-T therapy eligibility screening and clinical trial matching.
- FISH:Fluorescence in situ hybridization detects specific chromosomal translocations with single-cell resolution on intact nuclei. This technology dominates MYC, BCL2, and BCL6 rearrangement testing for double-hit lymphoma classification in reference laboratories.
- RT-PCR:Reverse transcription polymerase chain reaction quantifies RNA expression levels for minimal residual disease monitoring. Specialized oncology networks in Alberta are adopting these assays for post-treatment surveillance protocols.
- Microarray:Gene expression profiling distinguishes molecular subtypes with prognostic significance, though clinical adoption remains concentrated in research applications.
Reimbursement coverage is broadest for FISH. Steepest expansion trajectory belongs to Next-Gen Sequencing as payers gradually authorize comprehensive genomic profiling.
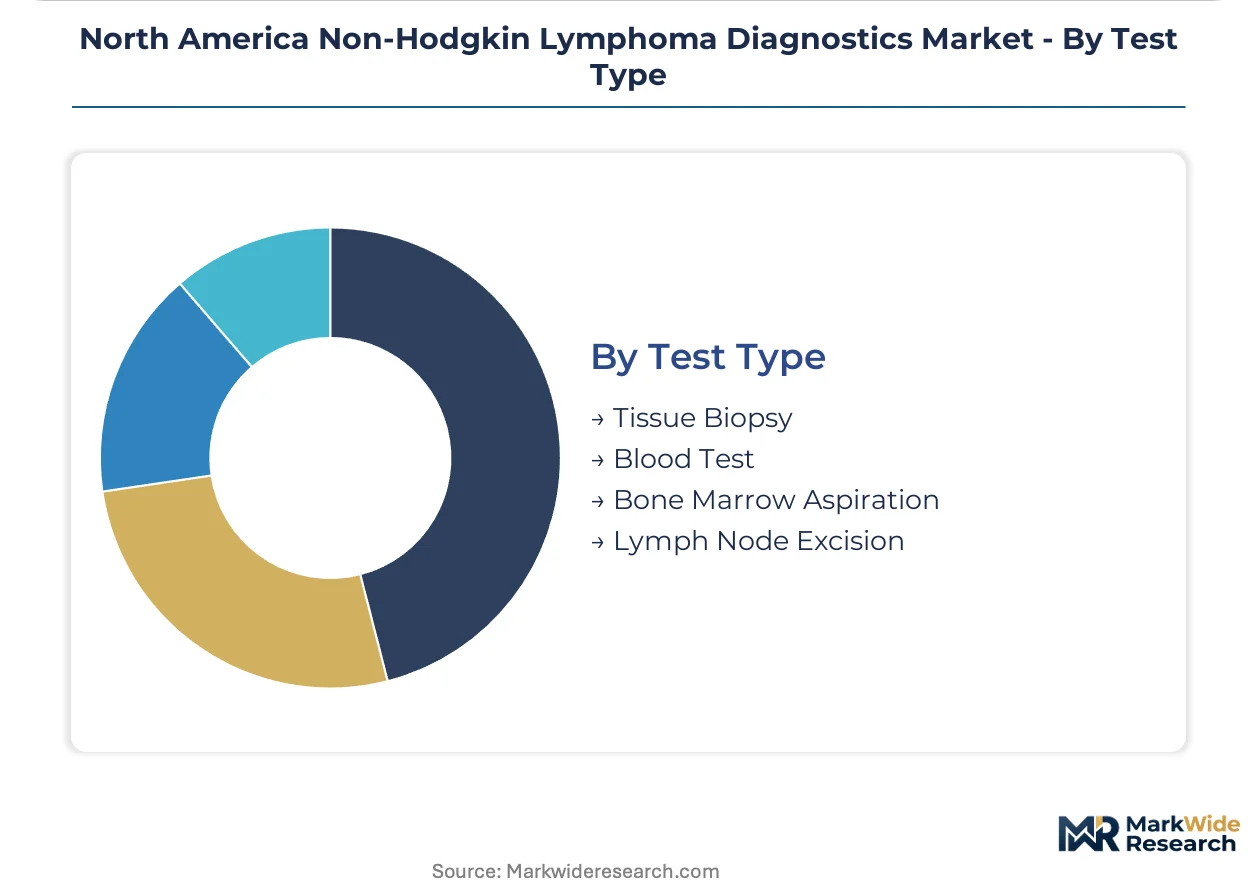
Test Type:
Specimen source and collection methodology determine downstream analytical options, with tissue-based testing retaining diagnostic primacy despite liquid biopsy advances.
- Tissue Biopsy:Core needle or excisional specimens provide cellular architecture for morphological assessment and generate formalin-fixed paraffin-embedded blocks for ancillary studies. Community hospitals across Illinois and Pennsylvania process these specimens through automated tissue processing systems.
- Blood Test:Peripheral blood draws enable flow cytometric immunophenotyping and circulating tumor DNA analysis. Medicare Administrative Contractors in the United States are issuing favorable coverage determinations for liquid biopsy monitoring in relapsed mantle cell lymphoma.
- Lymph Node Excision:Complete nodal resection remains the gold standard for initial diagnosis, with specimen triage protocols distributing material across multiple diagnostic platforms.
- Bone Marrow Aspiration:Aspirate and biopsy procedures assess disease staging and detect bone marrow involvement, with fresh aspirate material prioritized for flow cytometry and cytogenetics.
Procedure volume is highest for Tissue Biopsy. Technical innovation is concentrating in Blood Test methodologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and California concentrate reagent manufacturing for lymphoma diagnostics, anchoring supply-side infrastructure across the continent. Hospital consolidation into regional reference hubs redistributes testing volumes toward fewer procurement centers.
United States
FDA companion diagnostic pathways accelerate biomarker assay commercialization timelines for multiplex immunohistochemistry panels. Medicare Administrative Contractors issue favorable coverage determinations for circulating tumor DNA monitoring in relapsed mantle cell lymphoma. NCI-designated cancer centers in Texas, California, and New York scale next-generation sequencing infrastructure to support clinical trial enrollment.
Canada
CAP-accredited laboratories across Ontario and Quebec adopt standardized eight-color flow cytometry panel protocols for diffuse large B-cell lymphoma subtyping. Health Canada issues guidance documents clarifying evidentiary requirements for in vitro diagnostic devices with machine learning components. Alberta Health Services funds specialized oncology diagnostic hubs to reduce send-out testing to United States reference laboratories.
Mexico
Hospital systems in Mexico City Metro and Nuevo León expand pathology department capabilities to retain routine immunohistochemistry staining internally. The national pharmaceutical regulator tightens quality benchmarks for imported diagnostic reagents. Northern Border States develop cross-border laboratory partnerships to access specialized molecular testing capacity.
North America Non-Hodgkin Lymphoma Diagnostics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle instrument-reagent workflows to secure multi-year exclusive contracts with consolidating health systems. The vendor base organizes around three tiers: integrated life science conglomerates with full workflow portfolios, specialized oncology reference laboratories with high-complexity certification, and regional distributors with service-intensive local presence. Competitive moves concentrate on geographic expansion through reference laboratory acquisitions and technology licensing agreements for algorithm-augmented diagnostic platforms.
Among integrated diagnostic platform suppliers, Thermo Fisher Scientific and QIAGEN exemplify the instrument-reagent bundling archetype, while NeoGenomics Laboratories occupies a position within the specialized oncology reference laboratory tier. These entities represent contrasting strategic postures: the former anchor supply security through manufacturing concentration in Massachusetts and California, while the latter capture margin from consolidated send-out testing contracts across Midwestern Catholic health system networks.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| NeoGenomics Laboratories |
| Hologic, Inc. |
| Labcorp Genetics Inc. |
| PerkinElmer |
| QIAGEN |
| Thermo Fisher Scientific |
| Merit Medical Systems |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up reference laboratory networks in the United States Midwest are consolidating procurement authority across twelve-state Catholic health system footprints, concentrating pricing leverage while compressing margins for reagent suppliers locked into multi-year exclusive contracts.
Pricing Analysis
Service-bundling differentiation separates instrument-reagent contracts with embedded technical support from unbundled reagent-only purchasing favored by large academic medical centers. Three-tier pricing structure across premium, standard, and economy levels reflects CAP accreditation status, CLIA certification tier, and annual test volume commitments. Pricing pressure stems from hospital systems consolidating send-out contracts with single-source reference partners, forcing mid-tier laboratories to absorb service costs previously passed through. Community hospital pathology departments exhibit highest price sensitivity due to constrained capital budgets, while NCI-designated cancer centers prioritize turnaround time over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by major health systems in Texas and California are qualifying secondary suppliers for fluorochrome-conjugated antibodies and PCR master mixes. Manufacturing concentrates in Massachusetts, California, and North Carolina, drawing from concentrated production of optical detection components, thermal cycling hardware, and synthetic oligonucleotides. Single-source vulnerability persists for specialized flow cytometry lasers and rare-earth fluorochromes. Distribution runs through regional reference hubs that consolidate inbound reagent logistics and outbound specimen transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics dominate competitive positioning as integrated platform vendors pursue captive supply of critical reagents and reference laboratories build in-house instrument development capabilities.
For Market Incumbents: Anchor CLIA high-complexity certification expansion in underserved metropolitan clusters to preempt emerging reference laboratory entrants. Secure multi-year exclusive partnerships with consolidating Catholic health system networks before competitor platform conversions lock in switching costs. Defend against specialized oncology reference laboratories by bundling instrument placement with guaranteed reagent supply allocations during polymerase chain reaction master mix shortages.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium Thermo Fisher Scientific workflows and economy-grade regional distributors opens white-space targeting of community hospital laboratories seeking CAP-accredited eight-color flow cytometry without enterprise-scale capital commitments. Alberta and Quebec provincial health technology assessment bodies represent most penetrable regulatory entry points for algorithm-augmented diagnostic platforms. Go-to-market positioning should emphasize Health Canada machine-learning guidance compliance to differentiate from United States FDA submission timelines.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized oncology reference laboratories with existing CLIA high-complexity certification in the United States Southeast, where molecular pathologist workforce scarcity has constrained expansion. Long-term viability hinges on capturing consolidated send-out testing contracts before health system network standardization completes. Watch Medicare Administrative Contractor coverage determinations for circulating tumor DNA monitoring as inflection indicator for liquid biopsy reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Companion Diagnostic Submission | Streamlines premarket review for multiplex immunohistochemistry panels targeting lymphoma biomarkers. |
| Provincial Network Partnership | Alberta Health Services funding reduces United States reference laboratory dependency for specialized oncology diagnostics. |
| Artificial Intelligence-Augmented Platform | Health Canada guidance compliance enables parallel market entry for algorithm-based lymphoma classification tools. |
| Reagent Manufacturing Scale-Up | Massachusetts and California production expansion addresses geographic concentration vulnerability for PCR master mixes. |
| Liquid Biopsy Reimbursement Strategy | Medicare Administrative Contractor favorable determinations create reimbursable categories for relapsed mantle cell lymphoma monitoring. |
Research Methodology
Multi-period observation of CAP accreditation expansion, CLIA certification timelines, and provincial health technology assessment decisions anchored the trend analysis, supplemented by interviews with hematopathologists, hospital laboratory directors, reference network procurement executives, and Health Canada regulatory affairs specialists. Secondary validation drew from FDA 510(k) filings, Health Canada guidance documents, CMS Medicare coverage determinations, and CAP laboratory accreditation databases. Bottom-up test volume modeling triangulated against top-down health system consolidation tracking.
Input-output matrices mapped diagnostic modality adoption rates across product type, end user, and technology segments over the projection horizon. Segmentation dimensions included flow cytometry panel complexity, CLIA certification tier, and provincial versus private payer reimbursement status. CAGRs were derived from test volume elasticity to health system consolidation patterns and companion diagnostic approval trajectories. Forecast inputs incorporated NCI-designated cancer center infrastructure expansion and Medicare Administrative Contractor coverage evolution.
Inputs from hospital procurement databases and reference laboratory contract disclosures were available through the study window; gaps in liquid biopsy commercial claim data introduce uncertainty bands around circulating tumor DNA adoption curves. Forecasts reflect assumptions regarding payer coverage expansion and regulatory pathway timelines. Deviation in FDA premarket review duration or provincial health technology assessment decisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market