
 Alzheimer's Diagnostics and Therapeutics Market | 2026-2036
Alzheimer's Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Alzheimer's Diagnostics and Therapeutics Market Outlook
Hospital procurement for Alzheimer's diagnostics is tilting toward integrated biomarker platforms that combine blood-based assays with imaging confirmation. Biogen Inc. leverages its established neurology infrastructure to sustain infusion site networks for monoclonal antibody therapies. Eli Lilly and Company anchors its competitive position through vertical control over amyloid PET tracer manufacturing and companion diagnostic development.
Alzheimer's diagnostics and therapeutics encompass clinical tools and pharmacologic interventions designed to detect pathologic amyloid and tau accumulation and modify neurodegenerative progression. Diagnostic workflows typically require CSF biomarker quantification or PET imaging with fluorinated tracers targeting amyloid plaques, paired with neuropsychological batteries scoring cognitive decline across memory, executive function, and language domains. Biomarker-based testing is capturing margin pools as blood-based p-tau assays displace costlier PET scans for screening, while the injectables delivery mode dominates therapeutic administration due to the large molecular weight of monoclonal antibodies requiring intravenous infusion protocols.
FDA accelerated approval regulations, EMA conditional marketing authorization frameworks, and Japan's PMDA Sakigake designation system collectively compress development timelines and expand payer deliberation complexity for novel Alzheimer's therapies. These regulatory pathways shape demand by requiring confirmatory post-market trials that tie continued reimbursement to demonstrated clinical benefit. Stakeholders must monitor biomarker standardization efforts across FDA-qualified plasma assay programs and EMA-EMA joint qualification procedures to anticipate which diagnostic platforms will secure preferential reimbursement positioning.
Market Dynamics
FDA accelerated approval pathways for amyloid-targeting therapies are compressing commercialization timelines while forcing parallel investments in companion diagnostic infrastructure by specialty neurology clinics and hospital systems.
Growth Catalysts
- Blood-based p-tau assays:These plasma biomarker platforms enable scalable population screening without PET imaging capacity constraints, expanding diagnostic access beyond major academic medical centers.
- PMDA Sakigake designation:Japan's priority review system for breakthrough therapies accelerates market entry timelines and signals reimbursement commitment for novel Alzheimer's interventions.
- Specialty neurology clinic expansion:Dedicated memory disorder centers are building integrated diagnostic-therapeutic workflows that compress time from cognitive concern to treatment initiation.
Market Restraints
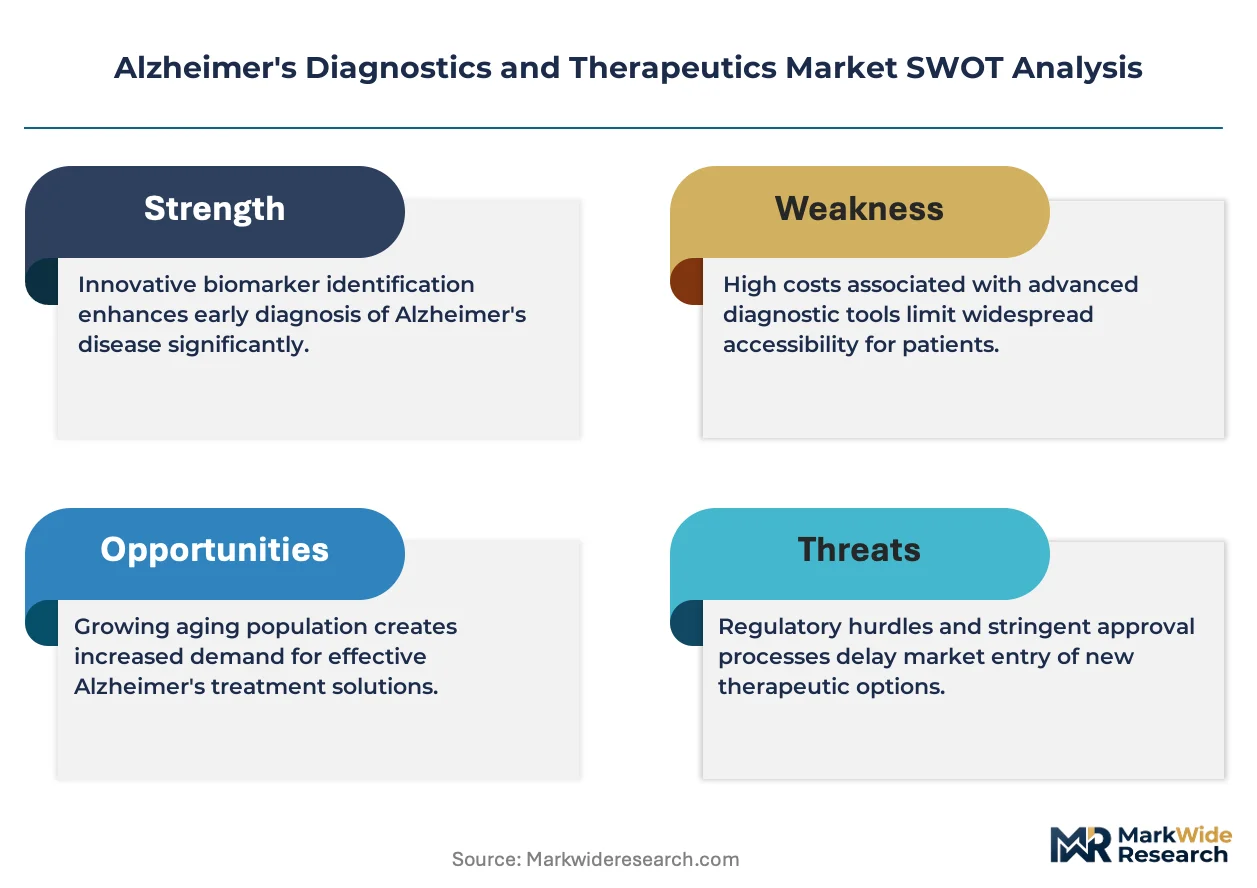
- Fluorinated tracer production concentration:Amyloid PET tracer manufacturing capacity clusters at limited radiopharmaceutical facilities, creating supply vulnerability for diagnostic confirmation workflows.
- Monoclonal antibody infusion infrastructure:Large-molecule therapeutics require intravenous administration protocols that strain outpatient capacity and create site-of-care bottlenecks.
- Confirmatory trial requirements:FDA accelerated approval mandates tie continued reimbursement to post-market clinical benefit demonstration, introducing regulatory uncertainty for therapy developers.
Strategic Opportunities
- Home-based cognitive monitoring:Digital biomarker platforms using smartphone-based assessments create pre-diagnostic engagement channels before specialist referral.
- CSF-to-plasma assay transition:Blood-based biomarkers are capturing margin pools previously allocated to lumbar puncture procedures and specialized neurochemistry laboratories.
- Germany's DiGA pathway:The BfArM digital health application fast-track creates reimbursement precedent for software-based cognitive assessment tools as prescription products.
Industry Challenges
- Biomarker harmonization delays:Lack of standardized cutoff values across plasma p-tau platforms creates inter-laboratory variability that complicates multi-site clinical trial enrollment.
- Neuroradiologist workforce scarcity:Amyloid PET interpretation requires specialized training that outpaces fellowship program output, creating diagnostic bottleneck at imaging confirmation stage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alzheimer's Diagnostics and Therapeutics Market |
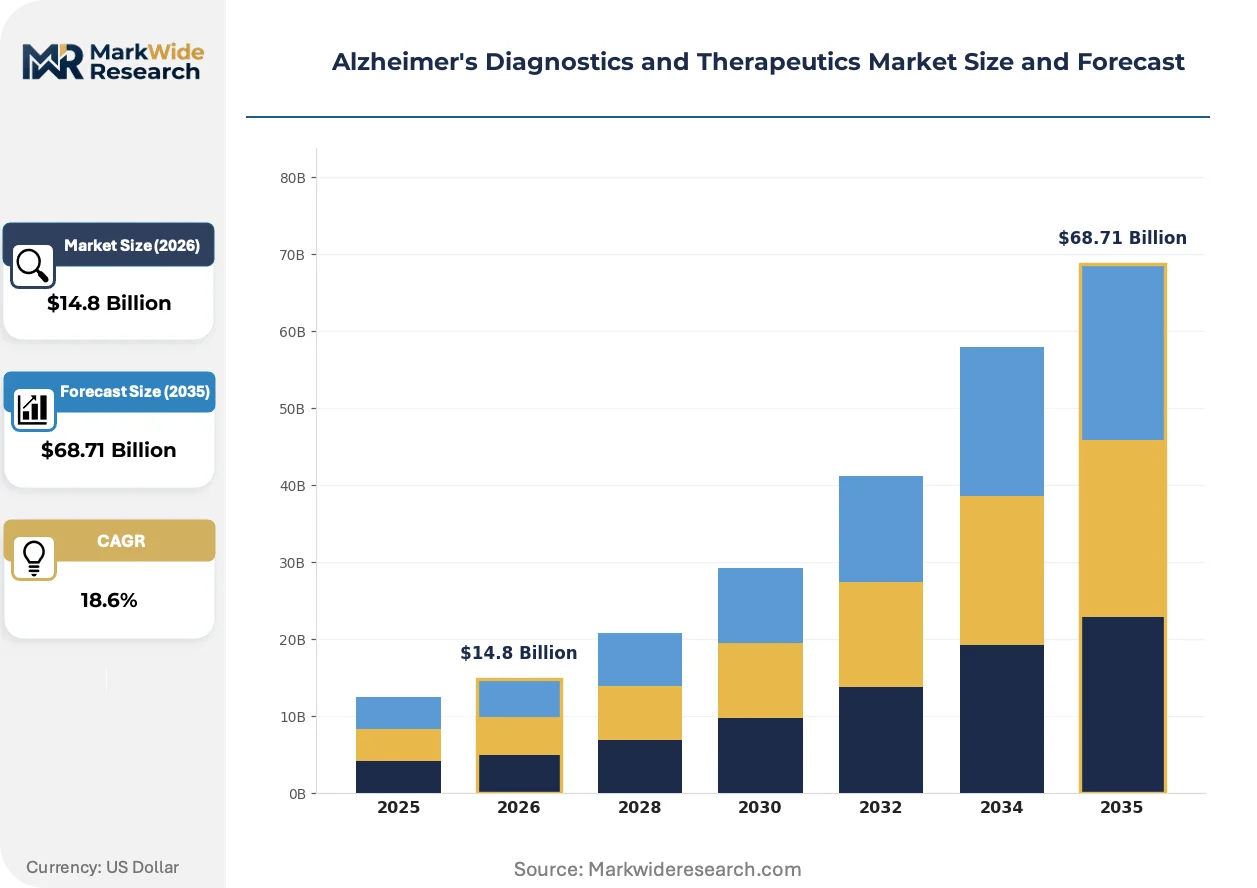
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, MRI, PET, Neuropsychological Tests Treatment Type: Cholinesterase Inhibitors, NMDA Receptor Antagonists, Antidepressants, Antipsychotics End User: Hospitals, Clinics, Home Care, Research Institutes Delivery Mode: Injectables, Oral Tablets, Transdermal Patches, Infusions |
| Companies Covered | Biogen Inc., AbbVie Inc., Eli Lilly and Company, Eisai Co., Ltd., Novartis AG, F. Hoffmann-La Roche Ltd., Johnson & Johnson Services, Inc., Teva Pharmaceuticals Ltd., Zydus Lifesciences Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alzheimer's Diagnostics and Therapeutics Market Strategic Shifts
Diagnostic-therapeutic convergence is restructuring competitive boundaries as pharmaceutical developers internalize companion test capabilities and imaging manufacturers build therapeutic alliances.
Plasma biomarker platforms are hybridizing immunoassay sensitivity with mass spectrometry specificity to achieve PET-correlated diagnostic accuracy at population-screening cost structures. Neurology clinics in the United States and Germany are adopting these hybrid workflows for pre-screening prior to imaging confirmation. This convergence is compressing the addressable market for standalone PET-based diagnostic services while expanding total evaluable patient volume.
EMA conditional marketing authorization frameworks require demonstrated clinical benefit within defined post-approval windows, forcing therapy sponsors to design adaptive trial infrastructure before initial reimbursement. This regulatory architecture shifts commercial risk toward confirmatory evidence generation rather than pre-market clinical development. European markets are responding with outcome-based reimbursement pilots that tie payment to cognitive endpoint achievement.
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic platforms that bundle blood assays, imaging coordination, and cognitive testing under single contracts. This concentration displaces point-solution vendors and elevates platform economics over standalone product margins. The United States exhibits the most pronounced procurement consolidation as health system integration accelerates.
Alzheimer's Diagnostics and Therapeutics Market Segmentation
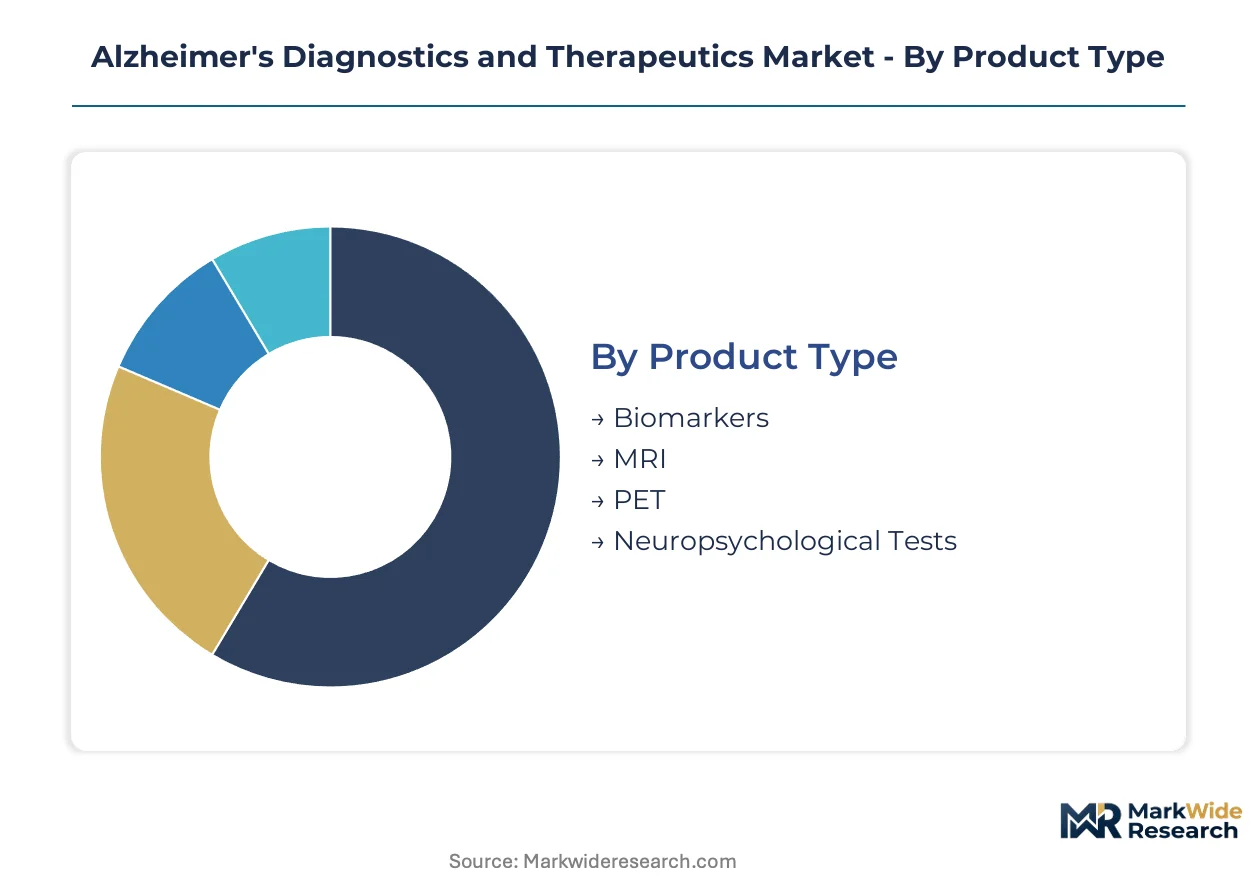
Segmentation in Alzheimer's care reveals how diagnostic and therapeutic workflows split across clinical settings and administration methods. Each category maps to distinct procurement patterns, reimbursement pathways, and infrastructure requirements that shape vendor positioning.
Product Type:
After-sales service intensity varies sharply across these platforms, with imaging systems demanding radiopharmaceutical logistics support while biomarker assays require laboratory quality assurance programs.
- Biomarkers:Blood-based p-tau and plasma amyloid assays use immunoassay or mass spectrometry detection methods. Demand concentrates in United States specialty neurology clinics seeking scalable screening alternatives to PET imaging, driven by Medicare reimbursement expansion for plasma-based testing. By volume, Biomarkers leads. By growth pace, this segment is climbing the fastest.
- MRI:Structural magnetic resonance imaging detects hippocampal atrophy and white matter changes. Hospital systems in Germany prioritize MRI as a first-line neuroimaging tool before amyloid confirmation, constrained by neuroradiologist interpretation capacity.
- PET:Positron emission tomography with fluorinated tracers enables direct amyloid plaque visualization. Academic medical centers in Japan maintain PET confirmation workflows despite blood-based alternatives, tied to PMDA diagnostic reimbursement structures.
- Neuropsychological Tests:Standardized cognitive batteries assess memory, executive function, and language domains. Memory disorder clinics deploy these tests across initial patient intake protocols.
By volume, Biomarkers leads. By growth pace, this segment is climbing the fastest.
Treatment Type:
Cost tier stratification separates legacy symptomatic therapies from emerging disease-modifying agents, with pricing and procurement channels diverging accordingly.
- Cholinesterase Inhibitors:Donepezil, rivastigmine, and galantamine enhance cholinergic neurotransmission. Primary care networks in the United States prescribe these agents for mild-to-moderate disease stages, facing generic price erosion.
- NMDA Receptor Antagonists:Memantine modulates glutamatergic signaling in moderate-to-severe Alzheimer's. Nursing home pharmacies in Germany represent concentrated dispensing points for this therapy class.
- Antidepressants:Selective serotonin reuptake inhibitors address behavioral and psychological symptoms. Psychiatric consultation-liaison services in hospital settings drive prescribing volume.
- Antipsychotics:Atypical antipsychotics manage agitation and psychosis in advanced disease. Regulatory scrutiny from FDA black box warnings limits utilization to severe behavioral disturbances.
By patient volume, Cholinesterase Inhibitors dominates. By revenue expansion, NMDA Receptor Antagonists shows steepest gains.
End User:
Application context determines workflow integration, with hospital-based comprehensive care contrasting against home-based monitoring emergence.
- Hospitals:Academic medical centers and community hospitals house integrated diagnostic-therapeutic units. United States health systems concentrate PET imaging and infusion center capacity within hospital campuses, shaped by FDA accelerated approval site requirements.
- Clinics:Specialty neurology and memory disorder clinics deliver longitudinal cognitive care. Japan's clinic network expansion supports PMDA Sakigake therapy distribution.
- Home Care:Home health agencies and family caregivers administer oral therapies and monitor behavioral symptoms. Germany's DiGA pathway enables prescription digital tools for home-based cognitive assessment.
- Research Institutes:Clinical trial sites and academic research centers drive biomarker validation and novel therapy investigation. EMA conditional marketing authorization frameworks concentrate trial infrastructure at these sites.
By patient throughput, Hospitals leads. By workflow innovation speed, Home Care is expanding most quickly.
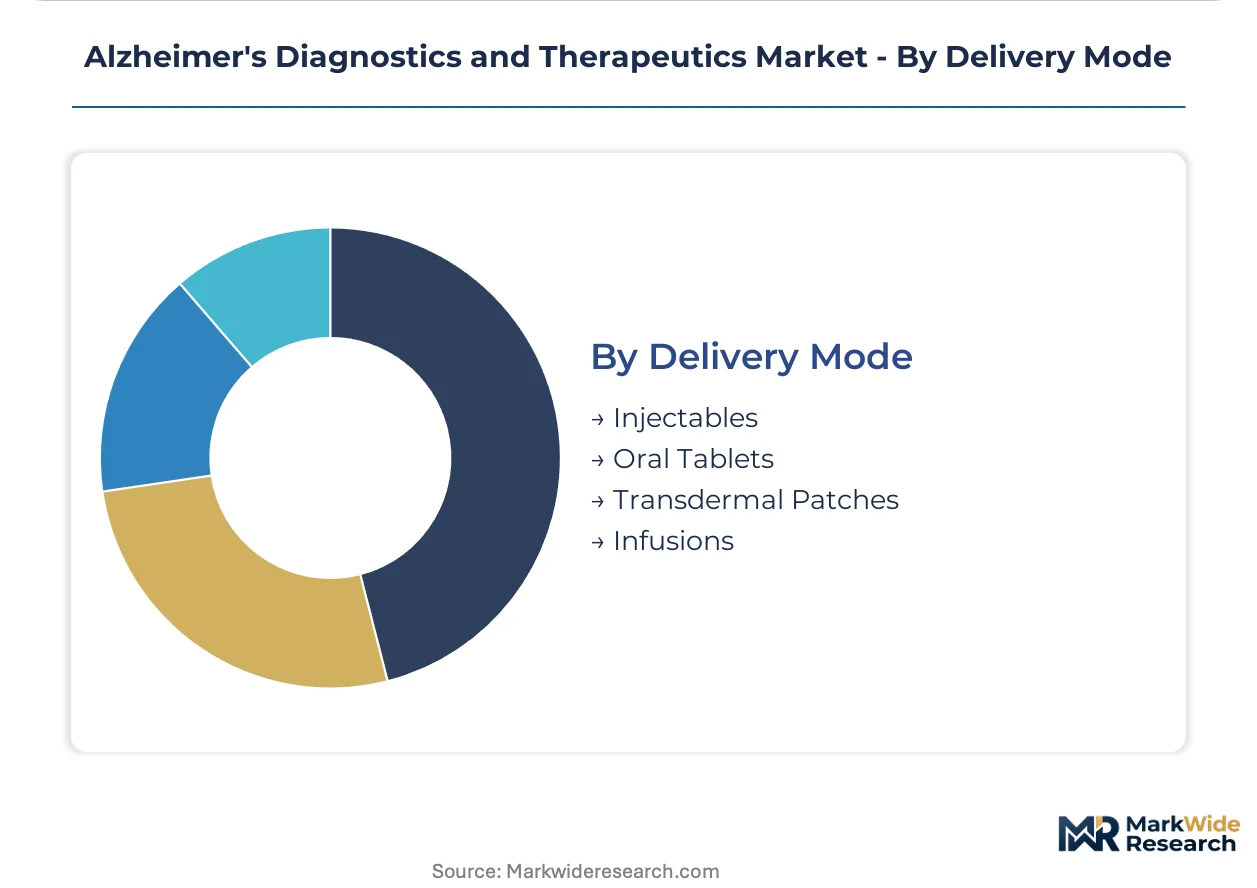
Delivery Mode:
Supply concentration in radiopharmaceutical manufacturing and infusion nursing capacity shapes availability across these administration methods.
- Injectables:Subcutaneous and intramuscular formulations include emerging monoclonal antibody therapies. Specialty pharmacy networks in the United States manage cold chain distribution for these biologics.
- Oral Tablets:Small-molecule symptomatic therapies dominate prescription volume. Retail pharmacy dispensing in Germany maintains high oral therapy share.
- Transdermal Patches:Rivastigmine patches offer continuous drug delivery with reduced gastrointestinal side effects. Nursing home formularies in Japan favor patch formulations for medication adherence.
- Infusions:Intravenous monoclonal antibodies require supervised administration over multiple hours. Hospital outpatient departments and standalone infusion centers in the United States compete for this service line.
By prescription count, Oral Tablets leads. By infrastructure investment, Infusions shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for amyloid-targeting therapies in the United States exceed reimbursement thresholds in Germany by substantial margins, concentrating profit pool capture in North American markets while European systems enforce cost-effectiveness floors through health technology assessment protocols.
United States
Medicare reimbursement expansion for plasma p-tau assays drives diagnostic volume migration from academic medical centers to community neurology practices. FDA accelerated approval pathways compress commercialization timelines for monoclonal antibody therapies while mandating confirmatory trial infrastructure. Massachusetts and California biotech clusters house the dominant amyloid PET tracer manufacturing and companion diagnostic development capabilities.
Germany
BfArM's DiGA fast-track pathway creates reimbursement precedent for prescription digital cognitive assessment tools, enabling home-based monitoring integration. EMA conditional marketing authorization frameworks require outcome-based reimbursement pilots that tie payment to demonstrated clinical benefit. The Rhine-Ruhr and Bavarian hospital networks concentrate integrated diagnostic-therapeutic unit deployment for memory disorder care.
Japan
PMDA Sakigake designation accelerates priority review timelines for breakthrough Alzheimer's therapies, signaling explicit reimbursement commitment from national health insurers. METI industrial policy supports domestic radiopharmaceutical production capacity expansion for fluorinated tracer supply security. Tokyo and Osaka metropolitan areas anchor specialty neurology clinic networks managing infusion site capacity for monoclonal antibody distribution.
United Kingdom
NICE health technology appraisals impose cost-effectiveness thresholds that filter market access for high-price disease-modifying therapies against cognitive endpoint benchmarks. NHS England's accelerated access collaborative creates pathway exceptions for therapies demonstrating transformational patient benefit. The Oxford-Cambridge-London golden triangle concentrates biomarker validation research and clinical trial site infrastructure.
Switzerland
Swissmedic's streamlined marketing authorization procedures attract therapy developers seeking rapid European market entry ahead of EMA centralized procedures. Outcome-based reimbursement contracts at cantonal hospital level create flexible pricing mechanisms for novel Alzheimer's interventions. Basel and Zurich pharmaceutical clusters sustain radiochemistry expertise for diagnostic tracer manufacturing and therapeutic antibody development.
Alzheimer's Diagnostics and Therapeutics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in biomarker assay and radiopharmaceutical manufacturing niches. The vendor structure bifurcates between consolidated pharmaceutical developers controlling therapeutic pipelines and fragmented diagnostic technology suppliers competing on assay sensitivity specifications. Three archetypes dominate: vertically integrated biopharmaceuticals with companion diagnostic capabilities, standalone neurology-focused drug developers, and diversified imaging and laboratory equipment manufacturers. Competitive moves concentrate on strategic partnerships bridging diagnostic-therapeutic workflows and capacity expansion in blood-based biomarker production.
Among North American biopharmaceutical developers, Biogen Inc., Eli Lilly and Company, and AbbVie Inc. exemplify the vertically integrated archetype combining therapeutic monoclonal antibody development with diagnostic infrastructure investments. Biogen Inc. represents established neurology infrastructure leverage for infusion site network management. Eli Lilly and Company occupies a position emphasizing upstream control over amyloid PET tracer manufacturing supply chains. AbbVie Inc. sits within the diversified pharmaceutical tier with neuroscience portfolio breadth spanning symptomatic and disease-modifying mechanisms.
| Leading Market Players |
|---|
| Biogen Inc. |
| AbbVie Inc. |
| Eli Lilly and Company |
| Eisai Co., Ltd. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Johnson & Johnson Services, Inc. |
| Teva Pharmaceuticals Ltd. |
| Zydus Lifesciences Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fluorinated tracer manufacturing clusters in the United States, Belgium, and Japan concentrate pricing power among three radiopharmaceutical suppliers serving amyloid PET confirmation workflows. This upstream concentration diverts margin pools toward blood-based biomarker platforms that bypass radiochemistry bottlenecks entirely.
Pricing Analysis
Configured-to-order pricing for companion diagnostic bundles commands substantial premiums over standard assay pricing for standalone biomarker tests. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform contracts from point-solution procurement, with certification grade and after-sales service intensity as primary differentiation drivers. Cost compression in the standard tier intensifies because Medicare reimbursement expansion for plasma p-tau assays commoditizes screening-stage diagnostics. Community neurology practices exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to research funding offsets.
Supply Chain Analysis
Extended payment terms from hospital procurement committees now stretch to 90-120 days, forcing diagnostic manufacturers to absorb working capital strain or seek supply-chain finance facilities. Geographic supply concentration centers on the United States, Germany, and Switzerland for monoclonal antibody production, while China and India anchor active pharmaceutical ingredient sourcing for symptomatic therapies. Raw material dependencies include fluorine-18 isotope production, specialized immunoassay reagents, and cold-chain biologics packaging. Single-source vulnerability in neuroradiologist-trained workforce creates diagnostic confirmation bottlenecks. Distribution runs through specialty pharmacy networks for infused therapeutics and hospital laboratory channels for biomarker assays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blood-based diagnostic substitution threatens incumbent imaging and CSF testing revenue streams as plasma p-tau platforms achieve PET-correlated accuracy at population-screening economics.
For Market Incumbents: Insulate core revenue by deepening backward integration into radiopharmaceutical manufacturing capacity and securing exclusive hospital system contracts that bundle imaging confirmation with therapeutic infusion site access. The blood-based biomarker substitution threat demands preemptive companion diagnostic platform control to capture margin migration from PET workflows. For New Entrants and Emerging Players: Germany's DiGA reimbursement pathway for prescription digital cognitive tools offers the most penetrable entry point for software-based assessment platforms seeking regulatory-validated market access. Target home-based monitoring integration through BfArM fast-track qualification, then leverage demonstrated outcomes to expand into United States Medicare Advantage contracts. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated biopharmaceuticals with captive companion diagnostic capabilities and established infusion site networks. Long-term viability across the analysis window hinges on confirmatory trial execution rather than accelerated approval capture alone. The signal to watch is post-market clinical benefit demonstration rates that determine continued reimbursement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Biogen Inc. and Eli Lilly and Company internalize biomarker platform control to capture diagnostic-therapeutic margin convergence. |
| Infusion Site Network Expansion | Specialty neurology clinics in the United States and Japan build supervised administration capacity for monoclonal antibody distribution. |
| Blood-Based Assay Scale-Up | Mass spectrometry-immunoassay hybrid platforms displace PET confirmation for screening-stage patient evaluation. |
| Regulatory Fast-Track Navigation | PMDA Sakigake and FDA accelerated approval pathways compress commercialization timelines for amyloid-targeting therapies. |
| Digital Health Reimbursement Strategy | Germany's DiGA pathway creates precedent for prescription software-based cognitive assessment tool reimbursement. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration across primary interview phases. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down health system expenditure analysis enabled triangulation across data sources.
Scenario-bracketing framed analytical approach across the projection horizon, with sensitivity testing on biomarker adoption curves and infusion site capacity constraints. Segmentation dimensions modeled included treatment line, diagnostic confirmation modality, administration route, and regional regulatory cluster. CAGRs derived from patient volume projections multiplied by evolving reimbursement rates, with specific inputs for PMDA Sakigake designation impact and EMA conditional marketing authorization timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by blood-based diagnostic pure-plays or digital health platform entrants would shift outcomes substantially. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Diabetes Testing System Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market