
 Brazil in Vitro Diagnostics Market | 2026-2036
Brazil in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil in Vitro Diagnostics Market Outlook
Trained clinical laboratory technologist availability is collapsing across Brazil's interior states, forcing diagnostic networks to deploy automated immunoassay and molecular platforms that reduce manual processing steps. Roche Diagnostics leverages its installed base of cobas systems to sustain service contracts in major metropolitan hospitals. bioMérieux anchors its position through specialized microbiology and blood culture workflows that differentiate its portfolio from generalist competitors. Diagnosticos da America competes on geographic coverage, operating one of Brazil's largest independent laboratory networks.
In vitro diagnostics encompasses reagents, instruments, and systems used to analyze biological specimens—blood, urine, tissue—outside the living organism, typically requiring sample volumes between 10 microliters and 10 milliliters depending on assay complexity. These technologies enable disease screening, treatment monitoring, and therapeutic decision-making across clinical settings. Immunoassays occupy the largest revenue pool in Brazil's current landscape, reflecting established infrastructure for infectious disease and metabolic testing. Molecular diagnostics represents the fastest-expanding segment, propelled by oncology and genetic testing applications where next-generation sequencing and polymerase chain reaction platforms command premium pricing. Hematology remains mature, with replacement cycles driving modest growth in automated cell counters.
ANVISA governs medical device registration and quality standards for diagnostic products entering Brazil, while the country's national health surveillance system enforces post-market vigilance requirements that shape supplier compliance investments. The Brazilian Ministry of Health's diagnostic reimbursement frameworks directly influence purchasing decisions at public hospitals and contracted laboratories. Stakeholders must monitor how ANVISA's alignment with international harmonization initiatives affects registration pathways and competitive entry timelines for novel platforms.
Market Dynamics
Automated platform deployment is compressing manual processing workflows across Brazil's diagnostic networks, as laboratory technologist shortages in interior states force capital-intensive retooling of testing infrastructure.
Growth Catalysts
- ANVISA harmonization initiatives:Accelerated quality certification timelines for imported reagents reduce supplier entry barriers and expand platform availability for private hospital networks.
- Molecular diagnostics expansion:Oncology and genetic testing applications in São Paulo and Rio de Janeiro drive PCR and next-generation sequencing platform adoption.
- Aging population screening protocols:Expanded metabolic and infectious disease testing mandates from Brazil's Ministry of Health sustain immunoassay volume growth in public laboratories.
Market Restraints
- Import-dependent reagent supply:Currency volatility elevates landed costs for diagnostic consumables, compressing margins at independent laboratory networks.
- Specialized technologist scarcity:Trained clinical laboratory personnel collapse across Brazil's interior states limits manual assay expansion regardless of equipment availability.
- Replacement cycle maturity:Automated cell counter installed base in hematology approaches saturation, constraining new instrument revenue.
Strategic Opportunities
- Northeast and North region penetration:Underdeveloped diagnostic infrastructure in Amazonas and Bahia creates whitespace for automated platform deployment with reduced competitive density.
- Point-of-care molecular integration:Convergence of portable PCR systems with cloud-based result reporting enables decentralized testing outside metropolitan hospital networks.
- Service contract unbundling:After-sales technical support and reagent supply separation creates new channel structures for specialized distributors.
Industry Challenges
- ANVISA post-market vigilance compliance:National health surveillance system reporting requirements demand dedicated regulatory affairs capacity that strains mid-scale supplier operations.
- Legacy system integration friction:Automated platform deployment requires LIS connectivity with existing hospital information systems, extending implementation timelines.
- Capex intensity for full automation:Walk-away molecular and immunoassay systems require substantial upfront investment that public procurement cycles struggle to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil in Vitro Diagnostics Market |
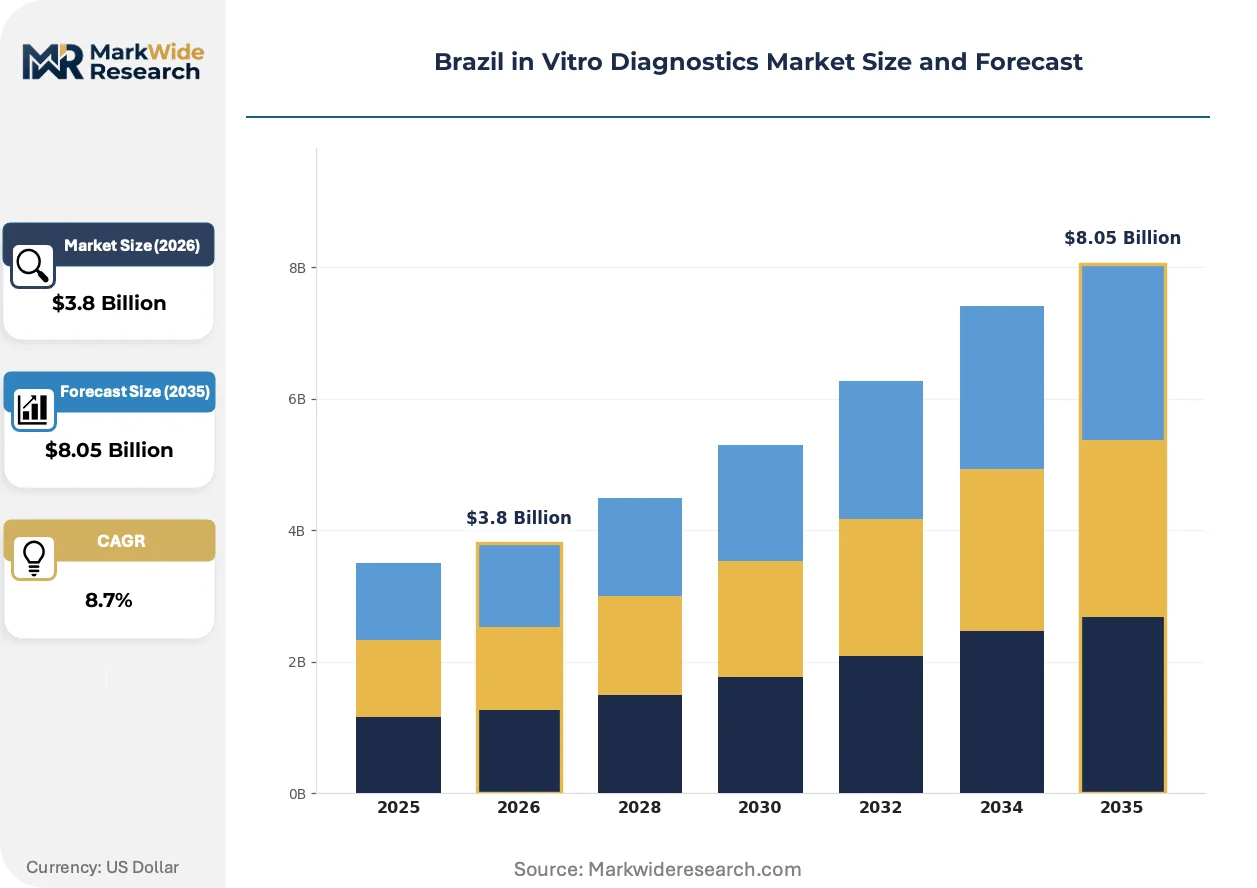
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Chemistry, Immunoassays, Molecular Diagnostics, Hematology Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing, Microfluidics End User: Hospitals, Diagnostics Laboratories, Research Institutions, Home Care Application: Infectious Diseases, Oncology, Metabolic Disorders, Genetic Testing |
| Companies Covered | Roche Diagnostics, bioMérieux, Becton, Dickinson and Company, Bio-Rad Laboratories Inc., Danaher Corporation, Siemens Healthineers, Abbott Laboratories, Sysmex Corporation, Diagnosticos da America (DASA), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil in Vitro Diagnostics Market Strategic Shifts
Platform miniaturization and regulatory pathway streamlining are restructuring competitive entry patterns, while procurement behavior shifts favor integrated service relationships over transactional reagent purchasing.
Next-generation sequencing workflows are supplanting single-gene PCR panels in oncology companion diagnostic applications. Private hospital networks in Brazil's Southeast region are adopting these platforms at accelerated pace. This technology shift is compressing turnaround times for mutational profiling while elevating capital requirements for competitive participation.
ANVISA's updated medical device regulations align registration pathways with international harmonization standards, reducing redundant documentation for established suppliers. This regulatory convergence compresses time-to-market for novel platforms. Molecular diagnostics segments respond fastest, leveraging prior FDA or EMA submissions to accelerate Brazilian approval.
Consolidated purchasing by diagnostic laboratory networks is displacing fragmented hospital-level procurement. Independent laboratory chains now negotiate enterprise reagent and service agreements directly with manufacturers. This concentration is most visible in São Paulo, where multi-site networks command volume-based pricing structures previously unavailable to standalone facilities.
Brazil in Vitro Diagnostics Market Segmentation
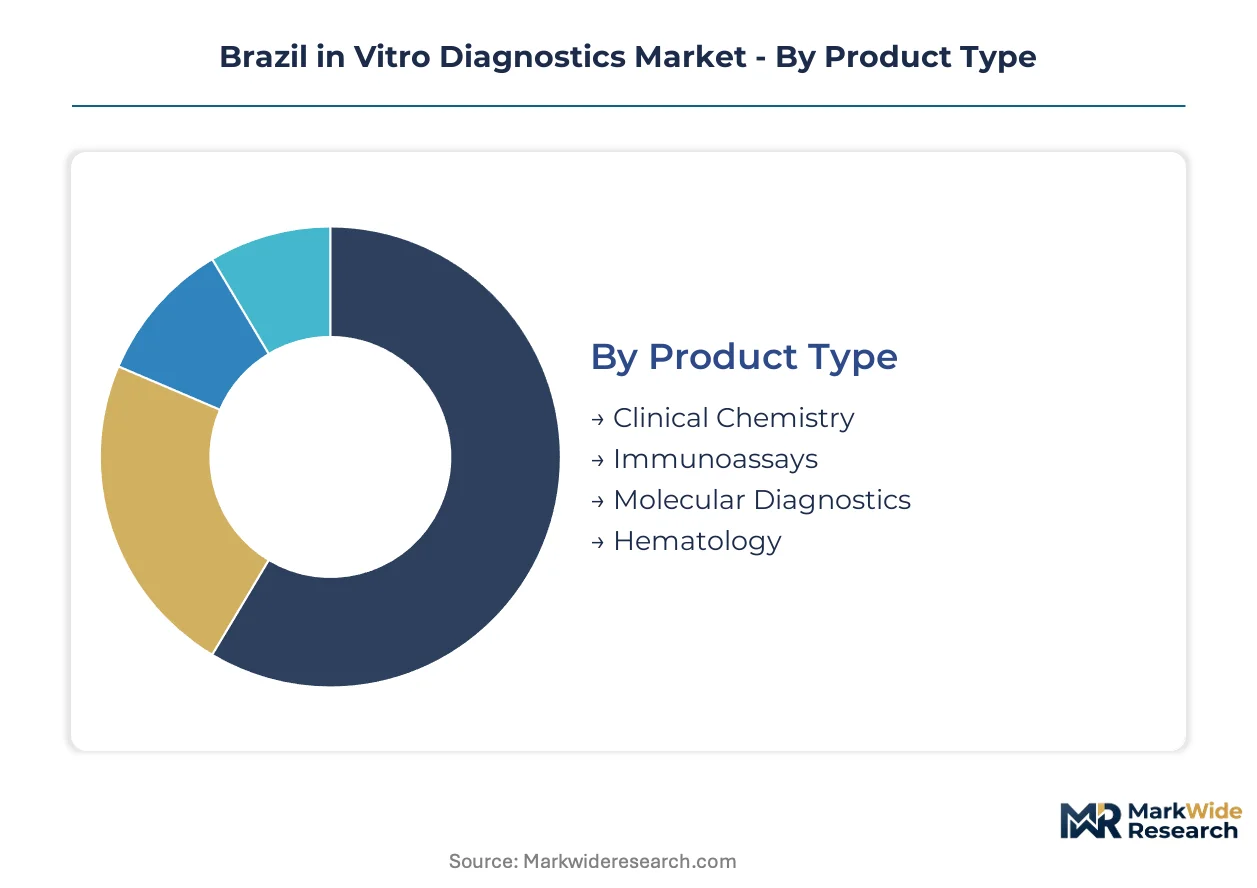
Segmentation reveals how diagnostic demand fragments across testing modalities, procurement channels, and care settings. Understanding these divides exposes where capital flows concentrate and where automation investments yield highest returns for laboratory networks and hospital systems.
Product Type:
Channel mix varies sharply by product category: immunoassays and clinical chemistry flow heavily through public laboratory tenders, while molecular diagnostics concentrate in private hospital capital budgets and research institution grants.
- Clinical Chemistry:Automated analyzers process electrolyte, enzyme, and metabolite panels on serum and plasma specimens. Demand concentrates in São Paulo and Rio de Janeiro diagnostic networks serving aging populations with diabetes and cardiovascular monitoring protocols.
- Immunoassays:Antibody-antigen detection systems dominate infectious disease and hormone testing workflows. Public health laboratories in Brazil's Southeast region drive procurement volume through Ministry of Health screening mandates for HIV, hepatitis, and prenatal panels.
- Molecular Diagnostics:Nucleic acid amplification and detection platforms command premium positioning in oncology and genetic applications.
- Hematology:Automated cell counters and coagulation analyzers support routine blood panel processing in high-throughput hospital laboratories.
By volume, immunoassays lead. By growth pace, molecular diagnostics is climbing the fastest.
Technology:
Cost tier separation is pronounced: ELISA and conventional PCR occupy mid-market positioning, while next-generation sequencing and microfluidics platforms target premium segments with specialized reimbursement pathways.
- Polymerase Chain Reaction:Thermal cycling amplification enables pathogen detection and genetic variant identification with high analytical sensitivity. Private hospital networks in Brazil's Southeast deploy PCR platforms for rapid infectious disease diagnostics and oncology companion testing.
- Next-Generation Sequencing:Massively parallel sequencing architectures generate comprehensive genomic profiles from minimal input DNA. Research institutions and specialized cancer centers in São Paulo drive adoption for tumor mutational burden assessment and hereditary cancer screening programs.
- Enzyme-Linked Immunosorbent Assay:Colorimetric antibody detection remains the workhorse for high-volume serological screening in resource-constrained settings.
- Microfluidics:Lab-on-chip miniaturization reduces reagent consumption and sample volumes for point-of-care deployment.
PCR commands the largest installed base. Next-generation sequencing shows the steepest expansion trajectory.
End User:
Customer type determines procurement rhythm: hospitals execute capital-intensive automation projects on multi-year cycles, while diagnostic laboratories negotiate enterprise reagent contracts with volume-tiered pricing.
- Hospitals:Integrated health systems combine inpatient, emergency, and outpatient testing under centralized laboratory medicine departments. Large private networks in São Paulo and Rio de Janeiro prioritize walk-away automation to offset technologist shortages.
- Diagnostics Laboratories:Independent chains and hospital-affiliated reference labs process high specimen volumes for contracted health plans. Diagnosticos da America and similar networks leverage geographic scale to negotiate direct manufacturer relationships bypassing traditional distribution.
- Research Institutions:Academic medical centers and biotechnology incubators deploy cutting-edge platforms for translational studies and clinical trial support.
- Home Care:Self-testing devices and remote sample collection services expand access outside traditional facility-based settings.
Diagnostics laboratories generate the highest reagent throughput. Home care is gaining share fastest as decentralized testing models mature.
Application:
Maturity gradients separate applications: infectious disease and metabolic testing rely on established immunoassay infrastructure, while oncology and genetic testing drive molecular platform refresh cycles.
- Infectious Diseases:HIV, hepatitis, tuberculosis, and respiratory pathogen detection constitute the historical revenue foundation for Brazilian IVD suppliers. Public health programs sustain volume through Ministry of Health procurement frameworks and ANVISA-mandated screening protocols.
- Oncology:Companion diagnostic testing for targeted therapeutics requires sophisticated mutational profiling capabilities. Private oncology centers in Brazil's Southeast region invest in next-generation sequencing to support precision medicine programs and clinical trial enrollment.
- Metabolic Disorders:Diabetes, thyroid dysfunction, and cardiovascular risk marker testing support chronic disease management in primary care networks.
- Genetic Testing:Prenatal screening, pharmacogenomics, and rare disease diagnosis expand as reimbursement frameworks evolve for personalized medicine applications.
Infectious diseases anchors current volume. Oncology is expanding most quickly as companion diagnostic linkages deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's regulatory framework shapes diagnostic infrastructure investment across Brazil's federative units, with regional disparities in laboratory automation and technologist availability driving divergent platform deployment patterns.
São Paulo
Private hospital networks in São Paulo deploy PCR and next-generation sequencing platforms for oncology companion diagnostics. The state's aging population sustains demand for metabolic and cardiovascular testing through Ministry of Health screening protocols. Diagnostic laboratory chains concentrate in Greater São Paulo, negotiating direct manufacturer relationships that bypass traditional distribution channels.
Rio de Janeiro
Rio de Janeiro's diagnostic laboratories expand automated immunoassay capacity to serve contracted health plans and public hospital networks. ANVISA's harmonized registration pathways accelerate quality certification for imported reagents entering through the state's port infrastructure. Research institutions in the city drive adoption of tumor mutational burden assessment platforms for precision medicine programs.
Minas Gerais
Belo Horizonte anchors diagnostic demand in Minas Gerais through university-affiliated hospital systems that process high specimen volumes for chronic disease management. The state's interior regions face acute technologist shortages, forcing laboratory networks toward walk-away automation that reduces manual processing steps. Public procurement cycles for hematology analyzers remain extended due to budget constraints.
Rio Grande do Sul
Porto Alegre's integrated health systems combine inpatient and outpatient testing under centralized laboratory medicine departments. Currency volatility elevates landed costs for diagnostic consumables, compressing margins at independent laboratory networks serving the state's southern border region. Automated cell counter replacement cycles approach saturation in mature hospital laboratories.
Bahia
Salvador's diagnostic infrastructure remains underdeveloped relative to Southeast Brazil, creating whitespace for automated platform deployment with reduced competitive density. The Northeast region's infectious disease burden sustains demand for HIV and hepatitis screening through Ministry of Health procurement frameworks. Point-of-care molecular integration opportunities emerge as portable PCR systems converge with cloud-based result reporting capabilities.
Brazil in Vitro Diagnostics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Brazil's diagnostic market. Multinational conglomerates with diversified life sciences portfolios occupy the upper tier, leveraging installed instrument bases to sustain long-term service contracts. The specialist tier comprises microbiology-focused firms and independent laboratory networks that compete on workflow differentiation or geographic coverage. Competitive moves center on enterprise reagent agreements and automated platform refresh cycles that displace legacy systems.
Within the integrated multinational tier, Roche Diagnostics and bioMérieux occupy positions anchored by established instrument footprints in major metropolitan hospitals. Roche leverages its cobas installed base across São Paulo and Rio de Janeiro networks, while bioMérieux exemplifies the microbiology specialist archetype through blood culture and infectious disease workflows. Diagnosticos da America represents the independent laboratory network model, competing on geographic scale rather than manufacturing integration.
| Leading Market Players |
|---|
| Roche Diagnostics |
| bioMérieux |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| Danaher Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Sysmex Corporation |
| Diagnosticos da America (DASA) |
| Others |
Value Chain & Pricing Dynamics
Automated platform substitution for manual immunoassay workflows simultaneously concentrates supply relationships with multinational instrument manufacturers and compresses reagent pricing power among independent Brazilian distributors. This dual restructuring elevates capital expenditure requirements for laboratory networks while fragmenting procurement leverage across interior states with limited vendor alternatives.
Pricing Analysis
São Paulo and Rio de Janeiro command 15-25% pricing premiums over Amazonas and Bahia for equivalent molecular diagnostic platforms, reflecting freight logistics and technical service density. Three-tier pricing structure across premium, standard, and economy levels separates next-generation sequencing systems from conventional PCR workstations and refurbished immunoassay analyzers. Cost compression in economy-tier hematology replacement cycles is intensifying because public procurement budgets face currency-adjusted import cost escalation. Independent diagnostic laboratories exhibit highest price sensitivity, while private hospital networks absorbing capital depreciation prioritize throughput reliability over per-test economics.
Supply Chain Analysis
United States, Germany, and Japan anchor diagnostic instrument manufacturing, shipping automated analyzers and molecular platforms through São Paulo's port infrastructure. Reagent production draws from Switzerland, France, and Singapore, with lyophilized enzyme formulations and monoclonal antibody conjugates constituting critical input dependencies. Single-source vulnerability concentrates in proprietary consumables locked to specific instrument footprints, constraining laboratory switching costs. Distribution runs through authorized distributor networks maintaining cold-chain integrity for temperature-sensitive reagents, with direct manufacturer relationships penetrating only the largest multi-site laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's IVD sector sits at an inflection where ANVISA's regulatory harmonization with FDA and EMA standards accelerates novel platform entry timelines, compressing competitive moats for legacy installed-base defenders.
For Market Incumbents: Fortify service contract stickiness by embedding predictive maintenance algorithms and remote technical support capabilities that raise switching costs for automated platform users. Deepen backward integration into reagent manufacturing to offset currency-driven import cost volatility threatening margin stability at independent laboratory accounts.
For New Entrants and Emerging Players: Anchor in Bahia and Amazonas where diagnostic infrastructure underdevelopment creates whitespace for portable PCR and point-of-care molecular systems with reduced incumbent competitive density. Pursue cloud-integrated result reporting partnerships with regional health secretariats as the primary go-to-market angle for decentralized testing adoption.
For Investors and Strategic Acquirers: ANVISA's alignment with international harmonization standards reshapes the acquisition landscape by elevating regulatory affairs capabilities as a scarce asset class. Target independent laboratory networks with established Ministry of Health contracting relationships and interior-state geographic coverage. Monitor post-market vigilance compliance cost escalation as the signal indicating margin pressure on mid-scale suppliers and forced consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Registration | Accelerated quality certification for imported reagents compresses competitive entry timelines against legacy suppliers. |
| Automated Platform Deployment | Walk-away immunoassay and molecular systems reduce manual processing steps in technologist-scarce interior states. |
| Direct Manufacturer Contracting | Multi-site laboratory networks bypass traditional distribution to negotiate volume-tiered reagent pricing structures. |
| Point-of-Care Molecular Integration | Portable PCR systems with cloud-based reporting enable decentralized testing outside metropolitan hospital networks. |
| Service Contract Unbundling | Separation of technical support from reagent supply creates specialized distributor channel structures. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with diagnostic laboratory directors, hospital biomedical engineers, ANVISA regulatory affairs specialists, and GPO contracts managers; and secondary validation against ANVISA registration databases, Ministry of Health procurement records, and customs import declarations for diagnostic instruments. Bottom-up triangulation aggregated instrument installation data and reagent consumption patterns, while top-down cross-checks applied macroeconomic drivers to regional healthcare expenditure trends.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology platform, end-user category, and application area, with regional regulatory clusters capturing ANVISA harmonization progression. CAGRs derived from historical volume trajectories adjusted for technologist availability constraints and public procurement cycle timing. Forecast inputs incorporated currency volatility assumptions for reagent import costs and capital expenditure elasticity at private hospital networks.
Underlying assumptions cover ANVISA regulatory pathway stability and Ministry of Health screening protocol continuity, with deviation risk concentrated in currency depreciation accelerating import cost inflation and technologist training pipeline collapse in northern states. Recalibration cycles align with material shifts in ANVISA harmonization implementation and federal diagnostic reimbursement framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Microdialysis Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Cervical Cancer Diagnostic Tests Market