
 Blood Testing Devices Market | 2026-2036
Blood Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Testing Devices Market Analytics
The capital-intensity divergence between fully automated hematology platforms and single-use portable strips is redrawing competitive boundaries in blood testing. Becton Dickinson leverages integrated specimen-handling architectures to sustain premium positioning in high-throughput laboratories. Abbott Laboratories anchors its presence through electrochemical glucose-sensing leadership across both clinical and consumer channels. Roche Diagnostics differentiates via immunoassay depth, particularly in coagulation and infectious disease panels.
Blood testing devices comprise analytical instruments and consumables that quantify cellular, biochemical, or molecular parameters from venous, capillary, or arterial samples using electrochemical, optical, or nucleic-acid detection principles, serving diagnostic screening and therapeutic monitoring functions. Hematology analyzers represent the most mature revenue pool, while portable testing devices capture the fastest structural expansion as CLIA-waived and over-the-counter pathways broaden addressable settings. The technology dimension shows electrochemical methods dominating glucose and basic metabolic panels, whereas nucleic-acid platforms command superior margins in infectious disease and pharmacogenomic applications.
FDA premarket notification and CLIA complexity categorization govern United States market access, with the EPA regulating device manufacturing waste streams and OSHA mandating bloodborne pathogen controls in clinical environments. The EU MDR and IVDR frameworks impose stricter clinical evidence requirements on European entrants, lengthening certification timelines. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring and home-based testing as payors recalibrate coverage toward decentralized care models.
Market Dynamics
CLIA waiver expansion and FDA clearance pathway acceleration are compressing time-to-market for point-of-care blood testing platforms, redistributing competitive advantage from centralized laboratory incumbents toward portable device specialists.
Growth Catalysts
- Home Care Decentralization:Patient preference for at-home diagnostics is pulling testing capacity from hospitals into residential settings, expanding addressable volume for CLIA-waived devices.
- IRA Reimbursement Adjustments:Medicare coverage expansion for remote patient monitoring is creating payment certainty for connected glucose and coagulation meters in the United States.
- Electrochemical Sensor Miniaturization:Advances in enzyme electrode stability are enabling single-use strip performance comparable to benchtop analyzers for basic metabolic panels.
Market Restraints
- Precious Metal Input Volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress margin predictability for strip manufacturers.
- EU IVDR Clinical Evidence Burden:Stricter performance validation requirements under the In Vitro Diagnostic Regulation are extending certification timelines for European market entry.
- Optical Platform Substitution:Photometric methods in emerging hematology analyzers threaten electrochemical dominance in certain parameter categories.
Strategic Opportunities
- Pharmacogenomic Testing White Space:Nucleic-acid blood platforms for drug-gene interaction screening remain underpenetrated in outpatient cardiology and psychiatry practices.
- India PLI Scheme Leverage:Production-linked incentives for medical device manufacturing offer cost advantages for export-oriented assembly operations.
- Retail Pharmacy Channel Integration:MinuteClinic-style embedded diagnostics in pharmacy chains create new high-frequency touchpoints for preventive screening panels.
Industry Challenges
- Multi-Omic Data Integration Complexity:Combining hematology, biochemistry, and molecular outputs into unified clinical decision support requires scarce bioinformatics talent.
- Legacy LIS Interoperability Friction:Hospital laboratory information systems built on HL7 v2 standards resist seamless integration with cloud-connected point-of-care devices.
- ISO 15189 Accreditation Timeline Compression:Accelerated facility certification demands are straining quality management system implementation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Testing Devices Market |
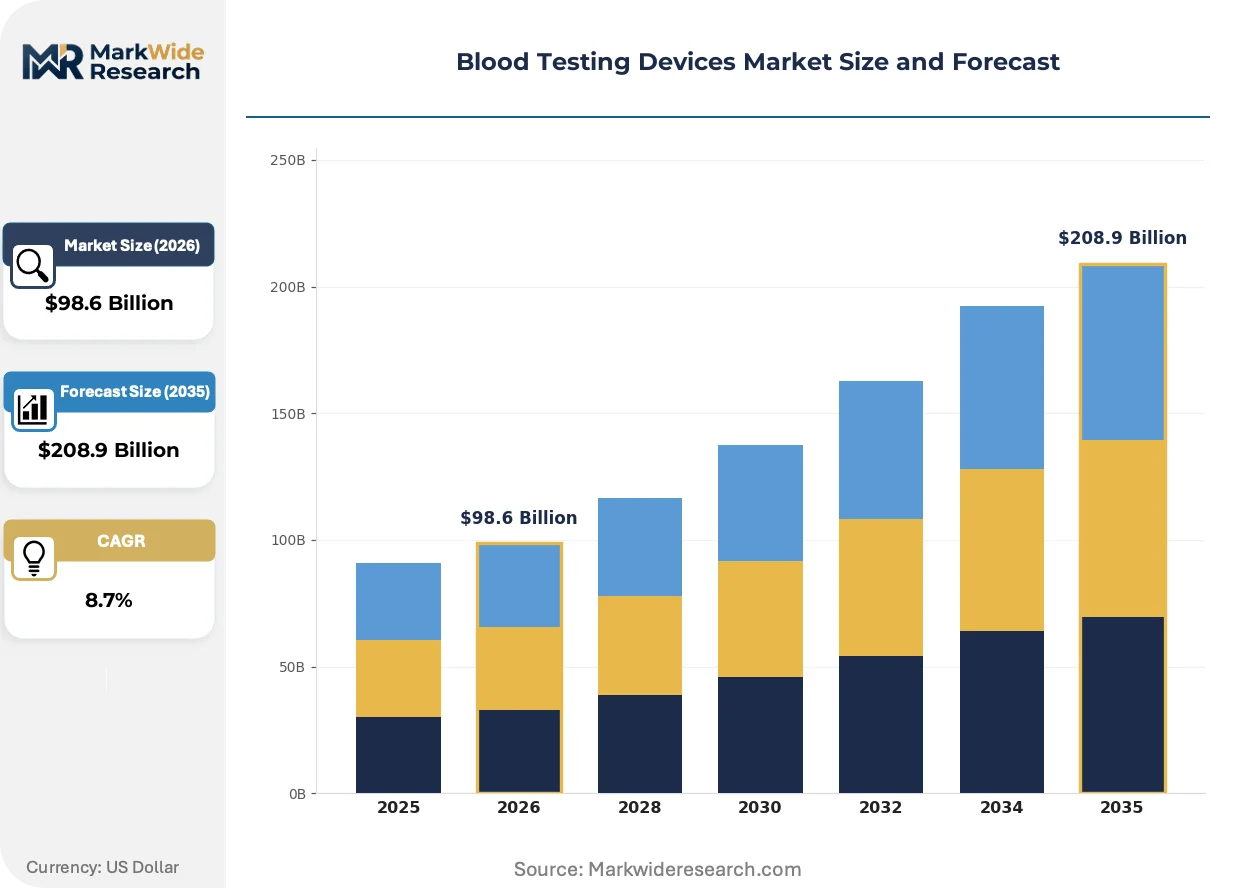
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzers, Glucose Meters, Coagulation Testers, Portable Testing Devices Technology: Electrochemical, Optical, Immunoassay, Nucleic Acid End User: Hospitals, Clinics, Home Care, Laboratories Application: Chronic Disease Management, Infectious Disease Testing, Blood Typing, Routine Screening |
| Companies Covered | Becton Dickinson, Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Danaher Corporation, Quest Diagnostics, Bio-Rad Laboratories, Greiner Bio-One, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Testing Devices Market Evolving Landscape
Microfluidic cartridge architectures and smartphone-integrated readout systems are collapsing the cost and skill barriers that historically separated consumer-grade from clinical-grade blood testing.
Lab-on-a-chip microfluidics is fragmenting the traditional hematology analyzer market by embedding cell-counting optics and impedance sensors into credit-card-sized disposable cartridges. Community health clinics and ambulatory surgery centers are adopting these platforms at twice the pace of hospital laboratories. The technology is fragmenting equipment purchasing decisions, shifting capital allocation from six-figure benchtop systems toward high-margin consumable contracts.
EU MDR and IVDR convergence is tightening post-market surveillance obligations for blood testing device manufacturers serving European markets. Manufacturers must now maintain active clinical follow-up registries for Class C and D devices, elevating compliance infrastructure costs. Hematology and coagulation panel suppliers are responding by consolidating European authorized representative functions and pre-positioning PMCF study protocols.
Hospital procurement committees are unbundling analyzer placement contracts from exclusive reagent supply agreements, enabling multi-vendor consumable sourcing. Integrated delivery networks in the United States are driving this shift, using volume aggregation to extract price transparency on per-test costs. The unbundling is most visible in the Midwest and Southeast IDN consolidation corridors, where centralized laboratory governance overrides individual hospital preferences.
Blood Testing Devices Market Segmentation
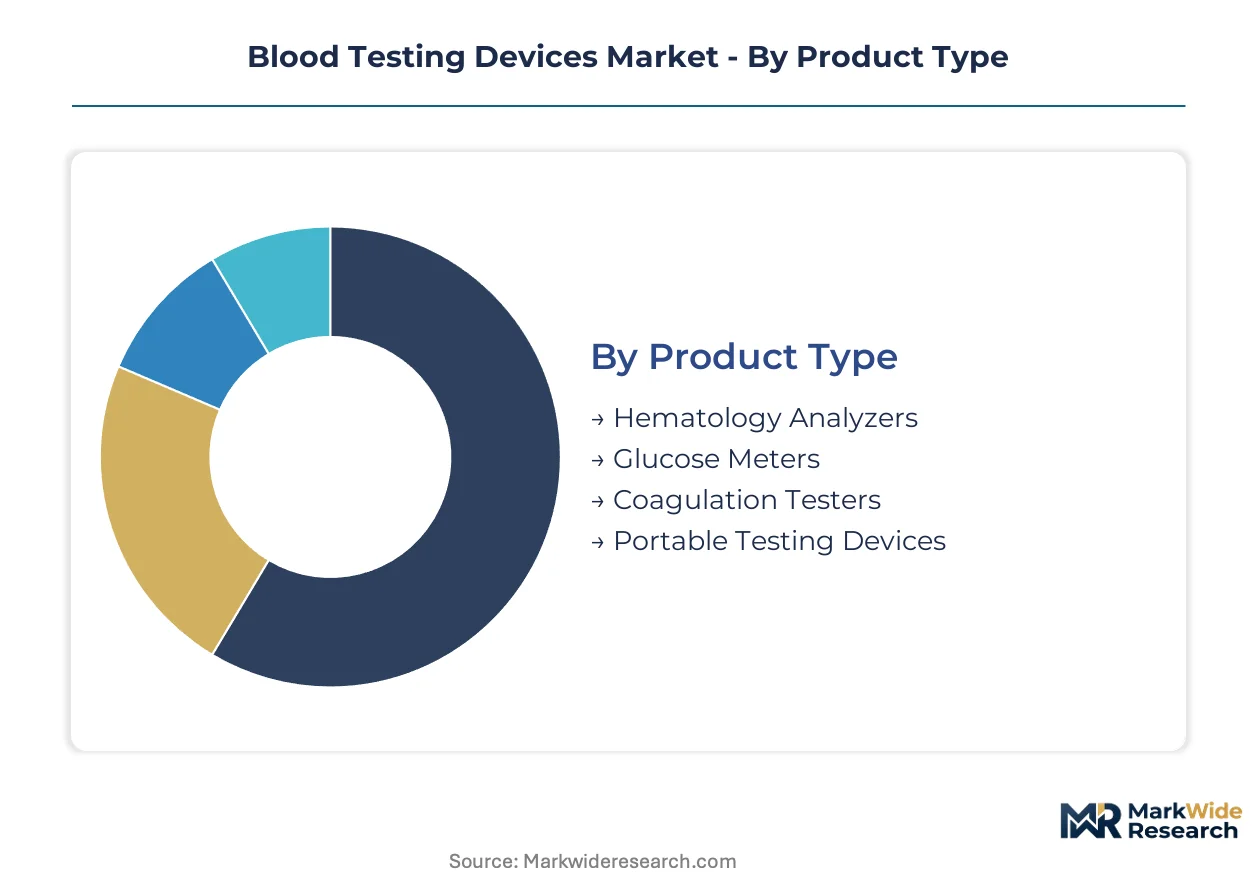
Segmentation in blood testing devices determines channel strategy, regulatory pathway selection, and margin architecture. Product type dictates capital intensity, while technology choice shapes reimbursement eligibility and geographic expansion feasibility.
Product Type:
Hospital procurement committees and retail pharmacy chains source through fundamentally different commercial models, with capital equipment flowing through GPO-negotiated contracts and portable devices penetrating via retail distribution.
- Hematology Analyzers:Benchtop systems integrate impedance-based cell counting with flow cytometry for complete blood count differentiation. Demand concentrates in United States hospital laboratories where integrated delivery networks aggregate purchasing volume, constrained by extended replacement cycles stretching toward decade-long intervals.
- Glucose Meters:Electrochemical enzyme electrode platforms dominate both prescription and over-the-counter channels. United States Medicare reimbursement for continuous glucose monitor alternatives drives volume in endocrinology practices and home care settings, with pharmacy benefit managers exerting pricing pressure on strip formularies.
- Coagulation Testers:Point-of-care INR monitoring devices serve anticoagulation clinics and cardiology practices.
- Portable Testing Devices:CLIA-waived platforms expand into ambulatory surgery centers and community health clinics.
By volume, glucose meters lead. By growth pace, portable testing devices are climbing the fastest.
Technology:
Cost tiers separate premium nucleic-acid platforms from commodity electrochemical strips, with optical methods occupying a mid-tier position in hematology automation.
- Electrochemical:Enzyme electrode and amperometric detection principles underpin glucose, lactate, and basic metabolic panel quantification. Home care and retail pharmacy channels absorb the majority of strip volume, with FDA CLIA waiver pathways accelerating placement in non-laboratory settings.
- Optical:Photometric and laser-scattering architectures enable hematology cell counting and coagulation endpoint detection. Hospital laboratories in the United States Midwest and Southeast consolidation corridors favor these platforms for throughput reliability.
- Immunoassay:Chemiluminescence and fluorescence methods target cardiac marker and infectious disease panels.
- Nucleic Acid:PCR and isothermal amplification platforms command premium pricing for pharmacogenomic and virology applications.
Electrochemical methods dominate unit shipments. Nucleic acid platforms capture the steepest expansion trajectory in outpatient cardiology.
End User:
Application urgency and reimbursement density vary sharply across settings, with acute care demanding rapid turnaround and home care prioritizing connectivity and simplicity.
- Hospitals:Emergency departments and intensive care units require STAT-capable analyzers with full parameter menus. United States academic medical centers drive demand for multi-omic integration, though legacy laboratory information system interoperability creates implementation friction.
- Home Care:Patients with diabetes, anticoagulation therapy, or chronic kidney disease operate connected meters with cloud data transmission. IRA reimbursement adjustments in the United States are expanding Medicare coverage for remote patient monitoring, validating this channel's commercial viability.
- Clinics:Federally qualified health centers and urgent care chains adopt CLIA-waived platforms for same-visit diagnosis.
- Laboratories:Reference laboratories and hospital core labs sustain demand for high-throughput automation.
Hospitals retain the largest installed base. Home care is gaining share fastest as decentralized models mature.
Application:
Customer type segmentation reveals divergent purchasing authority, with physicians driving infectious disease testing decisions and patients self-directing chronic disease monitoring.
- Chronic Disease Management:Diabetes, cardiovascular disease, and chronic kidney disease require longitudinal biomarker tracking. United States endocrinology and nephrology practices are embedding point-of-care testing to reduce referral leakage, with capitated payment models rewarding in-house diagnostic capacity.
- Infectious Disease Testing:HIV, hepatitis, and respiratory pathogen panels demand nucleic-acid sensitivity thresholds. Public health laboratories and community health clinics in the United States absorb volume through CDC and HRSA funding streams, with EU IVDR clinical evidence requirements constraining European market entry for novel assays.
- Blood Typing:Transfusion services and surgical pre-admission testing sustain demand for serologic and molecular methods.
- Routine Screening:Wellness panels and preventive chemistry drive volume in occupational health and retail pharmacy settings.
Chronic disease management leads by test frequency. Infectious disease testing is expanding most quickly as pandemic preparedness funding persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in blood testing devices tilt toward deficit positions in high-demand medical device markets, with manufacturing capacity concentrated in Germany, China, and the United States while import dependency persists across emerging diagnostic markets.
United States
Medicare reimbursement expansion for remote patient monitoring and IRA provisions for chronic disease management drive domestic device absorption. FDA CLIA waiver pathways accelerate point-of-care platform approvals, compressing regulatory timelines for portable hematology and glucose systems. The Research Triangle Park cluster in North Carolina hosts contract manufacturing operations serving East Coast integrated delivery networks.
Germany
Precision engineering demand from hospital laboratory automation sustains analyzer component exports. EU IVDR clinical evidence requirements and MDR post-market surveillance obligations extend certification timelines for European market entrants. The Baden-Württemberg medical technology corridor around Stuttgart concentrates electrochemical sensor fabrication and microfluidic cartridge assembly.
China
Domestic substitution policies under the 14th Five-Year Plan prioritize nucleic-acid platform localization for infectious disease panels. NMPA regulatory harmonization with international standards accelerates approval pathways for imported hematology analyzers. The Suzhou Industrial Park biotech zone attracts foreign joint ventures for blood testing device manufacturing serving Asia-Pacific distribution.
India
Production-linked incentive schemes for medical device manufacturing reduce import dependency for glucose meter and strip assembly. CDSCO regulatory streamlining for Class B and C devices shortens market entry timelines for multinational point-of-care platforms. The Maharashtra medical device cluster near Mumbai hosts contract electronics manufacturing for electrochemical sensor electrode production.
Japan
Aging demographic pressure and chronic disease prevalence sustain demand for home-based coagulation and glucose monitoring systems. PMDA quality management system requirements and JIS standards compliance elevate barriers for non-domestic hematology analyzer suppliers. The Kansai medical device manufacturing belt around Osaka specializes in optical component fabrication for cell-counting platforms.
Blood Testing Devices Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates commanding integrated specimen-handling architectures and electrochemical sensing leadership. The vendor base stratifies across three tiers: multinational platform specialists with full hematology-to-molecular portfolios, mid-scale regional manufacturers focused on CLIA-waived portable devices, and contract electronics assemblers serving private-label strip production. Consolidation pressure manifests through strategic partnerships between microfluidic technology developers and established distribution networks, while geographic expansion into India's PLI-subsidized manufacturing zones represents a dominant capacity relocation pattern.
Among the diversified diagnostics conglomerates, Becton Dickinson and Roche Diagnostics exemplify platform breadth across laboratory and point-of-care settings. Abbott Laboratories anchors the electrochemical sensing tier with glucose monitoring leadership spanning clinical and consumer channels. Siemens Healthineers occupies a position in imaging-integrated diagnostics workflows, while Danaher Corporation represents the life sciences tools-to-diagnostics convergence archetype through portfolio assembly across analytical instrumentation.
| Leading Market Players |
|---|
| Becton Dickinson |
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher Corporation |
| Quest Diagnostics |
| Bio-Rad Laboratories |
| Greiner Bio-One |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Long-term reagent supply contracts lock in both consumable access and per-test cost visibility for United States integrated delivery networks negotiating with hematology analyzer vendors. These arrangements transfer platinum and palladium price volatility from hospital procurement committees to manufacturers, compressing margin predictability for electrochemical strip producers while securing volume commitments for glucose meter deployments.
Pricing Analysis
Industrial OEM buyers anchor consumable bundling structures across United States hospital procurement. Pricing stratifies across premium, standard, and economy tiers based on CLIA complexity categorization and throughput capacity. Cost compression in economy-grade strips is intensifying because pharmacy benefit managers exert formulary pressure on glucose monitoring supplies. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize STAT capability over unit economics.
Supply Chain Analysis
Germany and China anchor precision component fabrication for hematology analyzers and electrochemical sensor electrodes. Manufacturing draws from platinum group metals for enzyme electrodes, optical-grade plastics for microfluidic cartridges, and semiconductor substrates for signal processing chips. Single-source vulnerability concentrates in rare earth refining for magnetic cell separation modules. Distribution runs through GPO-negotiated contracts for hospital laboratories and retail pharmacy chains for over-the-counter devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
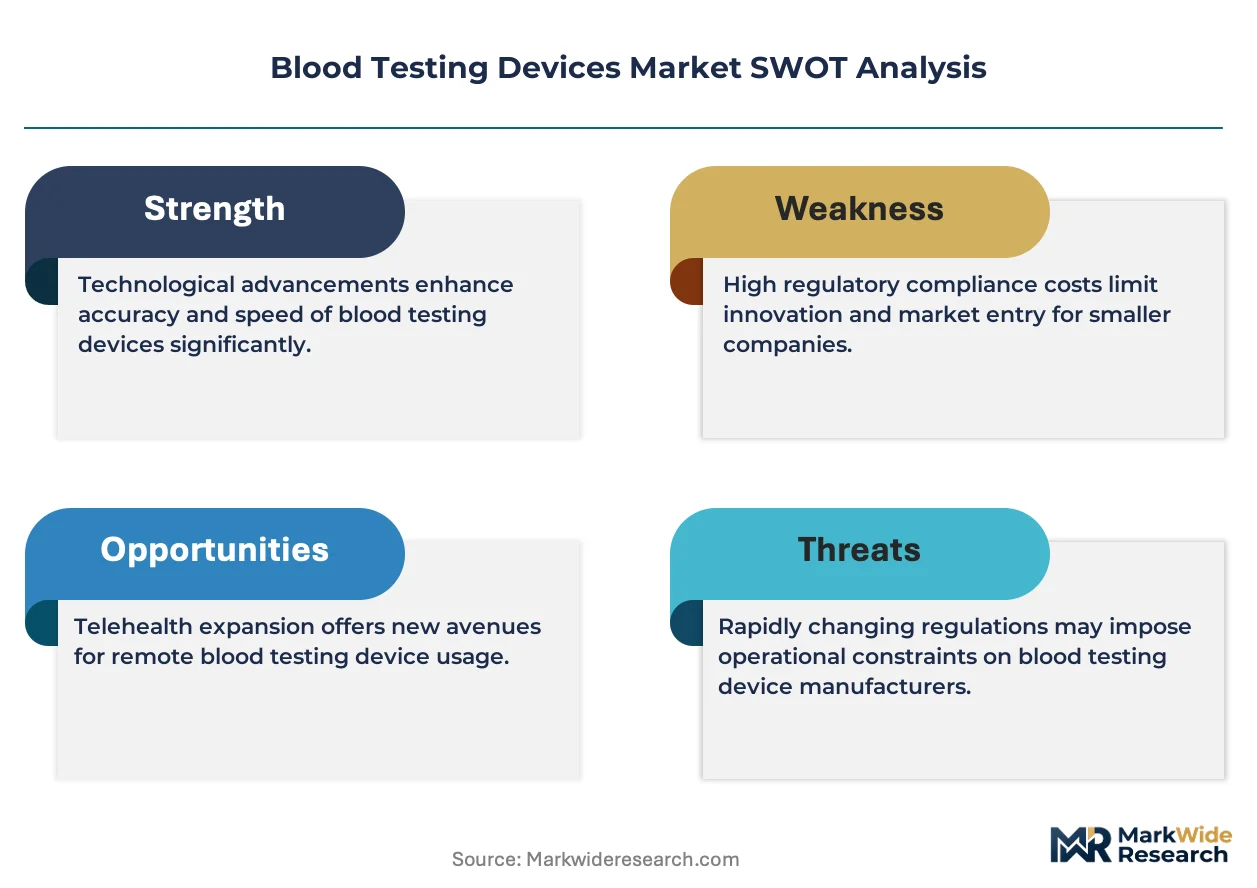
Blood testing devices sit in early-cycle expansion as CLIA waiver pathways and IRA reimbursement adjustments validate decentralized diagnostic models beyond traditional laboratory settings.
For Market Incumbents: Fortify installed base retention through backward integration into electrochemical sensor electrode production, capturing margin otherwise lost to precious metal volatility. Accelerate ISO 15189 accreditation support services for hospital laboratory clients facing compressed certification timelines. Defensive positioning must counter optical platform substitution threats in emerging hematology analyzers. For New Entrants and Emerging Players: Differentiate on pharmacogenomic testing integration for outpatient cardiology practices, where nucleic-acid platforms remain underpenetrated. Target India's PLI-subsidized manufacturing zones for export-oriented glucose strip assembly. Embed within retail pharmacy diagnostic footprints through MinuteClinic-style partnerships, capturing high-frequency preventive screening volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CLIA-waived portable device specialists with cloud-connected meter ecosystems. Long-term viability favors platforms spanning both clinical-grade certification and consumer channel penetration. Acquisition focus should center on microfluidic cartridge developers with FDA pre-submission pathways. Monitor NMPA regulatory harmonization progress as inflection signal for China market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Expansion | FDA pathway acceleration compresses time-to-market for point-of-care platforms entering ambulatory settings. |
| Reimbursement Strategy Development | IRA Medicare coverage adjustments create payment certainty for connected glucose and coagulation meters. |
| Backward Integration | In-house platinum group metal electrode production insulates strip manufacturers from commodity price swings. |
| Hospital System Partnership | Integrated delivery network contracts override individual hospital preferences in Midwest and Southeast corridors. |
| Software Companion Development | Cloud data transmission capabilities validate remote patient monitoring reimbursement under Medicare expansion. |
Research Methodology
Desk research of FDA 510(k) filings, CMS reimbursement databases, and GPO contract archives preceded structured interviews with hospital purchasing committee members, CLIA-waived device product managers, and biomedical engineering directors. Primary fieldwork captured procurement decision criteria and laboratory information system integration friction points. Secondary validation drew from EPA manufacturing waste stream regulations and EU IVDR clinical evidence requirements. Bottom-up test volume modeling and top-down diagnostics market sizing were cross-referenced for triangulation.
Variance decomposition across product type, technology platform, end-user setting, and application urgency shaped the analytical framework over the projection horizon. Segmentation dimensions included capital intensity tier, regulatory pathway complexity, and reimbursement density by care setting. CAGRs were derived from installed base replacement cycles and consumable pull-through rates. Industry-specific inputs encompassed CLIA waiver approval timelines and precious metal price forecasting.
Material uncertainties — regulatory pathway delays, reimbursement code revisions, and supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding FDA clearance velocity and Medicare coverage persistence. Recalibration cycles align with material shifts in CLIA complexity categorization and integrated delivery network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Pulmonary Function Testing Devices Market