
 Italy in Vitro Diagnostics Market | 2026-2036
Italy in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy in Vitro Diagnostics Market Intelligence
The EU In Vitro Diagnostic Regulation is expanding compliance obligations for Italian manufacturers and distributors. DiaSorin leverages its Lombardy-based manufacturing footprint to sustain domestic supply chain resilience. Abbott Laboratories anchors its southern European operations through specialized immunoassay production near Rome. bioMérieux competes aggressively in microbiology diagnostics through channel partnerships with Italy's regional hospital networks.
In vitro diagnostics encompasses reagents, instruments, and analytical systems used to detect diseases, conditions, or infections from biological specimens outside the living organism, typically requiring specimen volumes between 10 microliters and 10 milliliters depending on assay complexity. These technologies enable clinical decision-making in hospital laboratories, commercial diagnostics facilities, and research institutions by delivering quantitative or qualitative results within minutes to hours. Reagents and consumables generate recurring revenue streams that outperform instruments in margin stability across Italian procurement cycles. PCR and immunoassay technologies command premium positioning in infectious disease and oncology applications where diagnostic accuracy directly influences therapeutic pathways. Software and data management segments attract investment as laboratories integrate artificial intelligence-enabled result interpretation into routine workflows.
ANVISA-aligned quality benchmarks influence Italian exporters serving Latin American markets, while the Italian Medicines Agency enforces post-market surveillance protocols under EU MDR transitional provisions. The National Health Service's regional purchasing consortia consolidate procurement power, pressuring mid-tier suppliers on pricing transparency and performance documentation. Stakeholders must monitor how decentralized regional tendering evolves against centralized European framework contracts.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing certification timelines for Italian manufacturers while molecular testing platforms rewrite laboratory workflows across Lombardy and Emilia-Romagna hospital clusters.
Growth Catalysts
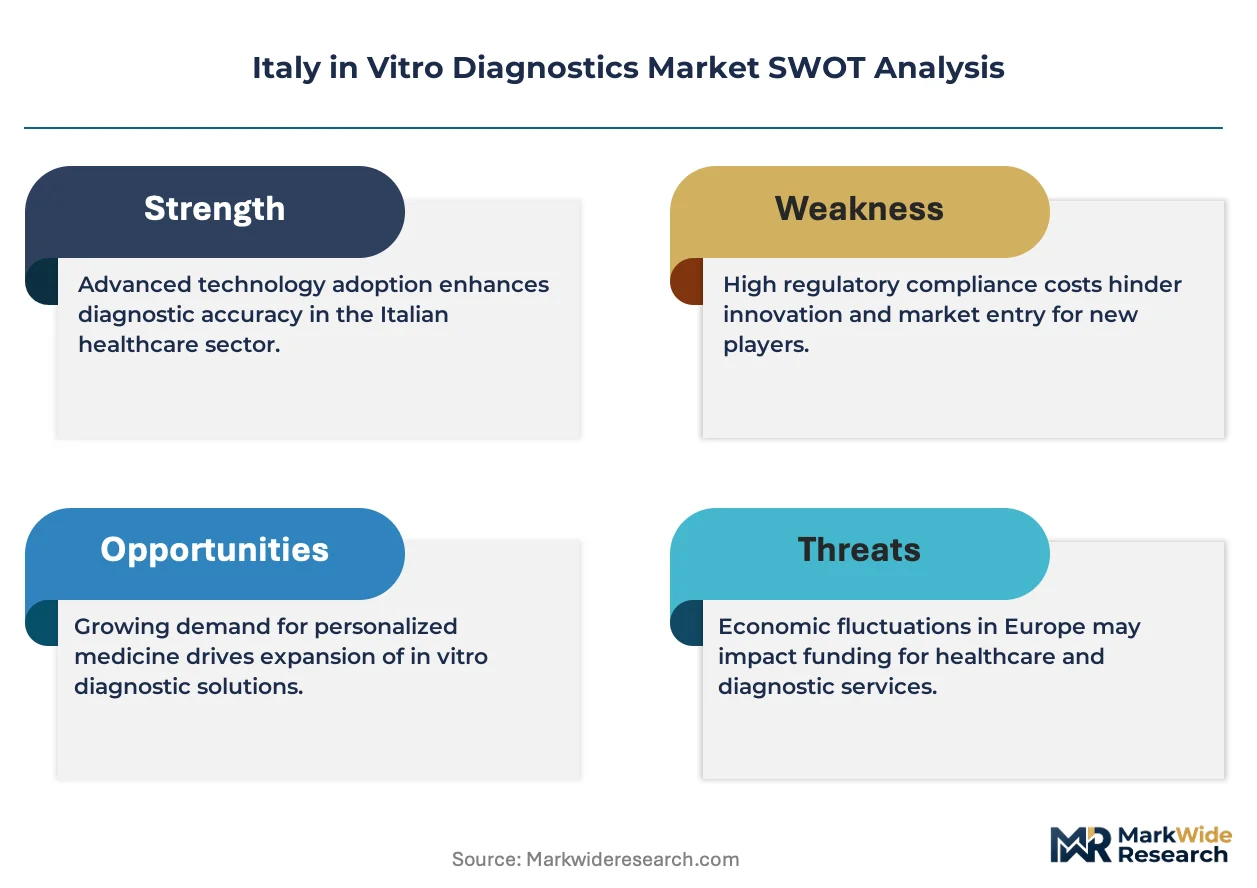
- IVDR compliance infrastructure:The EU In Vitro Diagnostic Regulation mandates post-market surveillance systems that domestic laboratories must build, creating sustained demand for quality management software and validation services.
- Molecular diagnostics expansion:PCR and next-generation sequencing platforms are penetrating regional hospital networks in northern Italy as oncology and infectious disease protocols require faster turnaround times.
- Reagent recurring revenue:Consumables generate predictable procurement cycles that stabilize manufacturer margins through Italy's regional purchasing consortia tendering processes.
Market Restraints
- IVDR transition costs:The EU In Vitro Diagnostic Regulation requires extensive clinical evidence packages that strain mid-tier manufacturers with limited regulatory affairs capacity.
- Supply concentration in Lombardy:Manufacturing and R&D capabilities cluster in Milan-Turin corridor, exposing distribution resilience to localized logistics disruptions.
- Laboratory technician scarcity:Specialized molecular diagnostics training programs produce insufficient certified personnel for expanding test volumes.
Strategic Opportunities
- Point-of-care decentralization:Community pharmacy networks in Sicily and Calabria remain underpenetrated for rapid diagnostic testing, offering channel expansion potential beyond hospital-centric models.
- AI-enabled result interpretation:Machine learning algorithms for cytology and histopathology screening are converging with digital pathology platforms to automate routine case triage.
- Regional tender consolidation:Italy's National Health Service purchasing consortia are centralizing procurement frameworks, favoring suppliers with comprehensive reagent-instrument-service bundles.
Industry Challenges
- Legacy LIS integration:Hospital laboratory information systems require costly middleware development to connect with modern cloud-based diagnostic instruments.
- IVDR technical documentation:Performance evaluation reports and clinical evidence compilation timelines extend product launch schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy in Vitro Diagnostics Market |
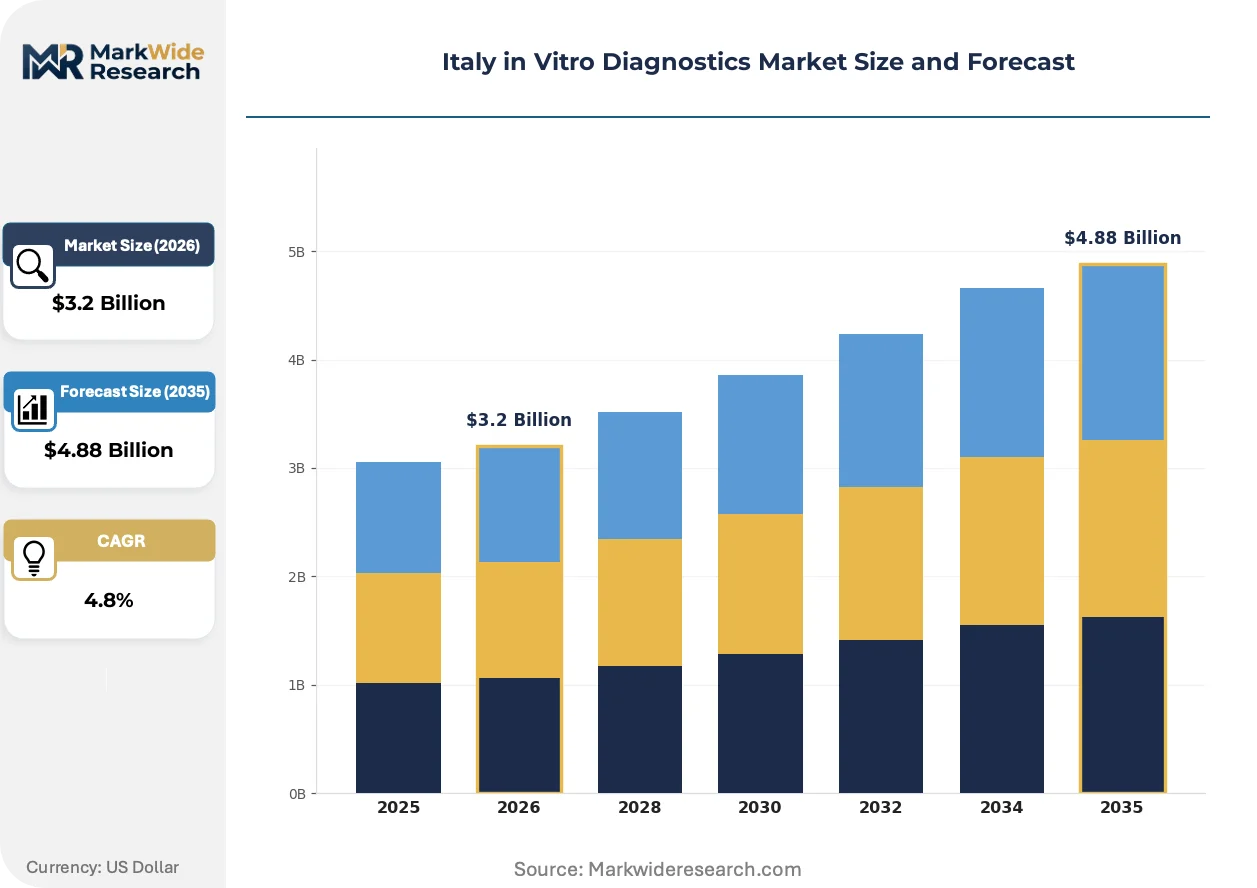
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Assays End User: Hospitals, Laboratories, Clinics, Research Facilities Technology: Microarray, PCR, Immunoassay, Sequencing Application: Oncology, Infectious Diseases, Hematology, Diabetes |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, DiaSorin, Siemens Healthineers, bioMérieux, Thermo Fisher Scientific, Danaher, Sysmex Corporation, QIAGEN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy in Vitro Diagnostics Market Strategic Shifts & Innovations
Digital pathology and artificial intelligence are compressing diagnostic workflows while regulatory frameworks force compliance investments that reshape competitive capabilities across Italian manufacturing.
Next-generation sequencing platforms are rewriting oncology diagnostics by enabling comprehensive genomic profiling from minimal specimen input. Academic medical centers in Milan and Bologna are adopting these systems for routine solid tumor characterization. The technology is compressing turnaround times from weeks to days, forcing community laboratories to outsource complex cases or invest in capital-intensive instrumentation.
The EU In Vitro Diagnostic Regulation is tightening clinical evidence requirements for Class C and D devices, mandating prospective studies that manufacturers previously avoided. Italian exporters serving Latin American markets must simultaneously satisfy ANVISA-aligned benchmarks and domestic IVDR obligations. Mid-tier suppliers are outsourcing regulatory affairs to specialized consultancies rather than building internal capabilities.
Regional purchasing consortia are consolidating tender specifications around total-cost-of-ownership metrics rather than instrument acquisition price alone. Hospital laboratories in Veneto and Tuscany are unbundling service contracts from equipment procurement, selecting third-party maintenance providers through separate competitive processes. This pattern is most visible in immunoassay analyzer contracts where reagent minimum purchase commitments now dominate vendor selection criteria.
Italy in Vitro Diagnostics Market Segmentation
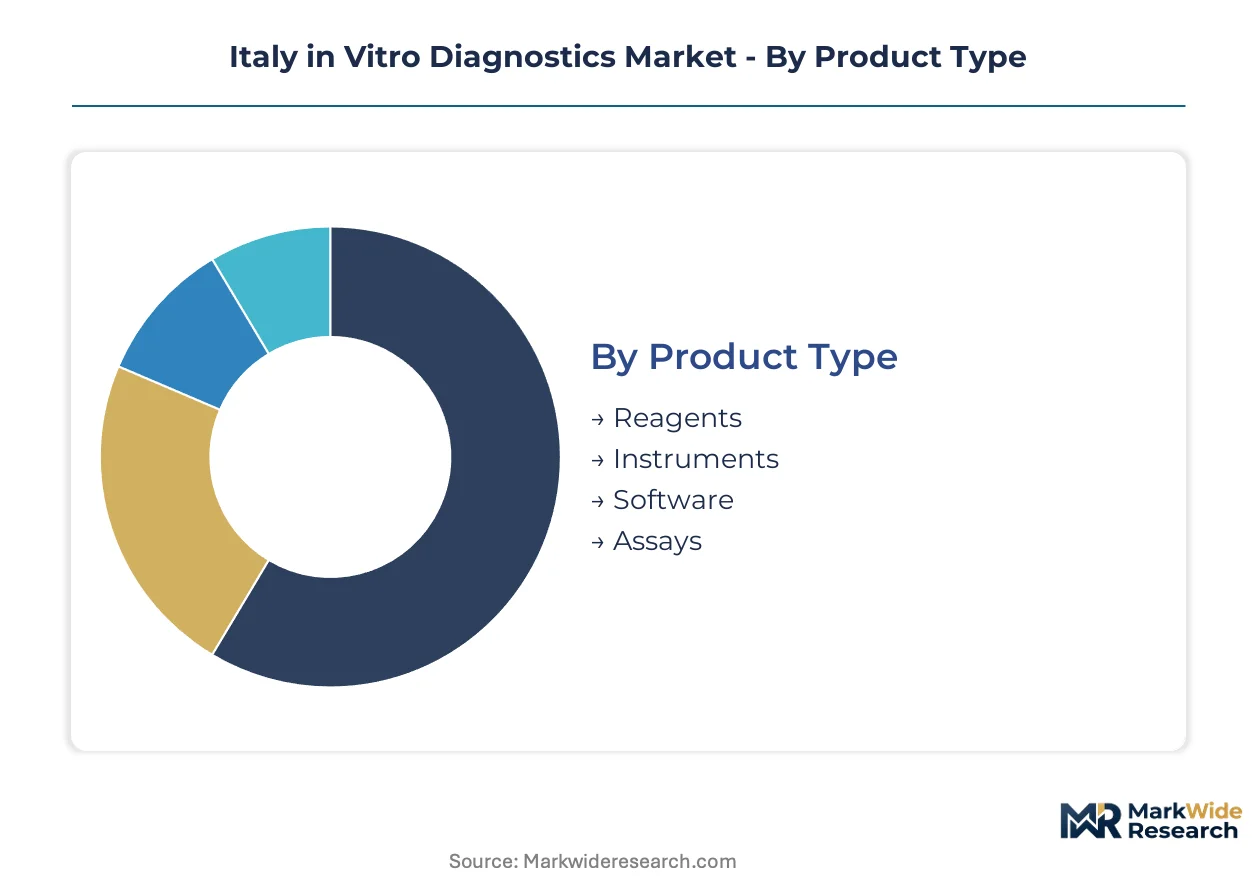
IVD market segmentation in Italy reflects procurement patterns shaped by regional purchasing consortia and the EU IVDR compliance burden. Understanding how product types, technologies, and applications split across end-user settings clarifies where manufacturers must concentrate commercial resources.
Product Type:
Customization intensity varies sharply across this category, from commoditized consumables to proprietary instrument-software bundles requiring extensive validation.
- Reagents:Chemical and biological preparations formulated for specific diagnostic reactions, typically stabilized for ambient or refrigerated storage. Demand concentrates in Lombardy and Emilia-Romagna hospital clusters where high-throughput molecular testing protocols consume bulk volumes. Regional purchasing consortia negotiate multi-year supply agreements that lock in predictable procurement cycles.
- Instruments:Analytical platforms ranging from benchtop analyzers to high-capacity automated systems processing thousands of samples daily. Northern Italian laboratories dominate installed base expansion as academic medical centers in Milan and Bologna adopt next-generation sequencing and digital pathology platforms.
- Software:Laboratory information systems and AI-enabled result interpretation modules integrating with existing hospital IT infrastructure. The Italian Medicines Agency's post-market surveillance mandates drive demand for quality management and traceability solutions.
- Assays:Pre-configured test kits combining reagents, calibrators, and protocols for specific diagnostic targets. Community laboratories in central and southern Italy favor these for standardized workflows with limited technical staff.
Most installed capacity flows through Reagents. Expansion is steepest in Software as IVDR compliance infrastructure requirements accelerate.
End User:
Procurement authority and test volume scale separate this category into centralized hospital systems versus fragmented outpatient settings.
- Hospitals:Integrated health systems with in-house laboratory services processing emergency, inpatient, and outpatient specimens. Veneto and Tuscany consortia are unbundling service contracts from equipment procurement, selecting third-party maintenance providers separately.
- Laboratories:Independent and network-affiliated diagnostic facilities serving multiple healthcare providers. These operators face IVDR technical documentation burdens that extend product launch timelines and strain mid-tier regulatory capacity.
- Clinics:Smaller outpatient settings with limited on-site testing capability, concentrated in Sicily and Calabria where rapid diagnostic testing penetration remains underdeveloped.
- Research Facilities:Academic and commercial R&D operations conducting clinical trials and biomarker discovery. Milan's biomedical research corridor anchors demand for cutting-edge sequencing and microarray platforms.
Procurement volume concentrates in Hospitals. Point-of-care decentralization is gaining share fastest in Clinics as pharmacy network expansion proceeds.
Technology:
Capital intensity and regulatory classification complexity create distinct competitive dynamics across this category.
- PCR:Amplification-based nucleic acid detection delivering high sensitivity for infectious disease and oncology applications. Lombardy hospital networks are expanding molecular testing adoption as faster turnaround times become protocol requirements.
- Immunoassay:Antibody-antigen binding reactions for protein and hormone quantification, dominant in routine clinical chemistry. Reagent minimum purchase commitments now dominate vendor selection criteria in regional tenders.
- Microarray:High-density probe arrays enabling multiplexed genetic analysis from minimal specimen input. Academic centers deploy these for research-grade genomic profiling with limited routine clinical penetration.
- Sequencing:Next-generation platforms enabling comprehensive genomic characterization of solid tumors and hematologic malignancies. Bologna and Milan medical centers are compressing oncology diagnostic turnaround from weeks to days.
Test volume runs predominantly through Immunoassay. Sequencing is climbing the fastest as precision oncology protocols expand.
Application:
Disease prevalence patterns and reimbursement pathways determine geographic concentration and technology requirements across this category.
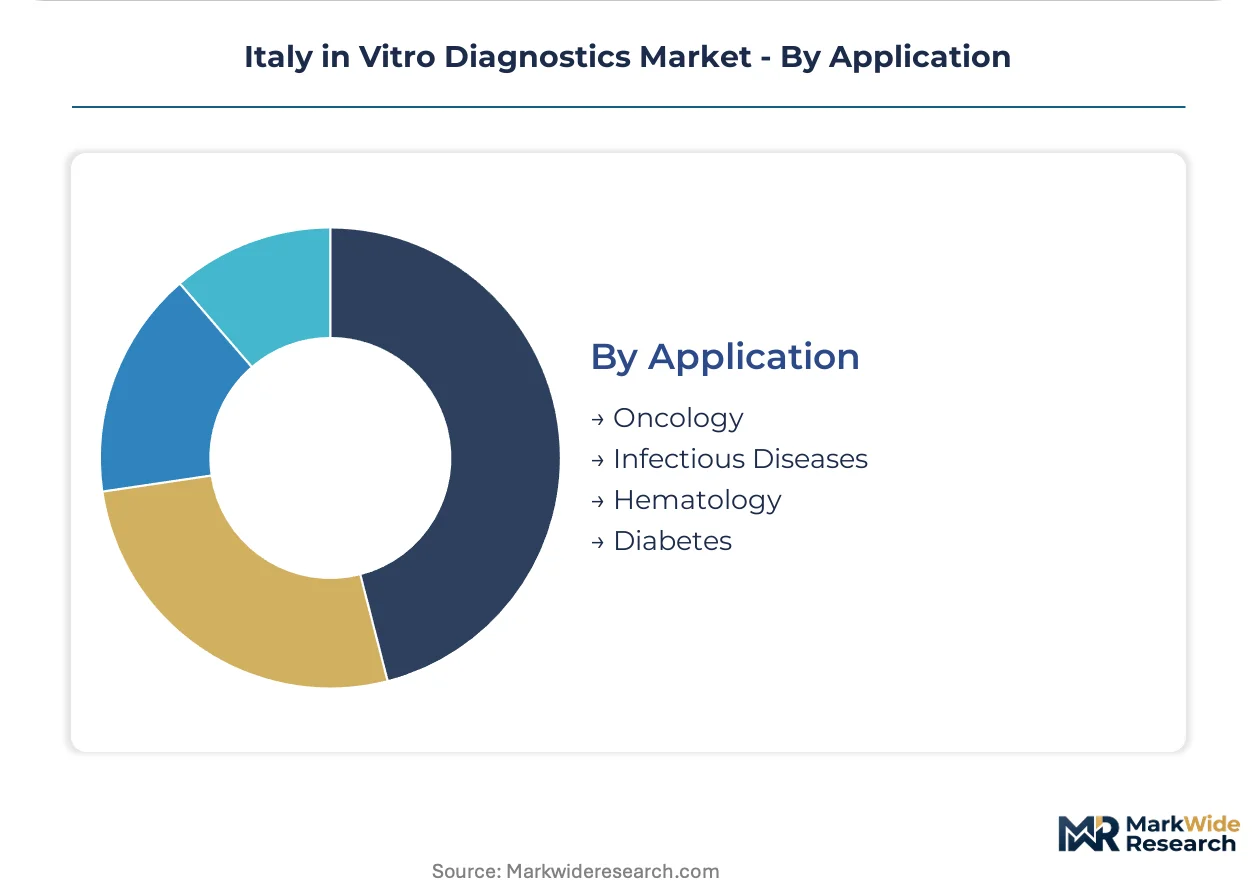
- Oncology:Diagnostic workflows for solid tumor and hematologic malignancy characterization, increasingly dependent on companion biomarker testing. Northern Italy's regional networks are consolidating molecular pathology services to achieve scale.
- Infectious Diseases:Detection and monitoring of bacterial, viral, and fungal pathogens, with pandemic preparedness investments sustaining platform utilization. PCR platforms dominate this segment with premium positioning in hospital emergency departments.
- Hematology:Complete blood count, coagulation, and bone marrow analysis for routine and specialized clinical decision-making. Automated cell counters anchor this segment with stable replacement cycles.
- Diabetes:Glucose monitoring, HbA1c testing, and related metabolic markers for chronic disease management. Community pharmacy networks in underpenetrated southern regions represent channel expansion opportunity.
Revenue concentration sits in Oncology. Infectious Diseases is gaining share fastest as antimicrobial stewardship programs mandate rapid diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Italian in vitro diagnostics industry traces its commercial roots to post-war industrialization in the Milan-Turin corridor, where precision instrument manufacturing converged with emerging biomedical research infrastructure. Regional purchasing consortia now concentrate procurement authority across northern manufacturing clusters and southern service expansion zones.
Lombardy
Molecular diagnostics adoption accelerates through Milan's academic medical centers as oncology protocols demand faster genomic turnaround times. The Italian Medicines Agency enforces post-market surveillance mandates that laboratories must satisfy through quality management infrastructure investments. The Milan-Turin corridor anchors manufacturing density for reagent production and automated analyzer assembly.
Emilia-Romagna
Hospital networks in Bologna consolidate molecular pathology services to achieve scale in precision oncology diagnostics. EU IVDR compliance timelines compress as regional laboratories upgrade validation capabilities for Class C and D devices. The Bologna biomedical research corridor attracts next-generation sequencing platform deployments for routine solid tumor characterization.
Veneto
Regional purchasing consortia unbundle service contracts from equipment procurement, selecting third-party maintenance providers through separate competitive processes. The National Health Service's decentralized tendering framework pressures suppliers on total-cost-of-ownership documentation. Padua and Verona hospital clusters drive immunoassay analyzer replacement cycles with reagent minimum purchase commitments dominating vendor selection.
Tuscany
Digital pathology adoption spreads through Florence and Pisa research hospitals as artificial intelligence-enabled cytology screening automates routine case triage. Post-market surveillance obligations under EU MDR transitional provisions require laboratories to build traceability systems. The region's diagnostic facilities outsource complex molecular cases to northern consolidated centers or invest in capital-intensive instrumentation.
Lazio
Abbott Laboratories anchors southern European immunoassay production operations near Rome, supplying regional hospital networks and export markets. ANVISA-aligned quality benchmarks influence Italian exporters serving Latin American markets from this manufacturing base. Community pharmacy networks in surrounding provinces remain underpenetrated for rapid diagnostic testing, offering channel expansion potential beyond hospital-centric models.
Italy in Vitro Diagnostics Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the Italian IVD landscape. The market structure consolidates around multinational instrument manufacturers with embedded reagent supply agreements, while mid-tier specialists compete on regulatory agility and niche application focus. Three archetypes dominate: integrated diagnostic platforms with captive consumables, regional reagent specialists with distribution depth, and software-enabled service providers addressing IVDR compliance infrastructure. M&A activity concentrates on molecular diagnostics capabilities and AI-enabled pathology platforms, while geographic expansion targets underpenetrated southern pharmacy networks.
Among Switzerland-based diagnostic conglomerates, Roche Diagnostics occupies a position exemplifying integrated platform-reagent bundling. Abbott Laboratories represents the American multinational archetype with southern European manufacturing anchoring. DiaSorin sits within the domestic specialist tier, leveraging Lombardy-based production for supply chain resilience. These three entities illustrate how geographic manufacturing footprint and regulatory compliance infrastructure separate competitive positions in Italy's regional purchasing environment.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| DiaSorin |
| Siemens Healthineers |
| bioMérieux |
| Thermo Fisher Scientific |
| Danaher |
| Sysmex Corporation |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
Italy's regional purchasing consortia concentrate procurement authority across the National Health Service, anchoring contract-based pricing structures that bundle reagent supply with multi-year instrument service agreements. The Milan-Turin manufacturing corridor feeds this buyer concentration, compressing margins for mid-tier suppliers lacking captive consumables revenue.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from regional reagent specialists and commodity consumables distributors. Price differentiation rests on IVDR certification tier and reagent bundling depth, with premium tiers commanding locked-in service contracts. Cost compression in the mid-tier intensifies because regional consortia unbundle equipment from maintenance procurement. Community laboratories in southern provinces exhibit highest price sensitivity, while academic medical centers in Milan and Bologna prioritize turnaround time over per-test economics.
Supply Chain Analysis
Freight cost volatility from German and Swiss precision component suppliers strains just-in-time inventory models for automated analyzer assembly. Manufacturing concentrates in Italy, Germany, and Switzerland for optical modules and liquid handling robotics. Raw material dependencies include stabilized enzyme formulations from German specialty chemical producers and monoclonal antibody reagents from Swiss biotech suppliers. Single-source vulnerability runs through Lombardy-based cold chain distribution for temperature-sensitive reagents. Distribution runs through regional logistics hubs serving hospital networks directly, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU In Vitro Diagnostic Regulation acts as a regulatory compounder, forcing sustained compliance infrastructure investment that favors scaled platform vendors over fragmented reagent suppliers.
For Market Incumbents: Deepen captive reagent supply agreements to lock in procurement cycles before regional consortia complete tender unbundling. Threat from AI-enabled pathology software vendors demands accelerated companion diagnostic platform integration. Vertical integration into quality management software addresses IVDR post-market surveillance mandates. For New Entrants and Emerging Players: Pharmacy network distributors in Sicily and Calabria offer the most penetrable channel for rapid diagnostic testing expansion. White-space targets include point-of-care molecular platforms for antimicrobial stewardship programs in under-resourced hospital clusters. Go-to-market positioning should emphasize total-cost-of-ownership documentation aligned with Veneto and Tuscany procurement frameworks. For Investors and Strategic Acquirers: Multinational diagnostic conglomerates with European regulatory affairs infrastructure are the most active acquirers in this space. Long-term viability favors targets with validated IVDR technical documentation for Class C and D devices rather than early-stage assay developers. Watch regional tender consolidation velocity as the inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | Accelerates product launch timelines by 18-24 months for Class C and D devices. |
| AI-Enabled Pathology Platform Integration | Automates cytology triage workflows at Milan and Bologna academic medical centers. |
| Regional Pharmacy Network Expansion | Captures rapid diagnostic testing demand in underpenetrated southern provinces. |
| Reagent-Minimum Purchase Commitment Structuring | Locks in multi-year revenue streams through regional purchasing consortia tenders. |
| Third-Party Maintenance Provider Partnership | Aligns with Veneto and Tuscany unbundling of service from equipment procurement. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged laboratory directors at Lombardy and Emilia-Romagna hospital clusters, regulatory affairs managers at domestic manufacturers, procurement officers within regional purchasing consortia, and biomedical engineers specializing in LIS integration. Secondary validation drew from EU IVDR implementation guidance documents, Italian Medicines Agency post-market surveillance protocols, GPO contract databases, and hospital procurement disclosure records. Bottom-up instrument installation tracking and top-down reagent consumption estimates were triangulated against manufacturer shipment disclosures.
Comparable-period anchoring tied projection assumptions to historical procurement cycle patterns across the analysis window. The analytical framework modeled segmentation across product type, end-user setting, technology platform, and application area, with additional dimensioning by regional regulatory cluster and tender consolidation stage. CAGRs were derived from instrument replacement cycle timing, reagent consumption intensity curves, and molecular testing protocol adoption rates. Forecast inputs incorporated IVDR compliance cost pass-through assumptions and regional purchasing consortia centralization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IVDR enforcement variability, regional tender unbundling velocity, and molecular diagnostics technician training program expansion. Forecasts reflect documented assumptions about procurement consolidation and regulatory transition pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Blood Culture Media Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Melioidosis Diagnostic Market