
 Global Paper Diagnostics Market | 2026-2036
Global Paper Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Diagnostics Market Foresight
Public health agencies are rotating into the dominant buyer archetype for paper diagnostics, displacing traditional hospital-centric procurement. Abbott Laboratories leverages its point-of-care infrastructure to sustain channel control across emerging health systems. Siemens Healthineers anchors European regulatory compliance capabilities, while Diagnostics for All Inc competes through cost-engineered formats for resource-limited settings.
Paper diagnostics encompass cellulose-based analytical devices that wick unprocessed biological samples through capillary channels to generate visual or electrochemical readouts, typically achieving sensitivity thresholds comparable to laboratory immunoassays at fractions of the cost and infrastructure requirements. Lateral flow assays dominate current manufacturing volumes due to established supply chains and minimal operator training requirements, though microfluidic paper devices represent the fastest-growing segment as multilayer wax-printing techniques enable multiplexed biomarker detection. Dipstick tests occupy mature margin pools in water quality and urinalysis applications where regulatory barriers remain lowest.
FDA 510(k) clearance pathways and WHO prequalification standards shape product development timelines and market access for paper diagnostic manufacturers, while EU MDR requirements under the In Vitro Diagnostic Regulation intensify clinical evidence demands for European commercialization. India's CDSCO and BIS certification frameworks govern import and domestic production standards for point-of-care devices deployed through national health missions. Stakeholders must monitor evolving harmonization between WHO emergency use pathways and national regulatory reciprocity agreements to anticipate procurement eligibility shifts.
Market Dynamics
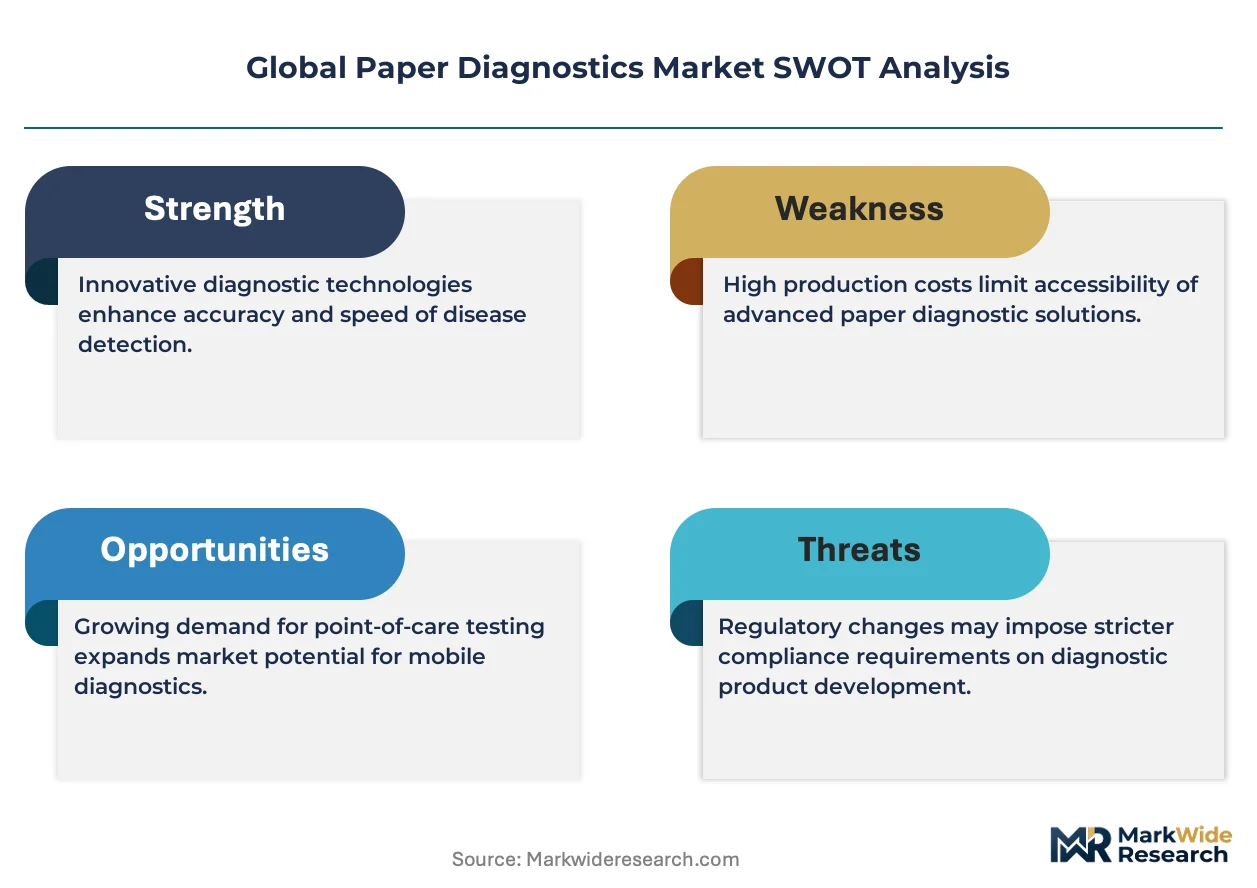
Cellulose nanofiber manufacturing advances are compressing production costs while WHO prequalification standards reconfigure procurement eligibility, creating a bifurcation between premium-certified and cost-optimized test formats across public health systems.
Growth Catalysts
- WHO prequalification pathways:Emergency use and prequalification frameworks accelerate market access for manufacturers targeting low-resource health systems, reducing time-to-deployment for priority diagnostics.
- India's rural health mission investments:National infrastructure programs scale point-of-care networks into underserved districts, generating concentrated demand for cellulose-based analytical devices.
- Cellulose nanofiber substrates:Advanced fiber engineering improves capillary flow precision and biomarker sensitivity, narrowing performance gaps with laboratory immunoassays.
Market Restraints
- Cellulose pulp price volatility:Raw material costs fluctuate with forestry commodity cycles, squeezing margins for manufacturers without backward integration into pulp sourcing.
- EU MDR clinical evidence demands:In Vitro Diagnostic Regulation intensifies documentation requirements for European commercialization, extending product development timelines.
- Centralized laboratory automation:High-throughput analyzers in urban hospital networks substitute for point-of-care formats in capitals and tertiary centers.
Strategic Opportunities
- Sub-Saharan African public health procurement:Ministries of Health in Kenya, Nigeria, and Ethiopia expand national diagnostic programs with donor-funded point-of-care deployment.
- Water quality monitoring applications:Dipstick formats for heavy metal and pathogen detection open municipal and industrial utility segments beyond clinical diagnostics.
- Multiplexed microfluidic convergence:Wax-printed multilayer devices combine lateral flow simplicity with biomarker panel detection, enabling infectious disease syndromic screening.
Industry Challenges
- Regulatory reciprocity fragmentation:Divergent national recognition of WHO emergency use pathways forces redundant certification submissions across import markets.
- Wax-printing equipment capex:Precision patterning infrastructure for microfluidic channels requires capital investment that strains early-stage manufacturing scale-up.
- Operator training standardization:Capillary-based devices demand consistent sample handling protocols, creating deployment friction where health worker turnover is elevated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Diagnostics Market |
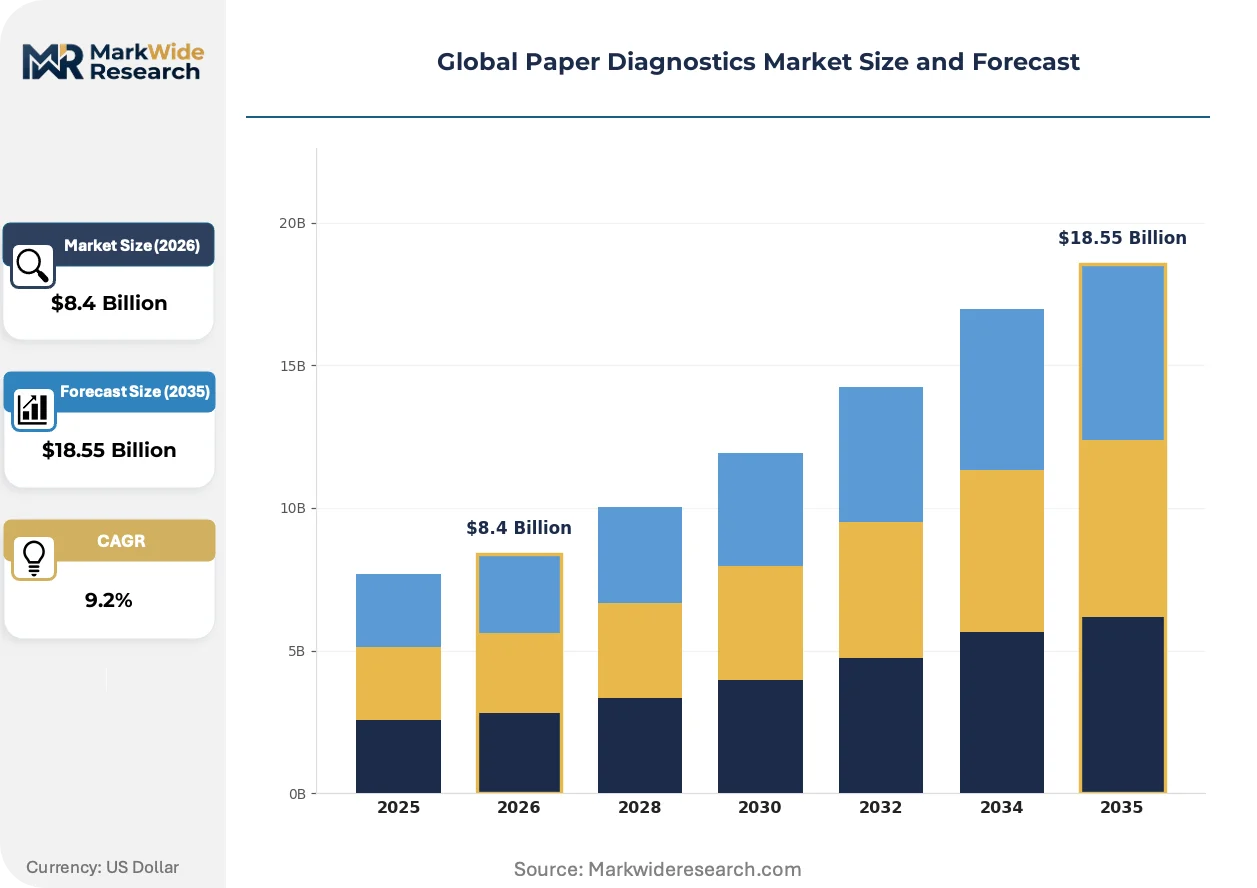
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lateral Flow Assays, Dipstick Tests, Microfluidic Paper Devices, Colorimetric Sensors, Immunoassays Application: Infectious Disease Detection, Environmental Monitoring, Food Safety Testing, Veterinary Diagnostics, Water Quality Analysis End User: Clinical Laboratories, Research Institutions, Public Health Agencies, Veterinary Clinics, Agricultural Testing Facilities Deployment: Point-of-Care, Home Testing, Mobile Health Units, Field Testing Kits, Telemedicine Platforms |
| Companies Covered | Bio-Rad Laboratories Inc, Chembio Diagnostic Systems Inc, Abbott Laboratories, Micro Essential Laboratory Inc, Diagnostics for All Inc, Arkray Inc, Siemens Healthineers AG, Abingdon Health, Acon Laboratories Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Diagnostics Market Shifts & Advancements
Multilayer wax-printing techniques and electrochemical readout integration are redefining performance thresholds, while regulatory harmonization efforts and procurement centralization reshape competitive access across emerging health systems.
Microfluidic paper analytical devices are decomposing the traditional trade-off between test complexity and infrastructure requirements. Public health agencies in India and Kenya deploy multiplexed cellulose substrates for HIV-malaria co-detection at village-level clinics. This convergence is decomposing the hospital-centric distribution model that historically controlled diagnostic access.
EU MDR implementation tightens clinical evidence standards for In Vitro Diagnostic Regulation compliance across European commercialization pathways. Manufacturers must generate expanded performance documentation for CE marking renewal and new product registration. Paper-based formats with established lateral flow architectures face compressed development timelines relative to novel microfluidic platforms requiring extensive validation.
Bulk procurement consortia anchored by Global Fund and PEPFAR programs consolidate purchasing authority for infectious disease diagnostics. National ministries in Ethiopia, Uganda, and Tanzania aggregate demand through centralized tender mechanisms, displacing fragmented hospital-level acquisition. This concentration is most visible in HIV and malaria vertical programs where prequalified manufacturer lists determine competitive participation.
Global Paper Diagnostics Market Segmentation
Channel configuration determines competitive access in paper diagnostics. Procurement centralization through public health agencies and donor programs has restructured which segments flow through institutional tenders versus retail and direct-to-patient routes.
Product Type:
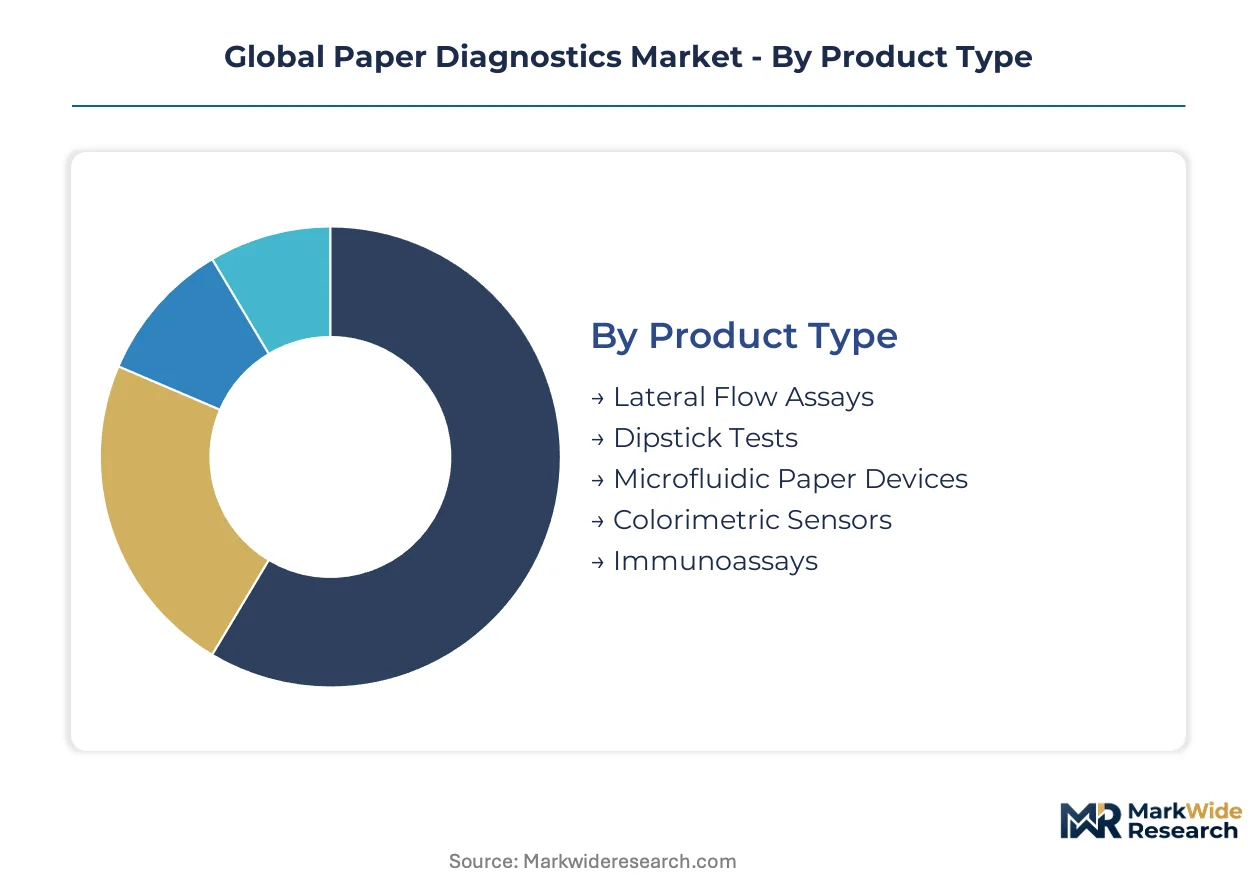
Lateral flow assays command the broadest distribution footprint through pharmacy and clinic networks, while microfluidic formats concentrate in national laboratory tenders requiring prequalification.
- Lateral Flow Assays:Cellulose nitrate or glass fiber membranes wick samples through capillary channels to generate visual readouts within minutes. Public health agencies in India and Kenya deploy these for HIV and malaria screening at village-level clinics where cold chain infrastructure is absent.
- Microfluidic Paper Devices:Multilayer wax-printed cellulose substrates enable multiplexed biomarker detection through precision-patterned hydrophobic barriers. Research institutions and centralized reference laboratories in Ethiopia and Nigeria are scaling procurement of these formats for syndromic infectious disease panels.
- Dipstick Tests:Simple cellulose strips with immobilized reagents serve water quality and urinalysis applications through municipal utility procurement channels.
- Colorimetric Sensors:pH-indicator-impregnated papers detect chemical analytes through hue shifts visible to unaided operators.
- Immunoassays:Antibody-functionalized cellulose matrices capture target antigens for qualitative or semi-quantitative detection in clinical settings.
Lateral flow assays dominate installed base. Microfluidic paper devices are where expansion concentrates.
Application:
Cost tier stratification separates premium-certified clinical formats from economy-positioned environmental and veterinary applications with lower regulatory barriers.
- Infectious Disease Detection:HIV, malaria, tuberculosis, and COVID-19 assays constitute the highest-value procurement vertical. Global Fund and PEPFAR consortia concentrate demand through prequalified manufacturer lists in Uganda, Tanzania, and Zambia.
- Environmental Monitoring:Heavy metal and pesticide detection strips serve industrial compliance and municipal water utilities. India's Central Pollution Control Board mandates dipstick monitoring for arsenic and fluoride in rural groundwater sources.
- Food Safety Testing:Pathogen and allergen detection formats address agricultural supply chain verification requirements.
- Veterinary Diagnostics:Livestock disease screening applications in Brazil and Kenya bypass human clinical regulatory pathways, accelerating deployment timelines.
- Water Quality Analysis:Bacterial contamination and chemical parameter tests deploy through humanitarian response networks and utility maintenance programs.
Infectious disease detection commands premium pricing tiers. Environmental monitoring is climbing the fastest as regulatory compliance mandates expand.
End User:
Customer type determines purchasing authority concentration, with public health agencies displacing fragmented hospital procurement through centralized tender mechanisms.
- Public Health Agencies:National ministries and vertical disease programs aggregate demand through multi-year supply agreements. Ethiopia's Health Ministry consolidates HIV diagnostic procurement through single-tender structures, displacing district-level acquisition.
- Clinical Laboratories:Hospital networks and reference facilities maintain demand for higher-sensitivity formats requiring reader instrumentation.
- Research Institutions:Academic and field research programs in Kenya and Bangladesh pilot novel assay formats before regulatory submission.
- Veterinary Clinics:Private livestock practitioners and government extension services drive demand for brucellosis and foot-and-mouth disease screening.
- Agricultural Testing Facilities:Grain export certification and supply chain verification programs deploy mycotoxin and GMO detection strips.
Public health agencies concentrate volume authority. Clinical laboratories retain margin premiums for complex panel testing.
Deployment:
Geography and infrastructure availability dictate format selection, with mobile and field configurations dominating low-resource settings while home testing expands through retail pharmacy channels.
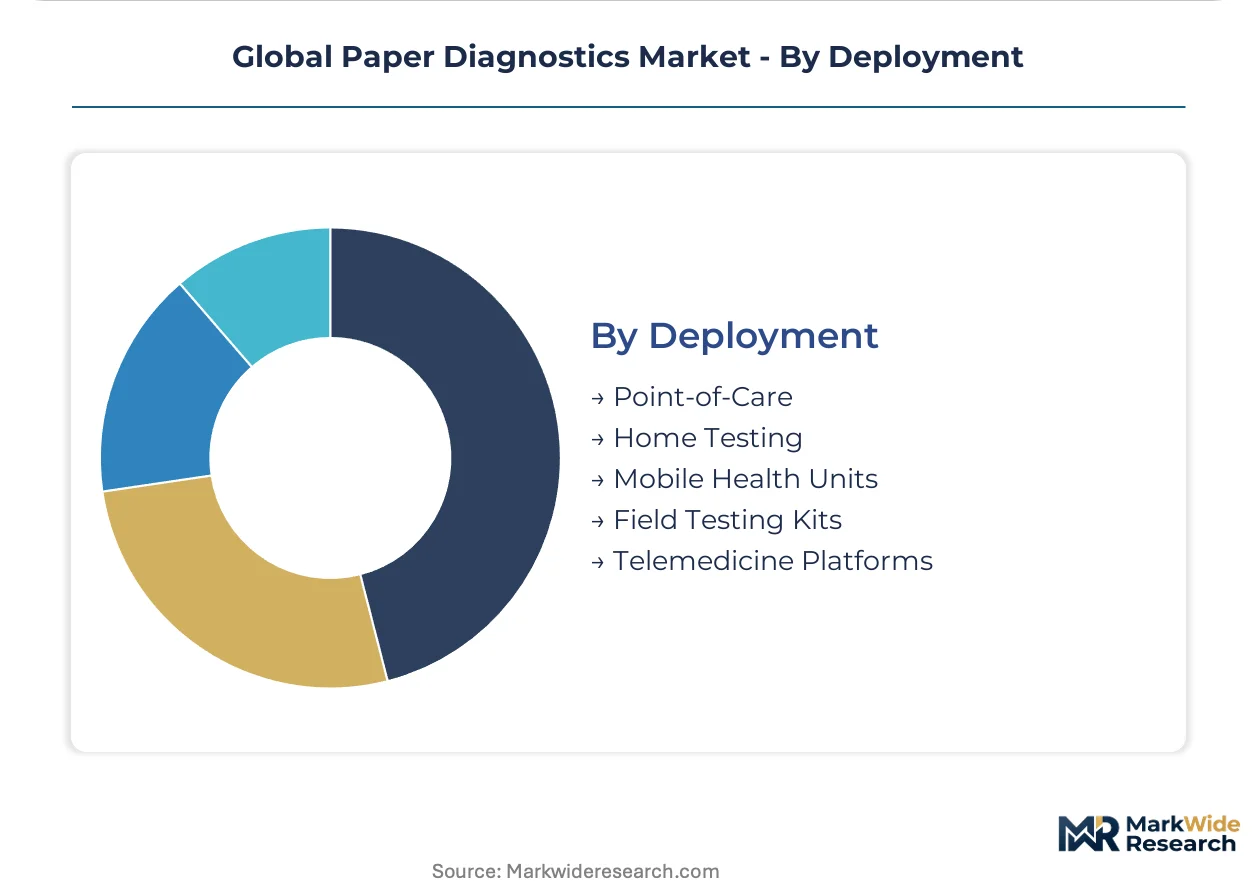
- Point-of-Care:Clinic-based deployment without laboratory infrastructure defines the core value proposition for cellulose-based diagnostics. India's rural health mission scales these networks into underserved districts through accredited social health activist distribution.
- Mobile Health Units:Van and motorcycle-mounted screening programs in Nigeria and Malawi require ruggedized packaging and extended temperature stability specifications.
- Home Testing:Over-the-counter pregnancy, glucose, and infectious disease formats flow through pharmacy retail chains in urban centers.
- Field Testing Kits:Humanitarian response and environmental monitoring applications demand portable, self-contained assay systems.
- Telemedicine Platforms:Smartphone-integrated readout systems transmit results to remote clinicians, emerging in pilot programs through Kenya's digital health infrastructure.
Point-of-care commands the deepest installed penetration. Mobile health units are gaining share fastest as last-mile network investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors cellulose substrate import flows for South Asian diagnostic manufacturing, while the Rhine-Main corridor in Germany channels precision wax-printing equipment distribution across European production networks.
United States
FDA 510(k) clearance pathways and emergency use authorization frameworks drive demand for point-of-care formats in federally qualified health centers. The Biomedical Advanced Research and Development Authority stockpiles rapid diagnostic reserves for pandemic preparedness. Boston's Route 128 biotech cluster hosts contract research organizations validating lateral flow architectures for tropical disease applications.
India
CDSCO certification requirements and BIS standards govern domestic manufacturing scale-up under the Production Linked Incentive scheme for medical devices. The National Health Mission deploys accredited social health activists to distribute HIV and malaria screening kits in Bihar and Uttar Pradesh. Karnataka's Bengaluru-Tumkur industrial corridor concentrates cellulose processing and reagent impregnation facilities.
Germany
EU MDR clinical evidence demands intensify documentation requirements for CE-marked devices entering European tender markets. The Paul-Ehrlich-Institut coordinates reference material standards for infectious disease assay validation. Baden-Württemberg's Stuttgart-Karlsruhe precision manufacturing belt supplies wax-printing equipment and automated assembly systems.
Kenya
Ministry of Health centralized procurement aggregates HIV and malaria diagnostic demand through Global Fund-supported supply agreements. The Kenya Medical Supplies Authority manages national prequalification lists for point-of-care device eligibility. Nairobi's East African logistics hub distributes temperature-stabilized assay kits to county health facilities and mobile screening units.
Brazil
ANVISA regulatory pathways for in vitro diagnostics shape import substitution strategies under domestic manufacturing incentives. The Ministry of Agriculture's veterinary extension programs deploy brucellosis screening strips through Paraná and Rio Grande do Sul livestock cooperatives. São Paulo's Campinas research triangle hosts validation partnerships between federal universities and cellulose substrate suppliers.
Global Paper Diagnostics Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized point-of-care developers. The vendor base spans three tiers: multinational diagnostic platforms with established regulatory infrastructure, mid-scale contract manufacturers serving public health tenders, and research-stage microfluidic specialists. Strategic moves center on backward integration into cellulose pulp sourcing and technology licensing partnerships for multiplexed assay architectures.
Among diversified diagnostic platforms, Abbott Laboratories and Siemens Healthineers occupy positions defined by point-of-care infrastructure ownership and European regulatory compliance capabilities respectively. Diagnostics for All Inc exemplifies the cost-engineered format archetype targeting resource-limited procurement channels. Bio-Rad Laboratories Inc anchors the life science tools segment with reagent and quality control positioning that supports assay standardization across manufacturing tiers.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc |
| Chembio Diagnostic Systems Inc |
| Abbott Laboratories |
| Micro Essential Laboratory Inc |
| Diagnostics for All Inc |
| Arkray Inc |
| Siemens Healthineers AG |
| Abingdon Health |
| Acon Laboratories Inc |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between cellulose pulp suppliers and diagnostic manufacturers lock in feedstock access while flattening price volatility exposure across multi-year procurement cycles. These contractual structures concentrate pricing power with vertically integrated substrate producers in India and Brazil, compressing margin flexibility for mid-scale reagent impregnation specialists.
Pricing Analysis
Volume-discount tiering structures stratify procurement costs across public health agency tenders, private hospital networks, and retail pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified formats from BIS-certified domestic production and unregulated gray-market imports. Cost compression in economy tiers is intensifying because India's Production Linked Incentive scheme subsidizes domestic cellulose processing capacity. Public health agencies exhibit highest price sensitivity due to consolidated tender volumes, while research institutions tolerate premium positioning for novel microfluidic formats.
Supply Chain Analysis
Jawaharlal Nehru Port Trust transit congestion periodically chokes substrate import flows from Indonesian pulp mills to Bengaluru-Tumkur processing corridors. Manufacturing gravity centers on India, China, and Germany for cellulose nitrate membranes, wax-printing equipment, and automated assembly systems respectively. Raw material dependencies span bleached softwood pulp, chromatographic-grade cellulose, and photoresist wax formulations. Single-source vulnerability concentrates in precision patterning equipment where Baden-Württemberg suppliers command lead times. Distribution runs through national medical supply authorities in Kenya and Ethiopia, bypassing fragmented private distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive shelter. WHO prequalification standards impose multi-year validation barriers that substitute technologies and emerging contract manufacturers struggle to surmount.
For Market Incumbents: Compound channel control through backward integration into cellulose pulp sourcing and captive wax-printing equipment production. Threats from microfluidic specialists with multiplexed assay architectures demand accelerated R&D investment in biomarker panel detection. Certification investment in India's CDSCO and Kenya's KEMSA prequalification lists remains the critical lever for tender eligibility.
For New Entrants and Emerging Players: Anchor in water quality monitoring applications where municipal utility procurement bypasses clinical regulatory barriers. India's Central Pollution Control Board mandates for arsenic and fluoride detection strips represent the most penetrable segment. Direct-to-utility sales models circumvent consolidated hospital purchasing committees.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale contract manufacturers with established WHO prequalification and backward integration into cellulose substrate production. Long-term viability hinges on regulatory moat sustainability rather than technology differentiation alone. Watch for WHO emergency use pathway harmonization with national reciprocity agreements as the inflection signal for procurement eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | Unlocks Global Fund and PEPFAR tender participation across Uganda, Tanzania, and Zambia. |
| Cellulose Pulp Backward Integration | Captures margin compression from forestry commodity cycles in Indonesian supply basins. |
| Multiplexed Microfluidic Development | Enables HIV-malaria co-detection panels for Kenya's village-level clinic networks. |
| Water Quality Dipstick Expansion | Accesses India's municipal utility procurement outside CDSCO clinical device pathways. |
| Mobile Health Unit Packaging | Addresses Nigeria's van-mounted screening programs with temperature-stabilized formats. |
Research Methodology
A standing panel of point-of-care device procurement managers, CDSCO regulatory affairs leads, cellulose substrate manufacturing engineers, and Global Fund supply chain coordinators provided ongoing calibration throughout the study period. Primary interview intelligence combined with secondary validation against WHO prequalification databases, BIS certification registries, and Indian customs import records for cellulose nitrate membranes. Bottom-up tender volume aggregation and top-down macroeconomic scaling were triangulated against hospital procurement surveys.
Consistency checks validated volume and value outputs against external benchmarks including national health mission expenditure disclosures and donor program procurement reports. Segmentation modeling spanned product architecture, application vertical, end-user purchasing authority, and deployment configuration across the projection horizon. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Forecast inputs incorporated cellulose pulp futures pricing and WHO emergency use pathway evolution.
Material uncertainties — regulatory reciprocity fragmentation, cellulose commodity price shocks, and centralized laboratory automation substitution — sit outside the modeled envelope. Forecasts reflect documented assumptions about tender centralization trajectories and prequalification list stability. Practitioners should keep alternative scenarios live as EU MDR clinical evidence demands and India's PLI scheme implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
IVD Antibody Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Predictive and Presymptomatic Testing Market