
 Inflammatory Markers Market | 2026-2036
Inflammatory Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Inflammatory Markers Market Foresight
The gap between premium high-sensitivity assays and commodity rapid-test formats is expanding as hospital laboratories demand greater precision for cardiovascular risk stratification while point-of-care settings prioritize cost and speed. F. Hoffmann-La Roche Ltd leverages its cobas platform dominance to sustain premium positioning in automated clinical chemistry. Thermo Fisher Scientific Inc anchors the research-grade segment through specialized immunoassay portfolios serving academic medical centers. Abbott Laboratories competes aggressively in portable diagnostic formats for emergency department deployment.
Inflammatory markers comprise measurable biomolecules—principally acute-phase proteins such as C-reactive protein and cytokines including interleukin-6 and tumor necrosis factor-alpha—whose serum concentrations rise in response to tissue injury, infection, or immune dysregulation, typically quantified via immunoturbidimetric or chemiluminescent methods with detection thresholds below 0.3 mg/L for high-sensitivity CRP applications. ELISA technology leads installed base volumes across diagnostic laboratories due to protocol standardization and reagent cost efficiency, while Luminex multiplex platforms capture margin pools in research institutes running simultaneous cytokine panels for autoimmune disorder studies. C-reactive protein testing occupies the largest revenue share among product types given its established role in cardiovascular disease screening protocols.
EU IVDR compliance timelines enforced by notified bodies across Germany, France, and Italy are reshaping market access requirements for in vitro diagnostic manufacturers seeking CE-marked assay certifications. FDA clearance pathways for high-sensitivity CRP cardiovascular risk claims maintain stringent analytical performance thresholds that filter subscale assay developers from the US hospital market. Stakeholders must monitor evolving reimbursement codes for multiplex inflammatory panels as payors scrutinize clinical utility evidence against single-biomarker alternatives.
Market Dynamics
EU IVDR compliance deadlines are compressing certification timelines for in vitro diagnostic manufacturers, forcing assay developers to consolidate technical documentation and clinical evidence packages ahead of notified body capacity constraints.
Growth Catalysts
- Cardiovascular risk protocols:Hospital laboratories in Germany and France are embedding high-sensitivity C-reactive protein testing into standard sepsis and cardiac event workups, expanding routine panel volumes.
- EU IVDR transition:The regulatory framework mandates enhanced performance evaluation and post-market surveillance, filtering out marginal competitors and concentrating demand among certified suppliers.
- Automated immunoassay platforms:Clinical chemistry systems with walkaway processing capabilities are displacing manual ELISA workflows in high-throughput hospital laboratories across Western Europe.
Market Restraints
- Notified body bottleneck:EU IVDR designation delays at BSI Group and TÜV SÜD Product Service GmbH are extending CE-marking timelines to 18-24 months for novel inflammatory assays.
- Reagent cost concentration:Specialized antibody and calibrator supply chains cluster among North American and European contract manufacturers, exposing assay producers to input price volatility.
- Interleukin-6 standardization gaps:Lack of harmonized reference materials across diagnostic platforms creates result variability that limits clinical utility in multicenter trials.
Strategic Opportunities
- Point-of-care expansion:Emergency departments in Italy and Spain are piloting portable interleukin-6 devices for rapid sepsis stratification, creating new channel access outside central laboratories.
- Multiplex cytokine panels:Luminex and flow cytometry convergence enables simultaneous quantification of interleukin-6, tumor necrosis factor-alpha, and interleukin-1β in autoimmune research settings.
- Biomarker-guided therapy:Pharmaceutical sponsors are incorporating inflammatory marker endpoints into immuno-oncology trials, opening companion diagnostic development partnerships.
Industry Challenges
- Bioinformatics talent scarcity:Multiplex platform interpretation requires computational pathology expertise that diagnostic laboratories struggle to recruit against technology sector competition.
- Legacy LIS integration:Hospital information systems in France and Germany use proprietary data formats that complicate automated result transmission from new immunoassay analyzers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflammatory Markers Market |
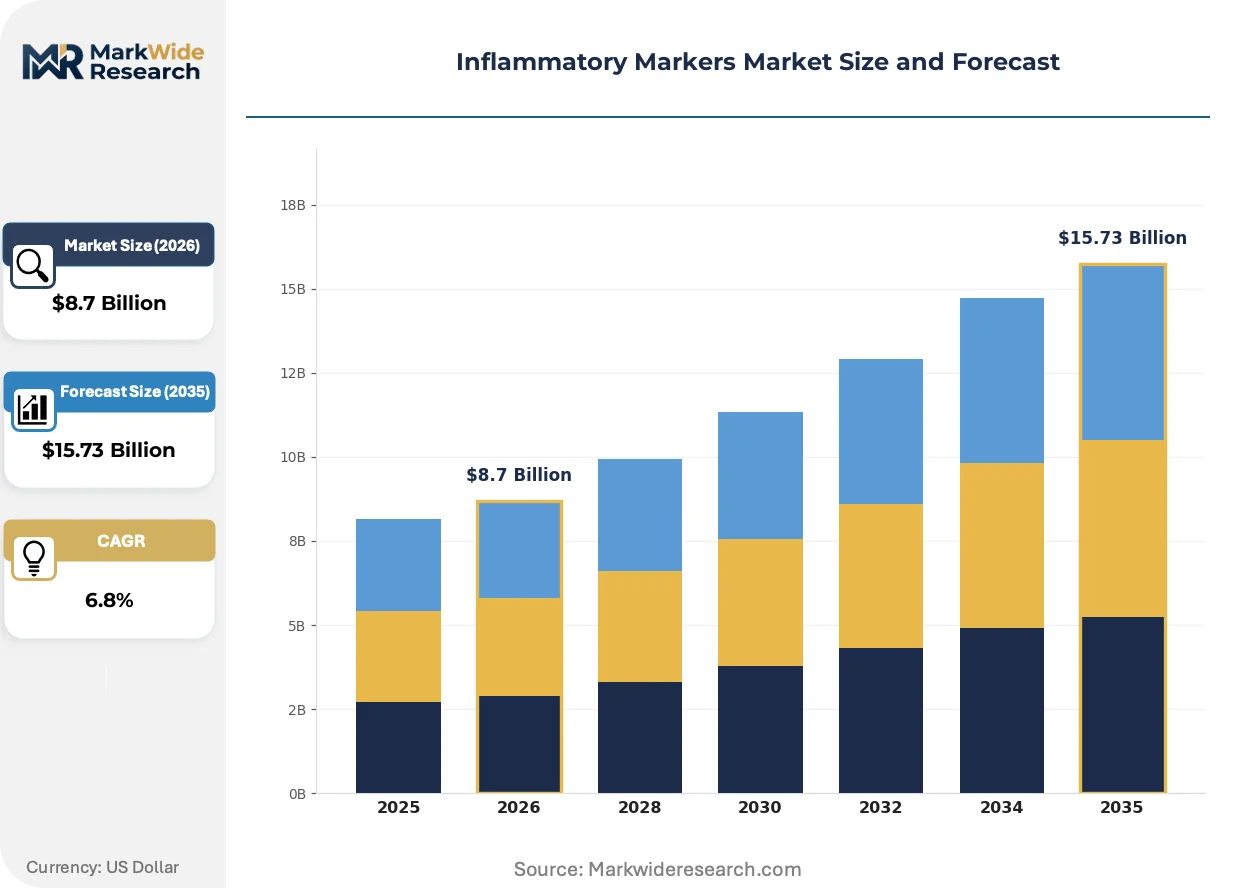
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C-Reactive Protein, Interleukin-6, Tumor Necrosis Factor-alpha, Ferritin Application: Cardiovascular Diseases, Infectious Diseases, Autoimmune Disorders, Neurological Disorders Technology: ELISA, PCR, Luminex, Immunohistochemistry End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Settings |
| Companies Covered | Thermo Fisher Scientific Inc, F. Hoffmann-La Roche Ltd, Bio-Rad Laboratories Inc, Abbott Laboratories, Siemens Healthineers AG, Merck KGaA, QIAGEN NV, BD Becton Dickinson and Company, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflammatory Markers Market Shifts & Advancements
Diagnostic platforms are converging toward automated, high-throughput configurations while regulatory frameworks demand escalating clinical evidence standards. These forces are compressing the viable supplier base and reshaping procurement criteria.
High-sensitivity C-reactive protein immunoassays are consolidating cardiovascular risk assessment workflows. Hospital laboratories in Germany and France are retiring nephelometric methods in favor of chemiluminescent platforms that detect below 0.3 mg/L with improved precision. This consolidation is compressing the mid-tier assay segment and concentrating purchasing power among platform-integrated suppliers.
EU IVDR Article 56 performance evaluation requirements are extending clinical validation obligations for quantitative immunoassays. Manufacturers must generate measurement uncertainty budgets and traceability documentation that exceeds predecessor IVD directive standards. High-sensitivity C-reactive protein assays with cardiovascular risk claims face the most intensive scrutiny, with notified bodies demanding prospective outcome studies.
Health system procurement is consolidating inflammatory panel purchasing through centralized tenders. Hospital networks in France are negotiating multi-year reagent contracts that bundle C-reactive protein, procalcitonin, and interleukin-6 testing under single-supplier frameworks. This consolidation favors automated platform vendors with broad assay menus and penalizes standalone specialty test developers.
Inflammatory Markers Market Segmentation
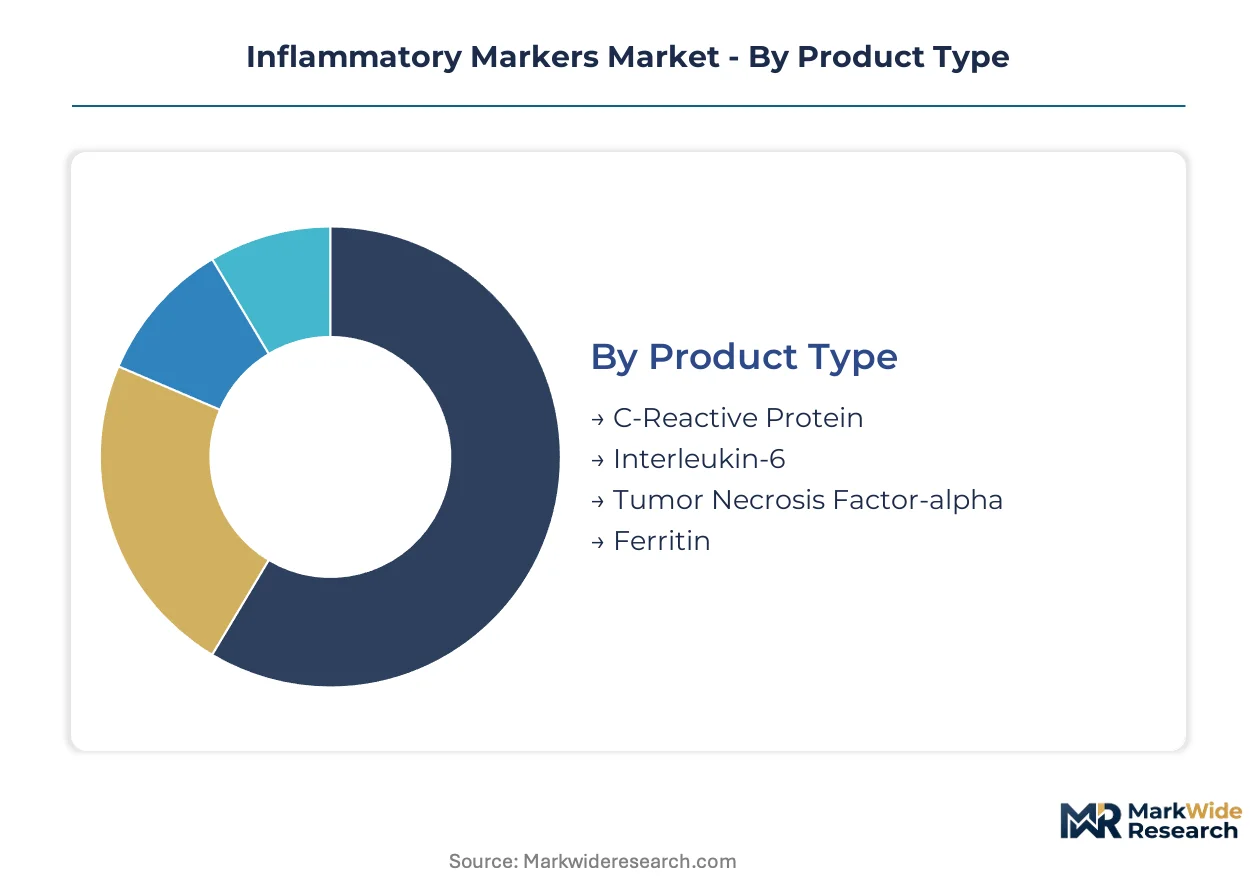
Inflammatory marker purchasing concentrates along technology-platform lines, with automated immunoassay systems commanding premium pricing in hospital laboratories while manual methods persist in resource-constrained settings. Segmentation clarity enables suppliers to align R&D investment with the specific analytical performance thresholds required by each end-use channel.
Product Type:
High-sensitivity detection thresholds differentiate premium assays from commodity alternatives, with cardiovascular risk stratification protocols demanding sub-0.3 mg/L precision.
- C-Reactive Protein:Acute-phase protein quantified via immunoturbidimetric or chemiluminescent methods with detection thresholds below 0.3 mg/L for cardiovascular applications. Hospital laboratories in Germany embed hs-CRP testing into standard cardiac event workups, driving reagent consumption volumes under EU IVDR-compliant quality systems.
- Interleukin-6:Pro-inflammatory cytokine measured through sandwich immunoassay formats with emerging point-of-care deployment for sepsis stratification. Emergency departments in Italy pilot portable IL-6 devices, though standardization gaps across platforms limit multicenter trial adoption.
- Tumor Necrosis Factor-alpha:Cytokine biomarker primarily deployed in autoimmune research protocols requiring specialized antibody pairs.
- Ferritin:Iron-storage protein serving dual roles in anemia workups and inflammation monitoring, with established reimbursement in European hospital networks.
Mature deployment sits with C-Reactive Protein. Newer deployment is concentrated in Interleukin-6.
Application:
Clinical utility evidence requirements vary sharply across indication areas, with cardiovascular protocols commanding the most stringent analytical validation standards.
- Cardiovascular Diseases:High-sensitivity CRP testing for risk stratification requires FDA-cleared or CE-marked assays with documented prospective outcome data. Hospital networks in France negotiate bundled reagent contracts covering cardiovascular panels, concentrating purchasing power among platform-integrated suppliers.
- Infectious Diseases:Procalcitonin and IL-6 combination testing guides antibiotic stewardship decisions in sepsis protocols. Diagnostic laboratories across Western Europe automate these workflows on chemiluminescent analyzers to meet turnaround-time targets for emergency department referrals.
- Autoimmune Disorders:Multiplex cytokine panels enable simultaneous quantification of IL-6, TNF-alpha, and IL-1β in research settings.
- Neurological Disorders:Emerging neuroinflammation markers face reimbursement uncertainty pending clinical utility demonstration.
Established volume anchors in Cardiovascular Diseases. Steepest expansion trajectory appears in Infectious Diseases.
Technology:
Platform selection determines throughput capacity, multiplex capability, and regulatory compliance burden for assay developers.
- ELISA:Enzyme-linked immunosorbent assay technology dominates installed base volumes across diagnostic laboratories due to protocol standardization and reagent cost efficiency. Manual workflows persist in smaller European laboratories awaiting capital replacement cycles for automated alternatives.
- PCR:Nucleic acid amplification methods enable cytokine gene expression analysis in research applications with high analytical sensitivity.
- Luminex:Multiplex bead-based platforms capture margin pools in academic medical centers running simultaneous cytokine panels for autoimmune studies.
- Immunohistochemistry:Tissue-based protein detection serves pathology departments with specialized staining protocols.
Volume concentration rests with ELISA. Margin expansion clusters in Luminex.
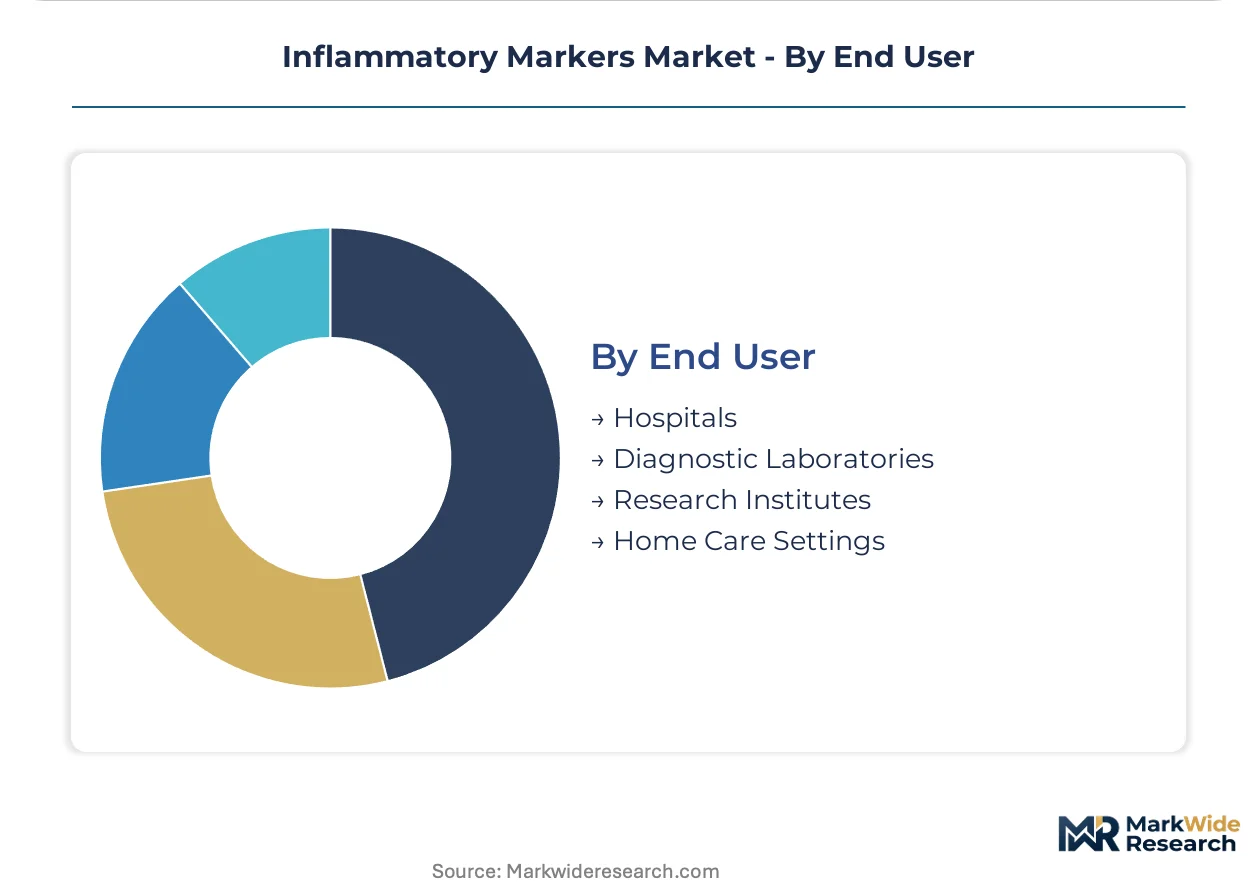
End User:
Procurement authority and technical specification requirements diverge between centralized laboratory networks and distributed care settings.
- Hospitals:Integrated health systems in Germany and France consolidate inflammatory panel purchasing through multi-year reagent contracts bundling CRP, procalcitonin, and IL-6 testing. Automated platform vendors with broad assay menus capture these tenders, squeezing standalone specialty developers.
- Diagnostic Laboratories:Commercial reference laboratories process high sample volumes requiring walkaway processing capabilities and LIS integration compatibility.
- Research Institutes:Academic medical centers demand specialized immunoassay portfolios with flexible protocol customization.
- Home Care Settings:Point-of-care formats target emergency department deployment with speed prioritization over analytical precision.
Procurement scale peaks in Hospitals. Channel development focuses on Home Care Settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European inflammatory marker demand through dense hospital networks and diagnostic laboratory clusters in Düsseldorf, Cologne, and Essen.
Germany
Hospital laboratories in Bavaria and North Rhine-Westphalia automate high-sensitivity CRP testing for cardiovascular risk protocols. EU IVDR compliance deadlines enforced by BSI Group and TÜV SÜD compress certification timelines for assay developers. The Berlin-Brandenburg corridor concentrates research-grade cytokine panel demand at Charité and Max Delbrück Center.
France
Île-de-France hospital networks bundle CRP, procalcitonin, and IL-6 testing under multi-year reagent contracts with automated platform vendors. ANSM post-market surveillance requirements extend clinical validation obligations beyond predecessor directive standards. The Lyon-Grenoble cluster drives autoimmune research cytokine consumption at Hospices Civils de Lyon.
United States
FDA-cleared high-sensitivity CRP assays with cardiovascular risk claims face stringent analytical performance thresholds that filter subscale developers. Hospital systems in Greater Boston and the Research Triangle integrate inflammatory panels into sepsis protocols. The San Francisco Bay Area anchors multiplex cytokine research demand at Stanford and UCSF medical centers.
United Kingdom
NHS England procurement frameworks consolidate inflammatory panel purchasing through centralized tenders favoring broad-menu suppliers. MHRA recognition of EU IVDR certificates streamlines market access for CE-marked assays post-Brexit. The Cambridge-Oxford-London golden triangle concentrates immunoassay R&D activity.
Japan
PMDA marketing authorization requirements maintain rigorous clinical evidence standards for quantitative inflammatory assays. Hospital laboratories in the Osaka-Kobe corridor deploy automated chemiluminescent platforms for cardiac biomarker panels. The Tokyo metropolitan area concentrates point-of-care IL-6 pilot programs for emergency department sepsis stratification.
Inflammatory Markers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology-platform tiers, with automated immunoassay systems commanding price multiples over manual ELISA workflows. The vendor base stratifies into three archetypes: diversified life science conglomerates with broad diagnostic menus, specialized immunoassay developers focused on cytokine quantification, and point-of-care format innovators targeting emergency department deployment. Consolidation pressures favor platform-integrated suppliers capable of bundling reagent contracts across multiple biomarkers. Competitive moves center on automated analyzer placement strategies and strategic partnerships with pharmaceutical sponsors for companion diagnostic development.
Within the diversified diagnostic tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc exemplify contrasting geographic and structural positioning. Roche, a Swiss-listed healthcare conglomerate, anchors premium automated platform supply through its Basel headquarters. Thermo Fisher, a US-incorporated life science group, represents research-grade segment specialization. Abbott Laboratories, an American diversified health company, occupies a distinct position in portable diagnostic formats. These three entities illustrate the archetype spectrum without exhausting competitive dynamics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| F. Hoffmann-La Roche Ltd |
| Bio-Rad Laboratories Inc |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Merck KGaA |
| QIAGEN NV |
| BD Becton Dickinson and Company |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Monoclonal antibody raw material indices cascade through inflammatory marker supply chains into tiered assay pricing structures, with high-affinity antibody pairs commanding premium multiples over polyclonal alternatives as EU IVDR certification costs concentrate purchasing power among platform-integrated suppliers.
Pricing Analysis
Throughput-based value anchoring dominates automated immunoassay contracts, with hospital networks in Germany and France negotiating per-test pricing tied to annual volume commitments and analyzer placement terms. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked high-sensitivity CRP assays from research-grade ELISA kits and unregulated rapid-test formats. Cost compression in the mid-tier segment is intensifying because notified body certification delays extend time-to-revenue for novel assay developers. Emergency departments and point-of-care settings exhibit highest price sensitivity, while cardiovascular risk stratification protocols in academic medical centers prioritize analytical precision over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled antibody shipments has reconfigured regional sourcing strategies, with diagnostic manufacturers diversifying cold-chain logistics partners to mitigate per-dose cost inflation. Monoclonal antibody production concentrates in the United States, Germany, and Switzerland, while specialized calibrator manufacturing clusters in the United Kingdom and Japan. Reagent supply draws from recombinant protein expression systems, synthetic peptide conjugates, and stabilized control materials. Single-source vulnerability persists for rare cytokine-specific antibody pairs, particularly for emerging IL-6 point-of-care formats. Distribution runs through diagnostic distributor networks serving hospital laboratories, with direct-to-manufacturer contracting expanding among consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflammatory markers market sits in a technology-transition phase, with automated chemiluminescent platforms displacing legacy nephelometric and manual ELISA workflows across Western European hospital networks.
For Market Incumbents: To counter platform commoditization pressures from multi-analyzer vendors, F. Hoffmann-La Roche Ltd and Siemens Healthineers AG should deepen backward integration into specialized antibody production to secure reagent margin control. Certification investment in EU IVDR Article 56 performance evaluation documentation will filter subscale competitors and consolidate tender access. For New Entrants and Emerging Players: Emergency department point-of-care distributors represent the most accessible channel partner type for portable IL-6 device manufacturers seeking pilot deployment contracts outside centralized laboratory networks. Spain and Italy offer the most penetrable geography for sepsis stratification pilots, with autoimmune research multiplex panels providing an alternative white-space target through Luminex platform partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cytokine assay developers with EU IVDR technical documentation packages in Germany and France, where notified body bottlenecks have extended cash runway requirements beyond venture-scale funding. The inflection signal to watch is hospital network consolidation of reagent purchasing into multi-year bundled contracts that favor broad-menu platform vendors over standalone specialty developers.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Certification Pathway | BSI Group and TÜV SÜD designation timelines filter marginal competitors from CE-marked assay markets. |
| Hospital System Partnership | Multi-year reagent contracts with Île-de-France networks bundle CRP, procalcitonin, and IL-6 testing volumes. |
| Platform Integration | Cobas and Alinity analyzer placements lock in reagent consumption through closed-system consumable models. |
| Companion Diagnostic Development | Pharmaceutical sponsor partnerships incorporate inflammatory endpoints into immuno-oncology trial protocols. |
| Point-of-Care Expansion | Portable IL-6 devices in Italian emergency departments create channel access outside central laboratories. |
Research Methodology
FDA 510(k) clearance databases, EUDAMED device registrations, and ClinicalTrials.gov investigator-sponsored study records formed the secondary backbone, cross-referenced against primary interviews with hospital laboratory directors, diagnostic platform product managers, notified body technical reviewers, and GPO contracts managers. Bottom-up assay volume estimates triangulated against top-down health system procurement expenditure data across Germany, France, and the United States.
Historical trendline analysis of automated immunoassay analyzer placements and reagent consumption patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product type, application, technology platform, and end-user channel dimensions. CAGRs derived from fitted growth curves applied to base-year market sizing, with EU IVDR transition timelines and cardiovascular protocol adoption curves serving as key forecast inputs.
Caveats apply where notified body capacity constraints, reimbursement code revisions for multiplex panels, or raw material antibody supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Creatine Kinase Reagent Market