
 IVD Quality Control Market | 2026-2036
IVD Quality Control Market Size, Share, and Industry Trends Forecast 2026-2036
IVD Quality Control Market Intelligence
Third-party quality certification tiers is unwinding legacy supplier relationships across the IVD quality control landscape. Bio-Rad Laboratories leverages its vertical integration in control materials manufacturing to sustain pricing power in hematology segments. Thermo Fisher Scientific anchors North American supply chains through captive production of calibrator panels. Randox Laboratories differentiates via specialized external quality assurance programs that extend its influence beyond product sales into laboratory accreditation services.
IVD quality control encompasses the analytical systems, reference materials, and procedural protocols used to verify that in vitro diagnostic devices produce precise, reproducible patient results within clinically validated parameters. Control materials typically comprise stabilized human serum or synthetic matrices spiked with defined analyte concentrations, manufactured under ISO 17034 guidelines to ensure commutability across instrument platforms. Clinical diagnostics applications dominate current value flows, while molecular testing quality controls are capturing accelerated investment as next-generation sequencing and PCR-based assays expand into oncology companion diagnostics. Automated systems delivery modes are displacing manual kits in high-throughput laboratories, concentrating margin pools in integrated hardware-software platforms that reduce human error in quality review workflows.
FDA quality system regulation and ISO 15189 medical laboratory accreditation standards shape product development priorities by mandating traceable control ranges and documented corrective action protocols. The EU In Vitro Diagnostic Regulation (IVDR) is restructuring market access requirements, forcing manufacturers to generate expanded clinical evidence for control material stability claims. Stakeholders must monitor how CLIA proficiency testing enforcement evolves alongside laboratory consolidation trends to anticipate shifts in control material purchasing scale and specification intensity.
Market Dynamics
Laboratory consolidation across the United States is compressing procurement cycles and elevating specification intensity for control material vendors serving high-throughput reference networks.
Growth Catalysts
- EU IVDR compliance mandates:The EU In Vitro Diagnostic Regulation requires expanded stability documentation for control materials, forcing laboratories to refresh inventory with certified-compliant products and accelerating replacement demand across European clinical networks.
- NGS oncology expansion:Next-generation sequencing platforms for companion diagnostics require specialized molecular controls with defined variant frequencies, opening dedicated product lines that command premium positioning.
- United States reference laboratory consolidation:Large integrated delivery networks are centralizing quality control procurement, creating volume contracts that favor suppliers with automated platform compatibility and multi-analyte panel breadth.
Market Restraints
- Human serum supply volatility:Control material production depends on stabilized human serum matrices with defined analyte profiles, and donor pool limitations in key sourcing regions create batch-to-batch consistency risks.
- ISO 17034 accreditation concentration:Commutability certification capabilities cluster among a limited set of reference material producers, creating supply bottlenecks for novel biomarker controls.
- Synthetic matrix performance gaps:Engineered alternatives to human-based matrices demonstrate analyte binding differences on certain immunoassay platforms, limiting substitution in high-sensitivity applications.
Strategic Opportunities
- India clinical laboratory accreditation expansion:The country's national pharmaceutical regulator is strengthening medical laboratory standards, creating demand for external quality assurance programs and control material imports as domestic compliance infrastructure matures.
- Point-of-care molecular controls:Decentralized PCR and isothermal amplification devices in pharmacy and urgent care settings require shelf-stable, single-use controls with simplified interpretation protocols.
- Cloud-integrated quality management:Software platforms that automate control charting, Westgard rule application, and corrective action documentation are bundling with consumable contracts to capture recurring revenue.
Industry Challenges
- Commutability validation expertise scarcity:Demonstrating equivalent behavior between control materials and patient specimens across multiple instrument platforms requires specialized metrology capabilities that outpace current workforce training pipelines.
- Legacy LIS integration complexity:Automated quality systems must interface with heterogeneous laboratory information systems through HL7 or proprietary protocols, extending implementation timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IVD Quality Control Market |
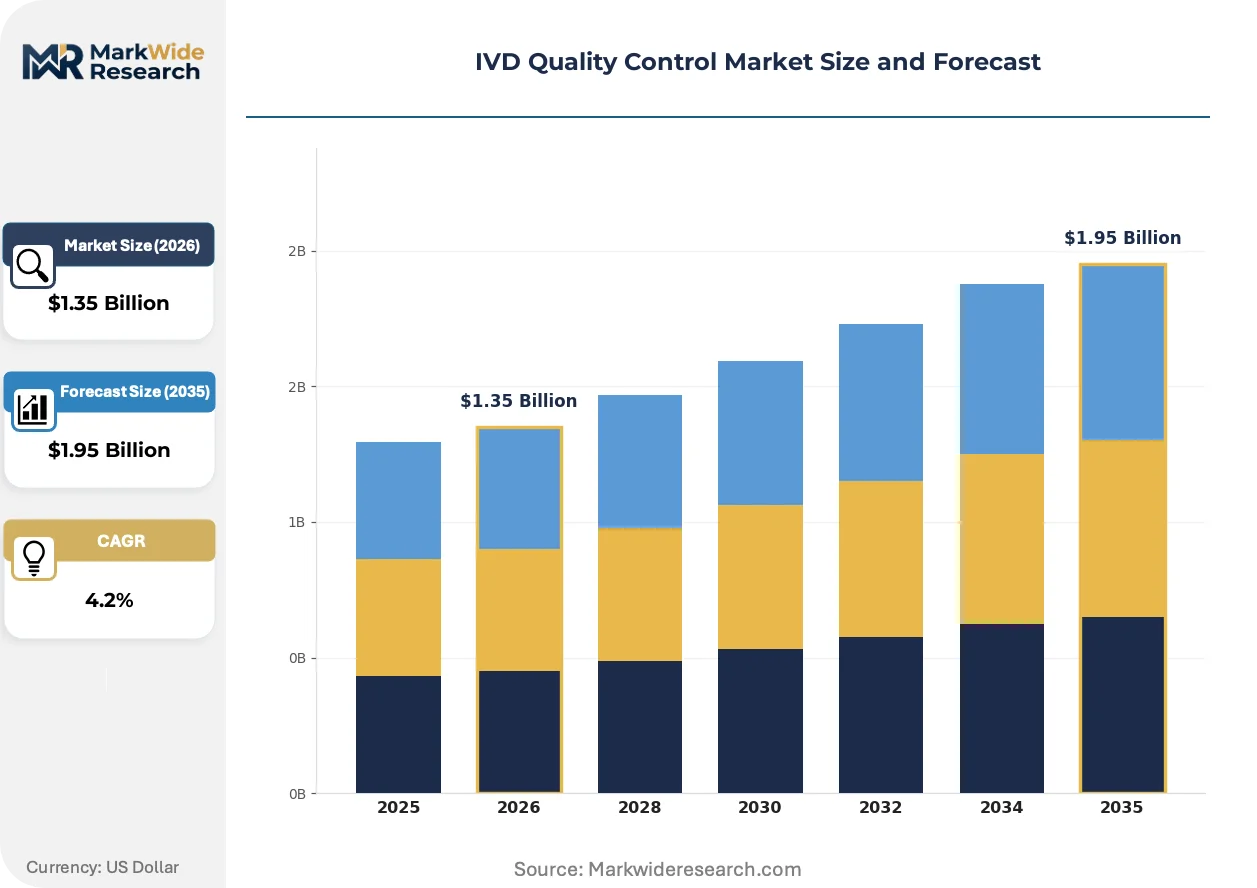
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $1.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Materials, Calibrators, Instruments, Software Tools, Reference Standards Application: Clinical Diagnostics, Molecular Testing, Immunoassays, Hematology, Microbiology End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Pharmaceutical Companies, Veterinary Clinics Delivery Mode: Manual Kits, Automated Systems, Cloud-Based Analytics, On-Premises Solutions, Third-Party Services |
| Companies Covered | Bio-Rad Laboratories, Inc., Thermo Fisher Scientific Inc., Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Randox Laboratories Ltd., LGC Limited, QuidelOrtho Corporation, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IVD Quality Control Market Strategic Shifts & Innovations
Digital integration is redefining how laboratories monitor analytical performance, with software platforms capturing real-time control data to preempt drift before patient results are compromised.
Lyophilized control materials with extended ambient stability are supplanting frozen liquid formats in distributed testing networks. Regional hospital systems and physician office laboratories lack ultra-low freezer infrastructure, and room-temperature shipping eliminates cold-chain logistics costs. This transition compresses working capital requirements for inventory management while expanding addressable markets beyond centralized reference facilities.
The FDA's updated quality system regulation tightens design validation requirements for IVD devices, cascading downstream to control material specifications. Manufacturers must now generate expanded performance data linking control ranges to clinical decision thresholds. Hematology and coagulation segments face the steepest documentation burdens as these disciplines carry the highest patient safety consequence for analytical error.
Consolidated procurement through group purchasing organizations is displacing direct vendor relationships in the United States hospital market. Multi-hospital systems negotiate enterprise contracts covering chemistry, immunoassay, and hematology controls across affiliated laboratories. This channel shift concentrates purchasing power among fewer decision-makers and rewards suppliers with broad portfolio depth and national distribution infrastructure.
IVD Quality Control Market Segmentation
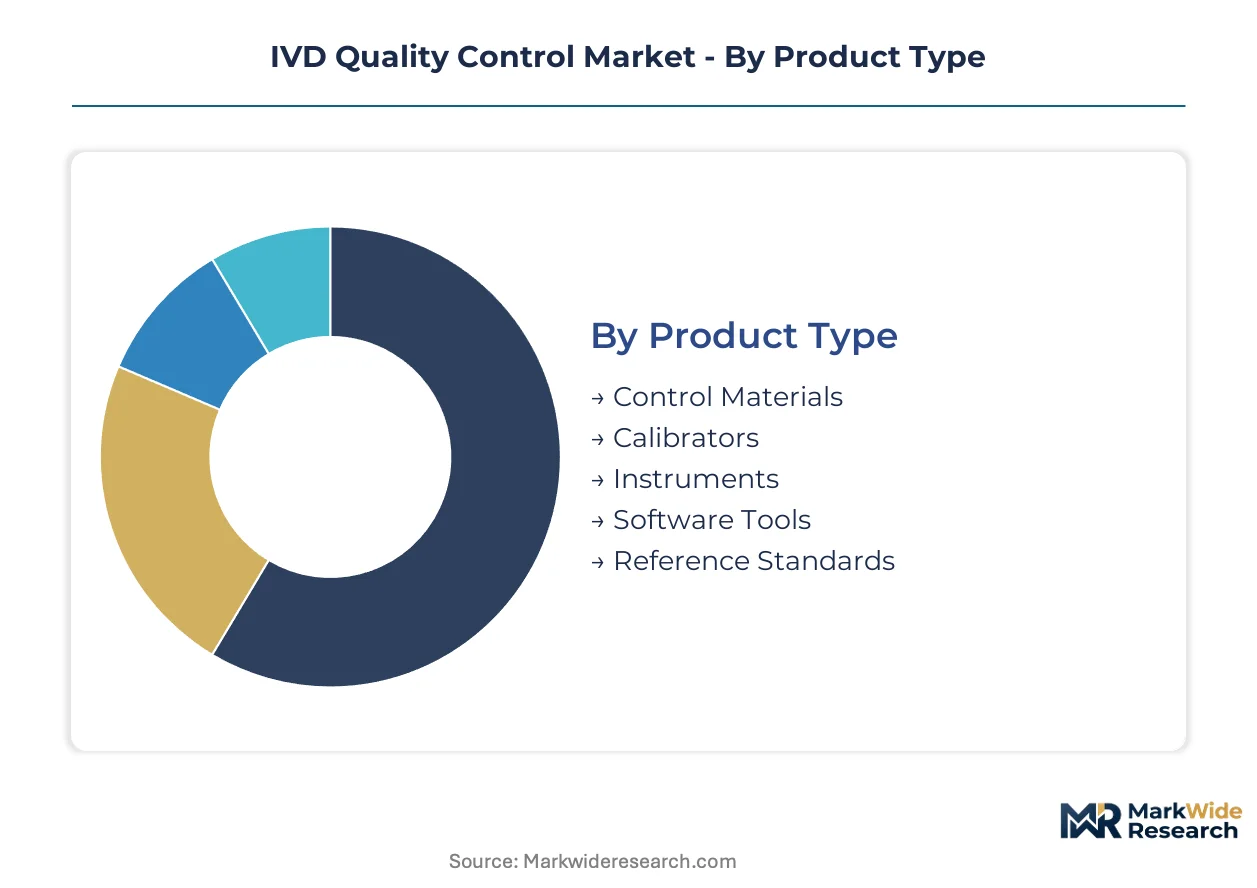
Segmentation in the IVD quality control market reveals how margin pools concentrate around automated platform compatibility and multi-analyte panel breadth. Procurement decisions increasingly hinge on integration capabilities rather than standalone product performance.
Product Type:
Margin concentration tracks toward integrated hardware-software bundles and high-specification reference materials with ISO 17034 commutability certification.
- Control Materials:Stabilized human serum or synthetic matrices with defined analyte concentrations manufactured under ISO 17034 guidelines. Demand concentrates in United States reference laboratories consolidating procurement through multi-year enterprise contracts that specify batch-to-batch consistency guarantees.
- Calibrators:Assigned value reference materials establishing traceability chains to SI units or certified reference standards. European clinical networks under EU IVDR compliance mandates are refreshing inventory with expanded stability documentation, accelerating replacement cycles for certified-compliant products.
- Instruments:Analytical platforms for control material processing and measurement.
- Software Tools:Applications for control charting, Westgard rule implementation, and corrective action documentation.
- Reference Standards:Certified materials with metrological traceability for assay validation.
Control materials hold installed capacity. Calibrators are rotating up the share rankings.
Application:
Application mix shifts with technology diffusion — clinical diagnostics maintains volume leadership while molecular testing climbs the value intensity ladder.
- Clinical Diagnostics:Chemistry and immunoassay quality controls for routine patient testing workflows. United States hospital systems negotiate enterprise contracts covering chemistry and immunoassay controls across affiliated laboratories, concentrating purchasing power among fewer decision-makers.
- Molecular Testing:NGS and PCR-based assay controls with defined variant frequencies for companion diagnostics. Oncology companion diagnostics expansion in the United States and European Union is opening dedicated product lines that command premium positioning.
- Immunoassays:Controls for antibody-antigen binding assays with sensitivity requirements.
- Hematology:Cell count and coagulation parameter controls with high patient safety consequence for analytical error.
- Microbiology:Culture-based and molecular identification assay controls.
Molecular testing is gaining share fastest. Clinical diagnostics anchors volume throughput.
End User:
Customer type determines specification intensity and contract structure — high-throughput networks demand automated integration while smaller facilities prioritize shelf stability.
- Diagnostic Laboratories:Clinical testing facilities ranging from hospital labs to independent reference networks. Large integrated delivery networks in the United States are centralizing quality control procurement, creating volume contracts that favor suppliers with automated platform compatibility.
- Research Institutes:Academic and government laboratories developing novel assay methodologies. Research institutes in Germany and Switzerland drive demand for high-characterization reference materials supporting translational research protocols.
- Blood Banks:Transfusion services requiring infectious disease and blood group controls.
- Pharmaceutical Companies:Drug development and manufacturing quality testing facilities.
- Veterinary Clinics:Animal health diagnostic facilities with simplified control requirements.
Diagnostic laboratories dominate contract value. Research institutes are climbing the specification intensity curve.
Delivery Mode:
Delivery format selection reflects infrastructure constraints and error-reduction priorities across decentralized versus centralized testing networks.
- Automated Systems:Integrated hardware-software platforms reducing human error in quality review workflows. High-throughput laboratories in the United States and Japan are displacing manual kits with automated systems delivery modes, concentrating margin pools in platforms with multi-analyte panel breadth.
- Manual Kits:Traditional control material formats requiring technician processing and interpretation. Regional hospital systems and physician office laboratories in India and Brazil lacking ultra-low freezer infrastructure sustain demand for manual formats with ambient stability.
- Cloud-Based Analytics:Remote quality management with real-time control charting and predictive drift detection.
- On-Premises Solutions:Locally hosted software with direct LIS integration capabilities.
- Third-Party Services:External quality assurance programs and proficiency testing administration.
Automated systems capture premium positioning. Cloud-based analytics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based control material suppliers export extensively to European clinical networks adapting to IVDR compliance timelines. Germany and Switzerland anchor European reference material production. India and Japan represent high-growth procurement destinations with diverging infrastructure constraints.
United States
Large integrated delivery networks centralize quality control procurement through multi-year enterprise contracts. FDA's updated quality system regulation tightens design validation requirements for IVD devices and downstream control specifications. Boston and San Diego clusters house reference laboratories driving automated platform adoption.
Germany
Research institutes in Munich and Heidelberg drive demand for high-characterization reference materials supporting translational protocols. EU IVDR mandates expanded stability documentation, forcing laboratories to refresh inventory with certified-compliant products. The country's national pharmaceutical regulator enforces medical laboratory accreditation standards that elevate specification intensity.
Switzerland
Swissmedic oversight shapes control material stability claims for products entering European distribution. Basel and Zurich clusters concentrate precision diagnostics manufacturing with captive quality control operations. Private laboratories source specialized external quality assurance programs alongside consumable procurement.
India
The country's national pharmaceutical regulator strengthens medical laboratory standards, creating demand for external quality assurance imports. Regional hospital systems and physician office laboratories lack ultra-low freezer infrastructure, sustaining demand for lyophilized formats with ambient stability. Maharashtra and Karnataka clinical networks drive accreditation expansion.
Japan
METI industrial policy supports diagnostic device quality infrastructure development. PMDA regulations align with international standards for control material traceability. Tokyo and Osaka high-throughput laboratories displace manual kits with automated systems delivery modes.
IVD Quality Control Market Key Industry Players
Listed leaders compete with private specialists across pricing power and portfolio breadth dimensions. The supplier base concentrates around three tiers: diversified life science conglomerates with captive control material production, independent reference material specialists with ISO 17034 accreditation, and regional distributors with localization capabilities. Dominant competitive moves include backward integration into human serum sourcing and strategic partnerships for automated platform compatibility.
Within the diversified conglomerate tier, Bio-Rad Laboratories, Inc. and Thermo Fisher Scientific Inc. exemplify scale-driven positioning through in-house manufacturing of control matrices and calibrator panels. Randox Laboratories Ltd. occupies a specialist position representing the independent reference material archetype with external quality assurance program offerings.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Thermo Fisher Scientific Inc. |
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Randox Laboratories Ltd. |
| LGC Limited |
| QuidelOrtho Corporation |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Capacity utilization at ISO 17034-accredited reference material facilities in Germany and the United States shapes both supply concentration and price floors for high-commutability control materials. Large integrated delivery networks leverage procurement scale to compress margins on standardized chemistry panels while premium positioning persists for NGS oncology controls with defined variant frequencies.
Pricing Analysis
Next-generation sequencing controls command substantial premiums over conventional immunoassay panels, while lyophilized formats with ambient stability bridge toward economy positioning. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17034-certified reference materials from CLIA-waived point-of-care controls and unbranded distributor products. Cost compression in chemistry and immunoassay segments is intensifying because group purchasing organizations consolidate contract negotiations across multi-hospital systems. Physician office laboratories and regional hospital networks in India and Brazil exhibit highest price sensitivity due to limited reimbursement infrastructure, whereas United States reference laboratories prioritize automated platform compatibility over unit cost.
Supply Chain Analysis
Inventory cycles for stabilized human serum matrices extend twelve to eighteen months due to donor pool screening and batch qualification protocols. Manufacturing concentrates in the United States, Germany, and Switzerland where ISO 17034 accreditation capabilities cluster. Production rests on stabilized human serum, synthetic matrix polymers, and certified reference standard traceability chains. Single-source vulnerability permeates novel biomarker control segments where commutability validation expertise concentrates among limited reference material producers. Distribution runs through direct vendor relationships for automated platform bundles and regional distributors for manual kit formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes molecular testing quality controls as NGS oncology companion diagnostics penetrate community hospital laboratories. EU IVDR compliance mandates and United States reference laboratory consolidation create dual tailwinds for accredited suppliers with automated platform breadth.
For Market Incumbents: Shield installed base relationships by embedding cloud-integrated quality management software with consumable contracts, creating switching costs that resist displacement by emerging synthetic matrix specialists. Prioritize backward integration into human serum sourcing networks to mitigate batch-to-batch consistency risks that threaten hematology segment pricing power. Defensive patent filings around lyophilization stabilization chemistry will constrain competitor format substitutions. For New Entrants and Emerging Players: EU IVDR certification fast-track programs offer accelerated market access for control materials with expanded stability documentation, opening white-space capture in European clinical networks refreshing inventory. Point-of-care molecular controls for decentralized PCR devices in pharmacy and urgent care settings represent the most penetrable segment given simplified interpretation requirements and limited incumbent software integration. Go-to-market positioning should emphasize single-use, shelf-stable formats with ambient shipping to bypass cold-chain infrastructure gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent reference material specialists with ISO 17034 accreditation and captive external quality assurance program revenue streams. Long-term viability hinges on commutability validation capabilities that outpace workforce training pipelines, creating durable moats against commoditization. Acquisition target archetypes include regional distributors with India laboratory accreditation relationships and synthetic matrix developers bridging performance gaps in high-sensitivity immunoassays. Monitor CLIA proficiency testing enforcement evolution as the inflection signal for control material purchasing scale shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Certification Pathway | Accelerated stability documentation generates replacement demand across European clinical networks. |
| Cloud-Integrated Quality Management Platform | Software bundling with consumable contracts captures recurring revenue and tightens customer retention. |
| Backward Integration into Human Serum Sourcing | Captive donor pool access mitigates batch consistency risks in hematology control production. |
| Point-of-Care Molecular Control Development | Shelf-stable single-use formats address infrastructure constraints in decentralized testing networks. |
| External Quality Assurance Program Expansion | Accreditation services extend influence beyond product sales into laboratory compliance consulting. |
Research Approach
Cross-validation between primary interviews with laboratory directors, quality assurance managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings alongside secondary validation. FDA quality system regulation guidance documents, EU IVDR technical documentation requirements, hospital procurement databases, and ISO 17034 accreditation registries provide foundational secondary data. Bottom-up segment sizing triangulates against top-down market envelope checks derived from reference laboratory capital expenditure disclosures.
Sensitivity analysis around donor pool availability, IVDR compliance timeline acceleration, and reference laboratory consolidation pace stress-tests projection robustness across the analysis window. Segmentation dimensions modeled include product type, application discipline, end-user facility scale, and delivery mode automation level. CAGRs incorporate instrument placement trajectories, control material consumption per analyzer, and pricing tier migration assumptions. Forecast inputs include CLIA proficiency testing participation rates and molecular testing menu expansion at community hospitals.
The analysis sits within stated boundaries; outcomes outside sustained EU IVDR enforcement intensity or accelerated United States laboratory consolidation would require recalibration. Forecasts reflect documented assumptions regarding commutability certification capacity expansion and synthetic matrix performance convergence. Pandemic-related donor pool disruptions or abrupt regulatory harmonization shifts represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Bleeding Disorders Testing Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Platelet Function Test Market
Testing Services
Pneumonia Testing Market
Testing Services
Apoptosis Testing Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Global Ovulation Test Market
Testing Services
Calprotectin Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Osmometer Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market