
 Global Cervical Cancer Diagnostics Market | 2026-2036
Global Cervical Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cervical Cancer Diagnostics Market Foresight
Diagnostic reagent manufacturing in Germany is expanding to serve molecular assay demand across European laboratories. BD leverages integrated sample-to-answer workflows to sustain competitive positioning in HPV DNA testing. Hologic anchors its portfolio through dominance in liquid-based cytology systems. Qiagen specializes in nucleic acid extraction technologies that extend its reach into emerging market reference laboratories.
Cervical cancer diagnostics encompasses laboratory and clinical methods for detecting human papillomavirus infection, premalignant cervical lesions, and invasive carcinoma through cytological, molecular, or imaging-based evaluation of cervical specimens. HPV DNA testing detects high-risk viral genotypes with greater sensitivity than conventional cytology, while colposcopy provides magnified visual assessment of acetowhite epithelial changes following abnormal screening results. Molecular diagnostics leads technology segmentation due to superior negative predictive value and automation compatibility. Pap smear cytology maintains substantial volume in resource-limited settings where infrastructure constraints limit molecular platform deployment. Diagnostic laboratories occupy the dominant end-user position, though community health centers represent the fastest-growing access point as decentralized screening models gain policy support.
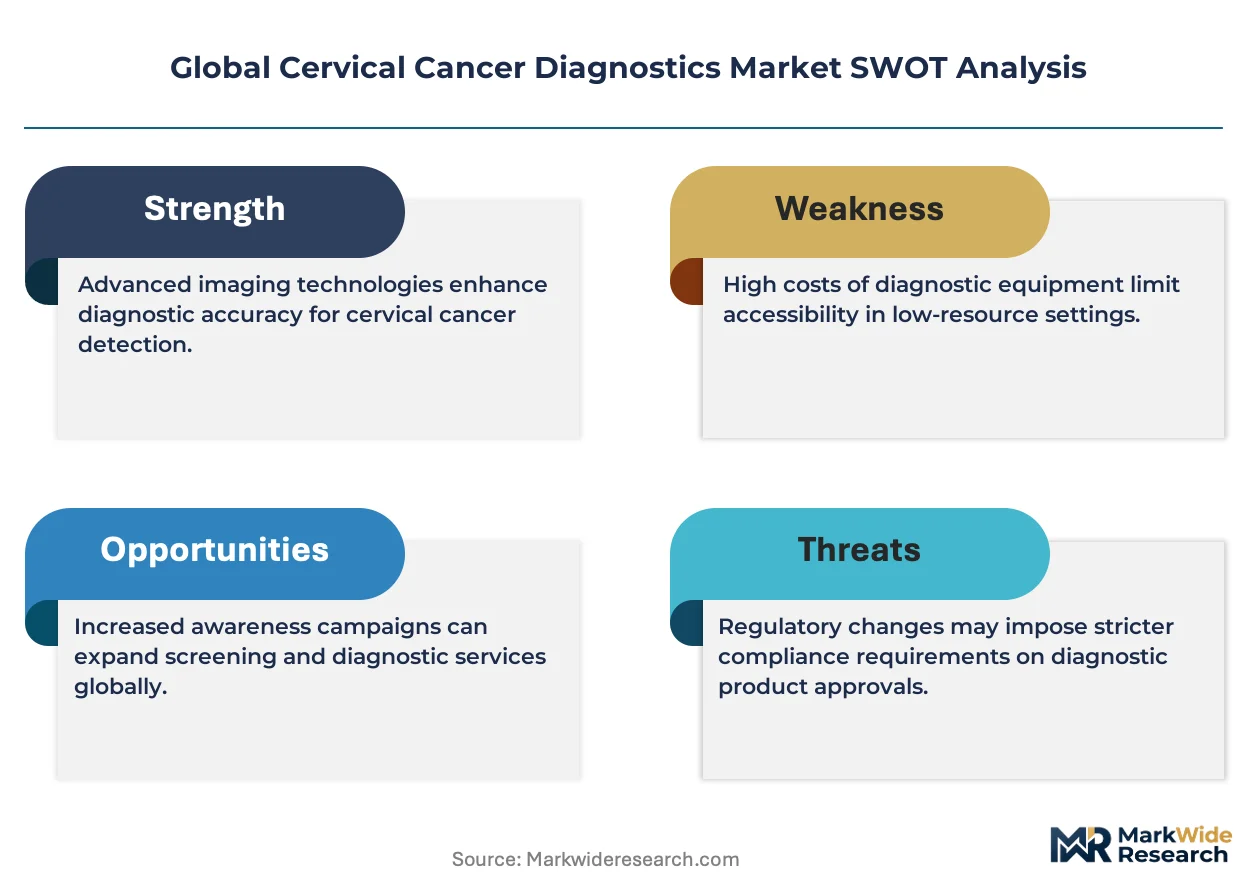
FDA premarket review under the Clinical Laboratory Improvement Amendments shapes assay performance requirements for US market entry, while EMA in vitro diagnostic regulation and WHO prequalification programs establish parallel compliance pathways for European and low-income country procurement. India's CDSCO and national screening mission directives are accelerating indigenization of HPV test kits for public health programs. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on next-generation sequencing-based cervical cancer screening algorithms to anticipate platform obsolescence risks.
Market Dynamics
HPV DNA testing is displacing conventional cytology as the primary screening modality, compressing laboratory workflows and forcing capital redeployment toward molecular platforms. This technological pivot concentrates procurement decisions among health system administrators rather than individual pathologists.
Growth Catalysts
- India's National Cervical Cancer Screening Mission:CDSCO directives are accelerating indigenization of HPV test kits, expanding community health center networks into rural districts previously underserved by cytology infrastructure.
- WHO Prequalification Programs:Low-income country procurement pathways are validating molecular assay performance standards, enabling volume purchases by ministries of health in Sub-Saharan Africa and Southeast Asia.
- EMA In Vitro Diagnostic Regulation:Harmonized performance benchmarks across European Economic Area member states are reducing assay validation burdens for manufacturers seeking multi-country market entry.
Market Restraints
- Reagent Supply Concentration:Nucleic acid extraction chemistries depend on German and Dutch specialty chemical suppliers, creating vulnerability to export licensing delays.
- Platform Capital Intensity:Automated sample-to-answer systems require laboratory infrastructure investments exceeding community health center budget allocations in low-resource settings.
- Cytology Infrastructure Lock-in:Existing liquid-based cytology installations in secondary hospitals generate organizational resistance to full molecular conversion despite superior negative predictive value.
Strategic Opportunities
- Point-of-Care Molecular Testing:Battery-operated HPV DNA platforms are penetrating rural Indian districts where cold chain logistics previously excluded laboratory-based screening.
- Self-Sampling Collection Devices:Vaginal swab protocols validated under WHO guidelines are bypassing clinician-dependent speculum examinations, expanding screening reach among never-screened populations.
- Next-Generation Sequencing Convergence:Genotyping panels integrating HPV detection with somatic mutation profiling are creating premium service tiers for private oncology networks in Brazil and Mexico.
Industry Challenges
- Cytopathologist Workforce Scarcity:Training pipelines for morphologic interpretation are contracting as medical residents redirect toward molecular pathology fellowships, degrading quality assurance capacity in hybrid screening programs.
- Interoperability Friction:Laboratory information systems deployed in the 2010s lack HL7 FHIR connectivity required for real-time screening registry integration, forcing expensive middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cervical Cancer Diagnostics Market |
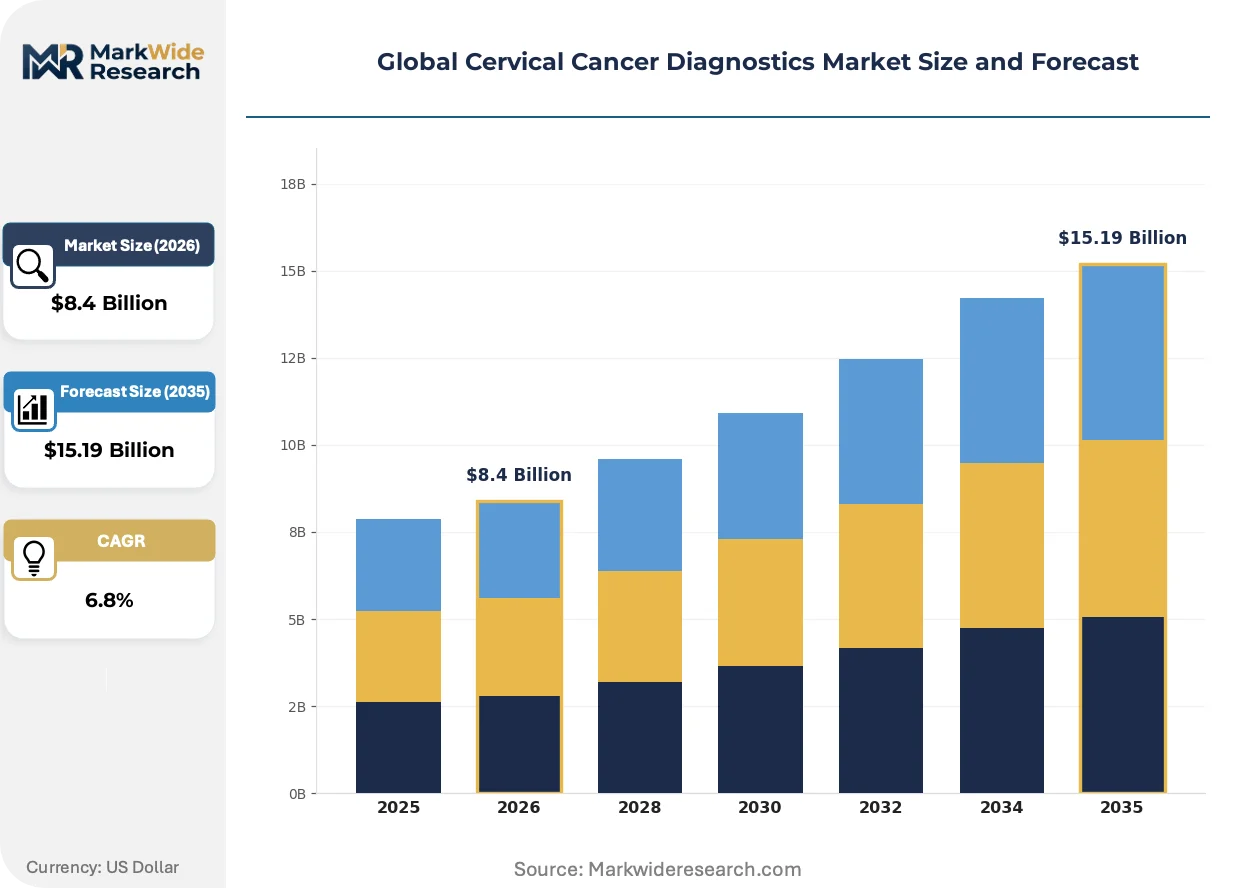
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HPV DNA Test, Pap Smear, Visual Inspection with Acetic Acid, Colposcopy Technology: Molecular Diagnostics, Immunoassays, Cytology, High-Resolution Imaging Application: Early Detection, Screening, Prognosis, Risk Assessment End User: Diagnostic Laboratories, Specialty Clinics, Research Institutes, Community Health Centers |
| Companies Covered | BD, Siemens Healthineers, Hologic, Thermo Fisher Scientific, Quest Diagnostics, Roche, Qiagen, LabCorp, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cervical Cancer Diagnostics Market Shifts & Advancements
Artificial intelligence classification algorithms are penetrating cervical cytology workflows, compressing diagnostic turnaround times while redefining pathologist role boundaries. These computational tools are reshaping laboratory staffing models and capital allocation priorities simultaneously.
CRISPR-based HPV detection is modularizing molecular assay architectures, enabling cartridge-based platforms that separate nucleic acid amplification from signal detection. Community health centers in Kerala and Tamil Nadu are piloting these systems for same-result screening visits. The technology is modularizing supply chains by decoupling instrument manufacturing from reagent production, allowing regional assemblers to compete with integrated platform vendors.
FDA premarket review pathways under Clinical Laboratory Improvement Amendments are tightening analytical performance benchmarks for high-risk HPV genotyping claims. Manufacturers must now demonstrate clinical sensitivity exceeding 95 percent for fourteen oncogenic types, elevating validation costs for market entry. Reference laboratories in the United States are responding by consolidating validation studies through collaborative trial networks rather than sponsor-sponsored investigations.
Self-collection acceptance is accelerating among never-screened women in Australian and Canadian provincial programs, displacing clinic-based speculum examination as the default entry point. Pharmacy distribution channels are capturing specimen collection kit volumes previously routed through primary care practices. This behavioral shift is most visible in Victoria and New South Wales, where mailed self-sampling kits now generate 40 percent of screening program specimens.
Global Cervical Cancer Diagnostics Market Segmentation
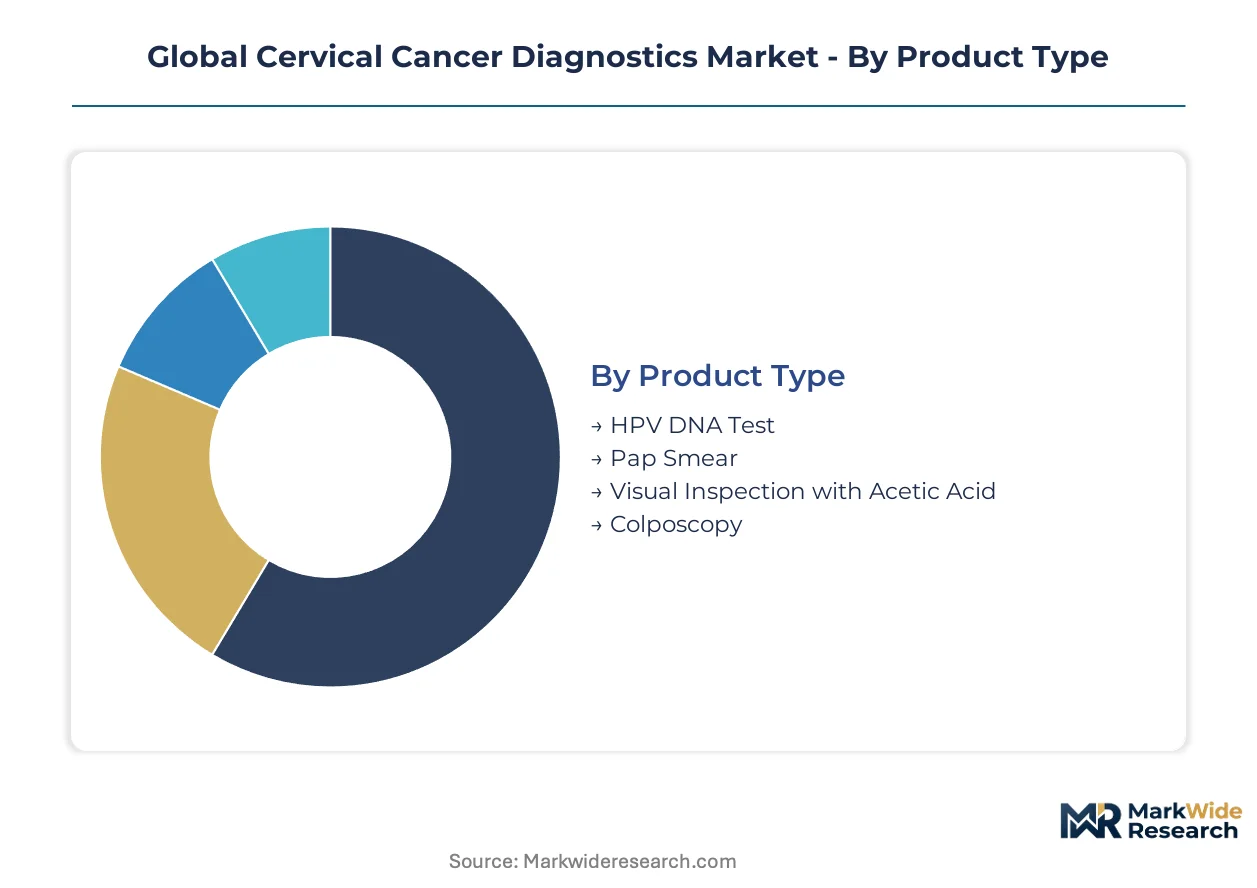
Segmentation in cervical cancer diagnostics reflects divergent capital requirements, workflow complexity, and patient access pathways. Procurement decisions increasingly favor integrated platforms over discrete consumables, reshaping vendor-customer relationships across health system tiers.
Product Type:
Capital intensity and reimbursement parity drive purchasing committee preferences toward platforms with lowest total cost of ownership.
- HPV DNA Test:Nucleic acid amplification detects fourteen high-risk viral genotypes with automated sample-to-answer workflows. Demand concentrates in India's community health centers where CDSCO-indigenized kits are displacing cytology under national screening mission directives.
- Pap Smear:Conventional and liquid-based cytology methods examine cervical cell morphology following specimen collection. Secondary hospitals in Brazil and Mexico maintain substantial volume where molecular platform budgets remain constrained by public procurement cycles.
- Visual Inspection with Acetic Acid:Low-cost acetowhite lesion detection requires minimal infrastructure. District hospitals in Sub-Saharan Africa deploy this method where cold chain logistics exclude laboratory-based alternatives.
- Colposcopy:Magnified visual assessment follows abnormal screening results. Specialty clinics in Germany and France invest in digital imaging attachments for teleconsultation integration.
HPV DNA testing leads on scale; visual inspection with acetic acid leads on momentum in lowest-resource settings.
Technology:
Automation compatibility and negative predictive value determine platform selection in high-throughput laboratory environments.
- Molecular Diagnostics:PCR and isothermal amplification methods target viral nucleic acid with superior analytical sensitivity. Reference laboratories in the United States and United Kingdom prioritize these systems for screening program efficiency.
- Immunoassays:Antibody-based detection of HPV capsid proteins or cellular biomarkers. Research institutes in Japan employ these methods for seroprevalence studies and vaccine efficacy monitoring.
- Cytology:Morphologic interpretation of Papanicolaou-stained specimens by trained cytopathologists. India's public health programs retain substantial volume where cytopathologist workforce scarcity limits full molecular conversion.
- High-Resolution Imaging:Digital colposcopy and optical coherence tomography enable real-time tissue characterization. Private oncology networks in São Paulo and Mexico City adopt these technologies for premium service differentiation.
Molecular diagnostics dominates revenue contribution; high-resolution imaging climbs fastest among technology categories.
Application:
Reimbursement coding and clinical utility evidence shape health system investment across the care continuum.
- Early Detection:Identification of premalignant cervical intraepithelial neoplasia before progression to invasive carcinoma. Australia's mailed self-sampling programs are redirecting never-screened women into this application category.
- Screening:Population-level asymptomatic testing to reduce cervical cancer incidence. National programs in India, Brazil, and South Africa concentrate procurement volume here.
- Prognosis:Risk stratification following treatment for cervical cancer. Oncology departments in Germany and France integrate HPV genotyping with somatic mutation profiling.
- Risk Assessment:Evaluation of persistent high-risk HPV infection probability. Research institutes in the United Kingdom develop algorithms combining viral load and host genetic markers.
Screening commands the largest addressable population; early detection gains share fastest through self-collection protocols.
End User:
Budget allocation authority and specimen volume determine vendor sales force deployment and service model design.
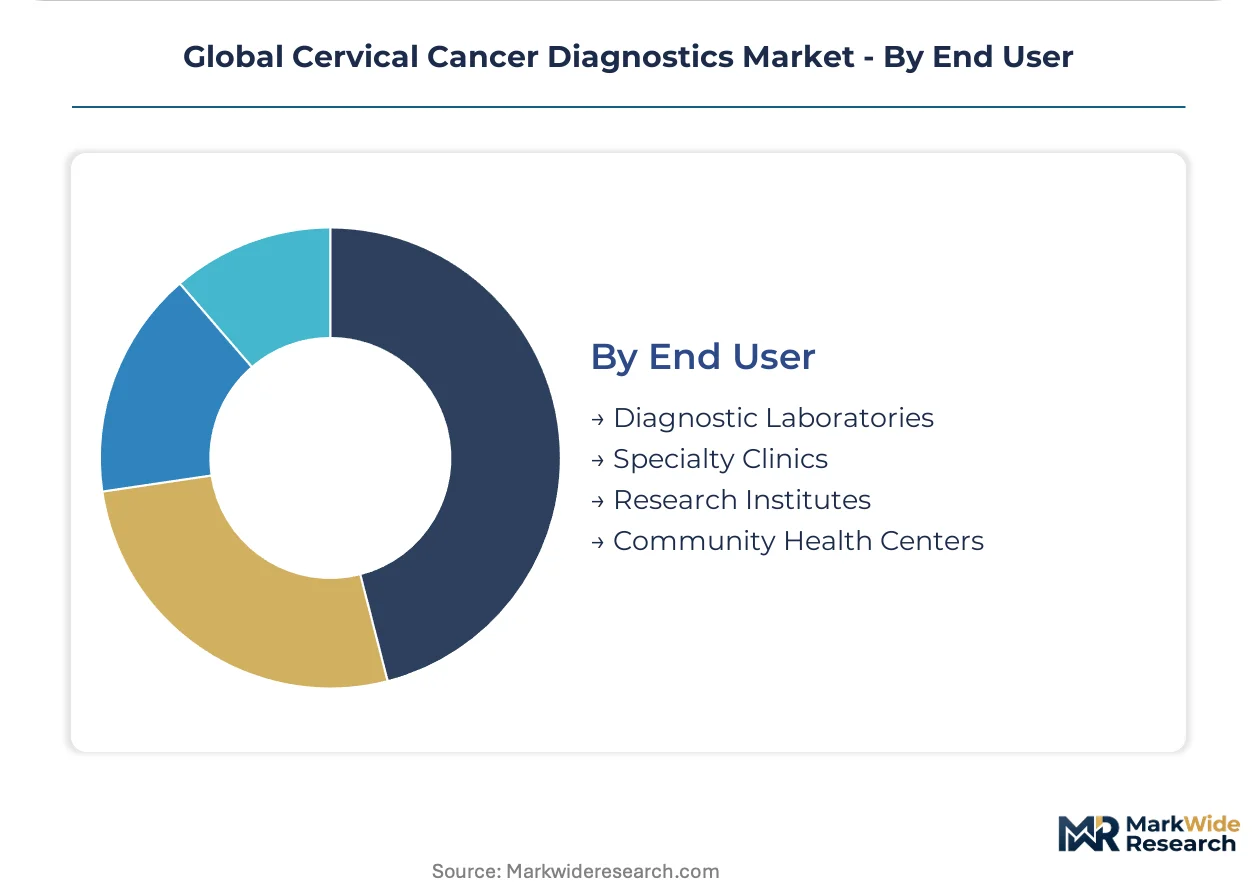
- Diagnostic Laboratories:High-throughput centralized facilities processing thousands of specimens daily. India's national reference laboratories anchor HPV DNA testing volume under CDSCO quality mandates.
- Specialty Clinics:Gynecologic oncology and reproductive health practices with integrated colposcopy services. São Paulo's private clinic networks are adopting next-generation sequencing panels for premium risk assessment.
- Research Institutes:Academic medical centers conducting epidemiological studies and assay validation. The United Kingdom's screening trial networks generate clinical evidence for regulatory submissions.
- Community Health Centers:Primary care access points in rural and underserved districts. Kerala and Tamil Nadu in India are piloting battery-operated molecular platforms for same-visit screening.
Diagnostic laboratories dominate absolute volume; community health centers expand most quickly through decentralized screening models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting diagnostic reagent manufacturing toward jurisdictions with streamlined quality certification pathways. German producers exploit EMA harmonization to serve laboratories across European Economic Area member states. Indian manufacturers leverage CDSCO indigenization mandates to capture public procurement volume under national health mission directives.
United States
Reference laboratories in Boston and Research Triangle Park consolidate HPV DNA testing volume under FDA Clinical Laboratory Improvement Amendments oversight. The agency's tightened analytical sensitivity benchmarks are elevating validation costs for assay market entry. California's Bay Area anchors artificial intelligence cytology development through academic medical center partnerships.
Germany
Specialty chemical suppliers in Baden-Württemberg and North Rhine-Westphalia dominate nucleic acid extraction chemistry production for molecular assay manufacturers. EMA in vitro diagnostic regulation harmonization reduces multi-country validation burdens for reagent exporters. Berlin-Brandenburg clusters digital colposcopy engineering for teleconsultation-integrated oncology networks.
India
Community health center networks in Kerala and Tamil Nadu pilot battery-operated HPV DNA platforms for same-visit rural screening. CDSCO directives accelerate kit indigenization under the National Cervical Cancer Screening Mission. Maharashtra's diagnostic reagent manufacturers scale production to serve public health program procurement.
Brazil
São Paulo's private oncology networks adopt next-generation sequencing panels for premium risk assessment services. ANVISA's streamlined molecular assay registration pathways attract multinational platform vendors seeking Latin American market entry. Rio de Janeiro's research institutes generate clinical evidence for WHO prequalification submissions.
Australia
Victoria and New South Wales redirect 40 percent of screening program specimens through mailed self-sampling kits distributed via pharmacy channels. TGA's expedited review pathways for validated self-collection devices are compressing product launch timelines. Melbourne's diagnostic laboratories integrate artificial intelligence cytology classification for turnaround compression.
Global Cervical Cancer Diagnostics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care decentralization and self-sampling enablement. The vendor base stratifies across integrated platform manufacturers, specialty reagent suppliers, and reference laboratory service operators. Three archetypes dominate: multinational conglomerates with sample-to-answer workflows, regional chemical specialists supplying nucleic acid extraction technologies, and national reference laboratories anchoring public screening program volume. Competitive moves concentrate on strategic partnerships for assay validation and geographic licensing for regulatory pathway acceleration.
Within the integrated platform tier, BD and Hologic exemplify divergent strategic positioning. BD leverages its sample-to-answer workflow integration to sustain positioning in high-throughput laboratory environments. Hologic anchors its portfolio through liquid-based cytology system dominance while navigating molecular conversion pressures. Qiagen occupies a distinct position as a specialty reagent supplier, extending nucleic acid extraction technology reach into emerging market reference laboratories through regional distribution partnerships.
| Leading Market Players |
|---|
| BD |
| Siemens Healthineers |
| Hologic |
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Roche |
| Qiagen |
| LabCorp |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Specialty chemical feedstocks for nucleic acid extraction chemistries flow from Baden-Württemberg and North Rhine-Westphalia through tiered pricing structures that separate premium-grade reagents for reference laboratories from economy-grade formulations for community health center pilot programs in Kerala and Tamil Nadu.
Pricing Analysis
Distributor margins for HPV DNA test kits compress as CDSCO-indigenized production in Maharashtra displaces imported molecular assays under India's national screening mission directives. Pricing stratifies across premium, standard, and economy tiers based on automation compatibility and WHO prequalification status. Cost compression in the standard tier is intensifying because German specialty chemical suppliers face export licensing scrutiny. Community health centers exhibit highest price sensitivity; private oncology networks in São Paulo and Mexico City demonstrate lowest sensitivity due to premium service bundling.
Supply Chain Analysis
FDA premarket authorization and EMA in vitro diagnostic regulation create dual certification gating that fragments reagent sourcing across German specialty chemical producers, Dutch nucleic acid chemistry suppliers, and Indian kit assemblers. Raw material dependencies center on purified nucleic acids, amplification enzymes, and fluorescent detection probes. Single-source vulnerability concentrates in German extraction chemistry suppliers serving European and North American reference laboratories. Distribution runs through national reference laboratory procurement consortia in India, Brazil, and South Africa, with direct-to-hospital contracts dominating high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into procurement volume as India's CDSCO indigenization mandates and WHO prequalification programs simultaneously expand addressable demand for molecular diagnostic platforms.
For Market Incumbents: Anchor defensive positioning through backward integration into nucleic acid extraction chemistry production and capacity expansion in Maharashtra to capture CDSCO-mandated public procurement volume. Battery-operated point-of-care platforms from regional assemblers threaten integrated platform vendors in rural Indian districts; certification investment for WHO prequalification remains the critical lever for low-income country access. For New Entrants and Emerging Players: Launch via pharmacy distribution channels for self-sampling collection devices in Australian and Canadian provincial programs where mailed kit acceptance has reached forty percent of screening specimens. Community health centers in Kerala and Tamil Nadu represent the most penetrable end-user segment; same-visit result platforms bypass cold chain logistics constraints that exclude laboratory-based alternatives. For Investors and Strategic Acquirers: Roll-up economics work for regional reagent assemblers because CDSCO indigenization mandates fragment procurement decisions away from multinational conglomerates toward local manufacturers with regulatory pathway expertise. Five-to-ten year viability hinges on convergence toward next-generation sequencing-based screening algorithms; acquisition targets should demonstrate nucleic acid extraction technology or self-collection device validation. The signal to watch is FDA-EMA regulatory convergence on genotyping panel performance benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Kit Indigenization | Maharashtra manufacturers capture public procurement volume under national screening mission directives. |
| WHO Prequalification Pathway | Low-income country ministries of health in Sub-Saharan Africa validate molecular assay performance standards. |
| Self-Sampling Device Launch | Pharmacy channels in Victoria and New South Wales displace clinic-based specimen collection. |
| AI Cytology Integration | Melbourne laboratories compress diagnostic turnaround through computational classification algorithms. |
| Point-of-Care Platform Deployment | Battery-operated systems in Kerala and Tamil Nadu enable same-visit rural screening without cold chain. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining structured interviews with regulatory affairs leads at molecular assay manufacturers, hospital procurement managers at diagnostic laboratories, GPO contracts managers, and biomedical engineers at community health center pilot sites. Secondary validation draws from FDA premarket authorization filings, EMA in vitro diagnostic regulation submissions, CDSCO manufacturing license databases, and WHO prequalification assessment reports. Bottom-up and top-down triangulation reconciles reagent production volumes with national screening program procurement disclosures.
Granularity-level modeling disaggregates the analysis window by product type, technology platform, application purpose, and end-user facility tier, with additional segmentation by regional regulatory cluster and automation compatibility grade. CAGRs derive from logistic adoption curves fitted to historical platform deployment rates and projected health system capital expenditure cycles. Forecast inputs incorporate CDSCO indigenization timelines, WHO prequalification pipeline volumes, and self-sampling protocol adoption trajectories across Australian and Canadian provincial programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export licensing disruptions for German specialty chemical suppliers or accelerated FDA-EMA convergence on next-generation sequencing performance benchmarks. A model refresh is warranted upon material change in national screening mission procurement schedules or point-of-care platform battery reliability validation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Viral Antigens Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Immunodiagnostics Market