
 Hospital Clinical Chemistry and Immunodiagnostics Market | 2026-2036
Hospital Clinical Chemistry and Immunodiagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Clinical Chemistry and Immunodiagnostics Market Foresight
High-sensitivity troponin testing is unwinding older cardiac marker protocols across tertiary care networks. Roche Diagnostics leverages its cobas platform integration to sustain installed-base loyalty in European hospital chains. Abbott Laboratories anchors its competitive stance through Alinity system standardization, while Siemens Healthineers differentiates with decentralized lab automation architectures.
Hospital clinical chemistry and immunodiagnostics encompasses quantitative biochemical analysis of blood, serum, and plasma specimens using automated analyzer systems with detection limits reaching picomolar concentrations, primarily serving diagnostic confirmation and therapeutic monitoring functions. Reagents and consumables capture the recurring revenue core as hospitals lock into long-term supply contracts tied to analyzer placements. Immunoassay technology leads application throughput for endocrinology and oncology panels, while infectious disease testing represents the fastest-expanding application segment driven by sepsis protocols and antimicrobial stewardship programs.
FDA premarket notification requirements under 21 CFR Part 862 shape analyzer validation timelines, while CLIA proficiency standards dictate laboratory accreditation thresholds that filter vendor eligibility. The EU In Vitro Diagnostic Regulation imposes post-market surveillance burdens that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving CMS reimbursement coding for multiplexed assays as payers recalibrate coverage toward diagnostic value rather than test volume.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing procurement cycles and forcing analyzer vendors into long-term sole-source contracts that lock out secondary suppliers.
Growth Catalysts
- Antimicrobial stewardship mandates:US hospital systems face CMS penalties for sepsis protocol non-compliance, driving automated infectious disease panel expansion.
- China:Academic medical centers in Shanghai and Beijing are automating chemistry lines to handle 40,000+ daily samples.
- High-sensitivity troponin I assays:Emergency departments are replacing legacy cardiac markers with 3-hour rule-out protocols.
Market Restraints
- Reagent cost concentration:Proprietary calibrators and control materials from single-source suppliers inflate per-test economics.
- EU IVDR post-market surveillance:Annual performance reporting requirements strain mid-tier manufacturers without dedicated regulatory infrastructure.
- Technical limitation:Interference from heterophile antibodies and biotin supplements generates false immunoassay results requiring costly reflex testing.
Strategic Opportunities
- India:Tier-2 and Tier-3 cities lack automated chemistry infrastructure, creating whitespace for analyzer placements with reagent rental models.
- Point-of-care immunoassay convergence:Handheld devices combining electrochemical detection with microfluidic sample processing enable decentralized testing.
- Germany's Hospital Future Act:Federal infrastructure funding for digitization subsidizes analyzer upgrades and laboratory information system integration.
Industry Challenges
- Medical laboratory scientist shortage:US clinical laboratory programs graduate insufficient personnel to operate complex analyzer networks.
- Legacy middleware integration:Hospital information systems from the 1990s require custom HL7 interface development for modern analyzer connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Clinical Chemistry and Immunodiagnostics Market |
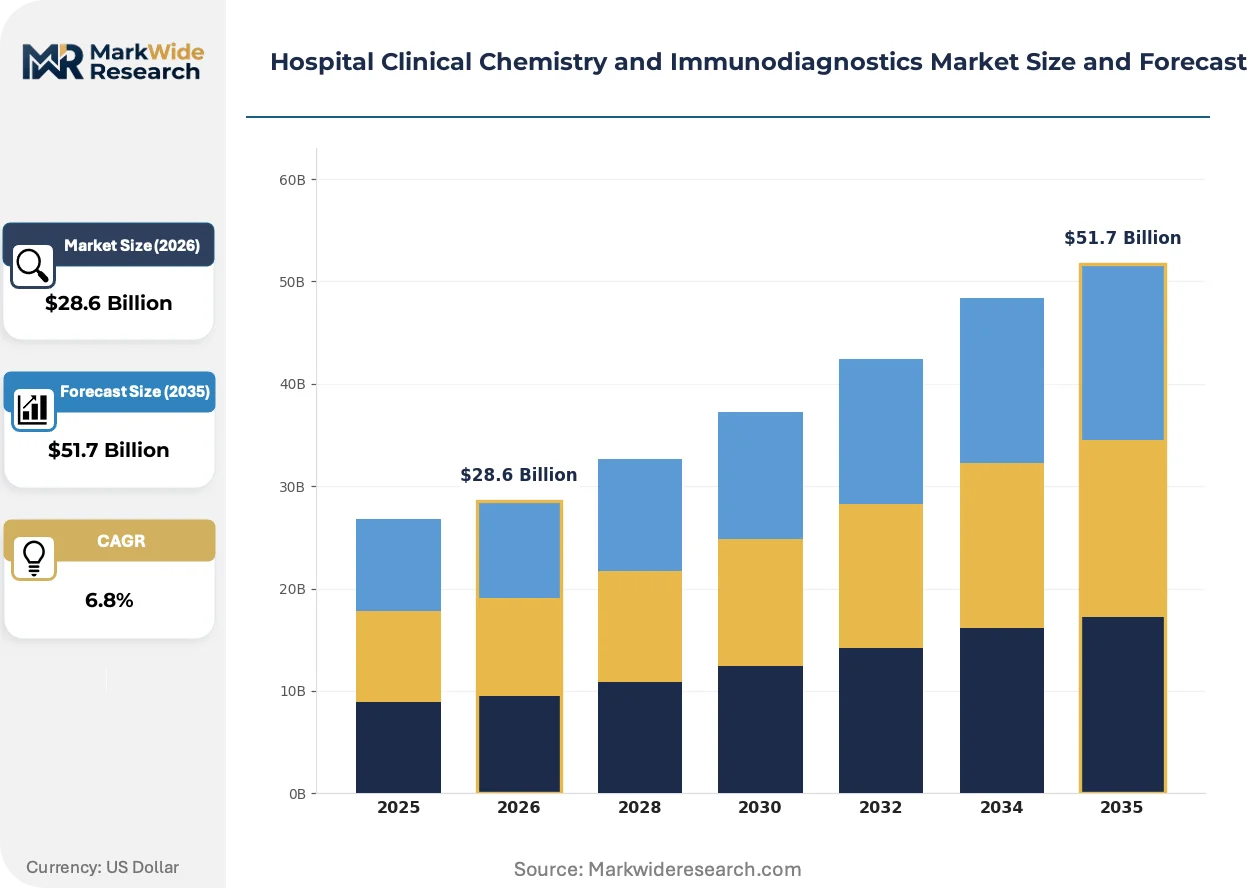
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Calibrators, Controls Technology: Immunoassays, Spectrophotometry, Chromatography, Electrochemistry Application: Oncology, Infectious Diseases, Metabolic Disorders, Cardiovascular Diseases End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Danaher Corporation, Thermo Fisher Scientific, Ortho Clinical Diagnostics, bioMérieux, Beckman Coulter, Mindray Medical International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Clinical Chemistry and Immunodiagnostics Market Shifts & Advancements
Automation architectures are fragmenting into modular, distributed configurations that sever the traditional link between high-throughput central labs and routine testing workflows.
Mass spectrometry is decomposing immunoassay dominance in endocrinology panels. Reference laboratories in Germany and the United States are adopting LC-MS/MS for steroid and vitamin D quantification. This technology is decomposing the installed-base economics of traditional analyzer vendors by enabling send-out testing with superior analytical specificity.
The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for class C and D devices. Manufacturers must submit post-market performance data annually. Oncology companion diagnostics face the heaviest documentation burden, prompting consolidation of regulatory affairs functions among mid-sized IVD firms.
Group purchasing organizations are consolidating hospital procurement decisions into multi-year sole-source agreements. Independent community hospitals are losing negotiating leverage as IDN-affiliated laboratories capture volume discounts. This concentration is most visible in the United States, where three GPOs control 70 percent of acute care purchasing.
Hospital Clinical Chemistry and Immunodiagnostics Market Segmentation
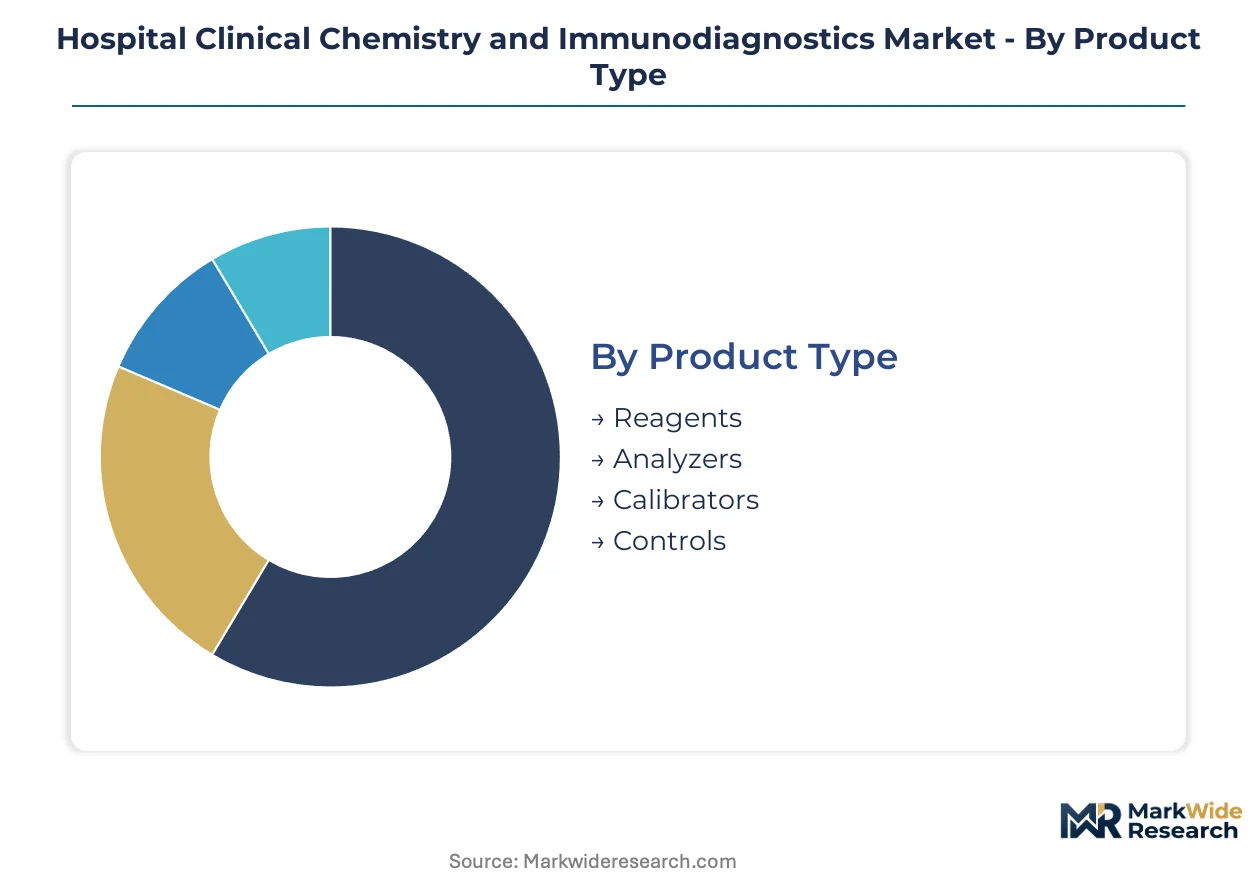
Segmentation in hospital clinical chemistry and immunodiagnostics reveals how procurement power, testing volumes, and regulatory requirements concentrate across different product configurations and care settings. Understanding these divisions exposes where vendors can lock in recurring revenue versus where price competition intensifies.
Product Type:
Reagents flow predominantly through domestic supply chains tied to analyzer placements, while analyzers themselves cross borders with heavy regulatory documentation.
- Reagents:Liquid-stable formulations with 12-24 month shelf stability dominate hospital contracts. Demand clusters in United States integrated delivery networks purchasing through sole-source agreements with locked pricing tiers.
- Analyzers:Modular systems processing 800-1,200 tests per hour serve high-throughput central laboratories. Academic medical centers in Germany and China anchor import demand for advanced chemistry-immunoassay integrated platforms.
- Calibrators:Traceable reference materials with NIST-recognized metrology chains ensure result harmonization across analyzer fleets.
- Controls:Third-party quality control products with multi-analyte panels support CLIA and EU IVDR compliance documentation.
Reagents command the established base. The steepest expansion runs through analyzers as China and India automate previously manual workflows.
Technology:
Cost tier separation divides this category: immunoassay and spectrophotometry platforms amortize across high test volumes, while chromatography and electrochemistry serve specialized reference applications.
- Immunoassays:Chemiluminescent detection with picomolar sensitivity drives endocrinology and oncology panels. United States emergency departments are converting cardiac marker protocols to high-sensitivity troponin I formats.
- Spectrophotometry:UV-Vis and turbidimetric methods quantify proteins, enzymes, and substrates in routine chemistry panels. German hospital laboratories maintain dense installed bases requiring reagent continuity.
- Chromatography:LC-MS/MS systems displace immunoassays for steroid and vitamin D quantification in reference laboratories seeking superior analytical specificity.
- Electrochemistry:Ion-selective electrodes and amperometric sensors enable point-of-care electrolyte and glucose testing with minimal sample volume.
Spectrophotometry anchors routine throughput. Chromatography gains share fastest as send-out testing economics improve.
Application:
Volume concentration varies sharply: metabolic and cardiovascular panels generate daily throughput, while oncology and infectious disease applications carry premium pricing per reportable result.
- Oncology:Companion diagnostic assays with FDA-approved drug labels require validated biomarker quantification. United States cancer centers are consolidating testing into centralized molecular pathology laboratories.
- Infectious Diseases:Automated sepsis panels with procalcitonin and proadrenomedullin markers support antimicrobial stewardship mandates. Chinese tertiary hospitals are expanding infectious disease testing lines to meet 40,000+ daily sample volumes.
- Metabolic Disorders:Diabetes and lipid panels constitute the highest test frequency in routine chemistry menus.
- Cardiovascular Diseases:High-sensitivity troponin protocols are displacing legacy CK-MB and myoglobin assays in emergency department triage.
Metabolic disorders sustain the installed base. Infectious disease testing climbs the fastest as sepsis protocol compliance tightens.
End User:
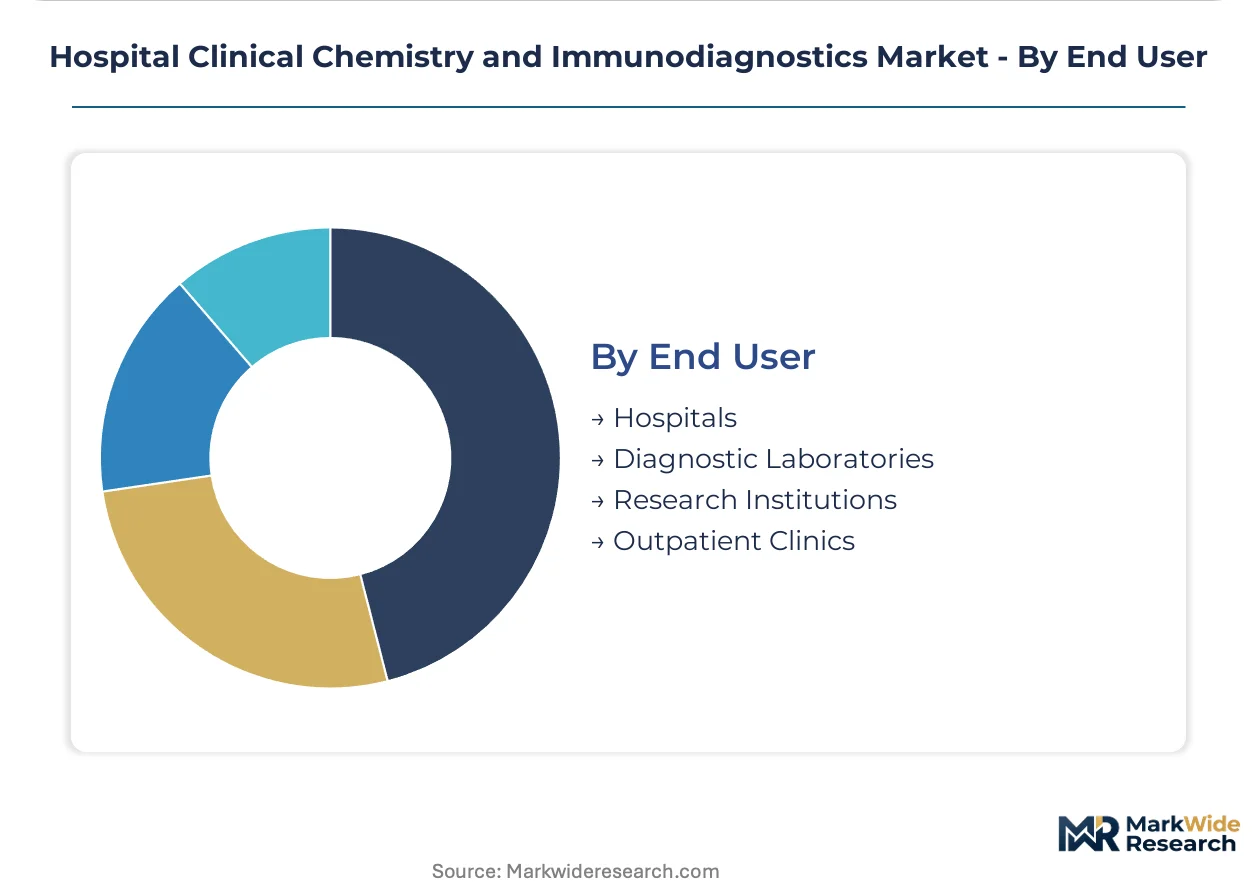
Customer type determines contract structure: hospitals negotiate enterprise pricing through GPOs, while outpatient clinics and research institutions purchase through distributor channels with less volume leverage.
- Hospitals:Integrated delivery networks in the United States and hospital chains in Germany concentrate procurement into multi-year sole-source agreements. Three GPOs control 70 percent of acute care purchasing, forcing analyzer vendors into locked reagent supply terms.
- Diagnostic Laboratories:Independent reference labs and hospital-affiliated outreach programs seek flexible reagent rental models to minimize capital expenditure.
- Research Institutions:Academic medical centers require research-use-only assay formats with customizable analyte menus.
- Outpatient Clinics:Federally qualified health centers and physician office laboratories favor waived-complexity devices under CLIA regulations.
Hospitals command the established base. Diagnostic laboratories represent the steepest expansion trajectory as hospital outreach programs capture ambulatory testing volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analyzer manufacturing clusters in Germany, the United States, and Switzerland supply the bulk of installed-base hardware, while demand concentrates in hospital systems consolidating procurement across North America, Western Europe, and East Asia.
United States
Integrated delivery networks in Texas and Florida are converting emergency departments to high-sensitivity troponin protocols. FDA premarket notification pathways under 21 CFR Part 862 compress validation timelines for companion diagnostics. The Mayo Clinic in Rochester anchors reference laboratory demand for mass spectrometry-based steroid panels.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia automate chemistry lines processing 40,000-plus daily samples. The EU In Vitro Diagnostic Regulation imposes annual post-market surveillance reporting that strains mid-tier manufacturers. Siemens Healthineers maintains its headquarters and primary R&D operations in Erlangen.
China
Tertiary hospitals in Shanghai and Beijing are expanding infectious disease testing capacity to meet sepsis protocol mandates. NMPA clearance pathways for class III IVD devices require local clinical trials. Mindray Medical International anchors domestic analyzer production in Shenzhen with growing export penetration.
India
Tier-2 cities in Maharashtra and Gujarat lack automated chemistry infrastructure, creating whitespace for reagent rental business models. CDSCO import licensing requirements for IVD analyzers add regulatory friction for foreign vendors. The All India Institute of Medical Sciences in Delhi serves as the national reference laboratory for harmonization studies.
Japan
University hospitals in Tokyo and Osaka are consolidating oncology companion diagnostic testing into centralized molecular pathology laboratories. PMDA reimbursement negotiations for novel biomarker assays extend commercialization timelines. Sysmex Corporation anchors domestic hematology and immunoassay production in Kobe.
Hospital Clinical Chemistry and Immunodiagnostics Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates controlling integrated analyzer-reagent ecosystems. Three manufacturers account for the majority of installed-base chemistry-immunoassay platforms in Western hospital systems. Strategic archetypes separate platform-integrated conglomerates from decentralized automation specialists and emerging regional challengers. Competitive moves center on sole-source contract lock-ins through long-term reagent supply agreements and modular system architectures that reduce laboratory footprint requirements.
Among Swiss and German-based platform-integrated conglomerates, Roche Diagnostics and Siemens Healthineers exemplify the installed-base defense archetype through cobas and Atellica system standardization. Abbott Laboratories anchors the North American competitive position through Alinity ecosystem consolidation. These three conglomerates represent the premium-tier vector where analyzer placement economics drive decade-long reagent capture.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Ortho Clinical Diagnostics |
| bioMérieux |
| Beckman Coulter |
| Mindray Medical International |
| Others |
Supply & Pricing Matrix
Ninety-day reagent inventory cycles at United States integrated delivery networks compress procurement leverage while amplifying sole-source contract pricing power for analyzer vendors with locked consumable supply terms. This inventory-service dynamic concentrates margin capture in reagent streams tethered to installed-base placements across Germany and China.
Pricing Analysis
CLIA proficiency standards dictate the pricing tier structure across hospital laboratory contracts in the United States. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic platforms from CLIA-waived point-of-care devices and research-use-only assay formats. Price differentiation rests on certification grade and volume scale, with antimicrobial stewardship mandates driving cost compression in infectious disease panels. Academic medical centers exhibit lowest price sensitivity due to federal infrastructure subsidies, while outpatient clinics face acute budget constraints under CLIA reimbursement ceilings.
Supply Chain Analysis
Strategic stockpiling of liquid-stable reagents dominates hospital procurement to mitigate NIST-traceable calibrator lead time volatility. Manufacturing concentrates in Germany, Switzerland, and the United States for modular analyzer platforms, while China anchors domestic production for 40,000-sample-per-day chemistry lines. Raw material dependencies span rare-earth magnets for electromechanical components, specialized optical glass for spectrophotometry modules, and recombinant antibody reagents for immunoassay kits. Single-source vulnerability in proprietary control materials generates tariff exposure for European Union imports under EU IVDR documentation burdens. Distribution runs through group purchasing organizations capturing seventy percent of acute care volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent rental models and long-term consumable supply contracts expand faster than hardware placements as hospital systems prioritize operational expenditure over capital allocation. This service-attach dynamic rewards vendors with dense installed-base footprints and regulatory compliance infrastructure.
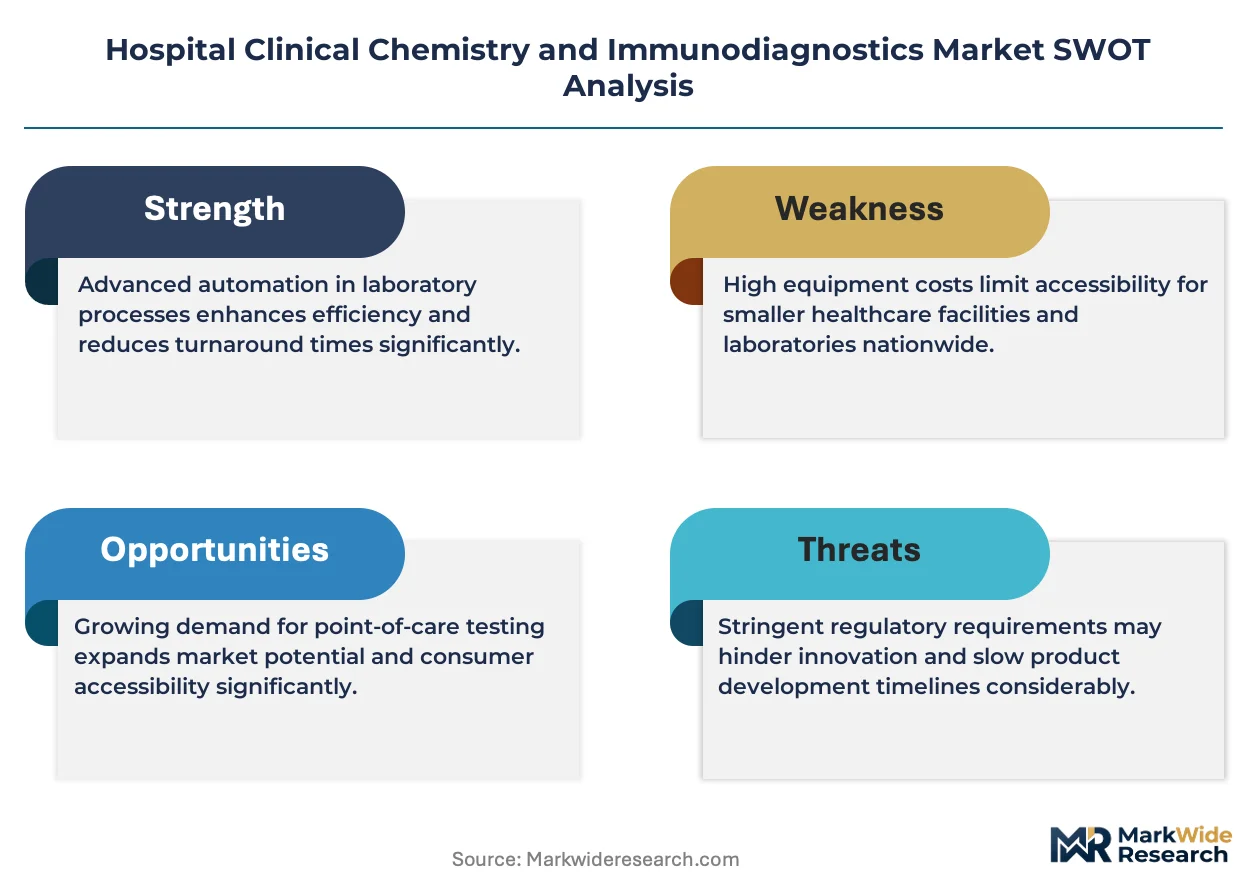
For Market Incumbents: Secure sole-source contract renewals through modular analyzer architectures that reduce laboratory footprint requirements in space-constrained facilities. Defend against mass spectrometry displacement in endocrinology panels by accelerating chemiluminescent assay specificity improvements. Prioritize backward integration into NIST-traceable reference material production to capture calibrator margin pools. For New Entrants and Emerging Players: Anchor in India's Tier-2 and Tier-3 cities where automated chemistry infrastructure remains underpenetrated and reagent rental models minimize capital barriers. Target Maharashtra and Gujarat hospital networks with localized regulatory affairs support for CDSCO import licensing. Deploy point-of-care immunoassay convergence devices combining electrochemical detection with microfluidic processing for decentralized testing workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier IVD manufacturers burdened by EU IVDR post-market surveillance documentation costs without dedicated regulatory infrastructure. Long-term viability favors platform-integrated conglomerates with analyzer-reagent ecosystem control and installed-base lock-in economics. Monitor antimicrobial stewardship penalty enforcement as inflection indicator for infectious disease panel demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Model Expansion | Minimizes capital barriers for Tier-2 Indian hospitals while locking long-term consumable revenue streams. |
| EU IVDR Regulatory Infrastructure Buildout | Enables annual performance reporting compliance for class C and D oncology companion diagnostics. |
| High-Sensitivity Troponin Protocol Conversion | Captures emergency department cardiac marker replacement cycles across United States IDN networks. |
| Mass Spectrometry Send-Out Partnership | Defends steroid and vitamin D quantification share against reference laboratory LC-MS/MS displacement. |
| Antimicrobial Stewardship Panel Automation | Aligns sepsis protocol compliance with CMS penalty avoidance in United States hospital systems. |
Research Methodology
A spread of perspectives from hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at IVD manufacturers converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EU IVDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up analyzer placement counts triangulated against top-down reagent consumption estimates across the analysis window.
Segmentation dimensions modeled include product type, technology platform, clinical application, and end-user facility tier across the projection horizon. CAGRs derived from historical installed-base growth rates, replacement cycle compression, and penetration assumptions in whitespace geographies. Forecast inputs incorporated antimicrobial stewardship mandate enforcement timelines and high-sensitivity troponin protocol conversion rates.
Material uncertainties — regulatory clearance delays, reagent supply disruptions, and hospital consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions about CLIA and EU IVDR compliance stability. Revision becomes warranted when group purchasing organization concentration crosses thresholds altering sole-source contract negotiability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Precision Diagnostics Market