
 Global Tissue Diagnostics Market | 2026-2036
Global Tissue Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tissue Diagnostics Market Foresight
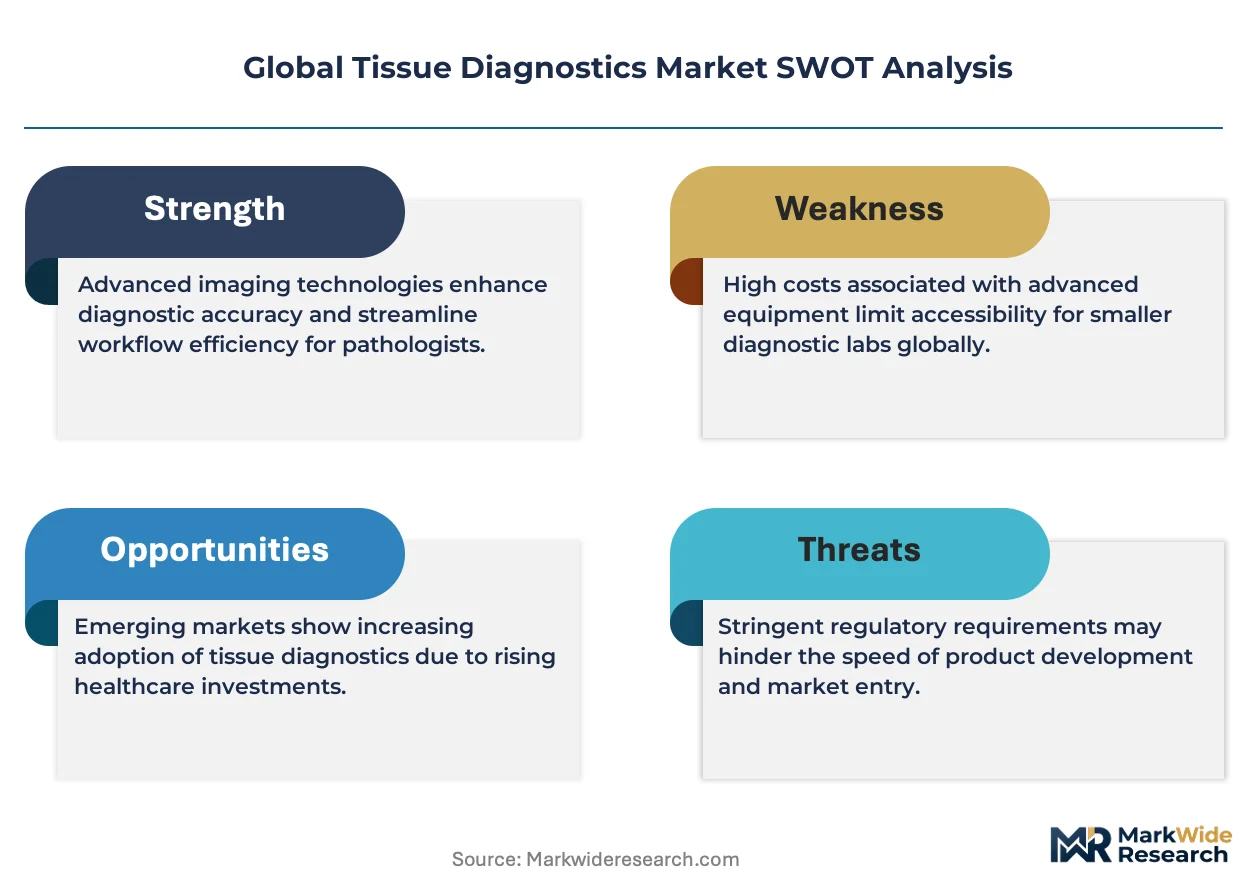
EU MDR is consolidating the cost-of-entry calculus for tissue diagnostics vendors seeking European market access. Roche Diagnostics leverages its installed base of automated immunohistochemistry platforms to sustain service revenue across clinical laboratories. Thermo Fisher Scientific anchors its position through backward integration into reagent manufacturing and controlled distribution of molecular diagnostics kits. Agilent Technologies differentiates via specialized in situ hybridization probe portfolios that command premium positioning in cancer profiling workflows.
Tissue diagnostics encompasses the histopathological and molecular analysis of preserved tissue specimens using antibody-based staining, nucleic acid probes, or spectrometric imaging to detect disease markers at cellular resolution. The primary purpose is enabling definitive diagnosis, biomarker quantification, and therapy selection in oncology and infectious pathology. Immunohistochemistry reagents occupy the largest revenue pool given their ubiquity in hospital labs, while digital pathology systems represent the fastest-expanding segment as artificial intelligence analytics reshape slide interpretation workflows. Cancer profiling dominates application demand, though biomarker discovery commands outsized R&D investment from pharmaceutical companies seeking companion diagnostic pairings.
FDA oversight of companion diagnostics, EMA's MDR conformity requirements, and China's NMPA registration pathways for imported IVD reagents collectively shape product development timelines and market access strategies. These frameworks elevate documentation burdens but simultaneously reward vendors with validated assay portfolios. Stakeholders must monitor how artificial intelligence analytics integration triggers new regulatory classification debates across FDA, EMA, and NMPA jurisdictions.
Market Dynamics
Artificial intelligence integration into digital pathology workflows is compressing diagnostic turnaround times and forcing incumbents to restructure their software licensing models around algorithmic performance rather than hardware throughput.
Growth Catalysts
- Companion diagnostic mandates:FDA's tightened validation requirements for oncology drug pairings are expanding the addressable market for validated immunohistochemistry assays in clinical laboratories.
- China's precision oncology scale-up:NMPA registration pathway streamlining for imported IVD reagents is accelerating market entry for multinational reagent manufacturers serving tertiary hospital networks.
- Automated staining platform proliferation:Hospital pathology laboratories in Germany and the United States are replacing manual workflows with integrated slide processing systems that reduce technician-to-specimen ratios.
Market Restraints
- EU MDR documentation burden:EMA conformity assessment timelines for in vitro diagnostic reagents have extended by 12-18 months, freezing product launch schedules for mid-tier manufacturers lacking notified body relationships.
- Fluorophore and chromogen supply concentration:Specialty dye synthesis capabilities cluster with German and Swiss chemical suppliers, exposing reagent vendors to input cost volatility and single-source risk.
- Digital pathology interoperability gaps:Proprietary image formats from scanner manufacturers lock hospital systems into vendor-specific ecosystems, retarding multi-site network deployment.
Strategic Opportunities
- India's diagnostic infrastructure buildout:CDSCO streamlined import licensing for IVD reagents coincides with government hospital pathology modernization programs in Maharashtra and Karnataka.
- Multiplex immunofluorescence convergence:Integration of spectral unmixing algorithms with high-plex antibody panels enables single-slide biomarker quantification that displaces serial sectioning workflows.
- Pharmaceutical-sponsored assay development:Biomarker discovery contracts from oncology drug developers provide captive revenue streams for diagnostic firms willing to co-invest in companion diagnostic validation.
Industry Challenges
- Computational pathology talent scarcity:Hospital laboratories lack personnel capable of validating AI-assisted image analysis algorithms against ground-truth pathologist reads, slowing regulatory submission timelines.
- Legacy LIS integration complexity:Digital pathology platforms must interface with decades-old laboratory information systems that lack standardized APIs, inflating implementation costs and delaying go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tissue Diagnostics Market |
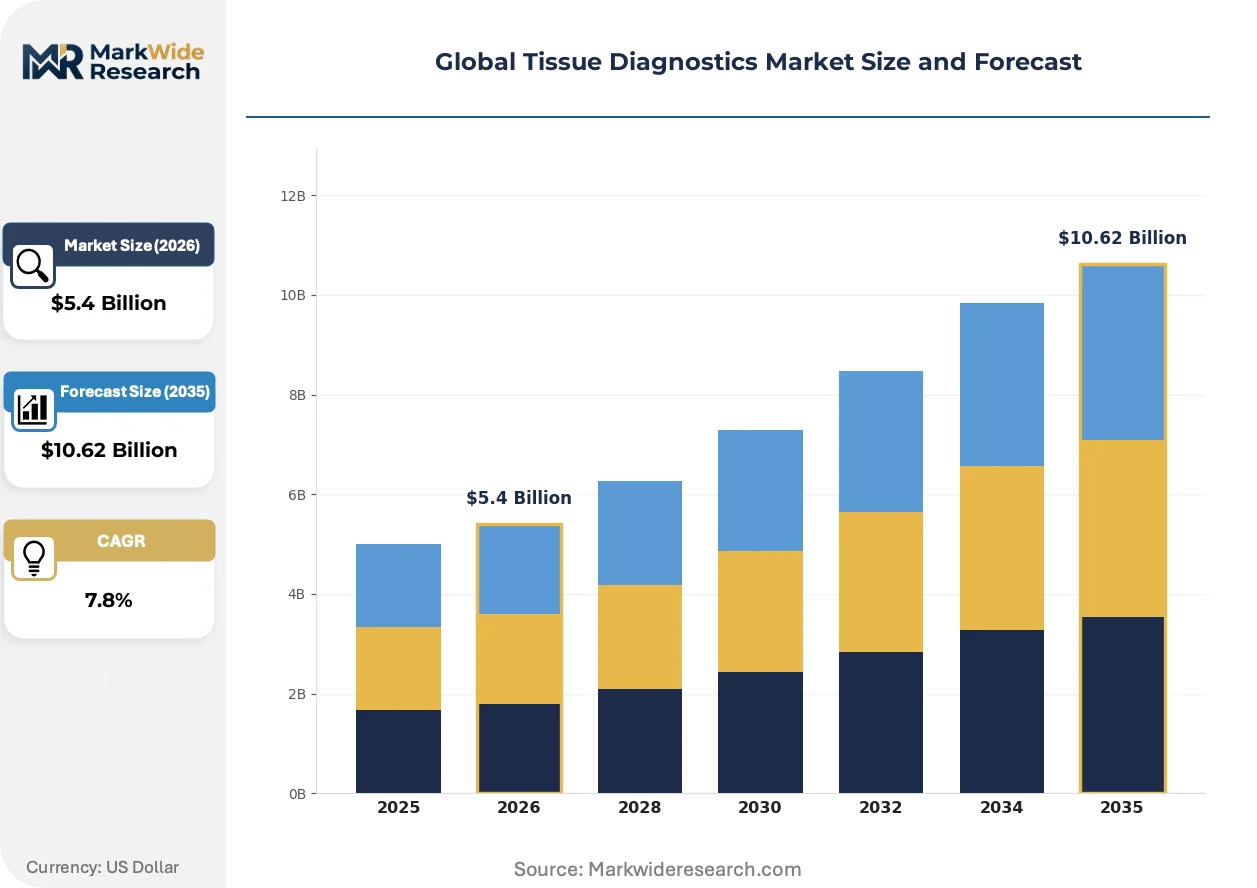
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $10.62 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunohistochemistry Reagents, In Situ Hybridization Probes, Molecular Diagnostics Kits, Tissue Microarrays, Digital Pathology Systems Application: Cancer Profiling, Infectious Disease Detection, Genetic Disorder Analysis, Biomarker Discovery, Personalized Treatment Planning End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Academic Centers Technology: Fluorescence Microscopy, Confocal Microscopy, Multiplex Immunoassays, Mass Spectrometry Imaging, Artificial Intelligence Analytics |
| Companies Covered | Roche Diagnostics, Thermo Fisher Scientific, Agilent Technologies, Danaher Corporation, Siemens Healthineers, Abbott Laboratories, Merck KGaA, QIAGEN, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tissue Diagnostics Market Shifts & Advancements
Deep learning algorithms trained on whole-slide images are reshaping how pathologists prioritize case review, with regulatory frameworks scrambling to classify software-as-medical-device across FDA, EMA, and NMPA jurisdictions.
Spatial transcriptomics platforms are absorbing capital allocation from traditional gene expression profiling as pharmaceutical researchers demand sub-cellular resolution for immuno-oncology target validation. Contract research organizations in Boston and Basel have scaled dedicated facilities around 10x Genomics and NanoString technologies. The shift is absorbing service revenue from centralized reference laboratories that previously dominated bulk RNA sequencing workflows.
EMA's Medical Device Regulation is forcing reagent manufacturers to rebuild technical documentation around clinical performance evidence rather than analytical validation alone. Small and mid-sized IVD firms face notified body capacity constraints that delay CE marking renewals. The regulation most acutely affects specialized in situ hybridization probe suppliers serving European cancer centers.
Pathology departments are consolidating purchasing decisions under health system central procurement offices rather than maintaining autonomous laboratory budgets. Academic medical centers in the United States now route staining platform acquisitions through value analysis committees that benchmark total cost of ownership across five-year horizons. The behavioral shift is most visible in multi-hospital integrated delivery networks seeking volume-based reagent pricing from sole-source vendors.
Global Tissue Diagnostics Market Segmentation
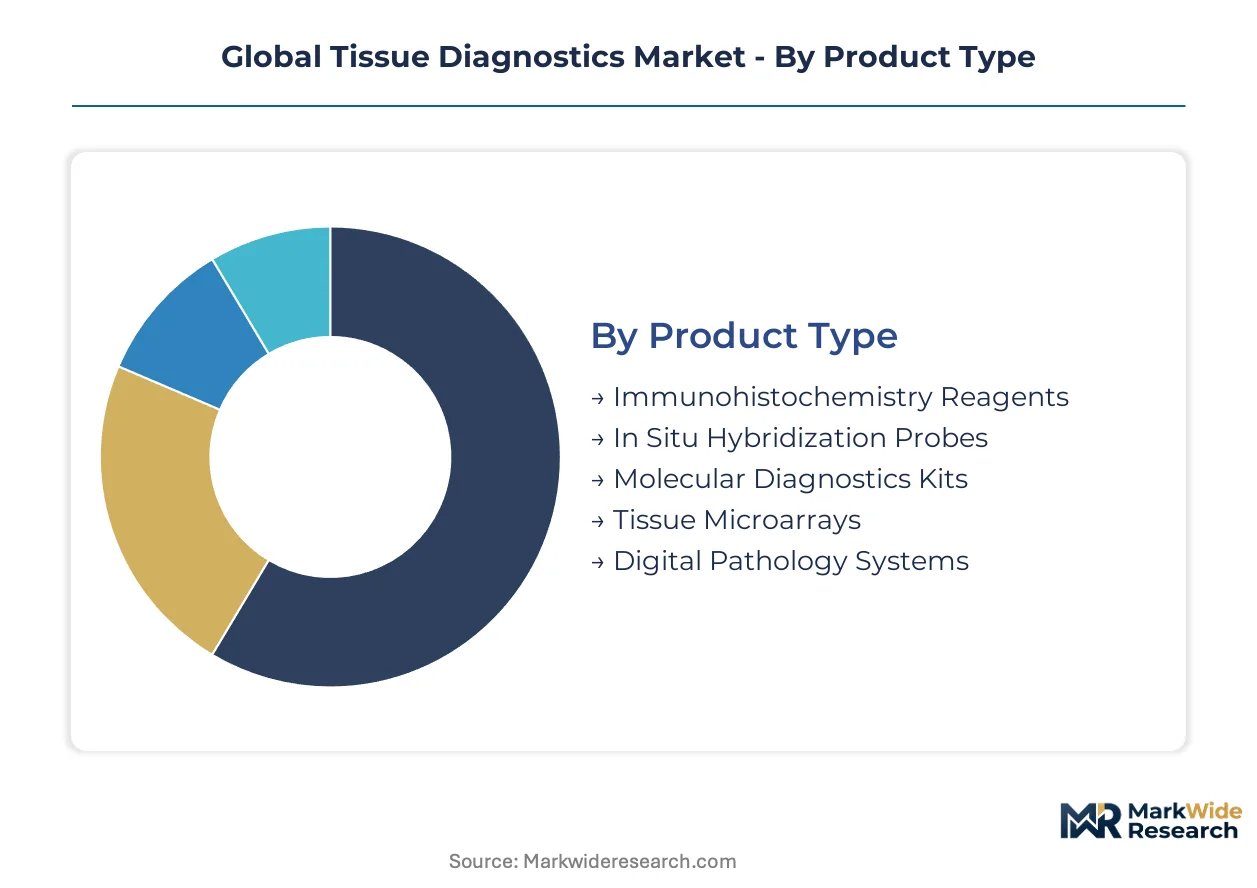
Tissue diagnostics segmentation reflects divergent supply chain economics across reagent manufacturing, instrumentation hardware, and software analytics. Vendors optimize portfolios around whether their core competency lies in chemical synthesis, optical engineering, or algorithm development.
Product Type:
Supply concentration varies sharply across this category, with chemical synthesis capabilities clustering in specialized geographies while hardware assembly disperses globally.
- Immunohistochemistry Reagents:Antibody-chromogen formulations for protein detection in formalin-fixed tissue sections. Hospital pathology laboratories in the United States and Germany consume the majority of output as automated staining platforms proliferate; FDA companion diagnostic mandates tighten validation requirements for antibody specificity.
- In Situ Hybridization Probes:Nucleic acid probes labeled with fluorophores or chromogens for chromosomal and gene expression localization. European cancer centers in Switzerland and the Netherlands drive premium demand; EMA MDR documentation burdens extend notified body review timelines for probe manufacturers.
- Molecular Diagnostics Kits:PCR and NGS-based reagent systems for nucleic acid extraction and amplification from tissue specimens.
- Tissue Microarrays:Paraffin blocks containing hundreds of tissue cores for high-throughput biomarker screening.
- Digital Pathology Systems:Whole-slide imaging scanners and storage infrastructure for digitized histopathology workflows.
Immunohistochemistry reagents absorb the bulk of installed capacity; digital pathology systems are expanding most quickly.
Application:
Application demand tiers separate according to reimbursement certainty and pharmaceutical sponsorship intensity.
- Cancer Profiling:Histopathological and molecular characterization of tumor specimens for diagnosis, staging, and therapy selection. Tertiary hospital networks in China and the United States scale precision oncology programs; NMPA streamlined registration accelerates multinational reagent entry.
- Biomarker Discovery:Exploratory research to identify predictive or prognostic molecular signatures for drug development. Contract research organizations in Boston and Basel dominate service demand; spatial transcriptomics platforms displace bulk sequencing workflows for immuno-oncology target validation.
- Infectious Disease Detection:Tissue-based identification of viral, bacterial, or fungal pathogens in immunocompromised patients.
- Genetic Disorder Analysis:Chromosomal and gene-level testing for hereditary conditions using tissue biopsies.
- Personalized Treatment Planning:Integration of multi-omic data to guide individualized therapy selection.
Cancer profiling commands the largest revenue pool; biomarker discovery exhibits the steepest expansion trajectory as pharmaceutical R&D budgets reallocate toward companion diagnostic co-development.
End User:
Customer procurement sophistication determines pricing power and contract structure across this category.
- Diagnostic Laboratories:Commercial and hospital-affiliated labs performing routine clinical testing on patient specimens. Integrated delivery networks in the United States centralize purchasing through value analysis committees; total cost-of-ownership benchmarking extends to five-year horizons.
- Pharmaceutical Companies:Drug developers requiring validated assays for clinical trial patient stratification and companion diagnostic registration. Oncology-focused firms sponsor biomarker discovery contracts; diagnostic partners co-invest in FDA validation studies for drug-diagnostic pairings.
- Research Institutes:Government and non-profit facilities conducting fundamental pathology and oncology research.
- Biotechnology Firms:Emerging therapeutic developers with outsourced diagnostic needs.
- Academic Centers:University medical schools combining clinical service with research and training missions.
Diagnostic laboratories represent the highest-volume customer segment; pharmaceutical companies deliver the strongest pricing premiums through sponsored assay development agreements.
Technology:
Technology maturity curves separate established optical methods from emerging computational and multi-plexing platforms.
- Artificial Intelligence Analytics:Deep learning algorithms for automated image analysis, pattern recognition, and diagnostic prioritization in digital pathology. Regulatory classification debates span FDA, EMA, and NMPA jurisdictions as software-as-medical-device frameworks evolve; hospital laboratories lack personnel to validate algorithms against ground-truth pathologist reads.
- Multiplex Immunoassays:Spectral unmixing algorithms combined with high-plex antibody panels for single-slide biomarker quantification. Research institutes in Germany and Massachusetts adopt platforms that displace serial sectioning workflows; fluorophore supply concentration with German and Swiss chemical suppliers creates input cost volatility.
- Fluorescence Microscopy:Widefield and epifluorescence systems for visualizing labeled tissue specimens.
- Confocal Microscopy:Laser-scanning optical sectioning for high-resolution three-dimensional tissue imaging.
- Mass Spectrometry Imaging:Label-free molecular mapping of tissue sections for metabolite and lipid localization.
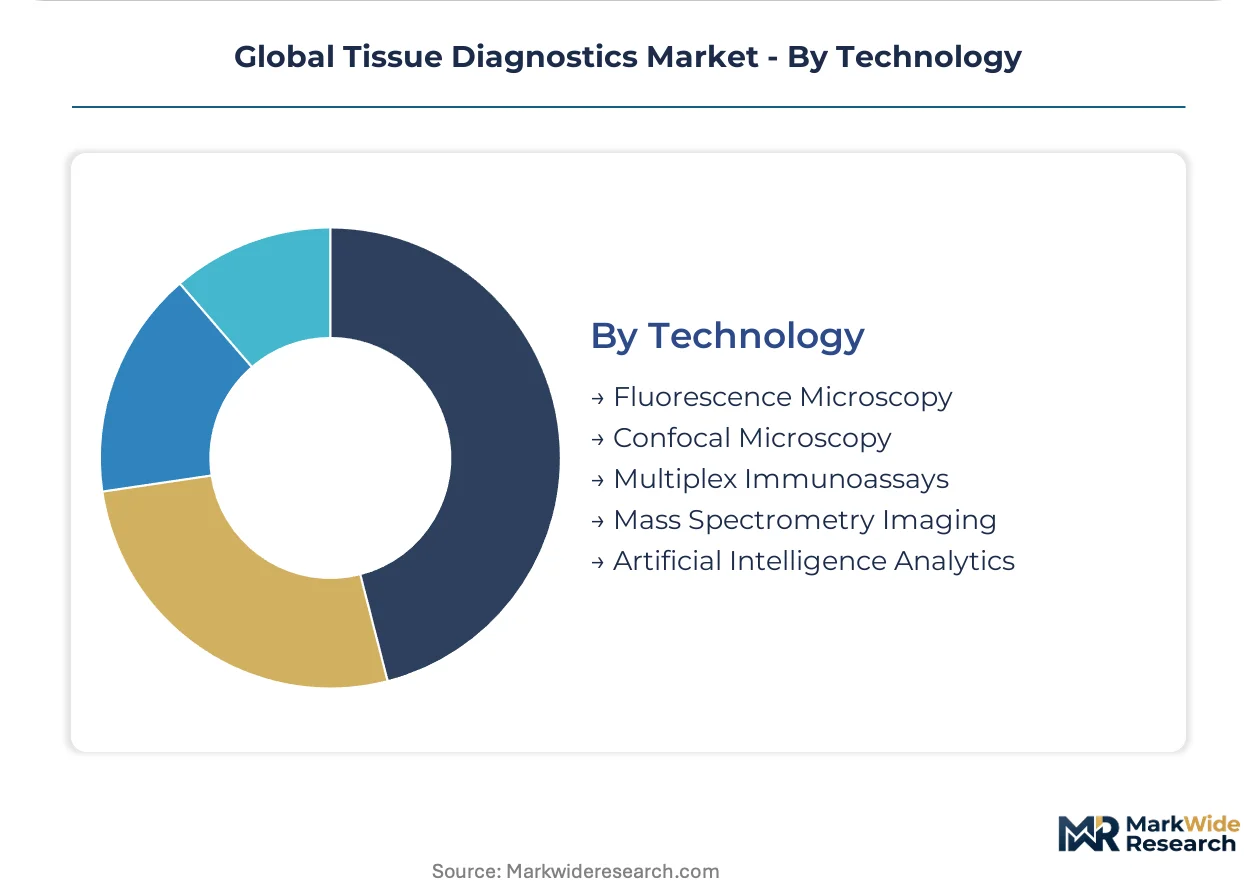
Fluorescence microscopy retains the largest installed instrument base; artificial intelligence analytics is gaining share fastest as pathology departments prioritize diagnostic throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biohub special economic zones in Singapore and Shenzhen concentrate precision medicine infrastructure investments that reshape tissue diagnostics procurement patterns across hospital networks.
United States
Precision oncology programs at MD Anderson and Memorial Sloan Kettering drive companion diagnostic assay demand. FDA tightened validation requirements for immunohistochemistry drug pairings in 2024. The Boston-Cambridge corridor anchors pharmaceutical-sponsored biomarker discovery contracts with contract research organizations.
Germany
University hospital pathology laboratories in Heidelberg and Munich replace manual staining workflows with automated platforms. EMA MDR conformity assessments extend notified body review timelines for in vitro diagnostic reagents. The Rhine-Main cluster concentrates specialty fluorophore synthesis capabilities among German and Swiss chemical suppliers.
China
Tertiary hospital networks in Shanghai and Guangzhou scale precision oncology programs with government funding. NMPA streamlined registration pathways for imported immunohistochemistry reagents accelerate multinational market entry. The Yangtze River Delta absorbs capital allocation for digital pathology infrastructure deployments.
Switzerland
Basel-based pharmaceutical headquarters sponsor companion diagnostic co-development agreements with diagnostic partners. Swissmedic oversees medical device conformity assessments for in situ hybridization probe portfolios. The Lake Geneva region concentrates contract research organization facilities serving immuno-oncology target validation.
India
Government hospital pathology modernization programs in Maharashtra and Karnataka expand automated staining platform procurement. CDSCO streamlined import licensing for immunohistochemistry reagents reduces market entry friction. The Mumbai-Pune corridor attracts diagnostic infrastructure buildout from multinational reagent manufacturers.
Global Tissue Diagnostics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across reagent manufacturing, instrumentation hardware, and software analytics segments. The market structure consolidates around vendors with validated assay portfolios that satisfy FDA companion diagnostic mandates. Three archetypes dominate: integrated life science conglomerates with backward control over reagent supply chains, specialized probe manufacturers commanding premium positioning in cancer profiling workflows, and digital pathology platform vendors restructuring licensing models around algorithmic performance. Competitive moves concentrate on M&A activity to acquire spectral unmixing capabilities and strategic partnerships with pharmaceutical developers for biomarker discovery contracts.
Among integrated life science conglomerates, Roche Diagnostics and Thermo Fisher Scientific exemplify archetypes built on installed base leverage and captive reagent manufacturing respectively. Agilent Technologies occupies a position within the specialized probe manufacturer tier. These three anchors represent distinct strategic postures: service revenue sustainment across clinical laboratories, backward integration into controlled distribution networks, and premium positioning through differentiated in situ hybridization portfolios.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Danaher Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Merck KGaA |
| QIAGEN |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Hospital pathology laboratory consolidation under integrated delivery networks is compressing reagent procurement timelines and forcing manufacturers to hold regional safety stock, inflating working capital requirements and compressing margins on standard-grade immunohistochemistry formulations.
Pricing Analysis
Short lead-time premiums of 15-25% apply to validated companion diagnostic assays required for FDA-mandated oncology drug pairings, while spot inventory of research-grade antibodies trades at discounts. The dominant structure is contract-based long-term offtake with five-year total cost-of-ownership benchmarking. Price differentiation rests on FDA validation tier and automated platform compatibility certification. Cost compression in standard-grade reagents is intensifying because German and Swiss hospital networks are consolidating purchasing through central procurement offices. Academic medical centers exhibit highest price sensitivity; pharmaceutical sponsors of companion diagnostic co-development agreements show least sensitivity.
Supply Chain Analysis
CE marking and FDA 510(k) clearance gates create 18-24 month qualification timelines that freeze out uncertified chemical suppliers. Specialty fluorophore and chromogen synthesis concentrates in Germany, Switzerland, and Japan. Raw material dependencies include high-purity optical dyes, monoclonal antibody cell lines, and precision-machined optical components. Single-source vulnerability runs through Swiss-German dye manufacturers exposed to energy cost volatility. Distribution feeds from centralized reagent manufacturing hubs through regional cold-chain logistics partners serving hospital networks and reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around validated assay portfolios, with FDA companion diagnostic mandates and EMA MDR documentation burdens forcing mid-tier manufacturers lacking notified body relationships toward exit or acquisition.
For Market Incumbents: Lock in automated platform installed bases through exclusive reagent supply contracts that embed multi-year service agreements. Deepen backward integration into antibody manufacturing to reduce dependence on contract cell-line developers. The priority lever is acquiring spectral unmixing algorithm capabilities from spatial transcriptomics specialists before pharmaceutical sponsors internalize those competencies. For New Entrants and Emerging Players: Begin with India's CDSCO-streamlined import licensing environment, where government hospital pathology modernization in Maharashtra and Karnataka outpaces established vendor coverage. Target research-grade tissue microarray supply to contract research organizations in Boston and Basel as the most penetrable segment. The go-to-market angle is positioning as a flexible development partner for pharmaceutical biomarker discovery contracts that incumbents deprioritize. For Investors and Strategic Acquirers: Re-rating potential sits with specialized in situ hybridization probe manufacturers given EMA MDR consolidation pressure on European cancer center supply chains. Long-term viability favors archetypes with captive fluorophore synthesis capabilities and validated companion diagnostic pipelines. The signal to watch is NMPA registration pathway streamlining completion, which would accelerate multinational reagent entry into Chinese tertiary hospital networks and trigger acquisition premiums for CDSCO-registered Indian distribution platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Validation Partnership | Secures captive revenue from oncology drug developers seeking FDA-mandated assay pairings. |
| Automated Platform Integration | Locks hospital laboratories into recurring reagent consumption through proprietary cartridge systems. |
| Spectral Unmixing Capability Acquisition | Enables single-slide multiplex quantification that displaces serial sectioning in cancer profiling workflows. |
| Regional Distribution Hub Establishment | Reduces lead times for NMPA-registered reagents serving Yangtze River Delta hospital networks. |
| AI-Assisted Image Analysis Regulatory Submission | Positions software-as-medical-device offerings ahead of FDA, EMA, and NMPA classification debates. |
Research Methodology
Document review covered FDA 510(k) filings, EMA MDR technical documentation, NMPA registration databases, and hospital procurement records, complemented by interviews with pathology department heads, diagnostic laboratory procurement managers, pharmaceutical biomarker discovery leads, and IVD regulatory affairs specialists. Secondary validation drew from GPO contract databases, CMS Medicare reimbursement schedules, and academic medical center capital expenditure disclosures. Bottom-up triangulation across reagent consumption models and top-down cross-checks against instrument installed base estimates anchored market sizing.
Output metrics span revenue pools across immunohistochemistry reagents, in situ hybridization probes, molecular diagnostics kits, and digital pathology systems, with segmentation by cancer profiling, biomarker discovery, and infectious disease applications. Modeled dimensions include technology maturity curves from fluorescence microscopy through artificial intelligence analytics, end-user procurement sophistication tiers, and regional regulatory framework clusters. CAGRs were derived from instrument replacement cycles, precision oncology program scale-up trajectories, and companion diagnostic mandate expansion patterns.
Underlying measurement precision varies by segment; digital pathology system deployments and pharmaceutical-sponsored assay development contracts carry tighter precision than research-grade reagent consumption in academic settings. Forecasts reflect assumptions around NMPA pathway streamlining completion, EMA notified body capacity constraints, and AI diagnostic software classification timelines. A model refresh is warranted upon material change in FDA companion diagnostic validation requirements or CDSCO import licensing procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Global Urinalysis Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Europe Blood Screening Market