
 Companion Diagnostics Market | 2026-2036
Companion Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Diagnostics Market Analysis
IVD regulation is rebalancing how pharmaceutical firms structure co-development agreements. F. Hoffmann-La Roche Ltd. leverages its integrated diagnostics-pharmaceutical model to sustain long-term therapy-test alliances. QIAGEN anchors its position through sample-to-insight workflows that span assay design through clinical validation. Illumina, Inc. competes by extending next-generation sequencing infrastructure into companion diagnostic workflows for oncology programs.
Companion diagnostics comprise in vitro tests that identify biomarker-defined patient subpopulations eligible for specific drug therapies, typically requiring nucleic acid extraction with PCR amplification or immunohistochemistry staining on formalin-fixed tissue. These tests enable targeted therapeutic decisions by linking molecular profiles to drug response probability, reducing exposure to ineffective treatments. Nucleic acid testing and next-generation sequencing segments lead technology adoption as oncology applications command the deepest R&D investment and fastest test validation cycles. Pharmaceutical companies represent the most concentrated end-user segment, driven by regulatory mandates for biomarker-stratified trials and post-market surveillance requirements.
FDA, EMA, and WHO frameworks govern analytical validation standards, clinical utility evidence, and post-market performance monitoring for companion diagnostics. These bodies shape demand by requiring prospective biomarker validation in registrational trials, which elevates development costs while creating barriers for non-integrated entrants. Stakeholders must monitor evolving evidentiary standards for real-world data acceptance and decentralized testing modalities to anticipate where regulatory flexibility or stringency will redirect capital deployment.
Market Dynamics
Precision oncology pipelines are forcing pharmaceutical firms to lock in biomarker-validated testing infrastructure before registrational trials commence, compressing development timelines and elevating co-development contract values.
Growth Catalysts
- EMA biomarker qualification pathways:Streamlined scientific advice for companion diagnostic developers accelerates parallel drug-test submissions across European markets.
- Liquid biopsy specimen workflows:Circulating tumor DNA extraction methods reduce tissue acquisition barriers in metastatic cancer settings, expanding addressable patient populations.
- Oncology therapeutic pipelines:FDA mandates for prospective stratification in Phase III trials create embedded demand for validated assays before commercial launch.
Market Restraints
- Reference material scarcity:Well-characterized positive control specimens for rare fusion variants constrain analytical validation throughput.
- Reimbursement lag:CMS coverage determinations for novel biomarker tests trail FDA approvals by 18-24 months in United States markets.
- Platform fragmentation:Proprietary PCR chemistries and NGS library prep methods lock laboratories into single-vendor ecosystems, limiting operational flexibility.
Strategic Opportunities
- Minimal residual disease monitoring:Post-treatment surveillance applications for ctDNA quantification open recurring revenue streams beyond initial diagnostic testing.
- CDx-IVD harmonization:WHO prequalification pathways for tuberculosis and HIV companion tests create template mechanisms for oncology expansion in low-income settings.
- Automated sample-to-result systems:Integrated nucleic acid extraction and real-time PCR platforms reduce manual handling errors in decentralized hospital laboratories.
Industry Challenges
- Bioinformatics pipeline validation:Variant calling algorithms for NGS-based assays require continuous retraining as reference databases expand, straining quality management systems.
- Clinical utility evidence generation:Payer demands for prospective health economic data extend post-market study timelines beyond original regulatory commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Diagnostics Market |
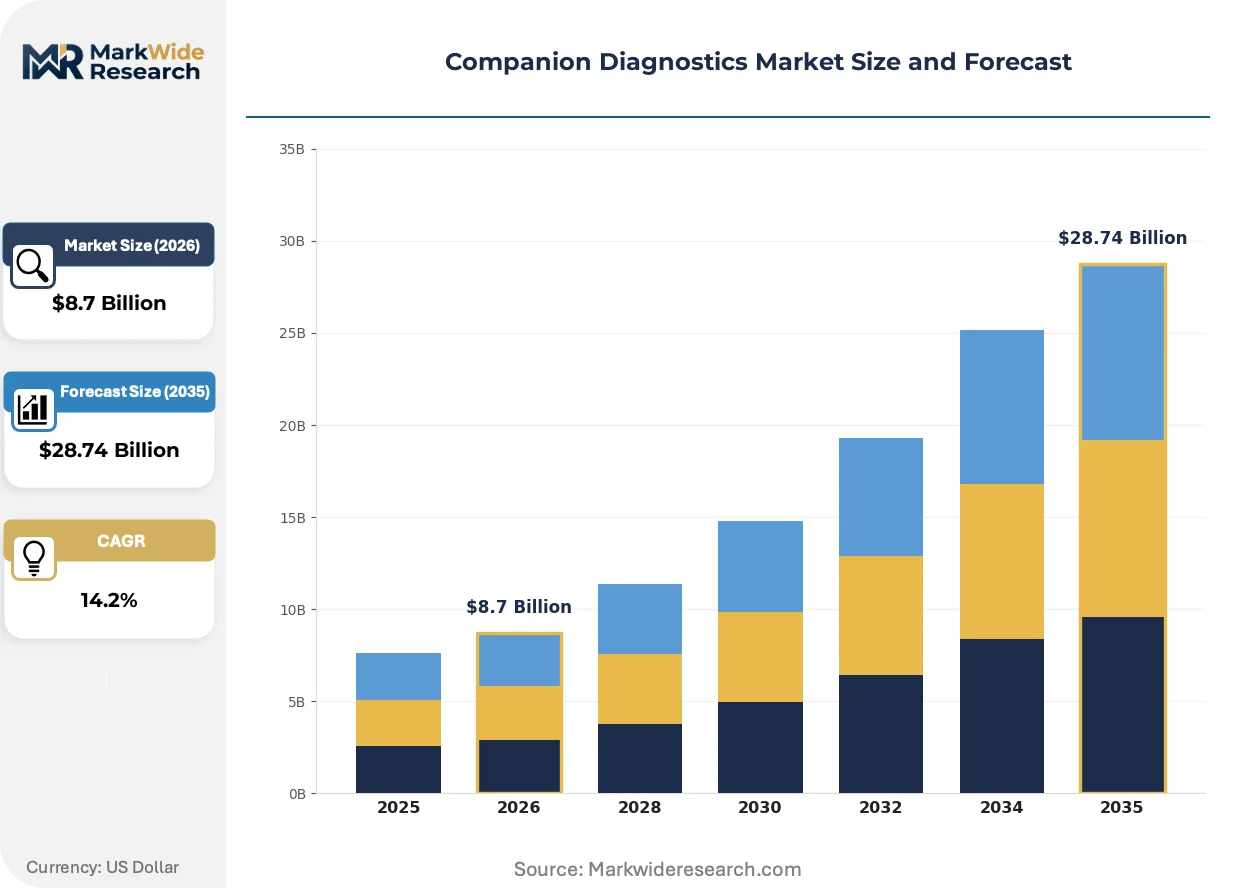
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
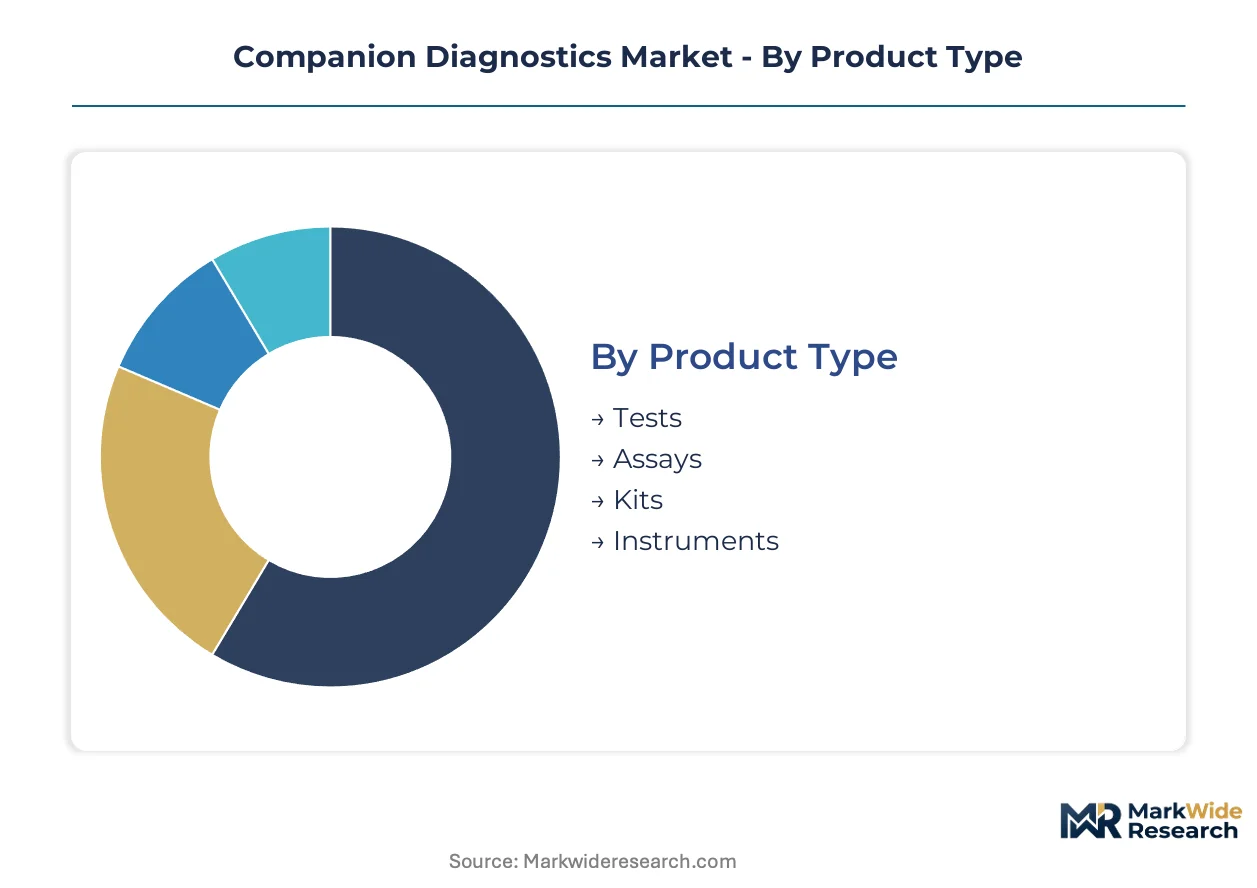
| Segmentation | Product Type: Tests, Assays, Kits, Instruments Technology: Nucleic Acid Testing, Immunohistochemistry, PCR, Next-Generation Sequencing End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Clinics Application: Oncology, Infectious Disease, Neurology, Cardiovascular |
| Companies Covered | F. Hoffmann-La Roche Ltd., Agilent Technologies, Inc., QIAGEN, Abbott Laboratories, Thermo Fisher Scientific Inc., bioMérieux, Illumina, Inc., Guardant Health Inc., Myriad Genetics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Diagnostics Market Emerging Trajectories
Next-generation sequencing workflows are compressing the economics of multiplex biomarker testing, while regulatory convergence around real-world evidence is rewriting validation standards for decentralized diagnostic deployment.
Comprehensive genomic profiling panels are expanding into routine oncology practice by replacing sequential single-gene tests with simultaneous mutation, copy number, and fusion detection. Community hospital pathology departments in the United States and Germany are adopting these platforms to retain specimen volume that previously flowed to academic reference centers. The technology is expanding into clinical trial enrollment screening, where sponsors now require local CGP availability to accelerate patient identification.
MDR implementation in European markets is elevating clinical performance study requirements for in vitro diagnostic devices, including companion diagnostics. Manufacturers must now demonstrate analytical validity, clinical validity, and clinical utility through prospective data collection rather than literature-based equivalence. Medium-sized assay developers in France and the Netherlands are restructuring quality management systems to accommodate notified body scrutiny of software lifecycle documentation.
Pharmaceutical procurement departments are consolidating vendor relationships around integrated drug-diagnostic development partners rather than transactional testing suppliers. Oncology business units at major biopharma firms now mandate companion diagnostic readiness at Phase II trial initiation, shifting contract timing 18-24 months earlier in development cycles. This pattern is most pronounced in United States and Swiss markets, where FDA breakthrough therapy designations accelerate regulatory timelines.
Companion Diagnostics Market Segmentation
Segmentation in companion diagnostics reveals how procurement authority, technology readiness, and therapeutic area economics concentrate demand across divergent customer workflows. Pharmaceutical sponsors, hospital laboratories, and reference centers each impose distinct validation requirements that reshape product configuration and pricing architecture.
Product Type:
Pharmaceutical procurement departments prioritize integrated assay-instrument bundles that compress validation timelines and lock in supply security for registrational trials.
- Tests:Pre-validated analyte-specific reagents for single-biomarker indications dominate Phase III companion diagnostic submissions. Demand concentrates among US-based oncology sponsors facing FDA prospective stratification mandates.
- Assays:Multi-analyte panels with frozen analytical validation packages reduce site-to-site variability in decentralized clinical trials. European pharmaceutical firms leverage EMA scientific advice pathways to align assay qualification with drug development timelines.
- Kits:Lyophilized reagent formats with extended ambient stability simplify logistics for emerging market deployments. Research laboratories in India and Brazil adopt these configurations to circumvent cold-chain infrastructure gaps.
- Instruments:Automated nucleic acid extraction platforms with embedded PCR modules reduce manual handling errors in high-throughput hospital laboratories. German pathology departments prioritize CE-IVD certified systems to satisfy MDR technical documentation requirements.
Tests lead on scale; assays lead on momentum.
Technology:
Laboratory infrastructure investment cycles and regulatory evidentiary standards determine technology adoption velocity across customer segments.
- Nucleic Acid Testing:Real-time PCR platforms with FDA-cleared oncology menus anchor companion diagnostic workflows in US community hospitals. Specimen volume retention drives capital allocation decisions as academic medical centers compete for molecular pathology referrals.
- Next-Generation Sequencing:Comprehensive genomic profiling panels replace sequential single-gene testing by delivering mutation, copy number, and fusion detection in unified workflows. Swiss pharmaceutical sponsors now require local NGS availability at Phase II initiation to accelerate patient identification.
- Immunohistochemistry:Chromogenic antibody staining on formalin-fixed tissue remains the cost baseline for protein biomarker validation. Japanese pathology laboratories favor automated stainers with quantitative image analysis to standardize PD-L1 scoring.
- PCR:Digital droplet PCR methods achieve rare variant detection sensitivity required for minimal residual disease monitoring. Liquid biopsy specimen workflows in metastatic cancer settings expand addressable patient populations beyond tissue acquisition constraints.
PCR leads on installed base; NGS leads on expansion trajectory.
End User:
Customer type dictates contract structure, with pharmaceutical partnerships commanding multi-year co-development commitments versus transactional reagent supply to clinical laboratories.
- Pharmaceutical Companies:Integrated drug-diagnostic development alliances with exclusive supply terms and profit-sharing mechanisms. FDA breakthrough therapy designations compress timelines, elevating contract values for validated assay readiness at Phase II initiation.
- Research Laboratories:Investigational use only reagents for biomarker discovery and retrospective clinical utility studies. Academic medical centers in the United States drive demand for research-grade NGS panels with customizable gene content.
- Hospitals:Decentralized testing infrastructure for same-day treatment decisions in oncology clinics. Community hospital pathology departments in Germany adopt automated sample-to-result systems to retain specimen volume previously referred to academic centers.
- Clinics:Point-of-care nucleic acid testing platforms with waived complexity status under CLIA regulations. US oncology clinics prioritize rapid turnaround for EGFR mutation testing to guide first-line tyrosine kinase inhibitor selection.
Pharmaceutical companies lead on contract value; hospitals lead on volume expansion.
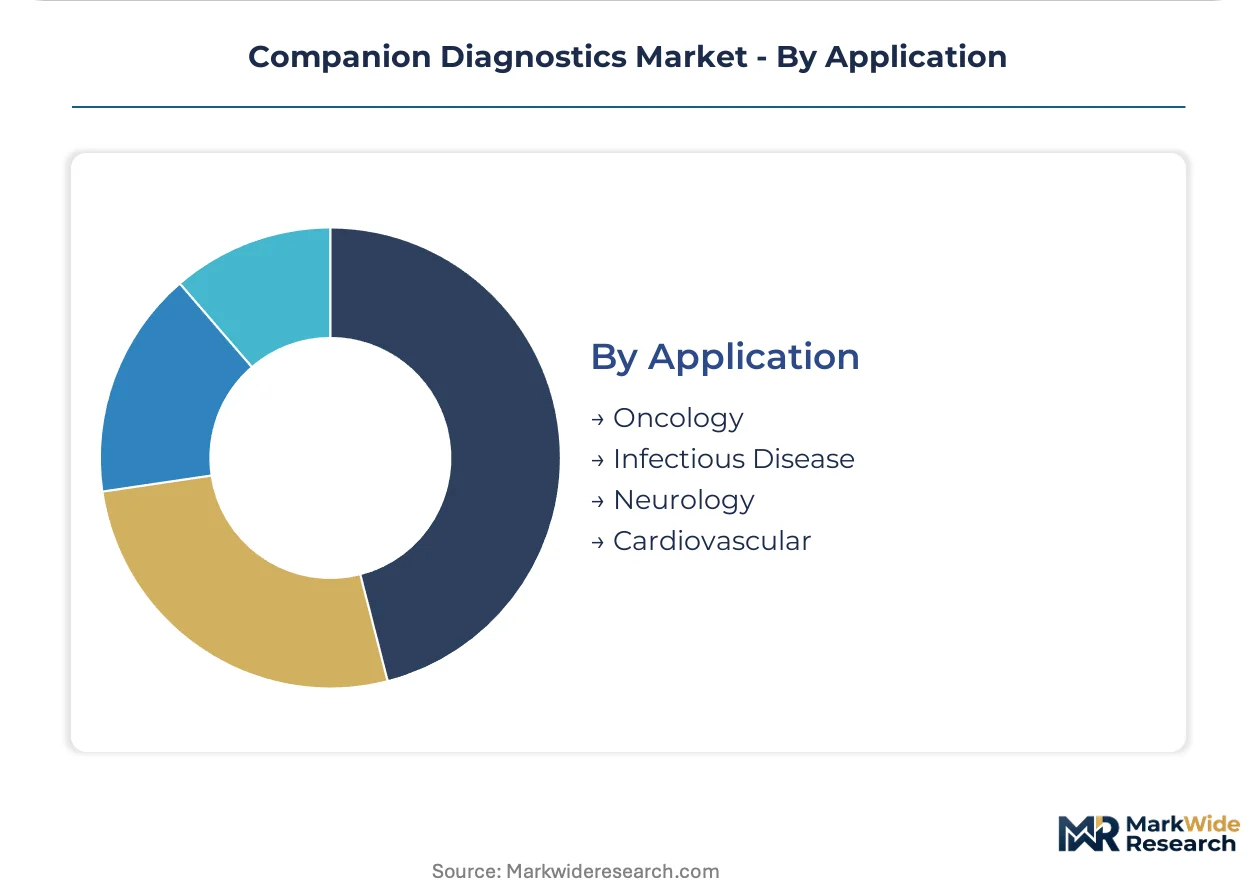
Application:
Therapeutic area pipeline economics and regulatory biomarker mandates concentrate R&D investment and fastest test validation cycles.
- Oncology:Precision medicine pipelines with FDA-mandated prospective stratification in registrational trials. Companion diagnostic development for lung cancer and colorectal cancer indications commands the deepest pharmaceutical investment.
- Infectious Disease:Antimicrobial resistance profiling and viral load monitoring for HIV and hepatitis C therapeutics. WHO prequalification pathways for tuberculosis companion tests create template mechanisms for low-income market expansion.
- Neurology:Cerebrospinal fluid biomarker quantification for Alzheimer's disease therapeutic eligibility. Biogen's aducanumab approval established precedent for amyloid PET and CSF assay co-development requirements.
- Cardiovascular:Pharmacogenomic testing for antiplatelet and anticoagulant response prediction. US health systems deploy CYP2C19 genotyping to guide clopidogrel prescribing in percutaneous coronary intervention patients.
Oncology leads on revenue concentration; infectious disease leads on policy tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision oncology talent clusters in Boston, Basel, and San Diego anchor companion diagnostic development, with regulatory science expertise concentrating near FDA, EMA, and Swissmedic headquarters.
United States
FDA's prospective stratification mandates for Phase III oncology trials drive pharmaceutical co-development investment. Breakthrough therapy designations compress validation timelines, elevating contract values for assay readiness at Phase II initiation. The Boston-Cambridge corridor hosts the densest concentration of integrated drug-diagnostic alliances, with Guardant Health and Foundation Medicine anchoring liquid biopsy infrastructure.
Germany
MDR implementation elevates clinical performance study requirements for IVD devices, forcing quality management system restructuring among mid-sized assay developers. EMA scientific advice pathways attract pharmaceutical sponsors seeking parallel drug-test submission alignment. The Munich and Heidelberg pathology clusters adopt automated sample-to-result systems to satisfy notified body scrutiny of software lifecycle documentation.
Switzerland
Swissmedic's streamlined consultation procedures for companion diagnostic developers accelerate market authorization timelines. Roche's integrated diagnostics-pharmaceutical model sustains long-term therapy-test alliances from Basel. The Zürich biotech corridor attracts precision medicine ventures seeking proximity to Novartis and Roche procurement departments.
China
NMPA's evolving technical review guidelines for innovative IVD devices reshape submission pathways for domestic and multinational manufacturers. The Shanghai Zhangjiang Hi-Tech Park concentrates CDMO capacity for nucleic acid extraction platforms. Beijing's clinical trial infrastructure supports biomarker-stratified studies for domestic oncology pipelines.
Japan
PMDA's sakigake designation system accelerates priority review for companion diagnostics linked to breakthrough therapies. Automated immunohistochemistry stainers with quantitative image analysis standardize PD-L1 scoring in Tokyo and Osaka pathology departments. The Kobe biomedical innovation cluster hosts pharmaceutical-diagnostic co-development programs targeting Asian patient populations.
Companion Diagnostics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Integrated life science conglomerates leverage diagnostics-pharmaceutical synergies to capture multi-year co-development contracts. Pure-play molecular diagnostic firms anchor positions through sample-to-insight workflow specialization. Emerging liquid biopsy specialists occupy the innovation frontier with circulating tumor DNA platforms. Strategic consolidation and exclusive supply agreements represent the dominant competitive moves, with pharmaceutical procurement departments consolidating vendor relationships around integrated partners.
Among Swiss and German integrated conglomerates, F. Hoffmann-La Roche Ltd. and QIAGEN exemplify the diversified archetype through diagnostics-pharmaceutical integration and sample-to-insight workflow dominance respectively. Illumina, Inc. occupies a position representing the sequencing infrastructure specialist tier. These three anchors illustrate how geographic proximity to Basel, Hilden, and San Diego talent pools shapes competitive positioning in precision oncology co-development.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies, Inc. |
| QIAGEN |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| bioMérieux |
| Illumina, Inc. |
| Guardant Health Inc. |
| Myriad Genetics, Inc. |
| Others |
Supply Flow & Price Mechanics
Next-generation sequencing platform commoditization simultaneously compresses per-test cost economics and concentrates reagent supply among three dominant instrument manufacturers. Pharmaceutical sponsors now negotiate multi-year bundled contracts that lock in consumable pricing across registrational trial timelines, transferring volume risk to diagnostic vendors.
Pricing Analysis
Bundled assay-instrument service contracts dominate pharmaceutical procurement, while unbundled reagent supply prevails in hospital laboratories. Price differentiation rests on FDA premarket approval tier versus CE-IVD self-certification, with breakthrough therapy-linked diagnostics commanding 40-60% premiums over standard oncology panels. Pricing pressure stems from CMS reimbursement lag trailing FDA approvals by 18-24 months, forcing manufacturers to absorb launch-period losses. Research laboratories exhibit highest price sensitivity due to grant-funded budgets; integrated pharma-diagnostic alliances show lowest sensitivity due to co-development profit-sharing structures.
Supply Chain Analysis
Reverse-logistics for expired reagent lots and instrument refurbishment flows remain underdeveloped, creating working capital drag for decentralized hospital laboratories. Manufacturing concentrates in United States, Germany, and China, with nucleic acid extraction consumables drawing from specialized polymer suppliers in Massachusetts and Hessen. Supply chain risk centers on single-source dependency for rare fluorescent dyes used in PCR probe chemistries. Distribution runs through authorized dealer networks for capital equipment and direct-to-laboratory e-commerce portals for recurring consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
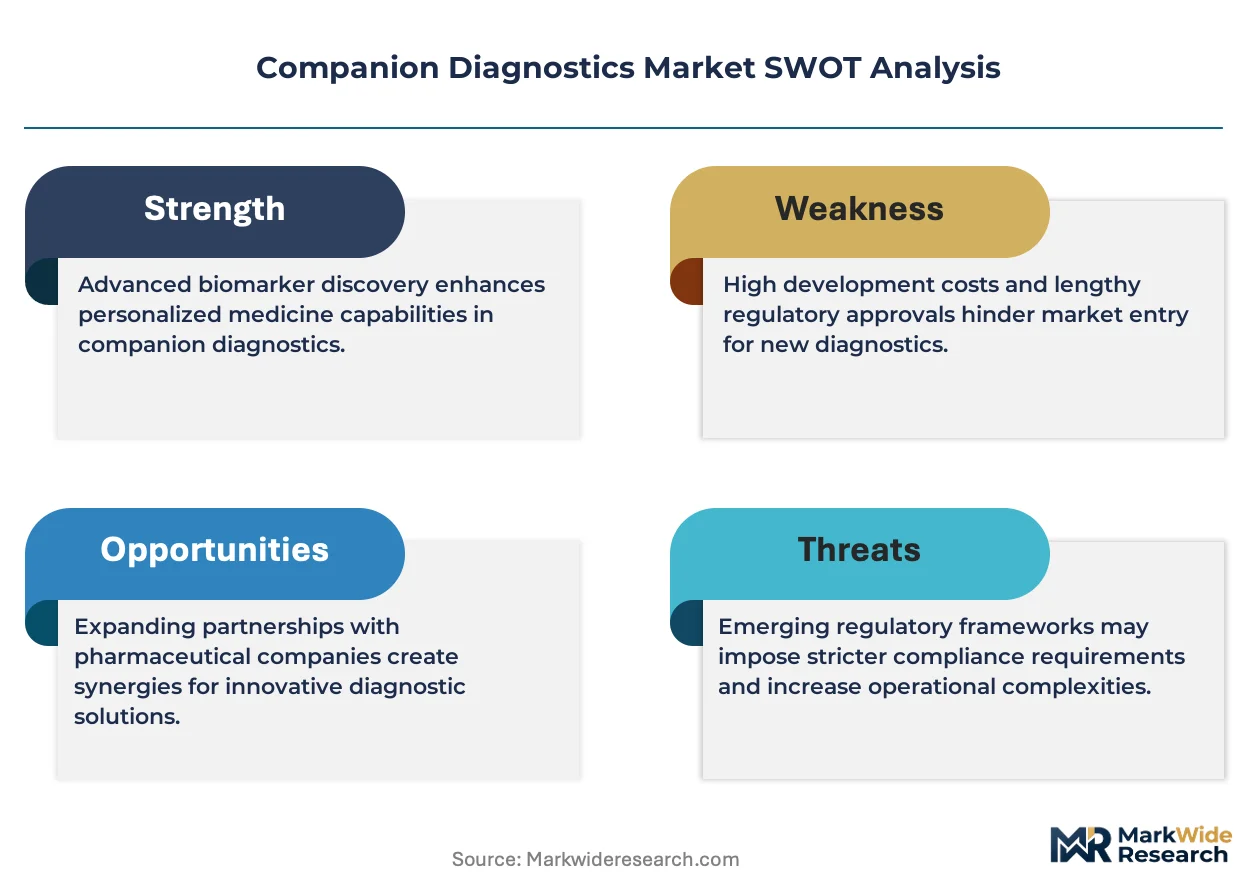
Companion diagnostics development functions as a geographic-arbitrage play: EMA scientific advice pathways offer 12-18 month timeline advantages over FDA pre-submission queues, reducing capital-at-risk for European-anchored programs.
For Market Incumbents: Anticipate liquid biopsy platform displacement of tissue-based assays by securing exclusive ctDNA supply agreements with Guardant Health and Foundation Medicine before Phase II trial initiation. Lock in German pathology department automation upgrade cycles through CE-IVD certified sample-to-result bundles. Prioritize MDR technical documentation investment to defend notified body relationships against mid-sized assay developer consolidation.
For New Entrants and Emerging Players: Community hospital pathology departments in secondary US metropolitan areas represent the most penetrable buyer archetype, lacking internal NGS bioinformatics capacity and seeking turnkey CGP partnerships. Target infectious disease CDx-IVD harmonization through WHO prequalification pathways for tuberculosis and HIV, where regulatory templates lower barrier entry. Deploy automated stainer-software bundles with quantitative image analysis to displace manual PD-L1 scoring in Japanese clinics.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized European assay developers restructuring quality management systems for MDR compliance. Long-term viability hinges on pharmaceutical co-development contract backlog depth rather than installed instrument base. Monitor FDA breakthrough therapy designation velocity as inflection indicator for diagnostic readiness contract timing compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Alliance Structuring | Pharmaceutical procurement now mandates diagnostic readiness 18-24 months before Phase II initiation. |
| Liquid Biopsy Infrastructure Deployment | Circulating tumor DNA workflows expand addressable populations beyond tissue acquisition constraints in metastatic settings. |
| MDR Quality System Restructuring | European notified body scrutiny of software lifecycle documentation forces medium-sized developer consolidation. |
| Automated Sample-to-Result Integration | Embedded nucleic acid extraction and real-time PCR modules reduce manual handling errors in decentralized laboratories. |
| Minimal Residual Disease Monitoring Expansion | Post-treatment ctDNA surveillance opens recurring revenue streams beyond initial diagnostic testing in oncology. |
Methodological Framework
Direct dialogue with pharmaceutical development executives, regulatory affairs leads, diagnostic laboratory directors, and payer access specialists grounded qualitative findings. Secondary validation drew from FDA premarket approval filings, EMA scientific advice outcome summaries, ClinicalTrials.gov biomarker stratification records, and CMS national coverage determination databases. Bottom-up test volume modeling and top-down pharmaceutical R&D pipeline analysis triangulated market sizing across the projection horizon.
Segment-level outputs reflect analytical frameworks incorporating technology platform, therapeutic area pipeline depth, end-user procurement authority, and regional regulatory cluster. CAGRs derived from pharmaceutical co-development contract value trajectories and instrument placement velocity in community hospital settings. Forecast inputs included oncology therapeutic pipeline biomarker stratification mandates and MDR implementation timelines for European IVD manufacturers.
Underlying measurement precision varies by segment; nucleic acid testing and next-generation sequencing carry tighter precision than emerging immunohistochemistry automation due to established volume reporting. Forecasts reflect assumptions around FDA prospective stratification mandate continuity and EMA biomarker qualification pathway stability. Periodic stress-testing of base assumptions is recommended given reimbursement lag volatility and decentralized testing regulatory evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Global DNA Test Kit Market