
 In-Memory Computing Market | 2026-2036
In-Memory Computing Market Size, Share, and Industry Trends Forecast 2026-2036
In-Memory Computing Market Intelligence
Enterprise distribution through cloud service providers is reshaping how in-memory computing platforms reach end users. Intel Corporation leverages its foundry scale to dominate high-bandwidth memory supply for data center deployments. Samsung Electronics anchors its position through captive DRAM fabrication and vertical integration into module assembly. Micron Technology competes aggressively on process node leadership, sustaining R&D intensity in advanced DRAM architectures.
In-memory computing refers to data processing architectures where information resides in RAM or other high-speed memory rather than disk storage, enabling microsecond-level query response and real-time transactional throughput. The technology eliminates I/O bottlenecks by keeping active datasets in volatile or non-volatile memory pools directly accessible to CPUs. Cloud-based deployment is gaining share fastest as hyperscalers integrate in-memory layers into managed database services. Finance and telecommunications end users generate the largest margin pools due to strict latency requirements in trading systems and network orchestration. Data analytics applications lead volume adoption while machine learning workloads represent the fastest-expanding segment for GPU-attached memory configurations.
FDA scrutiny of real-time healthcare data systems and FCC rules on telecommunications infrastructure resilience shape product certification requirements for in-memory platforms in regulated sectors. GDPR and the EU AI Act impose data locality and processing transparency mandates that favor on-premises and private cloud deployments over public cloud alternatives. Enterprises must evaluate regulatory jurisdiction overlap when selecting hybrid architectures that span multiple compliance regimes.
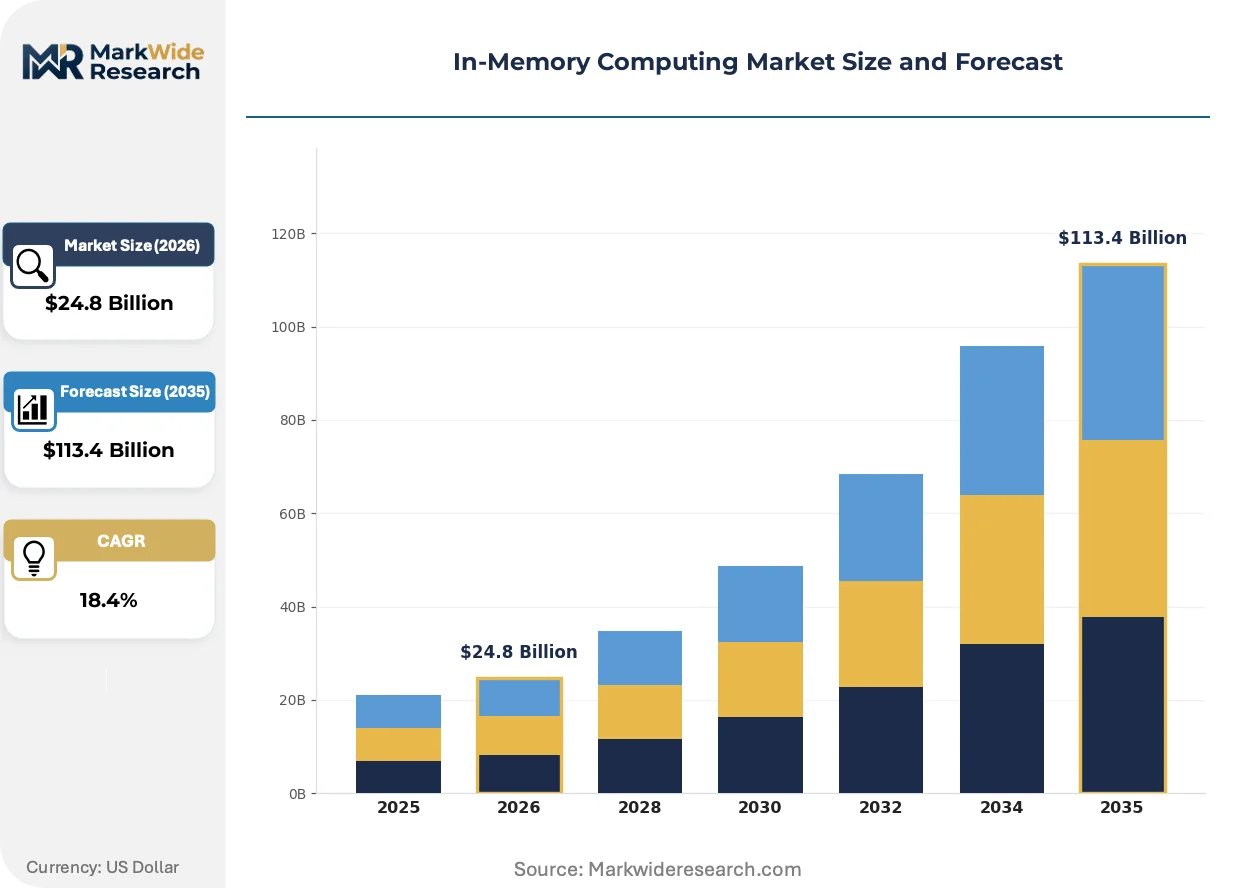
Market Dynamics
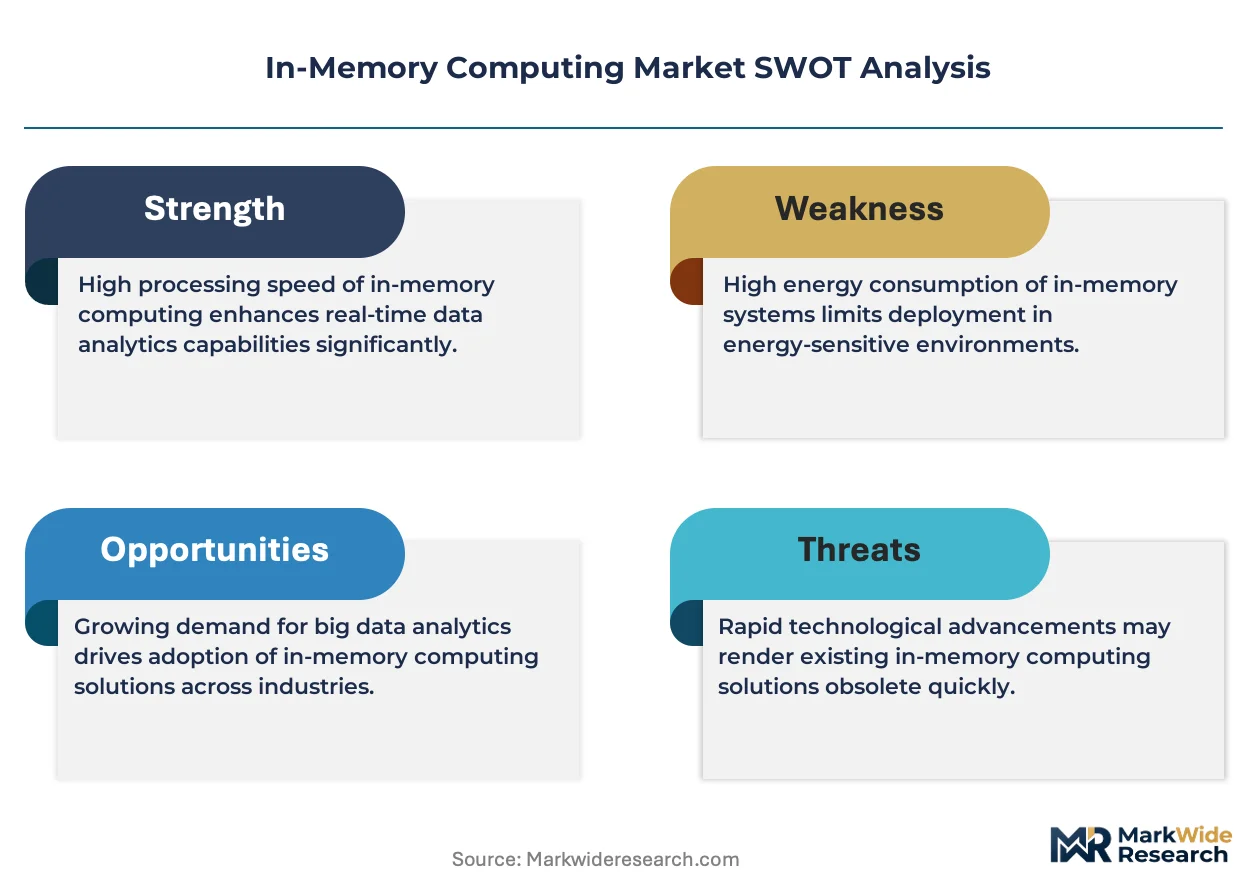
Real-time data processing mandates from financial services and industrial automation are compressing latency tolerances to microseconds, forcing infrastructure architects to redesign memory hierarchies around volatile and persistent RAM pools rather than disk-based architectures.
Growth Catalysts
- EU AI Act compliance deadlines:Enterprises across Germany, France, and the Netherlands are deploying low-latency processing architectures to satisfy algorithmic transparency and data locality requirements before enforcement phases begin.
- Automotive edge computing:German OEMs and Tier-1 suppliers are procuring high-bandwidth memory modules for autonomous vehicle perception pipelines and over-the-air update systems.
- Telecommunications network slicing:5G core infrastructure deployments require in-memory state management for subscriber sessions and quality-of-service enforcement at the network edge.
Market Restraints
- DRAM supply concentration:Three fabrication clusters in South Korea and Taiwan control over 90 percent of advanced memory wafer output, exposing procurement pipelines to geopolitical friction and export control volatility.
- GDPR data residency friction:Cross-border data movement restrictions complicate hybrid cloud architectures that span multiple jurisdictions, increasing compliance overhead for multinational deployments.
- Power density limitations:High-bandwidth memory modules consume disproportionate thermal budgets in rack-dense configurations, constraining deployment scale in legacy data center cooling environments.
Strategic Opportunities
- India's digital public infrastructure:The country's unified payments interface and health stack expansion create demand for real-time transaction processing at population scale, with procurement concentrated through state-level data centers.
- GPU-attached memory convergence:Machine learning training workloads are driving architectural integration between high-bandwidth memory and accelerator fabrics, opening design partnerships between foundries and AI chip vendors.
- Private cloud channel expansion:Managed service providers are bundling in-memory database layers with sovereign cloud offerings, capturing enterprises with strict data localization requirements.
Industry Challenges
- Legacy system integration complexity:Mainframe and disk-based data warehouses require extensive middleware development to interface with in-memory platforms without disrupting operational continuity.
- Certification timeline compression:FDA validation for real-time healthcare analytics and FCC infrastructure resilience approvals extend sales cycles by 12-18 months in regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Memory Computing Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $113.4 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud End User: Healthcare, Retail, Finance, Telecommunications Application: Data Analytics, Real-Time Processing, Machine Learning, Business Intelligence Technology: Non-Volatile Memory, Flash Memory, RAM, Distributed Computing |
| Companies Covered | Intel Corporation, Rambus, Samsung Electronics, IBM, Pure Storage, SK Hynix, Marvell Technology, Oracle, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Memory Computing Market Strategic Shifts & Innovations
Memory-centric computing architectures are displacing conventional storage hierarchies across latency-sensitive workloads, with technology vendors and cloud operators racing to integrate persistent memory tiers into standard service offerings.
Compute Express Link (CXL) is migrating from proprietary interconnect protocols toward open-standard memory pooling across disaggregated server architectures. Hyperscale operators in the United States and China are piloting CXL 2.0 fabrics to enable dynamic memory allocation between CPUs and accelerators. This shift is compressing hardware refresh cycles as enterprises defer capital commitments until CXL 3.0 ecosystem maturity arrives.
The EU AI Act's risk classification framework is mandating algorithmic audit trails and processing transparency for high-risk AI systems. Financial institutions in Frankfurt and Paris are re-architecting model inference pipelines to capture intermediate states in persistent memory for regulatory examination. Compliance teams are prioritizing on-premises deployments over public cloud alternatives to maintain jurisdictional control over training data.
Consumption-based pricing models are displacing perpetual licensing for in-memory database software. German automotive suppliers and Dutch trading firms are negotiating utility billing tied to peak memory utilization rather than core counts. This transition is most visible in DACH region procurement, where CFOs demand operational expenditure alignment with volatile production schedules.
In-Memory Computing Market Segmentation
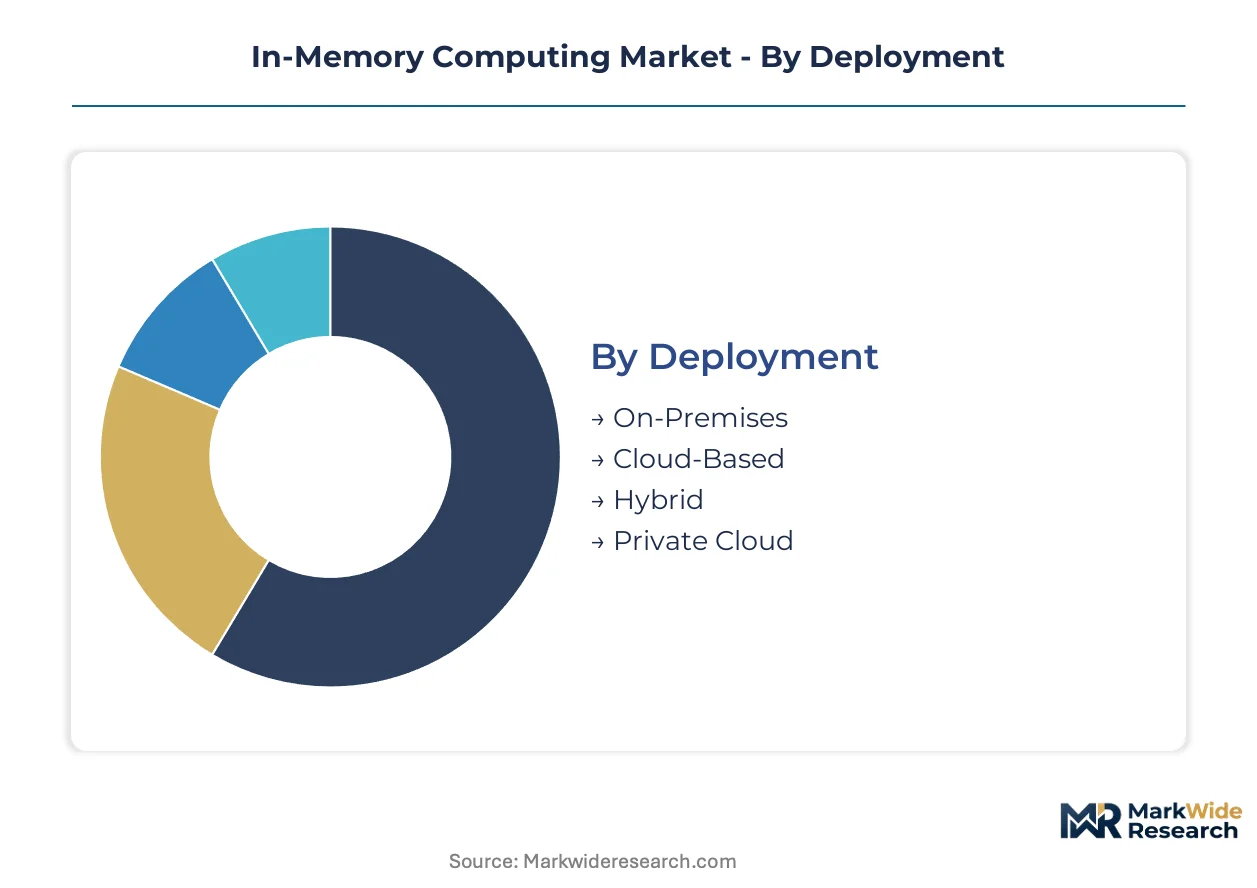
In-memory computing architectures exhibit divergent deployment economics and latency profiles across technology layers, with procurement decisions increasingly governed by regulatory jurisdiction and workload-specific throughput requirements. Segment boundaries blur as hybrid configurations absorb capabilities from adjacent categories, reshaping vendor positioning and channel strategy.
Deployment:
Mature on-premises installations coexist with rapidly maturing cloud-native services, creating a deployment spectrum where sovereignty requirements and operational expenditure preferences drive selection.
- On-Premises:Enterprises in Frankfurt and Paris maintain captive infrastructure to satisfy GDPR data residency mandates and EU AI Act algorithmic audit requirements. German automotive OEMs favor this model for autonomous vehicle development pipelines where intellectual property protection overrides cost optimization.
- Cloud-Based:Hyperscalers integrate in-memory layers into managed database services, capturing trading firms in Amsterdam and fintech startups in London seeking elastic capacity without capital commitment. FCC telecommunications infrastructure rules increasingly influence edge deployment specifications for network slicing workloads.
- Hybrid:Financial institutions split transactional workloads across private cores and burst capacity, navigating cross-border data movement restrictions through jurisdictional partitioning.
- Private Cloud:Sovereign cloud offerings bundle in-memory database layers for defense contractors and healthcare providers facing FDA scrutiny of real-time patient data systems.
Cloud-based deployment gains share most quickly; on-premises retains the largest installed base among regulated verticals.
End User:
Customer concentration varies sharply by margin pool, with latency-sensitive sectors commanding premium pricing and extended sales cycles driven by certification requirements.
- Finance:Real-time risk analytics and algorithmic trading in London, Zurich, and Singapore compress latency tolerances to microseconds, generating the highest per-node revenue in the sector. SEC and FCA compliance timelines extend procurement cycles substantially.
- Telecommunications:5G core infrastructure deployments require in-memory state management for subscriber sessions, with procurement concentrated through German network operators and South Korean carriers facing distinct national spectrum allocation regimes.
- Healthcare:FDA validation requirements for real-time clinical decision support create 12-18 month certification barriers, favoring established vendors with regulatory track records.
- Retail:Inventory optimization and personalization engines drive adoption among omnichannel operators, though margin pressure constrains deployment scale relative to financial services.
Finance commands the steepest pricing premiums; telecommunications exhibits the most aggressive expansion trajectory.
Application:
Workload characteristics determine memory hierarchy design, with analytics pipelines and transactional systems diverging on volatility requirements and persistence models.
- Data Analytics:Batch-oriented query acceleration dominates current volume, with German industrial conglomerates and Dutch logistics operators deploying terabyte-scale RAM pools for supply chain optimization.
- Machine Learning:GPU-attached memory configurations for model training represent the most resource-intensive growth vector, driven by Frankfurt-based quantitative funds and Parisian AI startups re-architecting inference pipelines for EU AI Act compliance.
- Real-Time Processing:Fraud detection and network orchestration demand microsecond-level consistency, constraining architecture choices to volatile memory tiers.
- Business Intelligence:Executive dashboards and operational reporting migrate from disk-based warehouses to in-memory caches, though sensitivity to memory cost per gigabyte limits penetration in mid-market accounts.
Data analytics retains volume leadership; machine learning claims the steepest expansion curve.
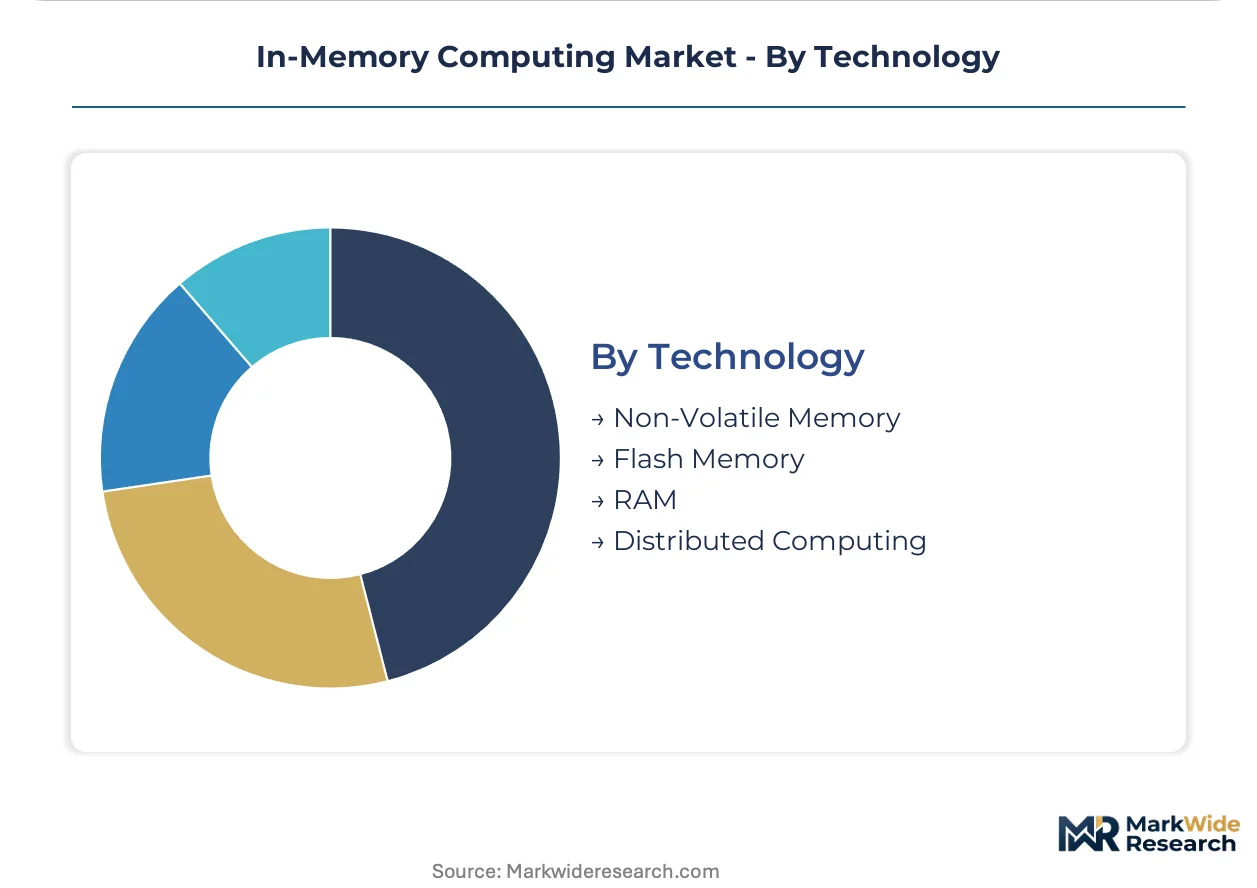
Technology:
Memory media selection involves trade-offs between persistence, speed, and cost, with emerging non-volatile alternatives threatening to collapse traditional hierarchy distinctions.
- RAM:DDR5 and HBM3 modules deliver the lowest access latency for transactional workloads, with supply concentration in South Korean and Taiwanese fabrication clusters exposing procurement to export control volatility.
- Non-Volatile Memory:Intel Optane discontinuation and CXL 2.0 ecosystem maturation are reshaping persistent memory strategies, with hyperscale pilots in Virginia and Guizhou testing disaggregated pooling architectures.
- Flash Memory:NVMe-attached storage-class memory bridges cost and performance gaps for analytics workloads with relaxed latency requirements.
- Distributed Computing:Software-defined memory fabrics aggregate heterogeneous media across rack-scale clusters, gaining traction in cloud-native deployments.
RAM dominates current procurement volumes; non-volatile alternatives are climbing the fastest as CXL standardization matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne railway corridor and DE-CIX internet exchange anchor Germany's central European position in low-latency data infrastructure. Submarine cable landings at Marseille and Lisbon underpin Southern Europe's connectivity advantages for transatlantic workloads.
Germany
Industrial automation from Siemens and Bosch drives demand for edge-computing memory modules in factory floors across Baden-Württemberg. The EU AI Act's algorithmic audit requirements push financial institutions in Frankfurt toward persistent memory architectures for model traceability. Automotive OEMs in Munich and Stuttgart deploy high-bandwidth memory for autonomous vehicle perception pipelines.
United States
Hyperscale operators in Northern Virginia and Oregon pilot CXL 2.0 fabrics for disaggregated memory pooling across AI training clusters. FCC infrastructure resilience rules shape edge deployment specifications for 5G network slicing workloads. Quantitative trading firms in Chicago and New York compress latency tolerances to microseconds for real-time risk analytics.
China
Guizhou and Inner Mongolia data centers test persistent memory tiers for state-backed cloud infrastructure expansion under MIIT guidance. The country's dual carbon goals constrain power density in rack-dense memory configurations. Beijing and Shanghai AI labs drive GPU-attached memory procurement for large language model training at population scale.
South Korea
SK Hynix and Samsung Electronics anchor global HBM3 supply from fabrication clusters in Gyeonggi-do and Chungcheongbuk-do. MFDS data localization requirements push healthcare providers toward on-premises memory architectures for genomic analysis. Seoul Capital Area fintech operators negotiate consumption-based pricing for real-time payment processing infrastructure.
India
The Unified Payments Interface and Ayushman Bharat health stack expansion create demand for real-time transaction processing through state-level data centers in Maharashtra and Karnataka. RBI guidelines on payment system resilience favor in-memory architectures for sub-millisecond settlement. Bengaluru and Hyderabad cloud operators build sovereign capacity to capture GDPR-conscious European outsourcing contracts.
In-Memory Computing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply hierarchy. The market exhibits tiered consolidation with memory fabricators controlling wafer supply and software vendors capturing recurring revenue from database layers. Three archetypes dominate: captive DRAM producers with foundry scale, fabless interconnect designers, and cloud-native platform operators. Competitive moves center on CXL ecosystem partnerships and strategic foundry capacity reservations.
Among captive fabrication specialists, Intel Corporation and Samsung Electronics occupy positions defined by backward integration into wafer supply and module assembly. SK Hynix sits within the high-bandwidth memory tier where process node leadership determines procurement access. IBM and Oracle exemplify platform integrators bundling in-memory layers with enterprise software stacks, capturing regulated verticals through compliance-certified deployment templates.
| Leading Market Players |
|---|
| Intel Corporation |
| Rambus |
| Samsung Electronics |
| IBM |
| Pure Storage |
| SK Hynix |
| Marvell Technology |
| Oracle |
| Micron Technology |
| Others |
Cost & Logistics Intelligence
Gyeonggi-do fabrication clusters in South Korea anchor wafer supply for high-bandwidth memory modules, concentrating pricing power among three dominant producers and compressing margin flexibility for downstream system integrators. This geographic lock-in amplifies procurement cost volatility when export controls disrupt cross-border logistics.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud commitments from mid-market enterprise licenses and spot-market module procurement. Price differentiation rests on certification grade—FDA-validated healthcare configurations command substantial premiums over standard data center SKUs—and volume scale, with petabyte-scale buyers extracting double-digit concessions. Cost compression in the mid-tier is intensifying because CXL 2.0 ecosystem maturation defers capital commitments. Retail and mid-market healthcare providers exhibit acute price sensitivity; Frankfurt-based quantitative funds show minimal elasticity for microsecond-latency configurations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for memory module assemblers sourcing controllers from Taiwanese foundries. Advanced DRAM output concentrates in South Korea, Taiwan, and the United States, drawing from silicon wafers, EUV lithography equipment, and specialty chemical precursors. Single-source vulnerability in extreme ultraviolet scanner maintenance creates chokepoint exposure. Distribution runs through direct OEM contracts for captive foundry output and cloud service provider channel partnerships for software-layer subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-memory computing platforms generate expanding recurring revenue from managed database services and compliance-certified deployment templates, with service attach rates outpacing hardware margin growth. This shift rewards vendors building operational expenditure alignment into customer contracts.
For Market Incumbents: Build switching-cost moats through CXL ecosystem partnerships that lock hyperscalers into proprietary memory pooling architectures. Deepen backward integration into advanced packaging capacity in South Korea and Taiwan to defend against emerging fabless interconnect designers. Prioritize FDA and EU AI Act certification investments to extend sales cycle advantages in regulated healthcare and financial services verticals.
For New Entrants and Emerging Players: Pursue sovereign cloud deployment gaps in India and Southeast Asia where GDPR-conscious European enterprises seek outsourced infrastructure. India's state-level data center expansion presents the most penetrable procurement channel. Lead with consumption-based pricing models that align with volatile production schedules at German automotive suppliers.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because persistent memory architectures collapse traditional hardware-software boundaries and capture recurring revenue from algorithmic audit compliance layers. Target platform integrators bundling in-memory layers with vertical-specific certification track records. Watch CXL 3.0 ecosystem maturity as the inflection signal for hardware refresh cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CXL Ecosystem Partnership | Intel and Samsung anchor open-standard memory pooling for disaggregated AI training clusters. |
| Regulatory Certification Investment | FDA validation pathways extend competitive moats in real-time healthcare analytics deployments. |
| Consumption-Based Pricing Launch | German automotive suppliers adopt utility billing tied to peak memory utilization schedules. |
| Sovereign Cloud Channel Expansion | Managed service providers capture GDPR-conscious European outsourcing through Indian data centers. |
| GPU-Attached Memory Convergence | Foundry partnerships with AI chip vendors integrate HBM3 into accelerator fabrics for training workloads. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and semiconductor trade data. Interviews with data center infrastructure architects, cloud procurement officers, memory module supply chain managers, and regulatory compliance leads in Frankfurt, Seoul, and Northern Virginia inform demand-side validation. Bottom-up sizing of wafer output and top-down triangulation against enterprise IT spending patterns anchor volume estimates.
Forecast inputs incorporate deployment model splits, workload-specific latency requirements, and regional regulatory cluster variations across the projection horizon. Segmentation dimensions modeled include technology layer, end-use vertical, application workload, and geographic adoption pattern. CAGRs derive from installed base evolution and replacement cycle compression. Memory density per server node and power density constraints in legacy cooling environments shape capacity expansion assumptions.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and enterprise capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about CXL standardization timelines and foundry capacity expansion. Material shifts in export control regimes or EU AI Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Memory Chip Market
Memory Chips
Memristor Market
Memory Chips
Mobile DRAM Market
Memory Chips
Memory Module Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Smartphone RAM Market
Memory Chips
DDR SDRAM Market
Memory Chips
China Flash Memory Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Magneto Resistive RAM (MRAM) Market