
 Memristor Market | 2026-2036
Memristor Market Size, Share, and Industry Trends Forecast 2026-2036
Memristor Market Intelligence
The gap between premium neuromorphic-grade memristors and commodity storage-class devices is shifting from a performance spread into a supply-chain bifurcation, with foundry capacity and materials certification now separating the two tiers. Samsung Electronics leverages its captive semiconductor fabrication network to sustain wafer-level integration of resistive-switching arrays. Intel Corporation anchors its position through in-house development of CMOS-compatible memristor logic for edge-AI inference. Crossbar Inc specializes in filamentary-switching architectures that occupy a distinct niche between analog computation and non-volatile storage.
A memristor is a two-terminal passive circuit element whose electrical resistance depends on the history of charge flow through it, typically fabricated from metal-oxide thin films such as titanium dioxide or hafnium oxide with switching thresholds in the sub-nanosecond range, serving as the hardware foundation for brain-inspired computing and ultra-dense non-volatile memory. Digital memristors command the largest revenue share in data storage applications where binary-state reliability outweighs analog precision, while analog memristors represent the fastest-expanding category because neuromorphic computing demands continuous resistance tuning for synaptic weight emulation. Hybrid memristors are capturing margin pools at the intersection of these domains, where systems require both deterministic switching and graded conductance states.
The EPA oversees hazardous substance reporting for oxide deposition processes in U.S. memristor fabrication, while REACH restricts precursor chemicals used in European thin-film manufacturing, and South Korea's Ministry of Trade, Industry and Energy channels national R&D funding through METI-aligned consortia for next-generation memory commercialization. These frameworks collectively raise barriers for uncertified suppliers while directing procurement toward qualified vendors with documented environmental compliance. Stakeholders must weigh foundry partnerships against captive fabrication investments as the technology crosses from laboratory qualification to volume manufacturing.
Market Dynamics
Neuromorphic computing demand is bifurcating the memristor supply base into captive foundry networks serving data centers versus merchant suppliers chasing edge-AI volume, with CMOS integration capability now determining tier access rather than device performance alone.
Growth Catalysts
- REACH compliance mandates:European material purity requirements for resistive-switching precursors are filtering out uncertified thin-film suppliers and consolidating procurement toward qualified vendors with documented environmental traceability.
- Data center neuromorphic deployment:Cloud operators are pulling advanced memristor architectures into commercial inference engines, creating guaranteed offtake for wafer-level integrated arrays.
- South Korean foundry consortia:Government-backed R&D funding through METI-aligned programs is accelerating CMOS-compatible production scale-up beyond laboratory qualification.
Market Restraints
- Hafnium oxide precursor volatility:Supply concentration for high-purity metal-organic sources creates input cost instability that compresses margins at the thin-film deposition stage.
- Filamentary switching reliability limits:Cycle-to-cycle variability in conductive-bridge formation remains a technical barrier for storage-class applications requiring deterministic endurance.
- EPA hazardous substance reporting:Oxide deposition process documentation requirements add compliance overhead that disproportionately burdens sub-scale fabrication facilities.
Strategic Opportunities
- Edge-AI inference modules:Analog memristor integration into microcontroller-class devices opens volume tiers below data-center scale, with automotive and industrial automation as early adopters.
- EU Green Deal semiconductor incentives:Carbon footprint reduction mandates for computing hardware are creating preference for non-volatile memory that eliminates refresh power consumption.
- Hybrid architecture convergence:Systems combining digital reliability with analog tunability are capturing margin pools at the intersection of storage and synaptic emulation functions.
Industry Challenges
- Multi-physics simulation expertise:The talent pool for coupled electro-thermal-mechanical device modeling remains shallow relative to scaling fabrication capacity.
- CMOS backend integration complexity:Thermal budget constraints during memristor stack deposition limit foundry process window compatibility and extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memristor Market |
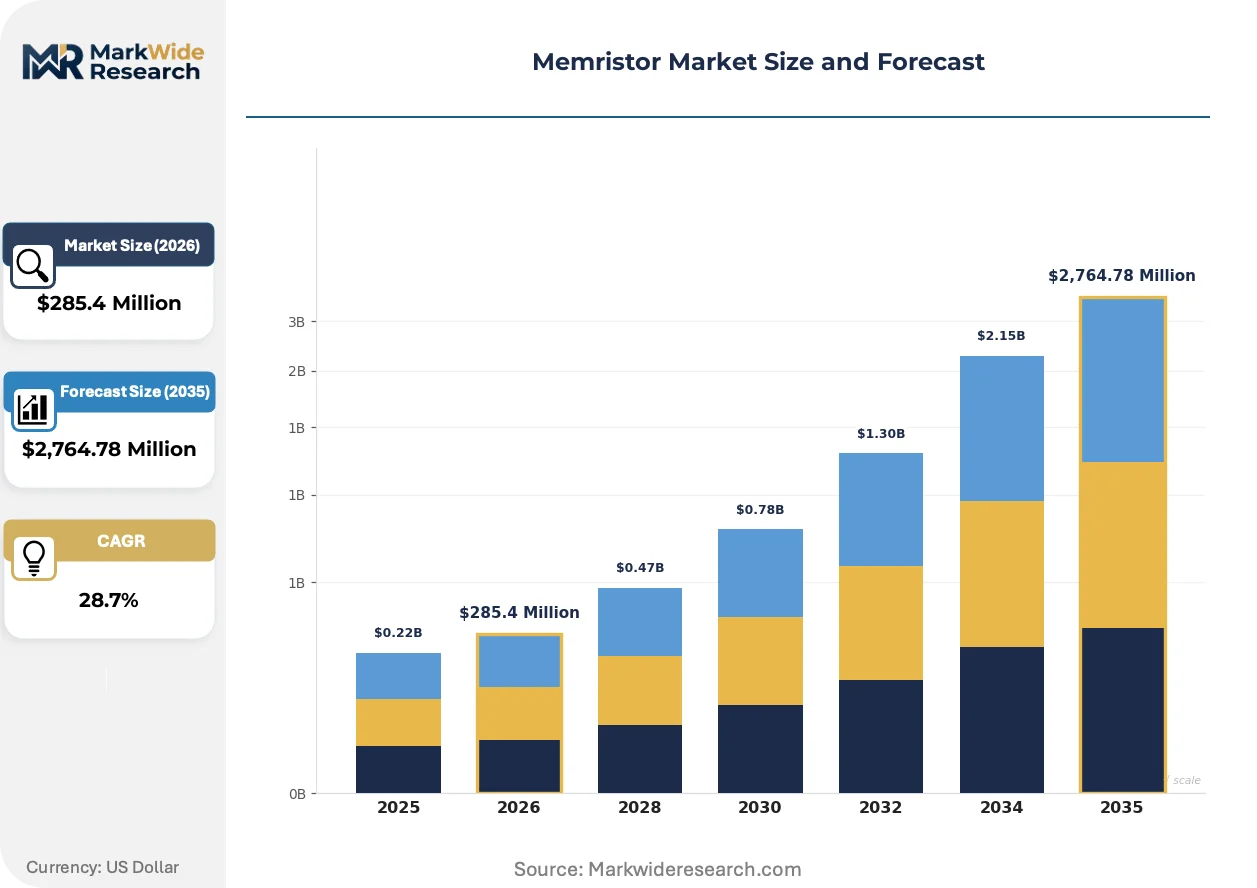
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,764.78 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Memristors, Digital Memristors, Hybrid Memristors, Memory Cells End User: Consumer Electronics, Telecommunication, Automotive, Industrial Applications Technology: Crossbar Arrays, Resistive Switching, 3D Architectures, CMOS Integration Application: Neuromorphic Computing, Data Storage, Signal Processing, Logic Circuits |
| Companies Covered | IBM Corporation, Samsung Electronics, Crossbar Inc, Fujitsu, Micron Technologies, Weebit Nano, Intel Corporation, Renesas Electronics Corporation, Knowm Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memristor Market Strategic Shifts & Innovations
Memristor technology is crossing from materials science demonstration toward system-level architecture decisions, with integration methodology now outpacing device physics as the primary innovation frontier.
Filamentary-switching hafnium-oxide stacks are unifying analog computation and non-volatile storage within single device structures. Automotive edge-AI developers are adopting these architectures for inference engines requiring both weight retention and in-situ learning capability. This unification is compressing the traditional separation between memory and processing units in neural network hardware.
REACH restrictions on precursor chemicals are reshaping European thin-film manufacturing supply chains. ECHA documentation requirements for metal-organic sources now extend to secondary suppliers of deposition equipment. South Korean foundries are responding by vertically integrating precursor purification to maintain qualification status for EU-bound shipments.
Buyer concentration among hyperscale data center operators is forcing memristor vendors into long-term capacity reservation contracts. Merchant suppliers without captive fabrication are losing access to leading-edge CMOS integration slots. This pattern is most visible in South Korea, where Samsung Electronics and government-backed consortia control wafer allocation for resistive-switching arrays.
Memristor Market Segmentation
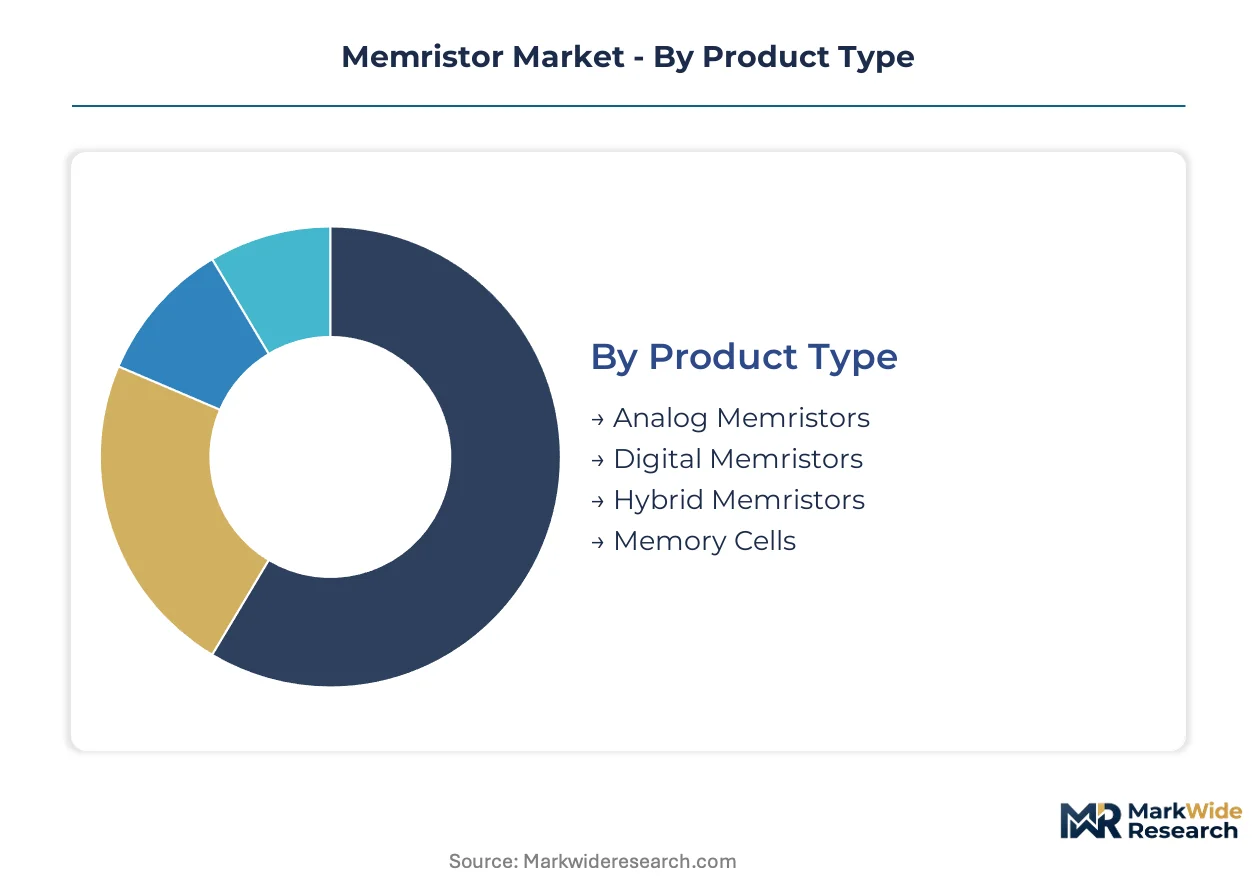
Memristor procurement patterns diverge sharply across integration complexity and end-use reliability requirements. Upgrade cycles in data center inference engines and automotive edge modules are pulling differentiated device architectures into volume production.
Product Type:
Replacement cycles in neuromorphic hardware favor architectures that bridge analog precision with digital endurance, reshaping foundry qualification priorities.
- Analog Memristors:These devices enable continuous resistance tuning through graded conductance states, essential for synaptic weight emulation in neural network accelerators. Cloud operators in South Korea are pulling these architectures into commercial inference engines requiring in-situ learning capability.
- Digital Memristors:Binary-state devices with deterministic switching thresholds serve non-volatile storage applications where refresh power elimination outweighs analog precision. Data center operators prioritize these for memory-class reliability in enterprise storage tiers.
- Hybrid Memristors:Architectures combining deterministic digital switching with tunable analog ranges are capturing margin pools at storage-compute boundaries.
- Memory Cells:Discrete resistive-switching elements optimized for density and endurance in standalone non-volatile arrays.
Digital memristors sit at the top of the volume ranking, with analog memristors climbing the fastest.
End User:
Cost tier differentiation separates captive foundry supply for hyperscale operators from merchant market access for industrial automation.
- Consumer Electronics:Wearable and mobile device manufacturers drive demand for ultra-low-power non-volatile storage. South Korean government-backed consortia are accelerating CMOS-compatible production for this tier.
- Telecommunication:Base station and edge infrastructure operators require memristor-based signal processing for adaptive filtering in 5G networks.
- Automotive:Edge-AI inference modules for autonomous systems demand both weight retention and radiation tolerance. REACH compliance documentation for precursor chemicals now extends to secondary suppliers serving this sector.
- Industrial Applications:Factory automation and predictive maintenance systems adopt resistive-switching arrays for embedded neural networks.
Consumer electronics commands the largest procurement volumes, while automotive applications are gaining share fastest.
Technology:
Integration maturity determines foundry slot allocation more than device performance alone, with CMOS backend compatibility now the primary gatekeeper.
- Crossbar Arrays:Dense two-terminal device matrices enable parallel read-write operations for neural network weight storage. Samsung Electronics leverages captive fabrication networks to sustain wafer-level integration of these architectures.
- Resistive Switching:Filamentary metal-oxide mechanisms in hafnium oxide and titanium dioxide films provide sub-nanosecond switching thresholds. EPA hazardous substance reporting requirements for oxide deposition processes add compliance overhead to sub-scale fabrication facilities.
- 3D Architectures:Vertically stacked memristor layers multiply bit density without lithographic scaling.
- CMOS Integration:Backend-compatible processing enables memristor deposition atop conventional logic wafers.
Resistive switching occupies the highest volume tier, with CMOS integration expanding most quickly.
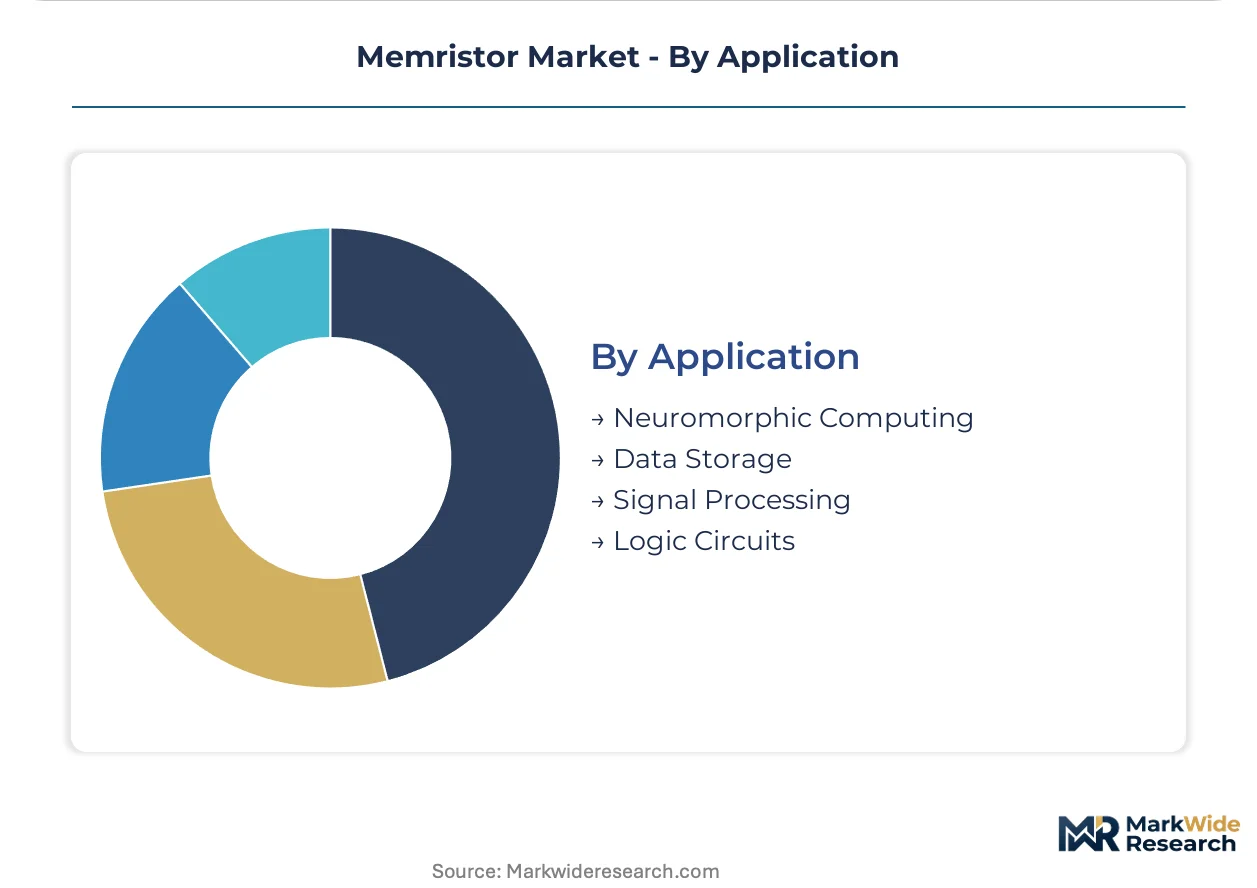
Application:
Customer type bifurcation separates hyperscale data center operators with guaranteed offtake contracts from industrial buyers in fragmented procurement.
- Neuromorphic Computing:Brain-inspired architectures using memristors as artificial synapses and neurons for event-based processing. Intel Corporation anchors its position through in-house development of CMOS-compatible logic for these systems.
- Data Storage:Non-volatile memory arrays replacing DRAM and flash in power-constrained environments. EU Green Deal carbon footprint mandates are creating preference for refresh-free alternatives.
- Signal Processing:Analog memristor networks performing matrix-vector multiplication for real-time sensor fusion.
- Logic Circuits:Stateful logic implementations using memristors as both memory and computational elements.
Data storage leads in current shipment volumes, with neuromorphic computing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized device physicists and process integration engineers cluster in South Korea, the United States, and Germany, anchoring the geographic distribution of memristor R&D and pilot production capacity.
South Korea
Seoul Capital Area foundries serve neuromorphic computing demand from hyperscale data center operators. The Ministry of Trade, Industry and Energy channels national R&D funding through METI-aligned consortia for next-generation memory commercialization. Samsung Electronics leverages its captive semiconductor fabrication network in Suwon and Pyeongtaek to sustain wafer-level integration of resistive-switching arrays.
United States
Silicon Valley and Greater Boston harbor edge-AI inference developers pulling CMOS-compatible memristor logic into commercial deployment. EPA hazardous substance reporting requirements for oxide deposition processes add compliance overhead that filters out sub-scale fabrication facilities. Intel Corporation anchors its position through in-house development in Hillsboro, Oregon and Santa Clara, California.
Japan
Tokyo-Osaka corridor electronics conglomerates drive demand for filamentary-switching architectures in industrial automation systems. METI standards for advanced memory commercialization guide national R&D allocation toward resistive-switching scale-up. Crossbar Inc maintains development operations in Tokyo while targeting the analog computation niche.
Germany
Bavaria and Baden-Württemberg automotive suppliers adopt memristor-based edge-AI modules for autonomous driving inference engines. REACH compliance mandates from ECHA restrict precursor chemicals used in thin-film manufacturing, consolidating procurement toward qualified vendors. Infineon Technologies AG and Robert Bosch GmbH anchor industrial demand in Dresden and Stuttgart clusters.
China
Yangtze River Delta memory fabs pursue CMOS backend integration for non-volatile storage applications. MIIT guidelines for domestic semiconductor self-sufficiency accelerate local memristor process development. Hefei and Shanghai house the primary concentration of government-backed foundry investment in resistive-switching technology.
Memristor Market Key Industry Players
Top-tier vendors anchor captive foundry networks, while merchant suppliers chase qualification status for hyperscale offtake contracts. The supply base bifurcates between integrated device manufacturers with in-house fabrication and fabless specialists dependent on external wafer allocation. Three archetypes dominate: captive semiconductor conglomerates, neuromorphic computing pure-plays, and memory-class diversified suppliers. Competitive moves center on CMOS integration partnerships and REACH-compliant precursor supply chain certification.
Among diversified memory suppliers, Micron Technologies and Fujitsu occupy positions spanning commodity storage and emerging resistive-switching applications. Samsung Electronics exemplifies the captive fabrication archetype, leveraging vertical control over wafer processing to secure neuromorphic-grade device supply. These three entities represent the tiered structure separating qualified volume suppliers from laboratory-scale competitors.
| Leading Market Players |
|---|
| IBM Corporation |
| Samsung Electronics |
| Crossbar Inc |
| Fujitsu |
| Micron Technologies |
| Weebit Nano |
| Intel Corporation |
| Renesas Electronics Corporation |
| Knowm Inc |
| Others |
Cost & Logistics Intelligence
CMOS backend integration of memristor stacks onto conventional logic wafers is compressing fabrication economics while concentrating procurement power among foundries with qualified thermal-budget processes. This production-method transition simultaneously raises capital barriers for sub-scale facilities and shifts margin capture toward vertically integrated device manufacturers with captive wafer allocation.
Pricing Analysis
Device-plus-certification bundling dominates memristor transactions, with REACH-compliant precursor documentation and CMOS integration slots priced separately from base silicon. Price differentiation hinges on foundry qualification tier and environmental traceability grade, with neuromorphic-grade analog devices commanding substantial premiums over storage-class digital variants. Pricing pressure stems from hafnium oxide precursor cost volatility as supply concentrates among limited high-purity metal-organic sources. Hyperscale data center operators exhibit lowest price sensitivity due to guaranteed offtake contracts, while industrial automation buyers face acute cost compression.
Supply Chain Analysis
Dual-sourcing mandates from automotive and defense buyers are forcing qualification of secondary precursor suppliers and redundant foundry relationships. Manufacturing concentrates in South Korea, the United States, and Germany, with each hub feeding distinct end-use certifications. Supply chains draw from high-purity hafnium and titanium metal-organic precursors, specialized sputtering targets, and qualified CMOS backend capacity. Single-source vulnerability persists in EUV-compatible deposition equipment. Distribution runs through captive foundry networks for tier-one buyers and merchant distributors for qualified smaller-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Memristor markets offer margin expansion through neuromorphic-grade premium tier capture as data center inference demand outpaces commodity storage growth. Cost-down trajectories in CMOS backend integration are compressing production economics for qualified suppliers.
For Market Incumbents: Deploy captive foundry capacity reservation as the primary defensive lever against merchant supplier encroachment. Secure long-term precursor supply agreements with REACH-certified chemical vendors to maintain EU market access. Accelerate in-house multi-physics simulation talent acquisition to compress device qualification timelines before emerging pure-plays achieve CMOS integration parity.
For New Entrants and Emerging Players: Capture edge-AI inference module opportunities in automotive and industrial automation where buyer concentration remains fragmented and qualification pathways are shorter. Target German automotive clusters and Japanese industrial automation OEMs as the most penetrable geographies outside South Korean foundry dominance. Pursue fabless partnerships with government-backed consortia to secure wafer allocation without capital-intensive fabrication investment.
For Investors and Strategic Acquirers: Valuations sit cheapest among neuromorphic computing pure-plays with demonstrated CMOS integration but limited commercial offtake contracts. Long-term viability over the next decade rests on securing hyperscale data center qualification status before captive fabrication networks achieve cost parity. Watch for South Korean government R&D funding announcements as the critical inflection signal for foundry slot allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Precursor Certification | ECHA documentation requirements filter uncertified suppliers from EU-bound shipments. |
| CMOS Backend Integration Partnership | Samsung Electronics and Intel Corporation anchor positions through captive wafer processing. |
| Neuromorphic-Grade Device Qualification | Cloud operators in South Korea pull advanced architectures into commercial inference engines. |
| Edge-AI Module Volume Scale-Up | Automotive and industrial automation buyers adopt resistive-switching arrays for embedded neural networks. |
| Multi-Physics Simulation Talent Acquisition | Coupled electro-thermal-mechanical modeling expertise remains scarce relative to fabrication capacity expansion. |
Research Approach
Coverage spans South Korea, the United States, Germany, Japan, and China, with primary inputs from each market cluster. Foundry process engineers, device physicists at neuromorphic computing startups, automotive Tier 1 procurement leads, and EPA regulatory compliance officers provided structured interviews. Secondary validation drew from ECHA REACH substance databases, SEC semiconductor capex disclosures, METI advanced memory program filings, and customs trade records for metal-organic precursor shipments. Bottom-up unit economics triangulated against top-down foundry capacity models.
Granularity-level modeling addressed product type, end-use sector, integration technology, and application across the analysis window. Analog memristor synaptic precision requirements, digital memristor endurance specifications, and hybrid architecture thermal budgets were parameterized separately. CAGRs derived from wafer-level shipment projections and foundry slot allocation forecasts. Neuromorphic computing adoption curves and data center power-consumption reduction mandates served as industry-specific demand inputs.
Filamentary switching reliability breakthroughs, REACH precursor supply disruptions, and CMOS backend thermal budget constraint relaxation are the dominant revision risks. Forecasts reflect assumptions on foundry qualification timelines and hyperscale offtake contract coverage. Deviation in South Korean government R&D funding allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
In-Memory Computing Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
In-Memory Grid Market
Memory Chips
Next Generation Memory Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Static RAM Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
MRAM Market
Memory Chips
DDR SDRAM Market
Memory Chips
ECC Memory Market
Memory Chips
Smartphone RAM Market
Memory Chips
Memory Chip Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
DDR RAM Market
Memory Chips
Automotive DRAM Market