
 Smartphone RAM Market | 2026-2036
Smartphone RAM Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone RAM Market Analysis
Flagship smartphone OEMs is reorganizing procurement priorities around on-device generative AI workloads, pulling memory specifications upward across premium tiers. Samsung Electronics leverages vertical integration from DRAM wafer fabrication through handset assembly to capture margin at multiple stages. SK Hynix anchors supply relationships with non-integrated OEMs seeking LPDDR5X qualification. Micron Technology competes on advanced packaging geometries for space-constrained mobile designs.
Smartphone RAM comprises low-power double data rate synchronous dynamic random-access memory engineered for thermal-constrained mobile environments, typically operating below 1.1V with multi-channel architectures to sustain bandwidth for application processors and neural engines. LPDDR5 and emerging LPDDR5X variants now dominate premium tier allocations where memory bandwidth directly constrains on-device AI inference performance. DRAM module form factors persist in repair and refurbishment channels, while BGA package configurations capture volume in original manufacturing. OEM end users command direct allocation agreements, whereas aftermarket providers navigate supply discontinuities as legacy LPDDR4 platforms phase down.
FCC equipment authorization in the United States, CE marking under the EU Radio Equipment Directive, and MIIT network access licensing in China collectively gate market entry and shape electromagnetic compatibility and material disclosure requirements. REACH substance restrictions and evolving EU battery regulation traceability mandates extend compliance burdens upstream to semiconductor packaging materials. Stakeholders must monitor whether on-device AI compute requirements compress replacement cycles or instead extend device longevity through cloud-offload architectures.
Market Dynamics
Memory bandwidth requirements for on-device generative AI inference are compressing smartphone refresh cycles and pulling LPDDR5X adoption forward across premium tiers, restructuring procurement relationships between integrated and non-integrated OEMs.
Growth Catalysts
- MIIT Network Access Licensing:China's accelerated certification timelines for 5G-enabled devices force memory component refreshes to align with handset launch windows, tightening supplier qualification schedules.
- On-Device AI Workloads:Neural engine integration in application processors demands higher memory bandwidth, expanding LPDDR5X allocations in flagship BOMs.
- East Asian Manufacturing Clusters:Concentrated DRAM fabrication in South Korea, Taiwan, and China reduces logistics friction for smartphone assembly hubs in Shenzhen and Hanoi.
Market Restraints
- Wafer Input Cost Volatility:Silicon wafer pricing fluctuations and noble metal sputtering targets in DRAM cell manufacturing compress foundry margins during supply gluts.
- Single-Source Packaging Concentration:Advanced BGA substrate supply concentrates among Japanese and Taiwanese specialists, creating chokepoints for high-density mobile modules.
- Power-Performance Ceiling:Thermal dissipation limits in sub-6mm chassis designs constrain voltage scaling below 0.5V for next-generation LPDDR6 architectures.
Strategic Opportunities
- India Production-Linked Incentive Scheme:Smartphone assembly shifting to Noida and Chennai creates localized memory module demand requiring new distributor relationships.
- EU Battery Regulation Traceability:Upstream material disclosure mandates for semiconductor packaging create first-mover advantage for suppliers with certified conflict-free supply chains.
- Foldable Form Factor Convergence:Dual-screen and tri-fold devices combine tablet-class multitasking with smartphone portability, expanding RAM configurations beyond traditional mobile ceilings.
Industry Challenges
- Advanced Packaging Talent Scarcity:Hybrid bonding and through-silicon via expertise concentrates among veteran engineers in Hsinchu and Yongin, constraining capacity expansion.
- LPDDR4 Legacy Integration Friction:Mid-tier OEMs maintaining dual-sourcing across memory generations face firmware complexity and validation timeline compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone RAM Market |
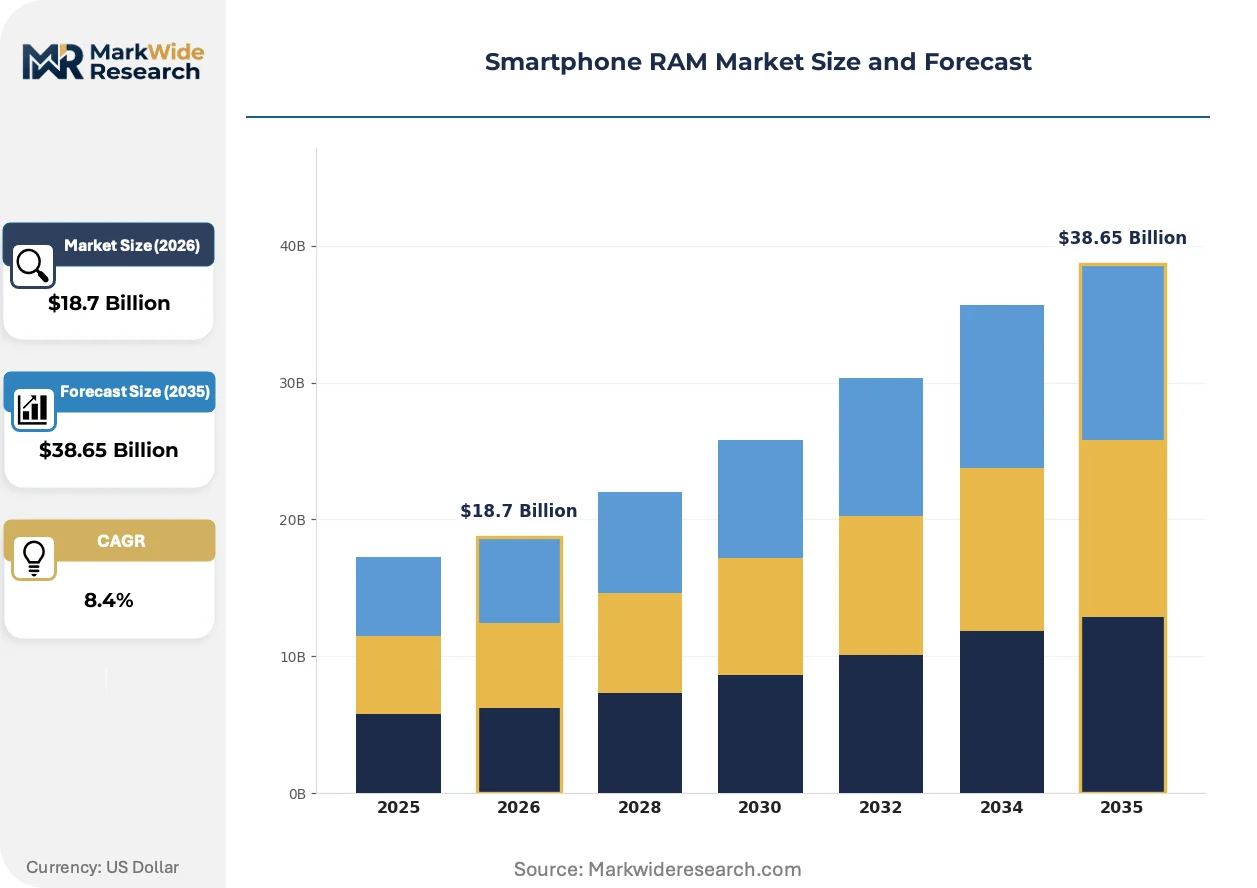
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: LPDDR4, LPDDR5, DDR4, DDR5 Capacity: 2GB, 4GB, 6GB, 8GB Form Factor: DRAM Chip, DRAM Module, BGA Package, TSOP Package End User: OEMs, Retailers, Distributors, Aftermarket Providers |
| Companies Covered | Apple, Oppo, Samsung Electronics, Transsion, Vivo, SK Hynix, Xiaomi, Honor, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone RAM Market Emerging Trajectories
Memory subsystem architectures are fragmenting across thermal envelopes and AI compute requirements, splitting development roadmaps between bandwidth-optimized and power-optimized trajectories.
Monolithic DRAM die stacking is decomposing into hybrid bonding configurations for flagship smartphones. Samsung Electronics and SK Hynix now deploy copper-to-copper direct bonding for 16-layer and above vertical integration, enabling 24GB+ capacities within 0.8mm z-heights. This bonding transition is decomposing traditional wire-bond packaging margins and forcing substrate vendors into co-development partnerships with foundries.
REACH substance restrictions under ECHA jurisdiction now mandate full material disclosure for semiconductor packaging sold into EU member states. Smartphone OEMs serving Germany, France, and Netherlands markets require suppliers to certify brominated flame retardant elimination and PFAS-free molding compounds by 2026. Memory module vendors are responding with halogen-free substrate laminates that trade thermal conductivity for regulatory compliance.
Direct allocation agreements between DRAM foundries and flagship OEMs are displacing spot-market procurement for premium tier volumes. Apple, Samsung Mobile, and Xiaomi now contract quarterly wafer starts rather than purchasing finished modules through distribution, compressing margin capture for independent memory houses. This contractual pivot is most visible in South Korea and China, where vertically integrated handset makers leverage captive foundry relationships.
Smartphone RAM Market Segmentation
Technology transitions in smartphone RAM fragment procurement strategies across memory generations, packaging formats, and supply chain tiers. Understanding segment-level margin distribution enables suppliers to prioritize qualification investments and OEMs to optimize BOM allocation across device tiers.
Type:
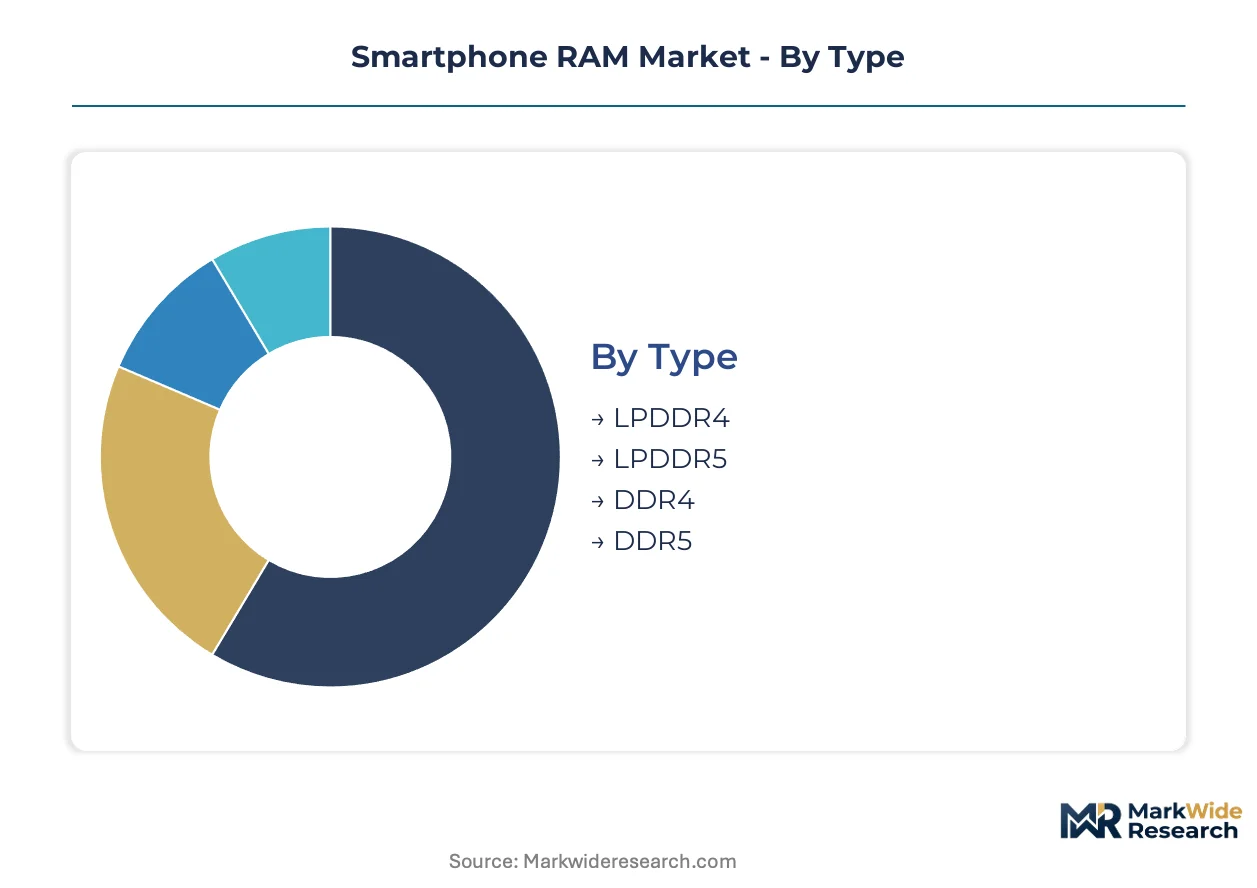
Margin pools concentrate in LPDDR5 and emerging LPDDR5X variants where bandwidth specifications differentiate flagship positioning and command premium pricing over legacy nodes.
- LPDDR4:Remains entrenched in mid-tier and budget smartphone SKUs where cost optimization outweighs AI bandwidth requirements. Demand concentrates in Southeast Asian assembly hubs serving India and Indonesia markets as OEMs extend platform lifecycles to manage certification costs.
- LPDDR5:Delivers 6400 Mbps transfer rates at sub-1.1V operation, enabling neural engine data feeds without thermal throttling in sub-7mm chassis designs. Samsung Electronics and SK Hynix have shifted wafer starts decisively toward this node as flagship OEMs in South Korea and China mandate minimum 8GB LPDDR5 for generative AI features.
- DDR4:Persists in ruggedized industrial smartphones and legacy platform maintenance where backward compatibility constraints block memory subsystem redesigns.
- DDR5:Captures negligible smartphone volume; limited adoption appears in hybrid tablet-phone convergence devices requiring desktop-class memory bandwidth.
LPDDR4 holds installed capacity across mature device ecosystems. LPDDR5 is rotating up the share rankings as MIIT certification timelines accelerate 5G handset refresh cycles.
Capacity:
Volume-weighted procurement concentrates at 8GB configurations where AI inference workloads and multitasking expectations converge across premium tier positioning.
- 2GB:Survives in ultra-low-cost feature phone replacements and secondary market refurbishment channels serving Sub-Saharan African and South Asian price-sensitive segments.
- 4GB:Dominates entry-level 5G smartphone SKUs where OEMs balance Android system requirements against sub-$150 retail price points. Indian PLI scheme beneficiaries in Noida and Chennai source this tier heavily for domestic distribution.
- 6GB:Occupies the mid-premium transition zone where Chinese OEMs differentiate sub-flagship lines; firmware optimization reduces physical memory requirements versus raw specification competition.
- 8GB:Standardizes across flagship tiers with on-device large language model deployment. Apple, Samsung Mobile, and Xiaomi direct allocation agreements specify 8GB minimums for generative AI photography and real-time translation features.
4GB maintains shipment volume leadership in absolute units. 8GB is climbing the fastest as BOM specifications inflate across premium tier roadmaps.
Form Factor:
Packaging margin capture splits between BGA substrate specialists capturing value-add assembly and bare die shipments feeding vertically integrated handset manufacturers.
- DRAM Chip:Bare die shipments flow directly to Samsung Electronics and Apple captive packaging operations, bypassing module vendor margin extraction entirely.
- DRAM Module:Standard DIMM and SO-DIMM configurations serve repair and refurbishment channels rather than original manufacturing; aftermarket providers in Shenzhen and Dubai source legacy modules for screen replacement bundling.
- BGA Package:Ball grid array mounting dominates smartphone original manufacturing with 0.35mm pitch specifications enabling 16-layer die stacking within strict z-height constraints. Japanese and Taiwanese substrate vendors co-develop laminate designs with SK Hynix and Micron Technology.
- TSOP Package:Thin small-outline package legacy persists in industrial smartphone variants requiring through-hole soldering compatibility and extended temperature range operation.
BGA Package commands original equipment attachment. DRAM Chip is gaining share fastest as vertical integration deepens among South Korean and Chinese handset OEMs.
End User:
Procurement authority concentrates with OEMs executing direct foundry allocation agreements, compressing distributor and aftermarket provider margin opportunities to legacy and repair segments.
- OEMs:Apple, Samsung Mobile, Xiaomi, OPPO, and vivo negotiate quarterly wafer start commitments with Samsung Electronics and SK Hynix, locking in supply security and price visibility across 12-18 month horizons.
- Retailers:Consumer electronics chains in Germany, France, and Netherlands stock replacement modules for customer self-installation; REACH substance disclosure requirements now mandate halogen-free substrate certification for EU market entry.
- Distributors:Arrow Electronics, Avnet, and regional specialists in Singapore and Hong Kong manage buffer inventory for mid-tier OEMs lacking direct foundry relationships; margin compression intensifies as allocation agreements displace spot purchasing.
- Aftermarket Providers:Independent repair shops and refurbishment specialists navigate supply discontinuities as LPDDR4 platforms phase down; Shenzhen component markets provide gray-market sourcing for legacy device support.
OEMs hold installed procurement authority. Aftermarket Providers are expanding most quickly as right-to-repair regulations in EU member states and US states mandate spare part availability extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flagship smartphone OEM procurement concentrates in East Asian manufacturing clusters where DRAM foundries and handset assembly hubs co-locate. Samsung Electronics and SK Hynix anchor supply relationships with device makers across South Korea, China, and Taiwan. Direct allocation agreements now displace spot-market purchasing for premium tier volumes.
China
MIIT network access licensing compresses 5G handset certification timelines, forcing memory component refreshes to align with launch windows. The regulator's accelerated approval schedules tighten supplier qualification cycles for LPDDR5X modules. Shenzhen assembly hubs source heavily from domestic DRAM packaging specialists serving Xiaomi, OPPO, and vivo.
South Korea
Samsung Electronics leverages captive DRAM fabrication through handset assembly to capture margin at multiple supply chain stages. The Korea Communications Commission enforces electromagnetic compatibility standards that shape BGA substrate specifications. Yongin and Hwasung industrial corridors host hybrid bonding expertise for 16-layer die stacking in sub-0.8mm z-heights.
United States
FCC equipment authorization gates market entry with electromagnetic compatibility and RF exposure requirements. Apple negotiates quarterly wafer start commitments directly with Samsung Electronics and SK Hynix, bypassing module vendor margin extraction. Cupertino and Austin engineering centers specify memory bandwidth minimums for neural engine integration.
India
The PLI scheme attracts smartphone assembly to Noida and Chennai, creating localized memory module demand through new distributor relationships. BIS certification mandates for electronic components extend qualification timelines for imported DRAM modules. Tamil Nadu and Uttar Pradesh manufacturing zones source 4GB LPDDR4 configurations heavily for sub-$150 domestic retail segments.
Taiwan
Advanced BGA substrate supply concentrates among Taiwanese specialists, creating packaging chokepoints for high-density mobile modules. The National Communications Commission aligns 5G device certification with international standards. Hsinchu engineering clusters co-develop laminate designs with SK Hynix and Micron Technology for 0.35mm pitch specifications.
Smartphone RAM Market Vendor Landscape
Player mix skews toward vertically integrated conglomerates with captive DRAM fabrication and handset assembly operations. The market structure concentrates around three Korean and Chinese firms controlling upstream wafer supply and downstream device manufacturing. Strategic archetypes include integrated OEM-foundry combinations, independent DRAM specialists serving non-integrated device makers, and fabless module vendors focused on advanced packaging geometries. Competitive moves center on hybrid bonding capacity expansion and direct allocation agreements that displace spot-market procurement.
Within the integrated tier, Samsung Electronics exemplifies the conglomerate archetype spanning DRAM wafer fabrication through handset assembly. SK Hynix occupies a position as the primary independent supplier to non-integrated OEMs seeking LPDDR5X qualification. Micron Technology represents the advanced packaging specialist competing on space-constrained mobile geometries. These three anchors illustrate how procurement authority concentrates with foundries capable of quarterly wafer start commitments rather than finished module distribution.
| Leading Market Players |
|---|
| Apple |
| Oppo |
| Samsung Electronics |
| Transsion |
| Vivo |
| SK Hynix |
| Xiaomi |
| Honor |
| Micron Technology |
| Others |
Supply Flow & Price Mechanics
MIIT network access licensing gates both supplier qualification timelines and price differentiation between memory generations, compressing margins for vendors unable to align LPDDR5X modules with accelerated 5G handset certification windows in China.
Pricing Analysis
LPDDR5X commands substantial premiums over LPDDR5 and legacy LPDDR4 nodes, with three-tier pricing structure across premium, standard, and economy levels separating flagship OEM direct allocations from distributor spot purchases and aftermarket refurbishment supply. Price differentiation hinges on bandwidth certification tier and quarterly wafer commitment scale, with flagship OEMs locking volume pricing through 12-18 month foundry contracts. Cost compression in mid-tier LPDDR4 configurations is intensifying because platform lifecycle extensions dilute per-unit value. Entry-level smartphone OEMs sourcing 4GB modules for Indian PLI scheme assembly exhibit highest price sensitivity; Apple and Samsung Mobile direct allocation agreements show lowest.
Supply Chain Analysis
South Korea and Taiwan anchor wafer fabrication and advanced BGA substrate production, with China capturing downstream module packaging and smartphone assembly concentration. Silicon wafer feedstock and noble metal sputtering targets for DRAM cell manufacturing draw from Japanese and Australian suppliers. Single-source vulnerability concentrates in 0.35mm pitch substrate laminates co-developed by Hsinchu specialists with SK Hynix and Micron Technology. Distribution runs through quarterly wafer start commitments direct to flagship OEMs, bypassing traditional module vendor channels for premium tier volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid bonding expertise for 16-layer die stacking represents the critical skill gap constraining capacity expansion, with veteran engineering talent concentrated in Yongin and Hsinchu corridors creating acquisition premiums for firms seeking packaging leadership.
For Market Incumbents: Consolidate hybrid bonding capacity through captive expansion in Yongin or strategic substrate vendor partnerships in Hsinchu, defending against margin compression from direct allocation agreements displacing spot-market module sales. Prioritize REACH-compliant halogen-free laminate certification to capture EU Battery Regulation traceability premiums before 2026 mandates activate.
For New Entrants and Emerging Players: Differentiate on India PLI scheme localization, targeting Noida and Chennai assembly hubs with 4GB LPDDR4 module distribution relationships where BIS certification barriers limit incumbent penetration. Pursue aftermarket refurbishment channel partnerships in Shenzhen and Dubai for legacy platform support as LPDDR4 phase-down creates supply discontinuities.
For Investors and Strategic Acquirers: EU Battery Regulation traceability mandates reshape the acquisition landscape toward packaging specialists with certified conflict-free supply chains and material disclosure infrastructure. Five-to-ten year viability favors advanced BGA substrate vendors with co-development partnerships across SK Hynix, Micron Technology, and emerging Chinese foundry relationships. Monitor MIIT certification timeline compression as inflection signal for memory generation transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Enables 24GB+ LPDDR5X stacking within 0.8mm z-heights for foldable flagships. |
| REACH-Compliant Substrate Certification | Secures EU market entry ahead of 2026 halogen-free molding compound mandates. |
| India PLI Localization Partnership | Captures Noida and Chennai assembly demand for 4GB LPDDR4 domestic retail segments. |
| Direct Wafer Allocation Agreements | Locks quarterly supply commitments with Xiaomi, OPPO, and vivo bypassing distribution. |
| Aftermarket Refurbishment Channel Development | Exploits LPDDR4 phase-down supply gaps in Shenzhen component markets. |
Methodological Framework
A spread of perspectives from DRAM foundry procurement directors, smartphone OEM supply chain managers, BGA substrate vendor technical leads, and India PLI scheme manufacturing heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, MIIT network access license disclosures, and ECHA REACH substance registration databases. Bottom-up module shipment estimates triangulated against top-down wafer start projections from Samsung Electronics and SK Hynix.
Segmentation dimensions modeled span memory generation node, capacity configuration, packaging form factor, and end-user procurement tier across the analysis window. CAGRs derived from volume-weighted average selling price trajectories and unit shipment elasticities tied to 5G handset refresh cycles. Forecast inputs incorporated MIIT certification timeline compression, EU Battery Regulation material disclosure phase-in, and on-device AI bandwidth requirement scaling.
Material uncertainties — silicon wafer pricing volatility, noble metal sputtering target supply disruptions, and regulatory timeline accelerations — sit outside the modeled envelope. Forecasts reflect assumptions about LPDDR5X adoption velocity and foldable form factor RAM configuration expansion. Recalibration cycles align with material shifts in MIIT licensing schedules and REACH substance restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
China Flash Memory Market
Memory Chips
GDDR6 Market
Memory Chips
ECC Memory Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Memory Interface Chip Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Automotive Memory Market
Memory Chips
Memory Market
Memory Chips
Next Generation Memory Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
Contactless Memory Market