
 China Dynamic Random Access Memory (DRAM) Market | 2026-2036
China Dynamic Random Access Memory (DRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
China Dynamic Random Access Memory (DRAM) Market Insights
Domestic foundry-direct procurement is fragmenting as Beijing pushes semiconductor supply chain localization. SK hynix sustains advanced node production through its Wuxi complex while navigating technology transfer restrictions. ChangXin Memory Technologies anchors mainland DDR4 and LPDDR4 output with captive wafer capacity. Samsung Electronics competes through premium DDR5 modules serving Chinese server OEMs despite geopolitical headwinds.
Dynamic Random Access Memory stores each data bit within a separate capacitor-transistor pair arranged in integrated circuit arrays, typically fabricated on 1x nm to 1y nm process nodes with refresh cycles under 64 milliseconds to prevent charge leakage. The technology serves as working memory for processors across computing devices, enabling temporary data access at nanosecond speeds. DDR5 modules command widening adoption in data center builds as power efficiency and bandwidth thresholds outpace DDR4 limitations. Edge computing applications favor LPDDR4 for thermal-constrained deployments. 3D DRAM architectures represent the emerging technology frontier where Chinese foundries concentrate R&D capital.
MIIT's integrated circuit promotion policies shape domestic procurement quotas while SAMR enforces antitrust scrutiny on foreign suppliers. GB standards for semiconductor reliability testing constrain product entry pathways. NMPA-equivalent quality frameworks for automotive-grade memory extend compliance burdens to DRAM destined for electric vehicle ECUs. Stakeholders must weigh localization incentives against process technology gaps when calibrating capacity investments.
Market Dynamics
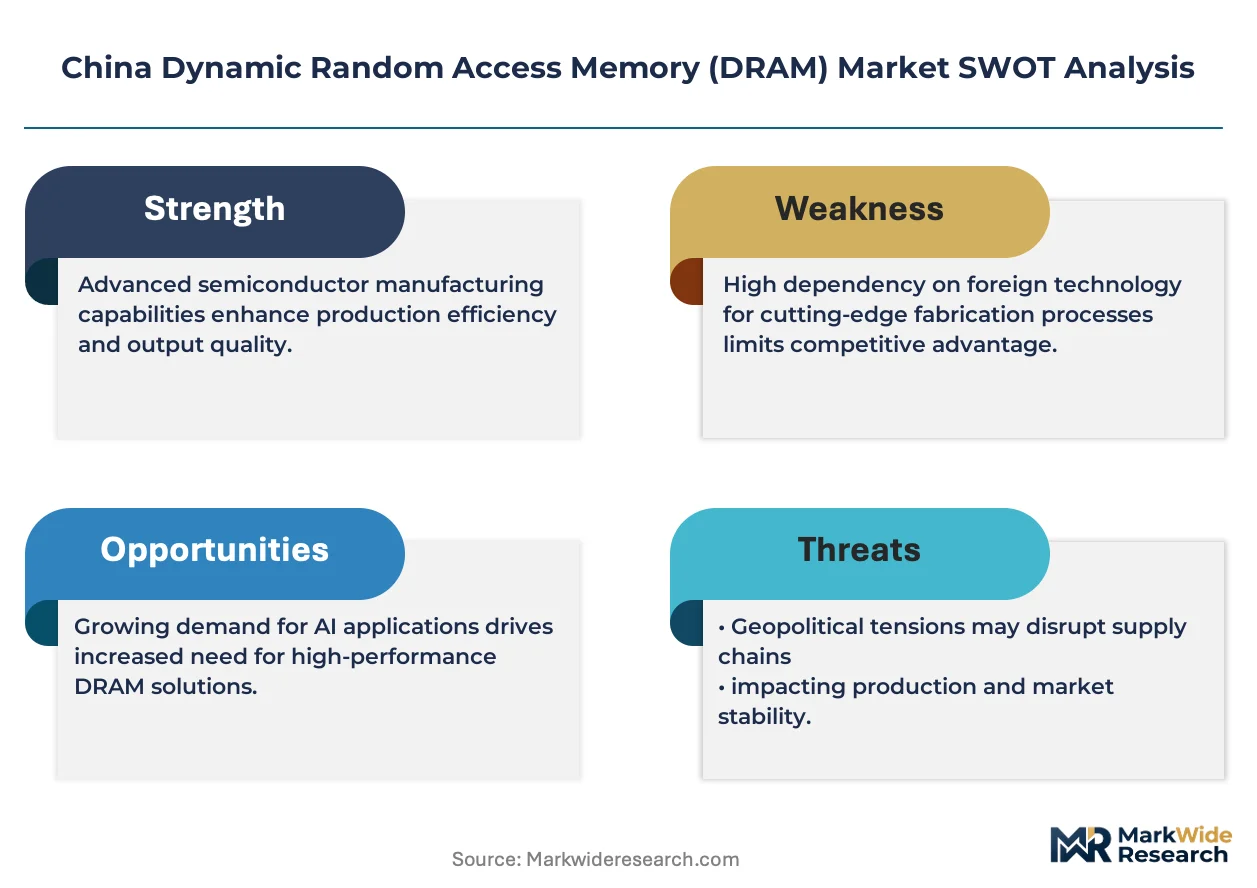
Beijing's localization mandates are fragmenting procurement channels across the China DRAM landscape, forcing foreign suppliers to restructure joint ventures and domestic foundries to accelerate captive capacity expansion.
Growth Catalysts
- Yangtze River Delta clustering:Shanghai-Nanjing-Hangzhou corridor concentrates advanced packaging and test facilities, creating density advantages for module assembly.
- MIIT integrated circuit guidelines:Domestic sourcing quotas for government cloud and state-owned enterprise procurement create guaranteed offtake for local DDR5 output.
- Server-grade DDR5 transition:Hyperscale datacenter buildouts by domestic cloud operators drive module refresh cycles at higher bandwidth-per-watt thresholds.
Market Restraints
- EUV lithography equipment embargo:Dutch ASML export controls constrain domestic foundries from advancing beyond 1x nm process nodes.
- Silicon wafer cost volatility:300mm prime-grade substrate prices fluctuate with polysilicon purity constraints and ingot pulling capacity.
- GB standards compliance burden:Reliability testing protocols for automotive-grade DRAM extend qualification timelines by 8-12 months versus consumer modules.
Strategic Opportunities
- Automotive ECU memory:Electric vehicle battery management and autonomous driving systems require AEC-Q100 qualified LPDDR4X at volumes outpacing current supply.
- 3D DRAM architecture R&D:Stacked cell designs bypass planar scaling limits and offer Chinese foundries a path to leapfrog foreign process leads.
- Edge computing thermal constraints:Industrial IoT gateways in Shenzhen and Chengzhou manufacturing zones favor low-power memory without active cooling.
Industry Challenges
- Process engineering talent scarcity:Senior DRAM designers with 1x nm experience command compensation premiums that strain domestic foundry opex.
- IP licensing complexity:Core cell architectures and sense amplifier patents held by foreign incumbents create royalty stacking for new entrants.
- Legacy DDR3 integration friction:Industrial automation systems in legacy manufacturing bases require extended support timelines incompatible with foundry product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Dynamic Random Access Memory (DRAM) Market |
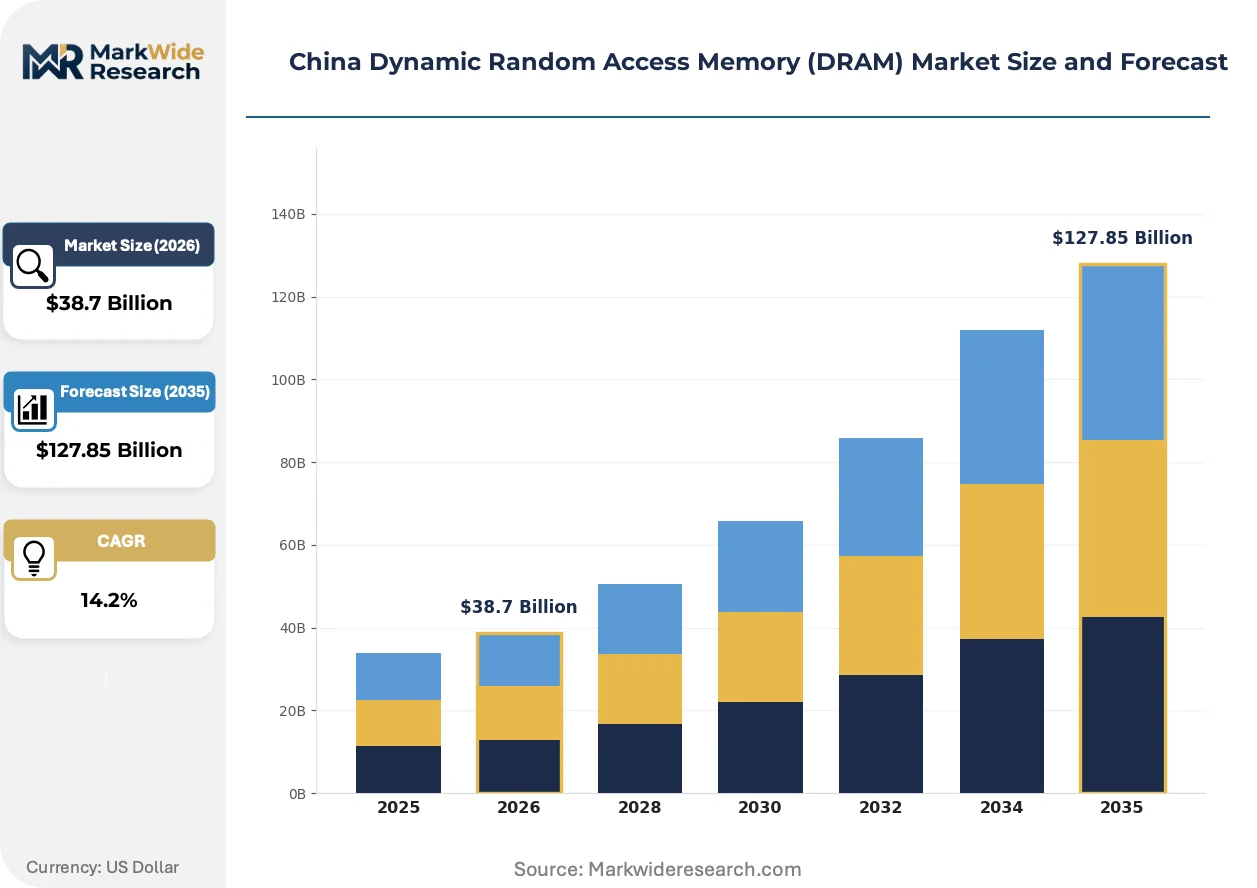
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR3, DDR4, DDR5, LPDDR4 End User: Consumer Electronics, Automotive, Data Centers, Mobile Devices Application: Gaming, Cloud Computing, Artificial Intelligence, Edge Computing Technology: CMOS, SOI, Hybrid Memory Cube, 3D DRAM |
| Companies Covered | SK hynix, GigaDevice Semiconductor, ChangXin Memory Technologies, Beijing Changxin Memory Technologies, Montage Technology, Yangtze Memory Technologies, Micron Technology, Wuhan Xinxin Semiconductor, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Dynamic Random Access Memory (DRAM) Market Trends and Innovations
Memory virtualization is compressing hardware refresh cycles across Chinese datacenter infrastructure, while regulatory pressure on supply chain provenance accelerates architectural redesigns.
Compute Express Link (CXL) is virtualizing memory pooling across server racks, enabling Chinese cloud operators to disaggregate DRAM from CPU sockets and improve utilization rates. ByteDance and Alibaba Cloud have deployed CXL 2.0 fabrics in trial clusters, treating memory as a composable resource rather than fixed capacity. This architecture is virtualizing the traditional DIMM procurement model and pressuring module vendors to certify interoperability at protocol layers.
MIIT's dual carbon goals are tightening energy efficiency mandates for semiconductor manufacturing facilities, with MEE enforcement extending to DRAM fabs in Wuxi and Hefei. New construction permits require renewable power purchase agreements covering 30% of baseload consumption. ChangXin Memory Technologies has responded by contracting solar farms in Anhui province to offset wafer fabrication draw.
Direct foundry procurement is displacing distributor intermediaries among tier-one server OEMs in Beijing and Shanghai. Lenovo and Inspur now negotiate annual volume agreements with SK hynix Wuxi and Samsung Xi'an for DDR5 modules, bypassing traditional component distributors. This channel compression is most visible in enterprise storage arrays where configuration standardization reduces the value of technical pre-sales support.
China Dynamic Random Access Memory (DRAM) Market Segmentation
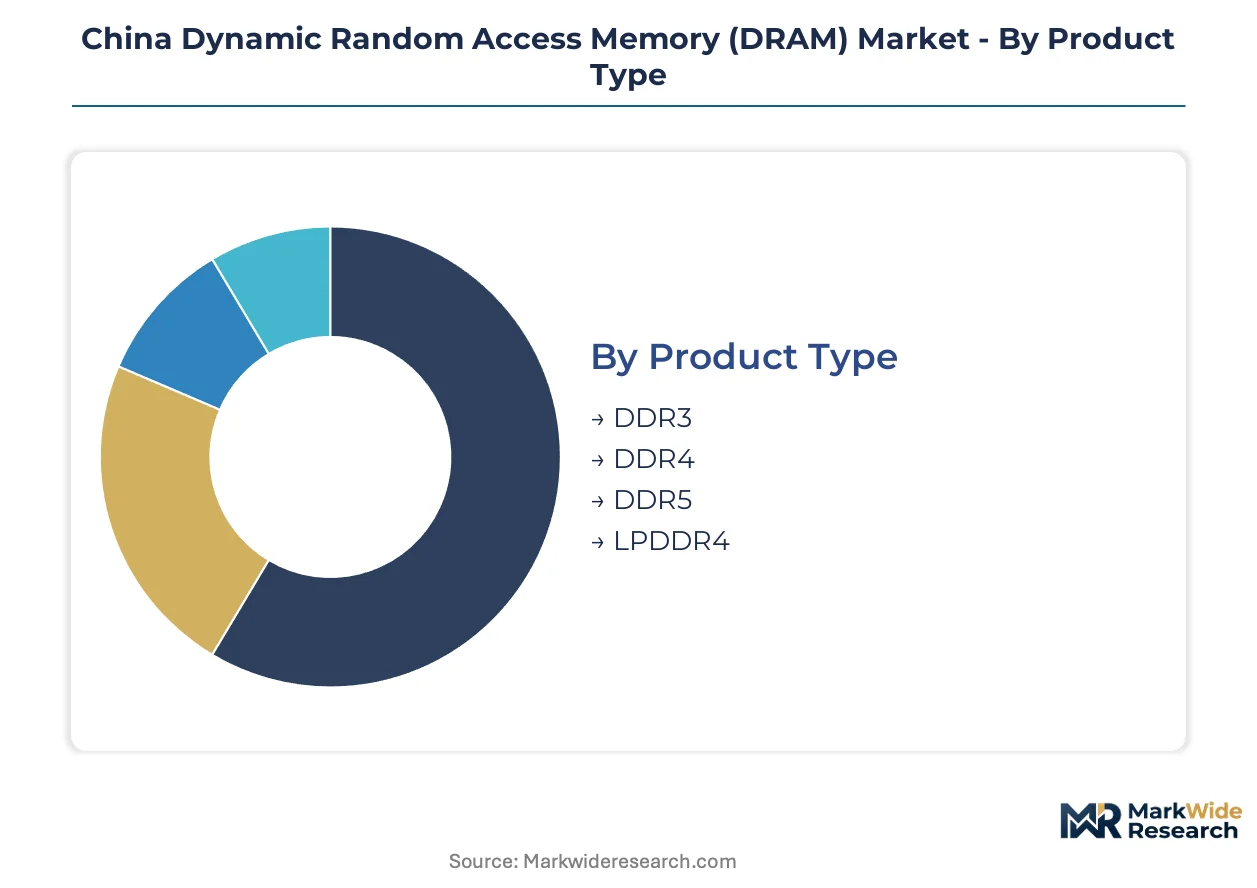
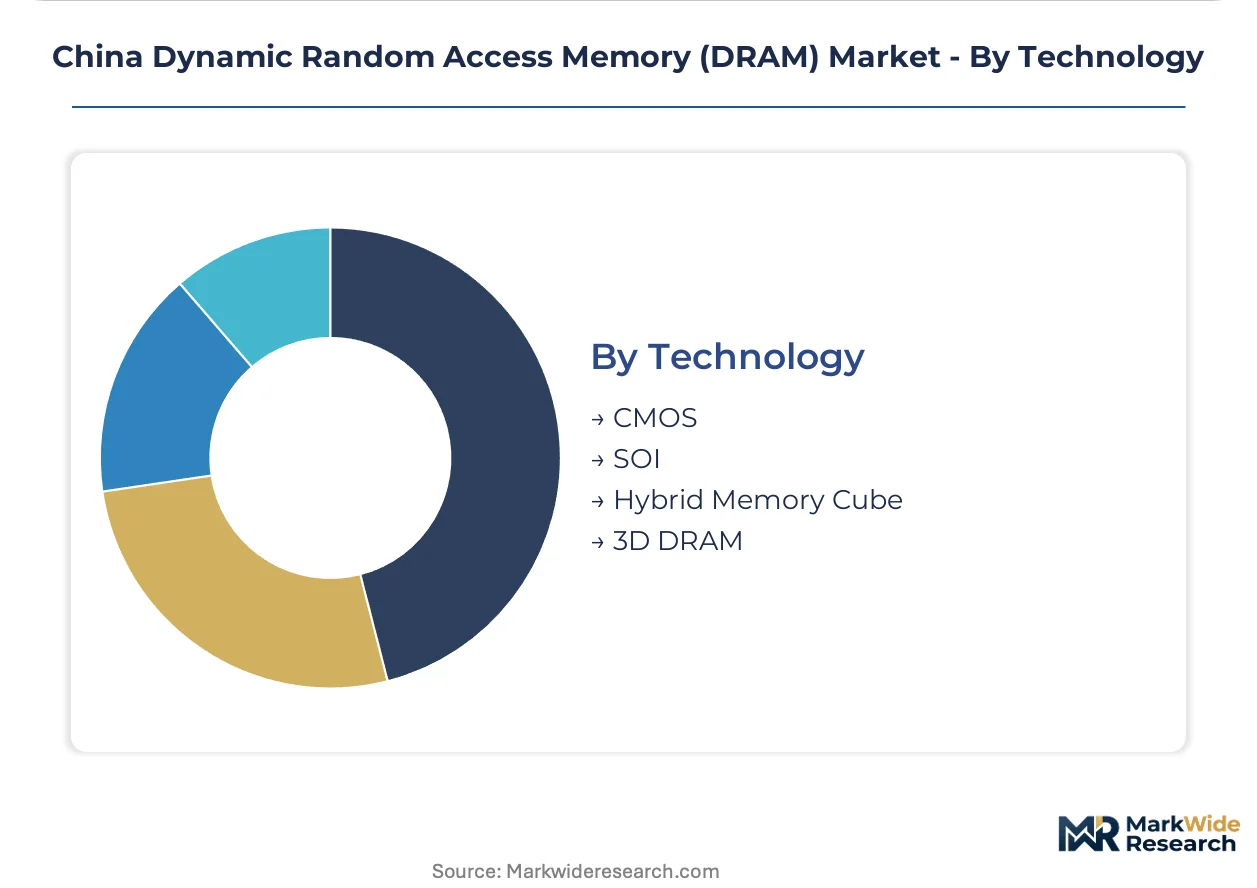
DRAM segmentation in China reflects a market caught between legacy infrastructure demands and frontier technology procurement. Product generations, end-use verticals, and architectural approaches each command distinct supply chain configurations and regulatory treatment under MIIT localization mandates.
Product Type:
Mature DDR generations anchor installed base replacement cycles while emerging standards capture hyperscale procurement volumes.
- DDR3:Legacy 1.5V modules persist in industrial automation controllers and medical imaging equipment where long qualification timelines resist migration. Procurement concentrates in legacy manufacturing zones around Chengdu and Xi'an where equipment refresh cycles extend beyond decade horizons.
- DDR4:1.2V operation with 3200 MT/s peak throughput dominates current server motherboard designs and consumer laptop builds. ChangXin Memory Technologies anchors mainland supply through captive wafer capacity in Hefei, though EUV constraints limit node advancement beyond 1x nm.
- DDR5:1.1V modules with on-die ECC and 4800+ MT/s bandwidth command premium positioning in domestic cloud operator racks. SK hynix Wuxi and Samsung Xi'an facilities supply hyperscale buildouts despite technology transfer restrictions.
- LPDDR4:Mobile-optimized 1.1V architecture with aggressive power gating serves thermal-constrained edge deployments. Shenzhen-based smartphone OEMs and automotive ECU designers drive qualification programs for extended temperature grades.
DDR4 retains volume leadership; DDR5 holds the steepest expansion curve.
End User:
Cost tier differentiation separates commodity procurement from qualification-intensive verticals with extended test protocols.
- Consumer Electronics:Desktop and laptop OEMs in Dongguan and Chongqing source DDR4 modules through distributor channels with minimal customization. Price sensitivity dominates procurement criteria with spot market exposure to wafer cost volatility.
- Automotive:AEC-Q100 qualification mandates separate production flows for temperature cycling and electromigration testing. NMPA-equivalent quality frameworks for electric vehicle battery management systems extend compliance timelines.
- Data Centers:ByteDance and Alibaba Cloud negotiate direct foundry agreements for server-grade DDR5, bypassing component distributors. CXL 2.0 memory pooling trials are virtualizing traditional DIMM procurement models.
- Mobile Devices:Shenzhen-headquartered smartphone assemblers specify LPDDR4X for flagship designs with stacked package-on-package configurations. Thermal constraints in 5G modem integration favor low-power architectures.
Data centers command the highest module ASPs; automotive offers the most demanding qualification barriers.
Application:
Volume concentration varies sharply between mass-market gaming builds and emerging AI training clusters with distinct memory bandwidth requirements.
- Gaming:RGB-equipped DDR4 modules with XMP 3.0 profiles target enthusiast desktop builds through e-commerce channels. Shandong and Guangdong-based system integrators drive seasonal procurement spikes.
- Cloud Computing:Hyperscale operators deploy DDR5 in 512GB-per-socket configurations for virtualization density. Direct foundry procurement is displacing distributor intermediaries among tier-one server OEMs.
- Artificial Intelligence:Training workloads demand HBM-class bandwidth that domestic foundries cannot yet supply, creating import dependency for GPU-attached memory. 3D DRAM R&D programs target this capability gap.
- Edge Computing:Industrial IoT gateways in manufacturing zones favor LPDDR4 without active cooling. Thermal-constrained deployments in Shenzhen and Chengzhou require extended temperature grade qualification.
Cloud computing absorbs the highest module volumes; artificial intelligence training clusters face the most acute supply constraints.
Technology:
Supply concentration separates established planar architectures from experimental stacked designs where Chinese foundries concentrate R&D capital.
- CMOS:Conventional bulk silicon processing with 1x nm feature sizes underpins DDR4 and DDR5 wafer fabrication. ChangXin Memory Technologies operates China's only captive DRAM fab using this approach.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for high-frequency LPDDR4X operation. Limited domestic substrate supply creates import dependency for premium mobile memory.
- Hybrid Memory Cube:Stacked memory-logic integration with through-silicon vias targets high-performance computing niches. Adoption remains constrained by thermal management complexity and ecosystem maturity.
- 3D DRAM:Vertical cell stacking architectures bypass planar scaling limits and offer a leapfrog path beyond EUV constraints. MIIT integrated circuit guidelines channel R&D funding toward this frontier.
CMOS retains fabrication dominance; 3D DRAM holds the most significant technology displacement potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's integrated circuit guidelines anchor procurement dynamics across Chinese sub-regions, with localization mandates reshaping supply chain configurations from the Yangtze River Delta to western industrial corridors.
Yangtze River Delta
Shanghai-Nanjing-Hangzhou corridor concentrates advanced packaging and test facilities for DDR5 module assembly. MIIT domestic sourcing quotas guarantee offtake for local output serving government cloud procurement. SK hynix sustains advanced node production through its Wuxi complex while navigating technology transfer restrictions.
Beijing-Tianjin-Hebei
Hyperscale datacenter buildouts by ByteDance and Baidu drive server-grade DDR5 demand at premium bandwidth-per-watt thresholds. SAMR antitrust scrutiny on foreign suppliers shapes procurement channel restructuring. Lenovo and Inspur negotiate direct foundry agreements, bypassing traditional component distributors in the capital region.
Pearl River Delta
Shenzhen-headquartered smartphone assemblers specify LPDDR4X for flagship designs with stacked package-on-package configurations. Thermal constraints in 5G modem integration favor low-power architectures. Industrial IoT gateways in Dongguan manufacturing zones favor LPDDR4 without active cooling.
Sichuan-Chongqing
Legacy DDR3 demand persists in industrial automation controllers where long qualification timelines resist migration. Chengdu-based equipment refresh cycles extend beyond decade horizons for medical imaging systems. GB standards compliance for automotive-grade DRAM extends qualification timelines for electric vehicle ECU suppliers.
Anhui Province
ChangXin Memory Technologies anchors mainland DDR4 and LPDDR4 output with captive wafer capacity in Hefei. MEE enforcement extends to DRAM fabs under MIIT dual carbon goals requiring renewable power purchase agreements. Solar farm contracts offset wafer fabrication draw for new construction permits.
China Dynamic Random Access Memory (DRAM) Market Competitive Landscape
Foreign-incumbent multinationals and domestic captive foundries split the market between premium DDR5 supply and localization-mandated procurement channels. The vendor base concentrates around three strategic archetypes: advanced-node foreign operators with Chinese fabrication assets, domestic pure-play memory specialists, and diversified semiconductor conglomerates with captive DRAM divisions. Competitive positioning hardens through direct foundry procurement agreements and R&D alliances targeting 3D DRAM architectures.
Among foreign operators with Chinese fabrication presence, SK hynix and Samsung Electronics occupy positions serving hyperscale cloud operator demand despite technology transfer headwinds. ChangXin Memory Technologies exemplifies the domestic captive foundry archetype, anchoring mainland supply for DDR4 and LPDDR4 generations under MIIT localization guidelines. Montage Technology sits within the interface specialist tier, representing connectivity and memory buffer chip positioning adjacent to core DRAM fabrication.
| Leading Market Players |
|---|
| SK hynix |
| GigaDevice Semiconductor |
| ChangXin Memory Technologies |
| Beijing Changxin Memory Technologies |
| Montage Technology |
| Yangtze Memory Technologies |
| Micron Technology |
| Wuhan Xinxin Semiconductor |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
Wafer fabrication equipment concentration in the Netherlands and Japan anchors margin capture at the lithography tier, leaving module assemblers in the Yangtze River Delta exposed to cost pass-through from upstream bottlenecks. Foundry-direct procurement by ByteDance and Alibaba Cloud compresses distributor margins while concentrating price negotiation leverage with hyperscale buyers.
Pricing Analysis
Geographic price spreads separate Wuxi-produced DDR5 modules from Korean-imported equivalents by certification tier and customs duty exposure. Three-tier pricing structure across AEC-Q100 automotive, enterprise server, and consumer desktop levels reflects qualification cost amortization rather than die yield differentiation. Cost compression in the DDR4 tier is intensifying because ChangXin Memory Technologies has expanded captive wafer output. Consumer electronics OEMs in Dongguan exhibit the highest price sensitivity; automotive ECU designers accept premiums for temperature-grade reliability.
Supply Chain Analysis
Dutch ASML export controls on EUV lithography systems constrain Chinese foundries from advancing beyond 1x nm process nodes. Taiwan, South Korea, and the United States anchor global supply for advanced node equipment and core IP licensing. The China DRAM supply chain draws from 300mm prime-grade silicon wafers sourced from Japan and Germany, photoresist chemicals from Belgium, and specialized packaging substrates from Taiwan. Single-source vulnerability concentrates at the lithography equipment tier where ASML holds effective monopoly. Distribution runs through direct foundry agreements for hyperscale buyers and authorized distributors for tier-two server OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hyperscale cloud operator consolidation, with ByteDance and Alibaba Cloud now commanding sufficient procurement volume to negotiate annual foundry-direct agreements that bypass traditional component distributors entirely.
For Market Incumbents: Entrench position through backward integration into advanced packaging capacity in the Yangtze River Delta corridor and accelerated R&D allocation toward 3D DRAM architectures that bypass EUV constraints. SK hynix and Samsung Electronics must defend Wuxi and Xi'an fabrication assets against technology transfer restrictions by localizing senior process engineering talent. Certification investment in AEC-Q100 automotive grades offers margin defense against commodity DDR4 price erosion. For New Entrants and Emerging Players: Build out captive wafer capacity targeting LPDDR4X for automotive ECU applications where AEC-Q100 qualification creates incumbent friction. The Sichuan-Chongqing industrial corridor offers the most penetrable geography given legacy DDR3 replacement cycles and extended equipment refresh timelines. Go-to-market execution should emphasize direct technical sales to medical imaging and industrial automation OEMs rather than distributor channel penetration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed semiconductor equipment distributors and legacy DDR3 module assemblers in Chengdu and Xi'an. Long-term viability hinges on exposure to localization-mandated procurement channels under MIIT integrated circuit guidelines. The signal to watch is ChangXin Memory Technologies' progress toward 1y nm node qualification, which would indicate domestic foundry capability advancement capable of displacing foreign incumbent share.| Strategic Initiative | Industry Significance |
|---|---|
| 3D DRAM Architecture R&D | Vertical cell stacking bypasses EUV lithography constraints that limit planar scaling. |
| Automotive Grade Qualification | AEC-Q100 certification opens electric vehicle battery management system procurement channels. |
| Direct Foundry Procurement | ByteDance and Alibaba Cloud volume agreements displace distributor intermediaries in server builds. |
| Renewable Power Contracting | MEE dual carbon enforcement requires solar farm agreements for new Hefei fab permits. |
| CXL 2.0 Memory Pooling | Compute Express Link virtualization treats DRAM as composable resource rather than fixed capacity. |
Research Methodology
Cross-validation between primary interviews with DRAM process engineers, cloud operator procurement directors, and automotive ECU designers and secondary sources anchors the qualitative findings. Secondary validation draws from MIIT policy circulars, SAMR antitrust filings, SEC 10-K disclosures from foreign-incumbent suppliers, and hyperscaler capex guidance. Bottom-up module shipment estimates triangulate against top-down wafer capacity calculations from ChangXin Memory Technologies and SK hynix Wuxi.
Calibration against historical node transition timelines and localization policy implementation rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product generation tier, end-use vertical, and architectural approach. CAGRs were derived from supply-side capacity buildout schedules and demand-side procurement quota enforcement under MIIT guidelines. Forecast inputs incorporate EUV equipment embargo persistence assumptions and 3D DRAM R&D funding trajectory under national integrated circuit promotion policies.
Stress conditions across EUV embargo duration, polysilicon purity constraints, and automotive qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transfer restriction enforcement and domestic foundry yield ramp schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
GDDR6 Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Automotive Memory Market
Memory Chips
China Flash Memory Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Contactless Memory Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Mobile DRAM Market
Memory Chips
Memory IC Market
Memory Chips
Japan DRAM Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Static Random-Access Memory (SRAM) Market