
 Next Generation Non Volatile Memory Market | 2026-2036
Next Generation Non Volatile Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Non Volatile Memory Market Outlook
A capital-intensity divergence between foundry-scale producers and fabless designers is rotating competitive advantage toward vertically integrated manufacturers. Samsung Electronics leverages captive wafer capacity to anchor pricing power in 3D NAND layers. SK Hynix sustains aggressive R&D intensity in MRAM cell architectures. Micron Technology competes through specialized DRAM-to-NVM process transitions at its Idaho and Singapore facilities.
Next generation non volatile memory encompasses storage technologies that retain data without continuous power, including MRAM devices built on magnetic tunnel junctions with sub-20nm cell sizes and PCM cells utilizing chalcogenide glass phase transitions above 600°C crystallization thresholds. These technologies serve industrial and commercial purposes where instant-on computing, zero-standby-power retention, and endurance beyond 10^15 write cycles prove critical. Flash memory occupies the dominant revenue position across consumer electronics and data center applications, while MRAM segments capture expanding margin pools in automotive ECUs and aerospace systems where radiation tolerance matters. ReRAM and PCM categories lead technology roadmaps for neuromorphic computing architectures, though manufacturing yields remain structurally below NAND flash maturation curves.
REACH restrictions on gallium and germanium compounds constrain PCM feedstock availability across European supply chains, while EPA hazardous substance rules govern etching chemistry disposal at US fabrication sites. South Korea's K-Battery and K-Semiconductor acts channel state subsidies toward domestic NVM capacity expansion, reshaping regional competitive access. China's MIIT mandates domestic GB standards for data retention specifications in government procurement tenders. Stakeholders must monitor how export control classifications on deposition equipment redirect capacity buildout timelines and alter foundry partnership structures.
Market Dynamics
Enterprise storage buyers are consolidating procurement around persistent memory modules for real-time analytics workloads, compressing vendor qualification timelines and rewarding captive wafer capacity.
Growth Catalysts
- EU AI Act compliance deadlines:Memory fabs serving European data centers must certify data retention specifications under new algorithmic transparency rules, accelerating replacement cycles for legacy flash arrays.
- Automotive ECU integration:Radiation-tolerant MRAM devices are penetrating aerospace and satellite subsystems where latch-up immunity determines supplier selection.
- South Korea's K-Semiconductor Act:State subsidies for domestic NVM capacity expansion are redirecting foundry partnership structures toward Seoul-based packaging clusters.
Market Restraints
- Gallium and germanium compound scarcity:REACH restrictions on chalcogenide glass feedstocks constrain PCM manufacturing yields across European supply chains.
- Deposition equipment export controls:Classification disputes over atomic layer deposition systems delay capacity buildout timelines for second-tier foundries.
- NAND flash cost curves:Mature 3D NAND pricing continues to undercut emerging NVM technologies on a per-gigabyte basis in consumer electronics.
Strategic Opportunities
- Neuromorphic computing architectures:ReRAM and PCM categories are capturing design wins for analog in-memory computation where synaptic plasticity emulation matters.
- India's PLI scheme for semiconductors:Domestic assembly and test incentives are attracting NVM module packaging investments away from traditional ASEAN hubs.
- Chalcogenide-free PCM formulations:Oxide-based phase change materials bypass REACH restrictions while maintaining crystallization thresholds above 500°C.
Industry Challenges
- Atomic layer deposition technician scarcity:Specialized equipment operation skills concentrate at incumbent fabs, constraining talent mobility for new market entrants.
- MIIT GB standard certification timelines:China's domestic data retention specifications add six to nine months to government procurement qualification cycles.
- Legacy DRAM-NVM process integration:Hybrid memory architectures require simultaneous optimization of volatile and non-volatile cell architectures on shared wafers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Non Volatile Memory Market |
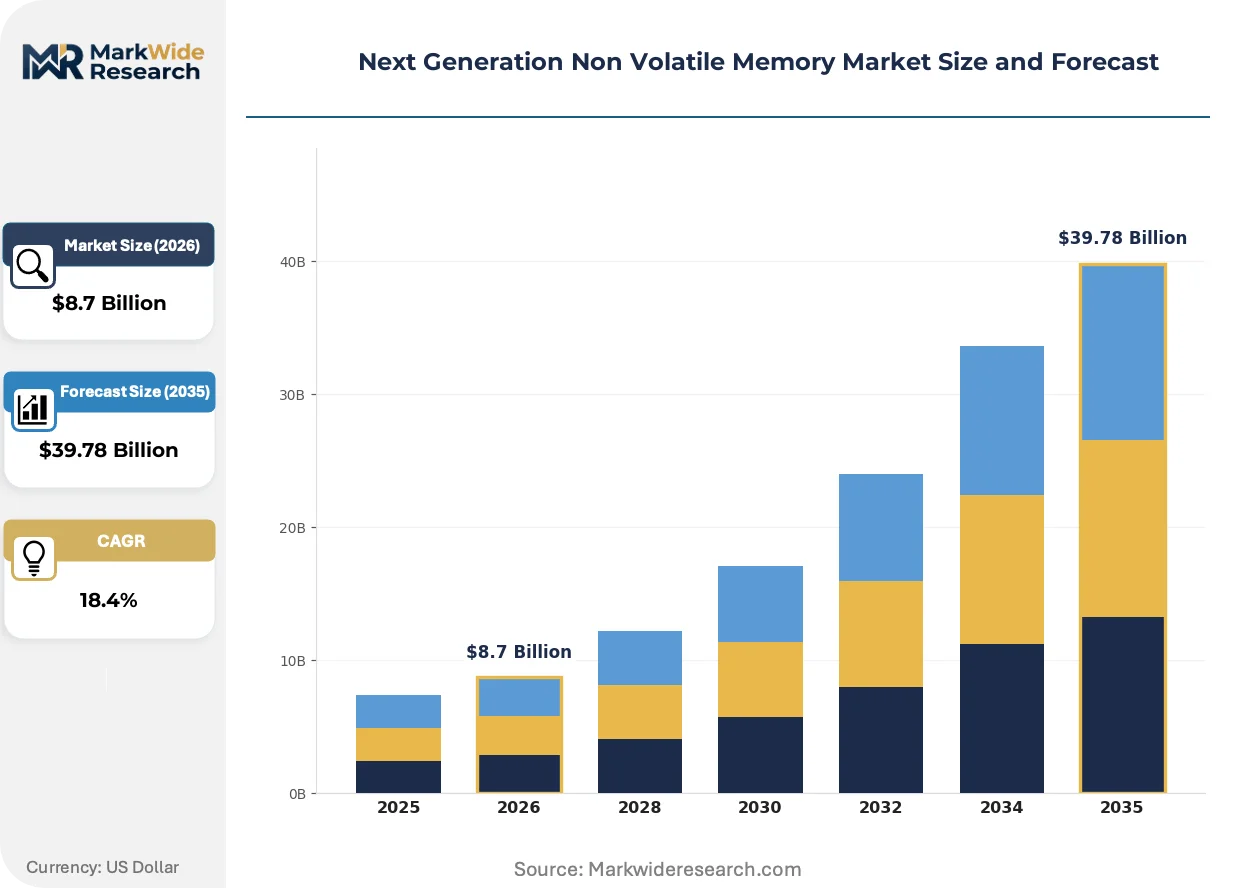
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Memory, MRAM, PCM, ReRAM Technology: 3D NAND, SONOS, Ferroelectric, Quantum Dot End User: Consumer Electronics, Enterprise Storage, Automotive, Industrial Applications Application: Data Centers, Mobile Devices, IoT, Embedded Systems |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, Intel Corporation, Western Digital Corporation, Kioxia Holdings Corporation, Fujitsu Limited, Infineon Technologies AG, Everspin Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Non Volatile Memory Market Strategic Shifts
Process node competition is fragmenting competitive advantage between vertically integrated manufacturers and specialized fabless designers, with captive wafer capacity emerging as the decisive differentiator.
Magnetic tunnel junction MRAM is fragmenting the automotive microcontroller market as sub-20nm cell sizes enable embedded non-volatile storage directly on processor dies. Tier-1 suppliers in Germany and Japan are qualifying these devices for powertrain controllers where write endurance beyond 10^15 cycles eliminates EEPROM wear-leveling overhead. The structural consequence is compression of standalone NOR flash socket opportunities in safety-critical ECUs.
EPA hazardous substance rules governing etching chemistry disposal are elevating capital requirements for US fabrication site expansions. Idaho and Arizona facilities face extended permitting timelines for perfluorinated compound treatment systems. Memory producers are responding by concentrating wet chemistry processes at Singapore sites where wastewater handling infrastructure carries lower regulatory compliance burdens.
Buyer concentration among hyperscale cloud operators is compressing supplier negotiation cycles from annual to quarterly frameworks. Amazon Web Services, Microsoft Azure, and Google Cloud Platform now dictate custom endurance specifications for data center SSDs, displacing JEDEC standard profiles. This pattern is most visible in US and Irish facility procurement where real-time analytics workloads demand persistent memory pools with sub-microsecond latency guarantees.
Next Generation Non Volatile Memory Market Segmentation
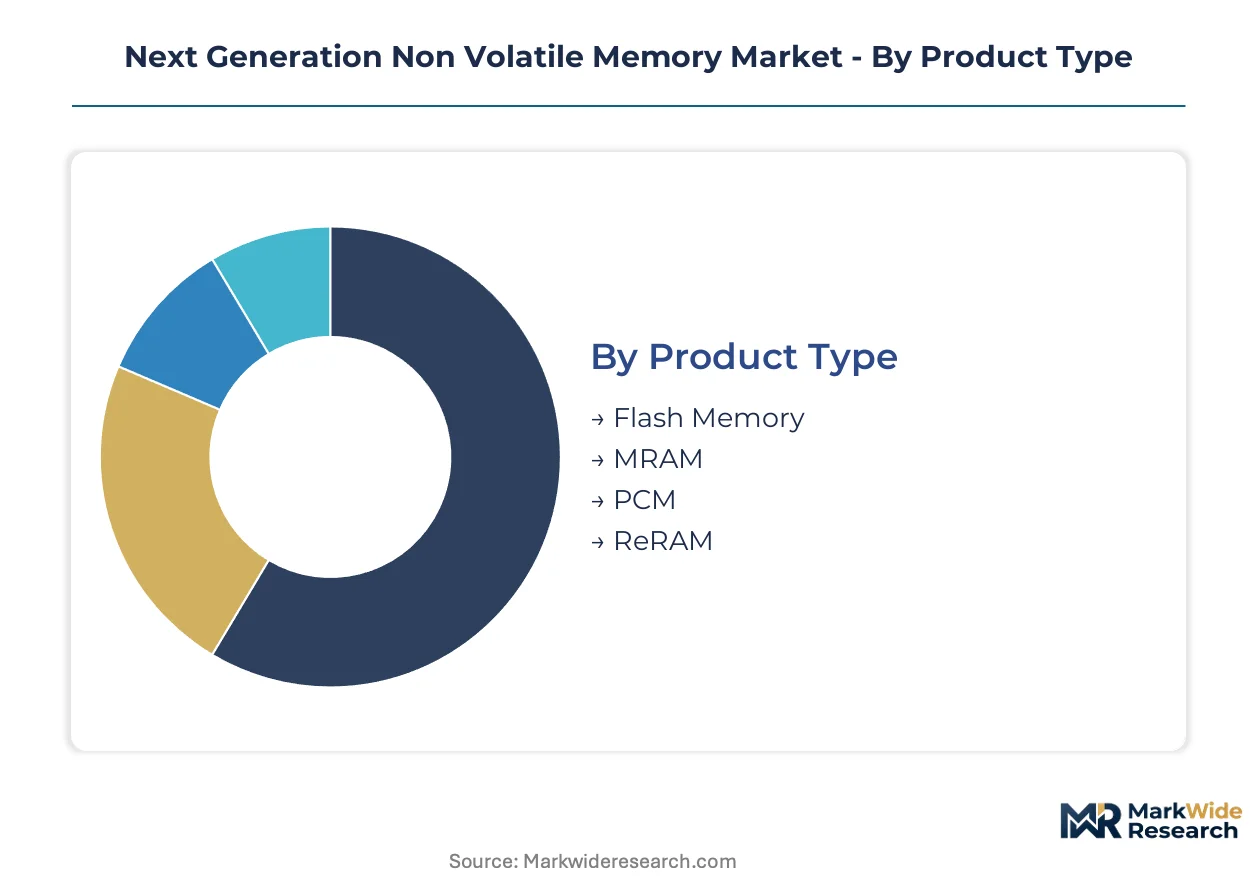
Next generation non volatile memory technologies occupy distinct performance-cost positions that determine procurement patterns across regulatory jurisdictions. Material composition restrictions and endurance specifications fragment supplier qualification pathways, creating segment-specific competitive moats.
Product Type:
REACH and EPA hazardous substance rules differentiate manufacturing feasibility across memory cell chemistries, concentrating investment in compliant feedstock formulations.
- Flash Memory:Charge-trap cells in 3D NAND architectures stack vertically to achieve terabit densities. Data center procurement in Ireland and Virginia compresses supplier negotiation cycles around JEDEC endurance profiles, displacing legacy planar configurations.
- MRAM:Magnetic tunnel junctions with MgO barriers enable sub-20nm cell sizes and radiation tolerance. Automotive ECU integration in Germany and Japan favors these devices for powertrain controllers where 10^15 write cycles eliminate EEPROM wear-leveling overhead.
- PCM:Chalcogenide glass phase transitions above 600°C crystallization thresholds enable neuromorphic analog computation. Gallium and germanium compound scarcity under REACH constrains European manufacturing yields.
- ReRAM:Metal-oxide filamentary switching creates synaptic plasticity emulation for edge AI inference. Oxide-based formulations bypass chalcogenide restrictions while maintaining thermal stability.
Established volume favors Flash Memory; emerging adoption favors MRAM.
Technology:
Process node maturation separates captive wafer capacity from fabless design licensing, anchoring margin capture at vertically integrated fabs.
- 3D NAND:Vertical charge-trap stacking achieves 200+ layers in mass production. Samsung Electronics and SK Hynix concentrate this capacity in South Korea's Hsinchu-to-Seoul corridor, leveraging state subsidies under the K-Semiconductor Act.
- SONOS:Silicon-oxide-nitride-oxide-silicon gate stacks provide embedded NVM for microcontroller integration. Industrial IoT sensor nodes in Taiwan and Singapore favor these devices for sub-50nm process compatibility.
- Ferroelectric:Hafnium oxide polarization switching enables ferroelectric FET logic-in-memory architectures. Atomic layer deposition technician scarcity constrains new market entrants.
- Quantum Dot:Colloidal semiconductor nanocrystals enable optoelectronic memory with wavelength-tunable properties. Research-stage commercialization concentrates at national laboratory partnerships.
Production scale concentrates in 3D NAND; steepest expansion trajectory belongs to Ferroelectric.
End User:
Procurement centralization among hyperscale operators compresses qualification timelines and customizes endurance specifications away from JEDEC standards.
- Consumer Electronics:Smartphone and tablet integration demands cost-optimized storage with instant-on retention. NAND flash cost curves undercut emerging NVM on per-gigabyte metrics.
- Enterprise Storage:Real-time analytics workloads drive persistent memory module deployment. Amazon Web Services, Microsoft Azure, and Google Cloud Platform dictate sub-microsecond latency guarantees.
- Automotive:Functional safety requirements under ISO 26262 mandate radiation-tolerant embedded storage. Tier-1 suppliers qualify MRAM for safety-critical ECUs.
- Industrial Applications:Extended temperature range and vibration tolerance specifications favor PCM in aerospace subsystems. Latch-up immunity determines supplier selection for satellite deployments.
Revenue concentration sits with Enterprise Storage; margin expansion favors Automotive.
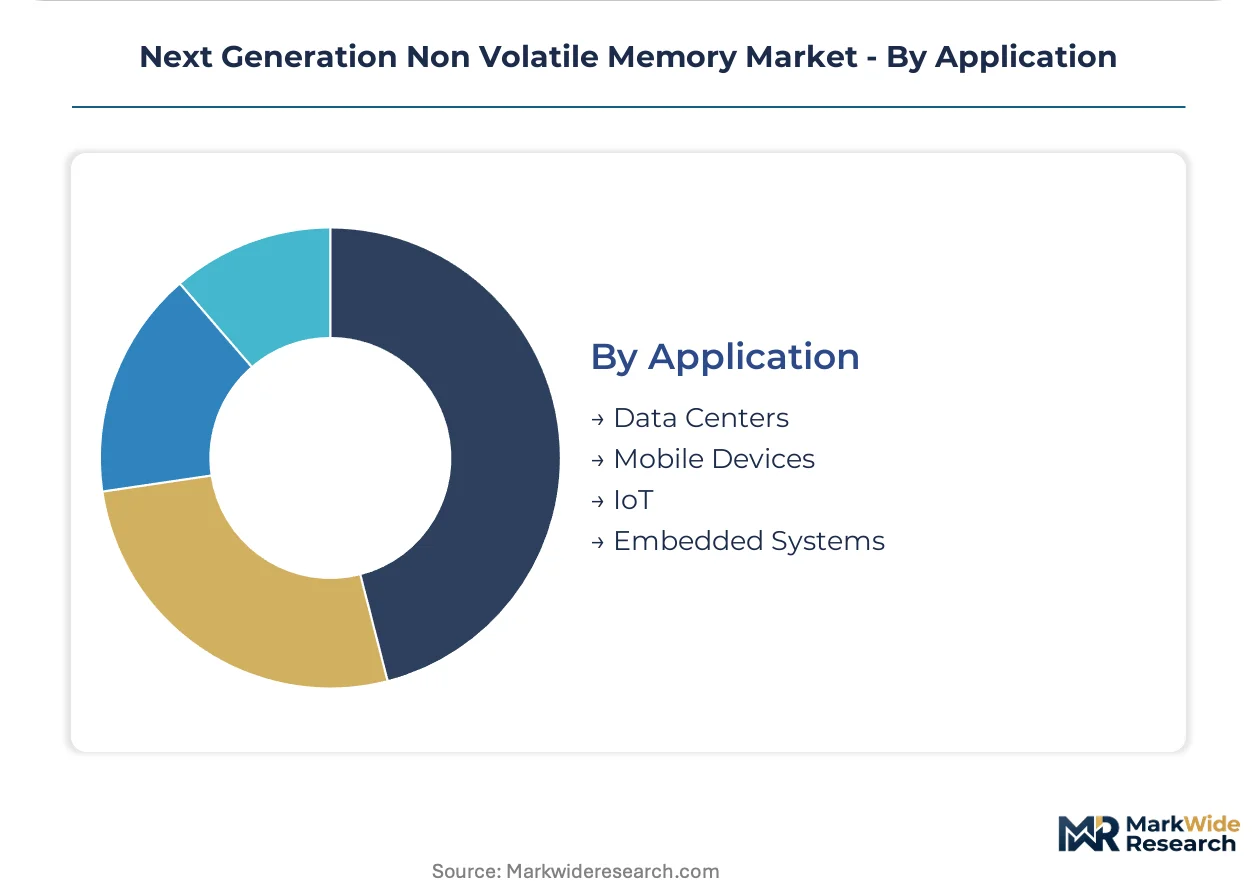
Application:
Latency requirements and power constraints fragment memory hierarchy placement across computing architectures.
- Data Centers:Persistent memory pools bridge DRAM and SSD tiers for in-memory databases. Custom endurance specifications displace standard JEDEC profiles.
- Mobile Devices:Package-on-package integration minimizes board area for smartphone storage. Power consumption constraints prioritize charge-trap flash over phase-change alternatives.
- IoT:Energy harvesting sensor nodes demand zero-standby-power retention. ReRAM and ferroelectric devices capture design wins for intermittent power environments.
- Embedded Systems:Processor-in-memory integration enables neuromorphic computing architectures. Analog in-memory computation favors PCM and ReRAM synaptic emulation.
Current procurement scale centers on Data Centers; design win momentum shifts toward Embedded Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea's captive wafer corridors while US fabrication sites absorb elevated compliance costs from EPA hazardous substance rules. This asymmetry redirects capacity expansion timelines and reshapes foundry partnership structures across the memory value chain.
United States
Hyperscale cloud operators in Virginia and Ireland compress supplier negotiation cycles around custom endurance specifications for data center SSDs. EPA hazardous substance rules governing perfluorinated compound treatment systems extend permitting timelines at Idaho and Arizona fabrication sites. Memory producers concentrate wet chemistry processes at Singapore facilities to bypass these compliance burdens.
South Korea
State subsidies under the K-Semiconductor Act channel investment toward domestic NVM capacity expansion along the Hsinchu-to-Seoul corridor. K-Battery and K-Semiconductor acts reshape regional competitive access by prioritizing Seoul-based packaging clusters. Samsung Electronics and SK Hynix leverage this support to anchor 3D NAND layer production and MRAM cell architecture development.
China
MIIT mandates domestic GB standards for data retention specifications in government procurement tenders, adding six to nine months to qualification cycles. Dual carbon goals under MEE oversight constrain energy-intensive deposition processes at domestic fabs. Yangtze River Delta and Beijing-Tianjin-Hebei clusters concentrate state-backed memory research despite export control complications on atomic layer deposition equipment.
Germany
EU AI Act compliance deadlines force memory fabs serving European data centers to certify algorithmic transparency rules, accelerating replacement cycles for legacy flash arrays. REACH restrictions on gallium and germanium compounds constrain PCM feedstock availability across continental supply chains. Automotive Tier-1 suppliers in Bavaria and Baden-Württemberg qualify radiation-tolerant MRAM for powertrain controllers under ISO 26262 functional safety requirements.
Japan
METI industrial policy supports ferroelectric memory research for logic-in-memory architectures at national laboratory partnerships. JIS standards govern embedded NVM integration for industrial IoT sensor nodes in Kansai and Chubu manufacturing belts. Fujitsu and Kioxia occupy positions within the vertically integrated and specialized memory tiers respectively.
Next Generation Non Volatile Memory Market Competitive Environment
Concentration sits with vertically integrated manufacturers possessing captive wafer capacity. The vendor base separates into three strategic tiers: Korean conglomerates controlling 3D NAND layer maturation, US-based specialists managing DRAM-to-NVM process transitions, and Japanese-German precision players serving automotive qualification pathways. Dominant competitive moves include state-subsidized capacity buildouts and deposition equipment partnership restructuring.
Among Korean-based fabricators, Samsung Electronics and SK Hynix exemplify the captive-capacity archetype through their dominance of vertical charge-trap stacking and magnetic tunnel junction development. Micron Technology occupies a position within the US specialist tier, managing process transitions across Idaho and Singapore facilities. These three entities represent the pricing-power core that compresses margin capture for fabless designers and second-tier foundries.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| Intel Corporation |
| Western Digital Corporation |
| Kioxia Holdings Corporation |
| Fujitsu Limited |
| Infineon Technologies AG |
| Everspin Technologies |
| Others |
Value Chain & Pricing Dynamics
Chalcogenide-free PCM formulations replacing gallium-germanium compounds simultaneously relocate manufacturing capacity toward oxide-feedstock corridors in East Asia and compress pricing premiums for REACH-compliant memory modules serving European automotive buyers. This substitution dynamic fragments procurement geography while rewarding suppliers with pre-positioned oxide-based material streams.
Pricing Analysis
Customization-premium spreads separate hyperscale-configured persistent memory modules from standard JEDEC-profile SSDs. Three-tier pricing structure across premium, standard, and economy levels reflects endurance specification tiers, with sub-microsecond latency guarantees commanding substantial uplifts over commodity flash. Pricing pressure stems from mature 3D NAND cost curves undercutting emerging NVM on per-gigabyte metrics in consumer electronics. Enterprise storage buyers exhibit lowest price sensitivity due to workload-specific performance requirements, while smartphone OEMs drive aggressive cost compression.
Supply Chain Analysis
Inbound logistics costs for atomic layer deposition equipment face extended timelines through port congestion at Busan and Kaohsiung, with container availability constraints on Asia-Pacific trade lanes stretching delivery schedules for second-tier foundries. Supply concentrates in South Korea, Taiwan, and Singapore, with wafer fabrication drawing from high-purity silicon ingots, sputtering targets, and specialty gases. Single-source vulnerability sits with EUV lithography systems. Distribution runs through Seoul-based packaging clusters and Singapore wet-chemistry hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as hyperscale procurement centralization creates tiered supplier ecosystems, with niche endurance specifications opening margin pools for specialized NVM architects outside the Korean captive-capacity core.
For Market Incumbents: Consolidate backward integration into sputtering target production to secure MgO barrier supply for magnetic tunnel junction scaling. Add captive wafer capacity in Singapore to bypass EPA hazardous substance permitting delays. Lock in atomic layer deposition technician pipelines through university partnerships before scarcity intensifies.
For New Entrants and Emerging Players: Lead with chalcogenide-free PCM formulations targeting REACH-constrained European automotive Tier-1s. Penetrate India's PLI-subsidized assembly and test corridors for module packaging cost advantages. Pursue neuromorphic computing design wins through analog in-memory computation partnerships with edge AI chip architects.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless designers holding MRAM cell architecture IP but lacking captive wafer capacity. Long-term viability centers on deposition equipment access and foundry partnership restructuring under export control classifications. Watch atomic layer deposition equipment reclassification disputes as inflection signals for capacity buildout feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Chalcogenide-Free Material Transition | Oxide-based PCM formulations bypass REACH restrictions while maintaining thermal stability thresholds above 500°C. |
| Captive Wafer Capacity Expansion | Singapore site concentration leverages lower regulatory compliance burdens for wet chemistry processes. |
| Neuromorphic Architecture Partnership | ReRAM and PCM categories capture design wins for synaptic plasticity emulation in edge AI inference. |
| Deposition Equipment Partnership Restructuring | Export control classifications redirect foundry relationships toward Seoul-based packaging clusters. |
| Atomic Layer Deposition Technician Pipeline | Specialized equipment operation skills concentrate at incumbent fabs, constraining talent mobility. |
Study Parameters
Cross-validation between primary interviews with memory fab process engineers, hyperscale cloud procurement directors, and automotive Tier-1 supplier quality managers anchors the qualitative findings against secondary validation from SEC filings, ECHA REACH substance databases, and MIIT GB standard certification records. Bottom-up and top-down triangulation reconciles wafer capacity announcements with module shipment customs data.
Sensitivity analysis across technology node maturation curves, deposition equipment lead time scenarios, and regulatory compliance cost trajectories shapes the analytical framework. Segmentation dimensions span memory cell chemistry, process architecture, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and emerging application penetration curves, with hyperscale capex disclosures and automotive ECU qualification timelines serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained state subsidy flows, stable export control classifications, and current REACH substance restrictions would require recalibration. Forecasts reflect assumptions on atomic layer deposition equipment availability, chalcogenide feedstock substitution rates, and hyperscale endurance specification standardization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
DDR RAM Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Digital RF Memory Market
Memory Chips
Nano RAM Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
China Flash Memory Market
Memory Chips
Memristor Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
Japan Flash Memory Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
MRAM Market