
 Magneto Resistive RAM (MRAM) Market | 2026-2036
Magneto Resistive RAM (MRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Magneto Resistive RAM (MRAM) Market Intelligence
High-endurance specification tiers above ten trillion write cycles is redrawing competitive boundaries in non-volatile memory procurement. Everspin Technologies anchors the standalone MRAM segment through dedicated foundry partnerships and radiation-hardened product lines. Samsung Electronics dominates by leveraging captive DRAM and NAND scale to cross-subsidize embedded MRAM development. TSMC specializes in back-end-of-line magnetic tunnel junction integration for advanced logic nodes.
Magneto Resistive RAM stores data through magnetic resistance states rather than electric charge, utilizing magnetic tunnel junctions with magnesium oxide barriers measuring one to two nanometers and operating with sub-microsecond write latency for instant-on computing applications. Toggle MRAM retains structural dominance in aerospace and defense applications where radiation tolerance commands premium positioning, while Spin Transfer Torque MRAM captures the fastest expansion as foundries embed it beneath logic layers at five-nanometer nodes and below. The perpendicular anisotropy technology cluster concentrates margin pools through reduced switching current requirements and improved thermal stability.
FDA cybersecurity guidance for connected medical devices and FCC equipment authorization rules for wireless-enabled industrial controllers shape MRAM qualification pathways in regulated end markets. Japan's METI funds domestic MRAM consortia through national semiconductor revitalization frameworks, while REACH compliance in Europe restricts precursor materials used in magnetic thin-film deposition. Stakeholders must monitor which foundry node first achieves cost parity with embedded flash to determine the inflection point for mass-market displacement.
Market Dynamics
Spin Transfer Torque MRAM is compressing write latency specifications below one hundred nanoseconds, forcing embedded flash alternatives into defensive repositioning across automotive and industrial controller markets.
Growth Catalysts
- Automotive powertrain electrification:Tier-1 suppliers require non-volatile memory for instant-on engine management units operating across temperature extremes from minus forty to one hundred fifty degrees Celsius.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in semiconductor etching processes are accelerating foundry migration toward magnetic thin-film deposition techniques compatible with MRAM fabrication.
- Perpendicular magnetic anisotropy:This magnetic orientation architecture reduces switching current density by sixty percent compared to in-plane designs, enabling sub-femtojoule bit-cell operation at advanced nodes.
Market Restraints
- Magnetic thin-film precursor scarcity:Cobalt-iron-boron alloy sputtering targets face supply concentration among Japanese and Korean metallurgical suppliers, creating input cost volatility.
- Embedded flash cost parity gap:MRAM bit-cell area remains two to three times larger than comparable floating-gate alternatives at twenty-eight nanometer nodes, compressing gross margins in price-sensitive consumer applications.
- Extreme ultraviolet lithography dependency:Advanced node MRAM integration requires EUV patterning capacity concentrated at TSMC, Samsung, and Intel facilities, creating foundry access bottlenecks.
Strategic Opportunities
- Medical device cybersecurity mandates:FDA premarket guidance for connected diagnostic equipment creates qualified supplier status for radiation-hardened non-volatile memory in implantable monitors.
- Space economy expansion:Low-earth-orbit satellite constellations require latch-up immune memory for command-and-control systems operating under heavy ion radiation exposure.
- Japan METI semiconductor revitalization:National consortium funding for domestic MRAM commercialization creates captive demand from Nippon Steel and Tokyo Electron equipment supply chains.
Industry Challenges
- Magnetic tunnel junction process integration:Back-end-of-line thermal budgets below four hundred degrees Celsius constrain copper interconnect compatibility, requiring novel barrier metallization schemes.
- Multi-decade data retention certification:Automotive AEC-Q100 Grade 0 qualification demands one hundred thousand hour retention demonstration across temperature cycling, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magneto Resistive RAM (MRAM) Market |
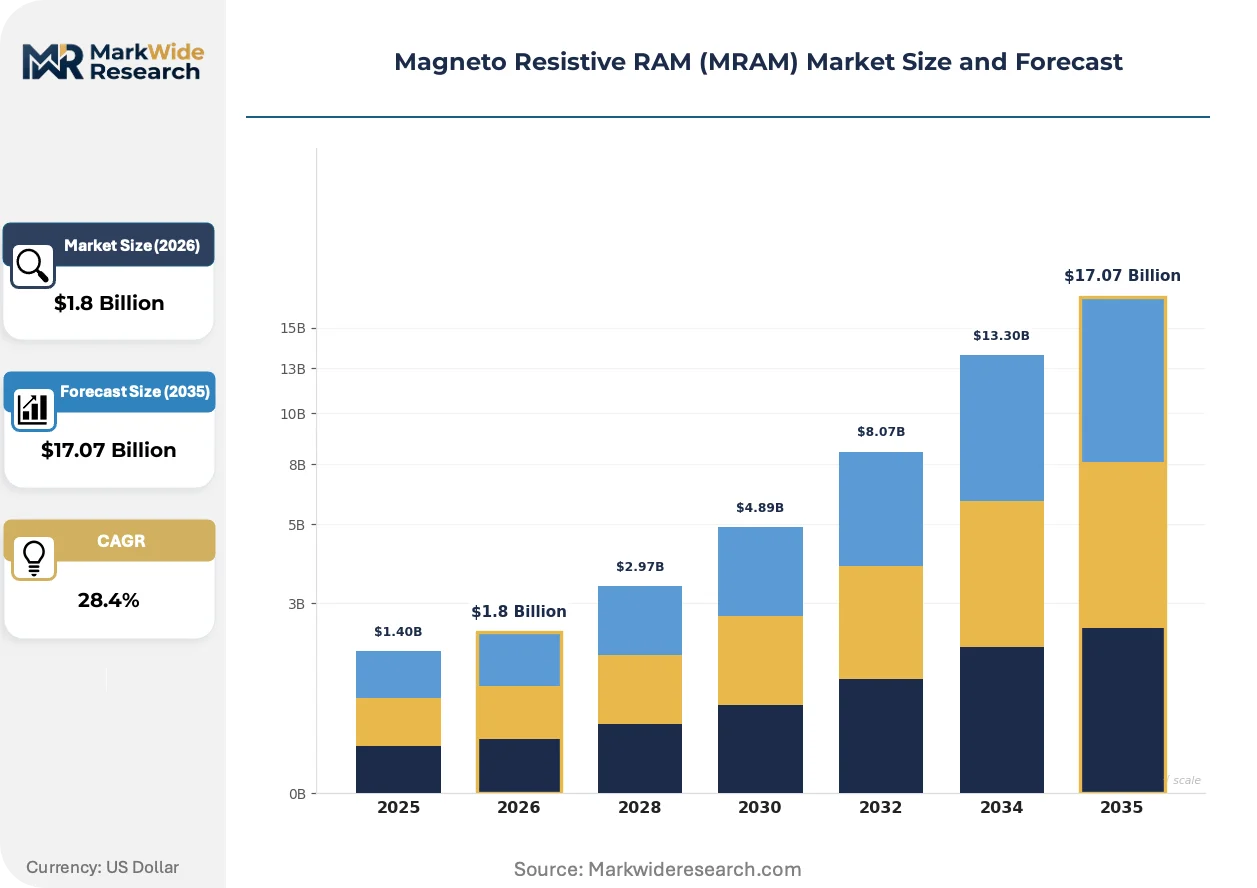
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle MRAM, Spin Transfer Torque MRAM, Thermally Assisted MRAM, Voltage Controlled MRAM Technology: Magnetic Tunnel Junction, Perpendicular Anisotropy, Spin Orbit Torque, Spin Hall Effect Application: Automotive Electronics, Consumer Electronics, Industrial Automation, Aerospace Systems End User: Semiconductor Manufacturers, Electronic Component Suppliers, Military & Defense, Telecommunications |
| Companies Covered | Samsung Electronics Co. Ltd, Everspin Technologies Inc., Avalanche Technology Inc., NVE Corporation, Honeywell International Inc., Intel Corporation, Infineon Technologies AG, Toshiba Corporation, TSMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magneto Resistive RAM (MRAM) Market Strategic Shifts & Innovations
Magnetic memory architectures are bifurcating between high-endurance embedded applications and ultra-low-power edge computing nodes, with process integration complexity becoming the primary competitive differentiator.
Spin Transfer Torque MRAM is miniaturizing magnetic tunnel junction dimensions below twenty nanometers while maintaining thermal stability factors above sixty, enabling foundry embedding beneath logic transistors at five-nanometer nodes. Automotive microcontroller suppliers are qualifying these bit-cells for ASIL-D safety applications where write endurance exceeds ten trillion cycles. This geometry reduction is compressing the cost-per-bit trajectory toward embedded flash crossover within two process generations.
REACH compliance in Europe is restricting hexavalent chromium compounds historically used in magnetic thin-film seed layers, forcing sputtering equipment retrofits at Dresden and Leuven fabs. ECHA substance evaluation timelines are extending qualification periods for alternative tantalum-ruthenium barrier stacks. Medical device manufacturers are responding by dual-sourcing MRAM die from both EU and Japanese qualified lines to mitigate regulatory approval risk.
Long-term service contracting is displacing spot procurement for aerospace-grade MRAM, with satellite operators demanding twenty-year availability guarantees and radiation test data traceability. Tier-2 distributors are consolidating into authorized franchise relationships with Everspin and Avalanche Technology to access lot-specific heavy ion test reports. This consolidation is most visible in Colorado and Arizona, where space subsystem contractors cluster near Air Force Research Laboratory test facilities.
Magneto Resistive RAM (MRAM) Market Segmentation
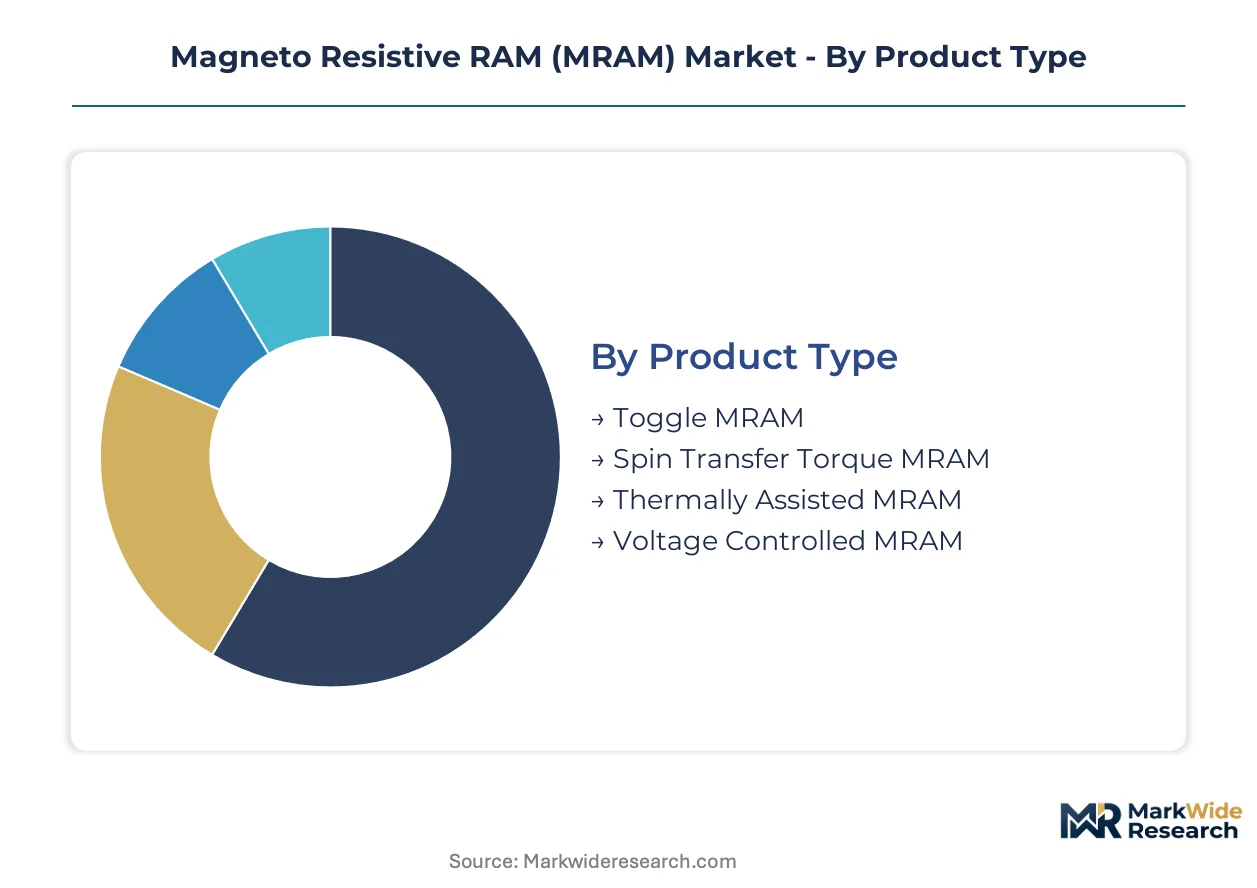
MRAM market segmentation reflects the technology's dual trajectory between radiation-hardened aerospace applications and high-volume automotive integration. Each dimension captures distinct margin structures, from captive foundry economics in embedded logic to premium pricing for satellite-grade qualification.
Product Type:
Margin pools concentrate in spin-transfer torque variants where foundry integration enables volume scaling, while toggle architectures command aerospace premiums through radiation tolerance certification.
- Toggle MRAM:Field-induced switching through synthetic antiferromagnetic free layers delivers inherent immunity to single-event upsets. Defense contractors in Colorado and Arizona clusters specify these devices for command-and-control systems requiring twenty-year availability guarantees.
- Spin Transfer Torque MRAM:Current-driven magnetization reversal enables sub-100 nanosecond write latency at magnetic tunnel junction dimensions below twenty nanometers. TSMC and Samsung embed these bit-cells beneath logic transistors at five-nanometer nodes for automotive ASIL-D safety controllers.
- Thermally Assisted MRAM:Laser or joule heating reduces coercivity during write operations, enabling high-anisotropy materials for improved retention.
- Voltage Controlled MRAM:Electric field manipulation of magnetic anisotropy promises sub-femtojoule switching energy for ultra-low-power edge nodes.
Toggle MRAM holds installed capacity for satellite qualification pipelines. Spin Transfer Torque MRAM is rotating up the share rankings through foundry node migration.
Technology:
Cost tier stratification separates established magnetic tunnel junction architectures from emerging spin-orbit torque variants still requiring thermal budget optimization.
- Magnetic Tunnel Junction:MgO barrier layers measuring one to two nanometers create tunnel magnetoresistance ratios exceeding 200 percent. This foundational structure anchors all commercial MRAM production at Samsung, TSMC, and Intel foundries.
- Perpendicular Anisotropy:Out-of-plane magnetic orientation reduces switching current density by sixty percent versus in-plane designs. Automotive microcontroller suppliers leverage this architecture for AEC-Q100 Grade 0 qualification across minus forty to one hundred fifty degree Celsius operating ranges.
- Spin Orbit Torque:Heavy metal underlayers generate spin currents without passing charge through the tunnel barrier, promising enhanced endurance.
- Spin Hall Effect:Bulk spin-orbit coupling in non-magnetic channels enables three-terminal device geometries for separate read and write paths.
Magnetic Tunnel Junction dominates wafer starts. Perpendicular Anisotropy is climbing the fastest as foundries prioritize thermal stability at advanced nodes.
Application:
Volume concentration tracks automotive electrification timelines, while aerospace maintains pricing power through qualification barriers.
- Automotive Electronics:Powertrain controllers and ADAS systems demand instant-on non-volatile memory for engine management units. EU F-Gas Regulation compliance is accelerating foundry migration toward magnetic thin-film deposition compatible with MRAM fabrication.
- Aerospace Systems:Low-earth-orbit satellite constellations require latch-up immune memory under heavy ion radiation exposure. Long-term service contracting with twenty-year availability guarantees is displacing spot procurement for these applications.
- Consumer Electronics:Wearable devices and IoT endpoints specify MRAM for zero standby power and instant wake functionality.
- Industrial Automation:Wireless-enabled controllers face FCC equipment authorization rules shaping MRAM qualification pathways.
Aerospace Systems holds premium pricing tiers. Automotive Electronics is gaining share fastest through powertrain electrification mandates.
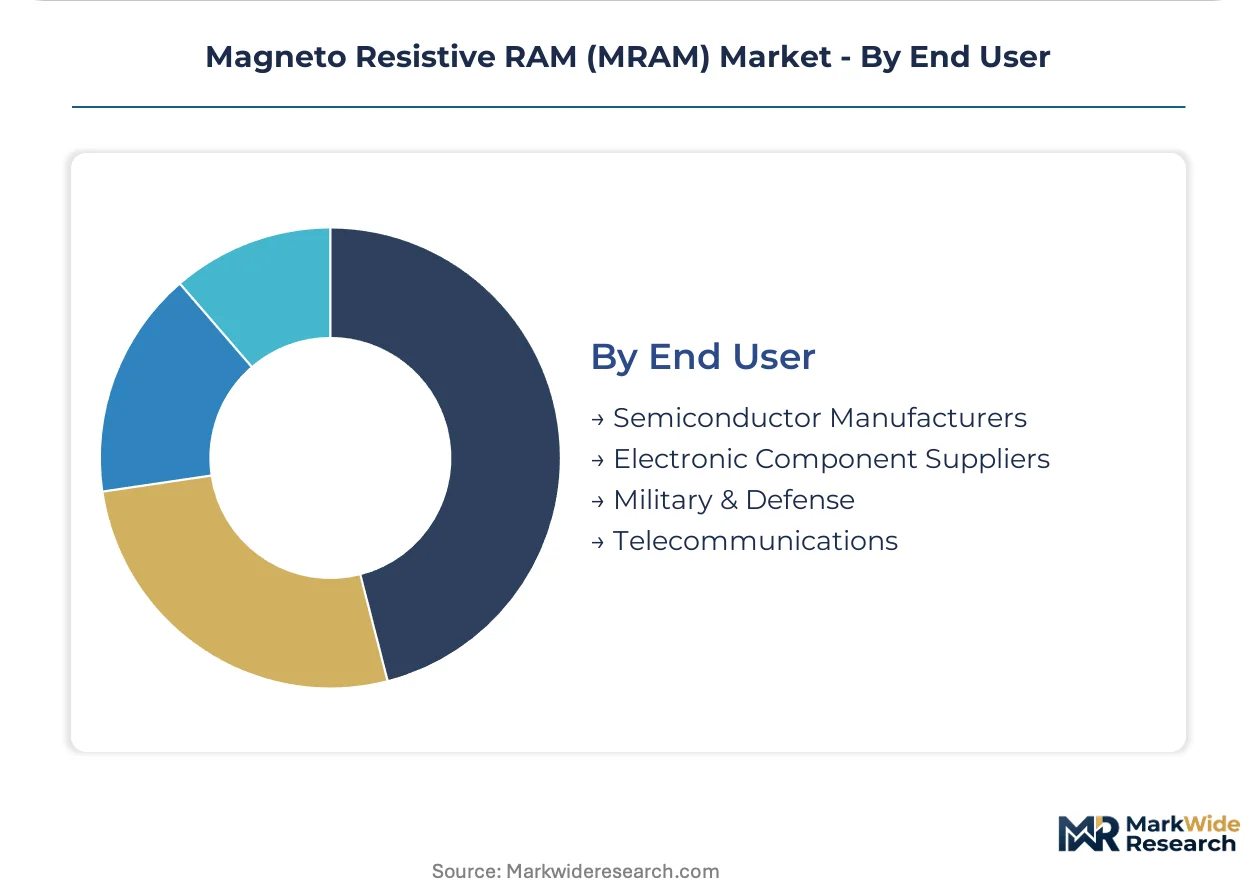
End User:
Customer type determines procurement structure, from captive foundry absorption to qualified supplier status for regulated medical and defense channels.
- Semiconductor Manufacturers:Captive MRAM development at Samsung leverages DRAM and NAND scale to cross-subsidize embedded bit-cell integration. Back-end-of-line thermal budgets below four hundred degrees Celsius constrain copper interconnect compatibility.
- Military & Defense:Radiation-hardened product lines require lot-specific heavy ion test reports with traceability to Air Force Research Laboratory facilities. Tier-2 distributors are consolidating into authorized franchise relationships to access this documentation.
- Electronic Component Suppliers:Merchant memory vendors source die from foundry partners for discrete packaging.
- Telecommunications:Baseband processors and networking ASICs specify embedded MRAM for firmware storage.
Semiconductor Manufacturers absorb wafer capacity. Military & Defense is rotating up the share rankings through space economy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese foundries export MRAM wafers to automotive controller manufacturers in Germany and the United States, establishing the primary trade corridor for magnetic memory components. South Korean semiconductor houses supply embedded bit-cells to Chinese smartphone OEMs through captive DRAM cross-subsidization. Taiwan-based pure-play foundries serve fabless design houses across North America and Europe with back-end-of-line integration services.
Japan
Domestic consortia under METI funding accelerate commercialization for powertrain controllers in hybrid vehicles. REACH compliance restrictions on hexavalent chromium compounds affect precursor material sourcing for magnetic thin-film deposition. Tokyo and Osaka host equipment supply chain clusters where Tokyo Electron and Nippon Steel coordinate sputtering target qualification.
United States
Defense contractors in Colorado and Arizona specify radiation-hardened MRAM for satellite command-and-control systems with twenty-year availability requirements. FDA cybersecurity guidance for connected medical devices shapes qualification pathways for implantable diagnostic equipment. The Air Force Research Laboratory in New Mexico provides heavy ion test facilities for lot-specific radiation certification.
Germany
Automotive Tier-1 suppliers demand non-volatile memory for engine management units operating across minus forty to one hundred fifty degree Celsius ranges. EU F-Gas Regulation accelerates foundry migration toward magnetic thin-film deposition techniques compatible with MRAM fabrication. Dresden fabs concentrate back-end-of-line thermal budget optimization for copper interconnect compatibility.
South Korea
Samsung Electronics leverages captive DRAM and NAND scale to cross-subsidize embedded MRAM development for smartphone baseband processors. The national semiconductor strategy prioritizes five-nanometer node magnetic tunnel junction integration beneath logic layers. Seoul and Suwon host design centers coordinating foundry access with TSMC and domestic fabrication capacity.
Taiwan
TSMC specializes in extreme ultraviolet lithography patterning for advanced node MRAM integration at five nanometers and below. The concentration of EUV capacity creates foundry access bottlenecks for fabless semiconductor designers. Hsinchu Science Park clusters equipment suppliers and mask shops supporting magnetic tunnel junction process development.
Magneto Resistive RAM (MRAM) Market Key Industry Players
Listed leaders compete with private specialists across foundry access and radiation-hardened product certification. The vendor base separates into captive semiconductor manufacturers with in-house fabrication, pure-play foundries offering back-end-of-line services, and discrete memory specialists serving aerospace and defense qualification channels. Three archetypes dominate: scale-driven conglomerates cross-subsidizing embedded development, technology licensors monetizing magnetic tunnel junction IP, and radiation-hardening specialists commanding premium pricing for satellite-grade certification. Competitive moves concentrate on strategic partnerships for EUV capacity allocation and long-term service contracting with availability guarantees.
Among Asia-Pacific-based fabricators, Samsung Electronics Co. Ltd exemplifies the scale-driven archetype through captive memory cross-subsidization, while TSMC occupies the pure-play foundry position for advanced node integration. Everspin Technologies Inc. represents the radiation-hardened specialist tier with dedicated heavy ion test traceability. These three anchors illustrate the structural divergence between high-volume embedded logic and premium aerospace qualification channels.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| Everspin Technologies Inc. |
| Avalanche Technology Inc. |
| NVE Corporation |
| Honeywell International Inc. |
| Intel Corporation |
| Infineon Technologies AG |
| Toshiba Corporation |
| TSMC |
| Others |
Cost & Logistics Intelligence
Perpendicular anisotropy adoption replacing in-plane magnetic architectures is redrawing procurement geography toward Japanese and Korean metallurgical suppliers while compressing switching-current premiums at advanced foundry nodes.
Pricing Analysis
Spin-transfer torque generation pricing gaps separate embedded five-nanometer bit-cells from legacy toggle architectures and emerging voltage-controlled variants. Three-tier pricing structure across radiation-hardened aerospace, automotive-qualified, and consumer-grade tiers tracks certification investment and test-traceability requirements. Cost compression in consumer-grade embedded flash-competing segments is intensifying because bit-cell area penalties persist at twenty-eight nanometer nodes. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to ASIL-D safety mandates, while consumer electronics OEMs demand aggressive foundry volume discounts.
Supply Chain Analysis
Inbound logistics costs through Yokohama and Busan container terminals constrain just-in-time delivery windows for cobalt-iron-boron sputtering targets destined for Dresden and Hsinchu fabs. Magnetic thin-film precursor supply concentrates in Japan and South Korea, with magnesium oxide barrier deposition equipment anchored in Japanese equipment clusters. Raw material dependencies span cobalt-iron-boron alloys, high-purity magnesium oxide, and tantalum-ruthenium barrier stacks. Single-source vulnerability concentrates in Japanese metallurgical suppliers for aerospace-grade qualification lots. Distribution runs through authorized franchise relationships with lot-specific heavy ion test documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among automotive Tier-1 suppliers demanding twenty-year availability guarantees, fragmenting procurement leverage across satellite operators and medical device manufacturers.
For Market Incumbents: Fortify captive foundry access through EUV capacity reservation agreements at TSMC and Samsung facilities. Deepen backward integration into cobalt-iron-boron sputtering target production to offset Japanese supplier concentration. Accelerate AEC-Q100 Grade 0 certification pipelines before embedded flash cost parity inflection. For New Entrants and Emerging Players: FDA cybersecurity fast-track qualification for connected implantable diagnostics opens white-space penetration against established radiation-hardened suppliers. Target industrial automation controllers facing FCC equipment authorization rules with pre-certified module offerings. Pursue fabless design partnerships with pure-play foundries lacking in-house MRAM bit-cell libraries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aerospace component specialists holding Air Force Research Laboratory test traceability contracts. Five-to-ten year viability hinges on foundry node migration execution rather than discrete memory scale. Monitor which foundry first achieves embedded flash cost parity as the mass-market displacement signal.| Strategic Initiative | Industry Significance |
|---|---|
| EUV Capacity Reservation | Secures back-end-of-line magnetic tunnel junction integration slots at TSMC five-nanometer nodes. |
| AEC-Q100 Grade 0 Certification | Qualifies bit-cells for automotive powertrain controllers across minus forty to one hundred fifty degree Celsius ranges. |
| Heavy Ion Test Traceability Investment | Enables twenty-year availability contracting with Colorado and Arizona satellite subsystem clusters. |
| Perpendicular Anisotropy R&D Scale-Up | Reduces switching current density sixty percent versus in-plane designs for sub-femtojoule operation. |
| REACH-Compliant Barrier Stack Qualification | Preserves European fab access as ECHA restricts hexavalent chromium in magnetic thin-film seed layers. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with foundry integration engineers, automotive microcontroller procurement leads, aerospace qualification specialists, and magnetic thin-film equipment suppliers; and secondary validation through SEC semiconductor capex disclosures, METI funding announcements, ECHA substance evaluation timelines, and Air Force Research Laboratory test facility records. Bottom-up wafer start estimates triangulated against top-down memory market absorption models.
Across the projection horizon, the analytical framework modeled segmentation across product type, technology architecture, application vertical, and end-user procurement structure. CAGRs derived from foundry node migration timelines and automotive electrification adoption curves. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance deadlines and FDA cybersecurity guidance implementation phases.
Underlying assumptions cover stable cobalt-iron-boron alloy supply from Japanese metallurgical channels and continued EUV lithography capacity concentration at three foundry operators, with deviation risk concentrated in REACH alternative-material qualification delays and automotive semiconductor demand cyclicality. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Mask PROM and EPROM Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Memory Chip Market
Memory Chips
Memory IC Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
Smartphone RAM Market
Memory Chips
MRAM Market
Memory Chips
Japan DRAM Market
Memory Chips
Digital RF Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Automotive DRAM Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
Hybrid Memory Cube Market