
 Magnetoresistive Random Access Memory (MRAM) Market | 2026-2036
Magnetoresistive Random Access Memory (MRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetoresistive Random Access Memory (MRAM) Market Foresight
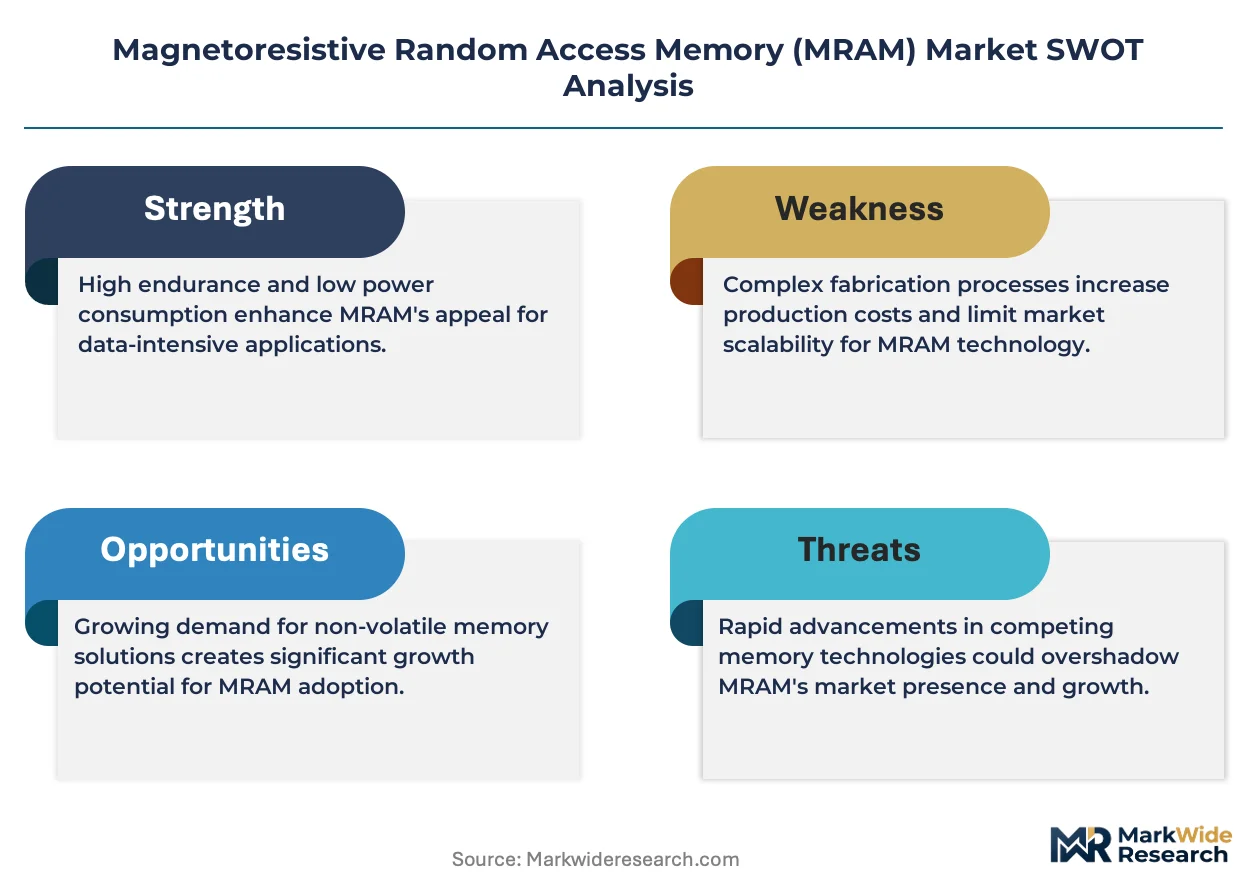
Spin-transfer torque integration is tilting the memory hierarchy toward persistent, byte-addressable architectures that displace discrete flash in space-constrained designs. Samsung Electronics Co., Ltd. leverages its foundry-scale deposition expertise to anchor embedded MRAM in advanced logic nodes. Everspin Technologies Inc. specializes in standalone MRAM for industrial and aerospace-grade reliability requirements. Infineon Technologies AG dominates automotive-qualified non-volatile memory sockets through tight coupling with microcontroller roadmaps.
Magnetoresistive Random Access Memory stores data via magnetic tunnel junction resistance states rather than electric charge, utilizing magnesium oxide barriers and cobalt-iron-boron free layers to achieve sub-nanosecond write speeds with zero standby power. Its primary purpose is to bridge the latency gap between SRAM and flash while eliminating data retention vulnerability in power-loss scenarios. Embedded MRAM leads product type adoption as foundries integrate it into 22nm and below logic processes for IoT device microcontrollers. Standalone MRAM competes in data center persistent memory tiers where write endurance requirements exceed NAND flash capabilities. Automotive end user demand concentrates in electric vehicle powertrain controllers requiring AEC-Q100 Grade 0 temperature tolerance.
FDA cybersecurity guidance for connected medical devices and EU REACH restrictions on hazardous substances in electronics shape MRAM material selection and qualification protocols. The EU Chips Act and US CHIPS and Science Act direct public capital toward domestic non-volatile memory fabrication capacity, altering foundry location decisions. NMPA device registration requirements in China create parallel certification tracks for MRAM-containing automotive and industrial systems. Stakeholders must monitor which foundry nodes achieve embedded MRAM yield maturity first, as this determines cost parity with incumbent flash-based solutions in high-volume IoT deployments.
Market Dynamics
Spin-transfer torque MRAM integration is forcing a structural reordering of the memory hierarchy, as foundries race to embed persistent storage into sub-22nm logic nodes for power-loss-resilient computing architectures.
Growth Catalysts
- EU Chips Act capital redirection:Sovereign semiconductor programs in Europe are funneling public investment toward domestic non-volatile memory foundry capacity, accelerating MRAM pilot line qualification.
- Automotive ECU specification shifts:Electric vehicle powertrain controllers now mandate embedded non-volatile memory for over-the-air firmware resilience, creating qualified socket demand.
- Taiwan cluster concentration:Hsinchu Science Park anchors global MRAM pilot production, concentrating process expertise and equipment vendor co-location for IoT and edge AI clients.
Market Restraints
- Yield maturity gaps at advanced nodes:Embedded MRAM bitcell variability remains elevated below 22nm, constraining cost parity with incumbent flash-based alternatives in high-volume deployments.
- Equipment supply concentration:Physical vapor deposition and etch tools for magnetic stack patterning concentrate among a handful of Japanese and European equipment vendors, creating capacity bottlenecks.
- REACH substance restrictions:EU hazardous substance regulations constrain cobalt and heavy metal usage in magnetic free layers, complicating material qualification for European-qualified devices.
Strategic Opportunities
- Edge AI inference acceleration:Byte-addressable persistent memory enables weight storage directly on inference accelerators, eliminating DRAM refresh overhead in battery-constrained neural network deployments.
- Space and radiation-hardened systems:Intrinsic radiation tolerance of magnetic tunnel junctions opens sockets in satellite command-and-control computers where single-event upset resilience is mandatory.
- US CHIPS Act domestic foundry incentives:Federal subsidies for non-volatile memory fabrication are altering location decisions for new MRAM capacity, creating first-mover advantages for qualified domestic producers.
Industry Challenges
- Magnetic materials process engineering talent scarcity:Deep expertise in perpendicular magnetic anisotropy stack optimization concentrates among a narrow cohort of researchers, constraining foundry yield ramp speed.
- AEC-Q100 Grade 0 qualification timelines:Automotive temperature cycling and data retention testing extends product introduction cycles by 18-24 months, compressing revenue realization windows.
- Legacy microcontroller architecture integration:Existing ARM and RISC-V core designs assume SRAM-flash memory hierarchies, requiring substantial firmware and compiler toolchain re-engineering for MRAM-native operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetoresistive Random Access Memory (MRAM) Market |
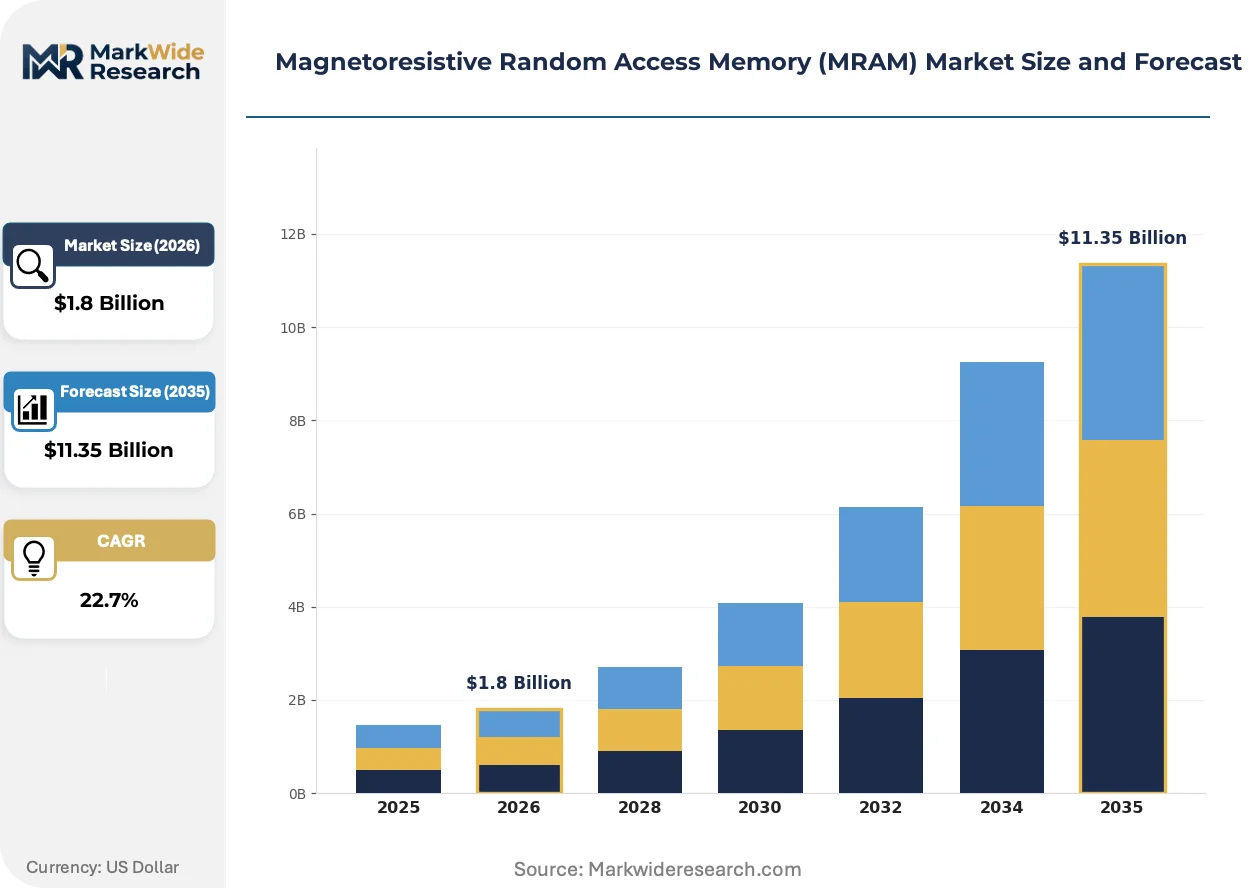
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded MRAM, Standalone MRAM, Non-Volatile MRAM, Advanced MRAM End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Integration Level: System-on-Chip, Module Level, Board Level, Chip Level Application: Data Centers, Mobile Devices, Wearables, IoT Devices |
| Companies Covered | Honeywell International Inc., Infineon Technologies AG, Intel Corporation, Samsung Electronics Co., Ltd., Everspin Technologies Inc., Avalanche Technology Inc., Taiwan Semiconductor Manufacturing Company Limited, STMicroelectronics N.V., Spin Memory Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetoresistive Random Access Memory (MRAM) Market Shifts & Advancements
Memory subsystem architectures are undergoing fundamental redesign as persistent, byte-addressable storage collapses the traditional boundary between working memory and long-term retention.
Spin-orbit torque MRAM is digitizing write path energy efficiency in edge computing devices. This technology harnesses spin-orbit coupling in heavy metal underlayers to switch magnetic free layers with substantially lower current density than spin-transfer torque architectures. IoT sensor hub designers in Taiwan and South Korea are adopting pre-production samples for always-on voice wake-word engines. The structural consequence is digitizing power budgets in energy-harvesting endpoints, enabling continuous operation from photovoltaic or thermal scavenging sources previously insufficient for flash write cycles.
EU REACH substance restrictions are tightening material selection protocols for magnetic tunnel junction fabrication. The European Chemicals Agency's candidate list expansion for cobalt compounds is forcing foundries to qualify alternative free layer alloys or implement closed-loop chemical management systems. Medical device manufacturers targeting EU markets are prioritizing MRAM suppliers with pre-validated REACH-compliant material sets, creating certification-driven supplier preference shifts in connected diagnostic equipment.
Automotive tier-one procurement patterns are consolidating non-volatile memory qualification around AEC-Q100 Grade 0-capable sources. Powertrain controller buyers are unbundling memory procurement from microcontroller bundled supply, directly engaging foundries for embedded MRAM wafers. This disintermediation is most visible in Germany's automotive supply chain, where Bosch and Continental are establishing direct foundry relationships for 28nm and 22nm embedded non-volatile memory capacity.
Magnetoresistive Random Access Memory (MRAM) Market Segmentation
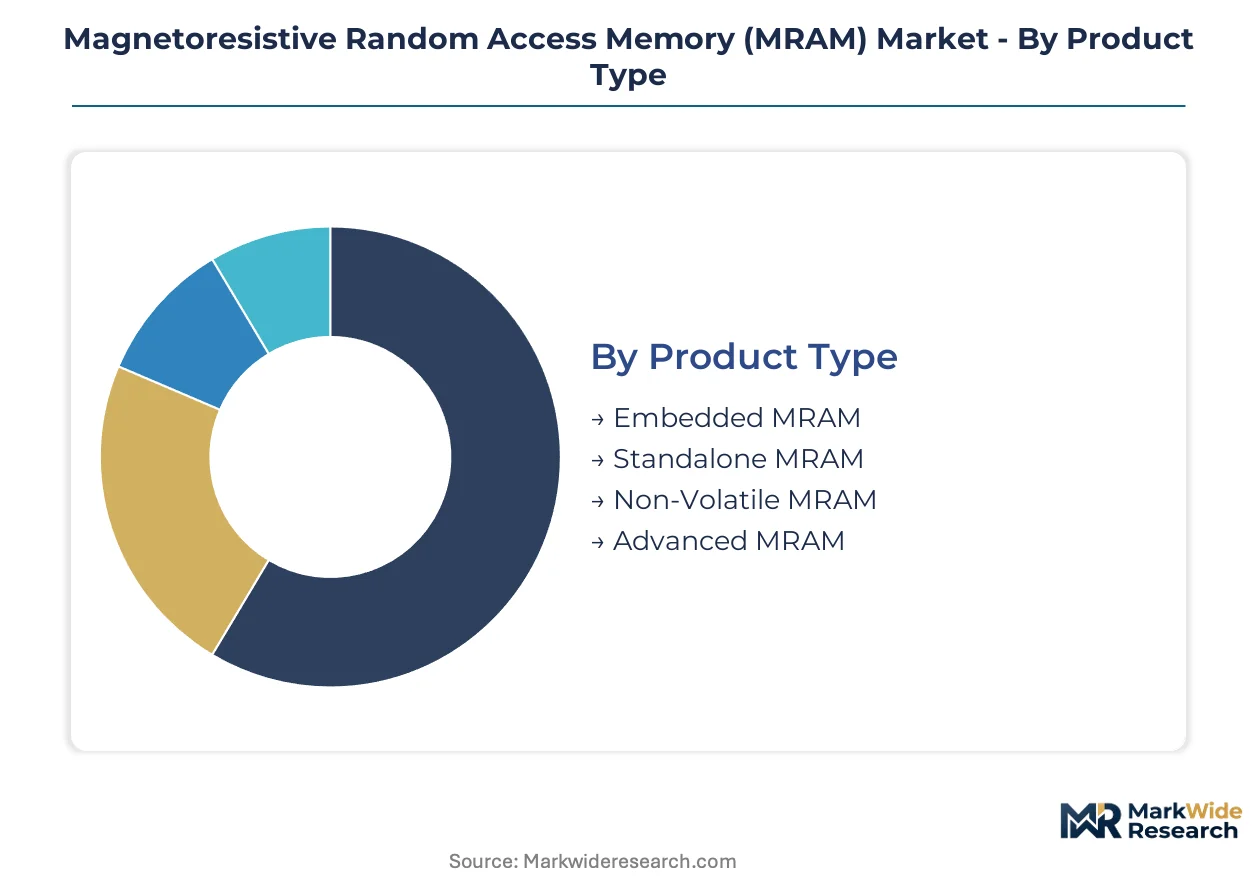
MRAM procurement patterns diverge sharply across integration architectures, with foundry-embedded solutions commanding fundamentally different service relationships than discrete component supply. Understanding these segment boundaries clarifies where margin pools concentrate and which qualification protocols govern vendor selection.
Product Type:
After-sales service intensity varies dramatically by product architecture, with embedded solutions requiring foundry-level process support while standalone devices demand field reliability programs.
- Embedded MRAM:Integrated directly into advanced logic process nodes at 22nm and below, utilizing magnetic tunnel junctions fabricated alongside CMOS transistors. Demand concentrates in Taiwan's Hsinchu Science Park cluster where pure-play foundries anchor pilot production for IoT microcontroller clients facing power-loss resilience requirements. EU Chips Act capital redirection is accelerating domestic embedded capacity qualification in European foundries.
- Standalone MRAM:Packaged as discrete non-volatile memory components with standardized interfaces, competing directly with NOR flash in industrial and aerospace sockets. Everspin Technologies anchors this segment with radiation-hardened devices for satellite command-and-control systems where single-event upset tolerance is mandatory.
- Non-Volatile MRAM:Emphasizes zero standby power retention for energy-harvesting endpoints in building automation and medical sensors.
- Advanced MRAM:Encompasses spin-orbit torque architectures and perpendicular magnetic anisotropy variants targeting sub-nanosecond write speeds.
Embedded MRAM holds the largest share; momentum sits with Advanced MRAM.
End User:
Automotive qualification timelines stretch 18-24 months, compressing revenue realization windows compared to consumer electronics sockets.
- Automotive:Electric vehicle powertrain controllers mandate AEC-Q100 Grade 0 temperature tolerance for firmware resilience during over-the-air updates. Infineon Technologies dominates this socket through tight coupling with microcontroller roadmaps, with procurement consolidating around direct foundry relationships in Germany's supply chain.
- Consumer Electronics:Smartphone and tablet manufacturers specify embedded MRAM for always-on voice assistants and secure enclave storage, with Samsung Electronics leveraging foundry-scale deposition expertise to anchor advanced logic node integration.
- Industrial Automation:Factory floor controllers require write endurance exceeding NAND flash capabilities for continuous data logging in predictive maintenance systems.
- Telecommunications:Baseband processors and network interface cards utilize persistent memory for configuration retention during power cycling.
Automotive commands premium pricing tiers; Consumer Electronics delivers volume scale.
Integration Level:
System-on-Chip integration collapses traditional memory hierarchy boundaries, eliminating package-level interconnect costs.
- System-on-Chip:MRAM macros embedded within processor die alongside CPU, GPU, and NPU cores, enabling byte-addressable persistent storage without off-chip buses. IoT edge AI accelerators in South Korea adopt this architecture for weight storage directly on inference engines.
- Chip Level:Bare die supply to module integrators, common in space-constrained wearable devices where custom packaging is required.
- Module Level:Standardized DIMM or M.2 form factors for data center persistent memory tiers.
- Board Level:Discrete components soldered to system motherboards in industrial control systems.
System-on-Chip integration captures the steepest expansion trajectory; Chip Level serves niche customization demand.
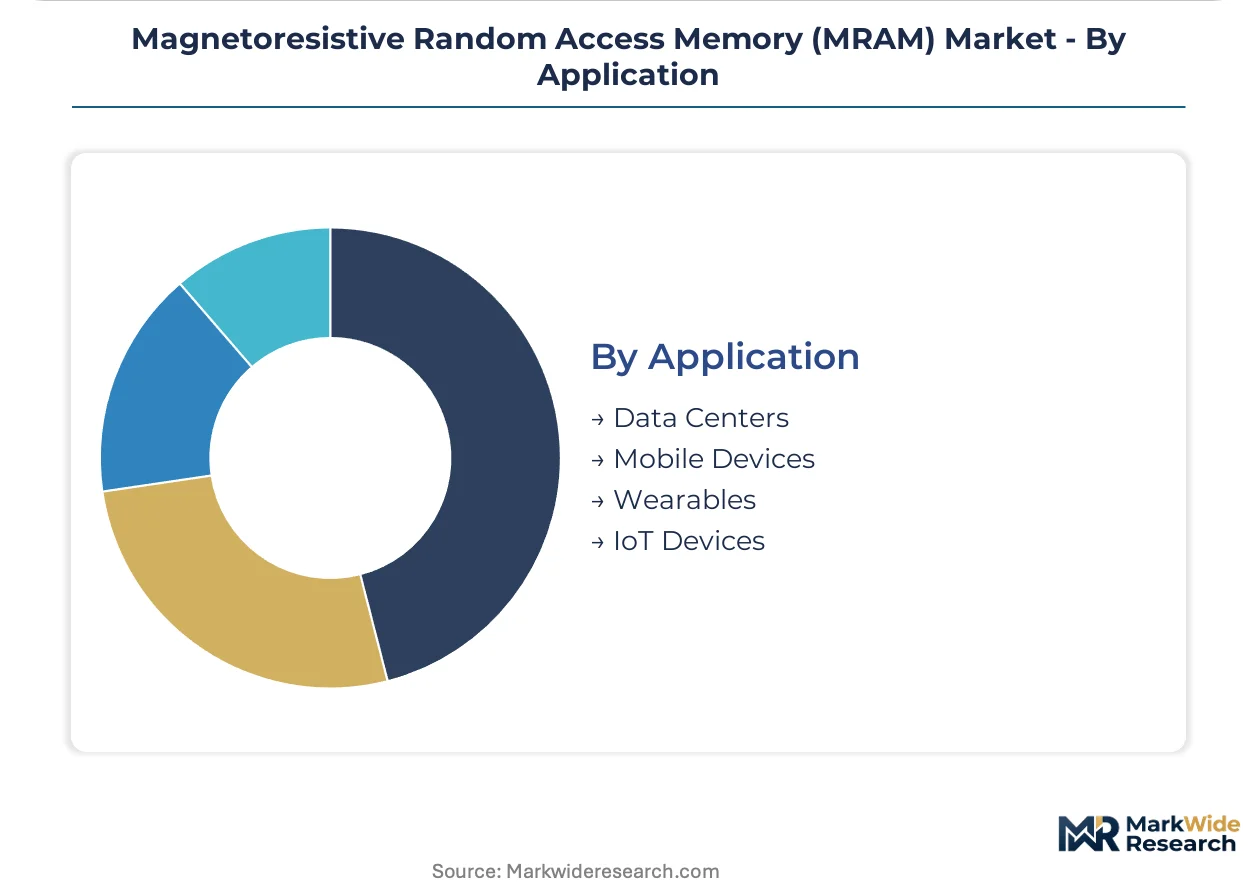
Application:
Wearables impose the most severe energy constraints, favoring MRAM's zero standby power over refresh-dependent DRAM.
- IoT Devices:Sensor hubs and edge nodes in smart buildings and connected agriculture deploy embedded MRAM for configuration retention without battery backup. FDA cybersecurity guidance for connected medical devices shapes qualification protocols in diagnostic equipment.
- Data Centers:Persistent memory tiers between DRAM and NAND flash enable fast recovery from power events in hyperscale facilities. Write endurance requirements here exceed conventional flash capabilities for logging and metadata storage.
- Wearables:Smartwatches and fitness trackers utilize compact MRAM for firmware and user data retention in extreme form factor constraints.
- Mobile Devices:Smartphones integrate MRAM for secure biometric template storage and rapid boot sequences.
IoT Devices lead current deployment volume; Data Centers offer the highest expansion ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive ECU architects in Germany, foundry engineers in Taiwan, and defense procurement officers in the United States represent the three dominant buyer archetypes determining regional demand patterns for embedded and standalone MRAM.
United States
Defense and aerospace contractors drive classified demand for radiation-hardened non-volatile memory in satellite command systems. FAA and DoD procurement specifications mandate single-event upset tolerance for space-grade computing. Albuquerque, New Mexico hosts concentrated testing facilities where MRAM devices undergo particle bombardment qualification.
Germany
Bosch and Continental directly engage foundries for 28nm embedded MRAM wafers, bypassing traditional microcontroller bundled supply. KBA automotive safety standards and EU REACH substance restrictions govern cobalt-free magnetic layer qualification. Bavaria's automotive supply corridor anchors powertrain controller development with AEC-Q100 Grade 0 requirements.
Taiwan
Pure-play foundries at Hsinchu Science Park pilot 22nm and below embedded MRAM for IoT microcontroller clients. The National Science and Technology Council directs public R&D funding toward magnetic tunnel junction yield improvement. Taichung's precision machinery cluster supplies physical vapor deposition equipment for magnetic stack patterning.
South Korea
Smartphone manufacturers specify embedded MRAM for secure biometric storage and always-on voice assistants. MFDS medical device cybersecurity guidance shapes connected diagnostic equipment qualification. Seoul's system semiconductor design houses integrate persistent memory into edge AI inference accelerators.
Japan
Industrial automation OEMs require write endurance exceeding NAND flash for predictive maintenance data logging. METI's semiconductor revitalization program subsidizes domestic non-volatile memory pilot lines. Hiroshima's precision materials suppliers optimize magnesium oxide barrier deposition for sub-nanosecond write speeds.
Magnetoresistive Random Access Memory (MRAM) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent qualification requirements. The market structures into tiered supply relationships where foundry-integrated memory providers face discrete component specialists. Three archetypes dominate: IDM-foundry hybrids with logic node integration capabilities, standalone memory specialists with radiation-hardened portfolios, and fabless design houses licensing magnetic tunnel junction IP. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves as yield maturity at advanced nodes determines socket access.
Among the IDM-foundry tier, Samsung Electronics Co., Ltd. and Intel Corporation occupy positions spanning logic integration and memory fabrication. Everspin Technologies Inc. exemplifies the standalone specialist archetype with discrete component supply for industrial and aerospace sockets. Taiwan Semiconductor Manufacturing Company Limited anchors foundry-scale embedded MRAM production for fabless design clients.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Infineon Technologies AG |
| Intel Corporation |
| Samsung Electronics Co., Ltd. |
| Everspin Technologies Inc. |
| Avalanche Technology Inc. |
| Taiwan Semiconductor Manufacturing Company Limited |
| STMicroelectronics N.V. |
| Spin Memory Inc. |
| Others |
Supply & Pricing Matrix
Hsinchu Science Park's embedded MRAM pilot line concentration grants Taiwan-based foundries asymmetric pricing power over automotive and IoT clients seeking AEC-Q100 Grade 0 qualification. Physical vapor deposition equipment bottlenecks at Japanese and European vendors amplify this leverage, compressing margin negotiation windows for buyers locked into 22nm node roadmaps.
Pricing Analysis
Cost-plus contracts with cobalt and magnesium oxide indexation dominate embedded MRAM procurement, insulating foundries from magnetic material volatility while exposing buyers to rare earth price swings. Price differentiation centers on AEC-Q100 certification grade and wafer volume commitments, with automotive powertrain controllers showing lowest price sensitivity due to firmware resilience mandates. Pricing pressure stems from yield maturity gaps below 22nm, where bitcell variability forces selective discounting to secure IoT microcontroller socket wins against NOR flash incumbents.
Supply Chain Analysis
Export control regimes restricting extreme ultraviolet lithography and advanced deposition tool flows to Chinese fabs concentrate high-node MRAM capacity in Taiwan, South Korea, and the United States. Supply chains draw from Japanese magnesium oxide barrier suppliers, German cobalt-iron-boron alloy producers, and Dutch etch equipment vendors. Single-source vulnerability pervades physical vapor deposition tool procurement, where Tokyo Electron and Singulus Technologies anchor global magnetic stack patterning capacity. Distribution runs through direct foundry relationships with automotive tier-ones and fabless design house consignment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perpendicular magnetic anisotropy stack optimization expertise concentrates among fewer than two dozen research groups globally, creating a chokepoint that determines which foundries achieve yield maturity first. This scarcity dynamic rewards early movers who secure talent and equipment slots before competitors.
For Market Incumbents: Pre-empt emerging spin-orbit torque entrants by locking exclusive physical vapor deposition equipment allocations with Japanese vendors for 2026-2028 delivery windows. Accelerate AEC-Q100 Grade 0 qualification pipelines to defend automotive socket access against Everspin's radiation-hardened standalone alternatives. Deepen backward integration into cobalt-free magnetic alloy R&D to neutralize EU REACH compliance risks in European-qualified devices. For New Entrants and Emerging Players: Build out edge AI inference accelerator design services targeting South Korean system semiconductor houses seeking persistent memory integration for on-device weight storage. White-space concentrates in satellite command-and-control radiation-hardened sockets, where Albuquerque testing infrastructure and FAA procurement specifications create qualification moats against Asian foundry competition. Lead with software-defined memory controller IP licensing to bypass capital-intensive fab construction. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign technology access play because EU Chips Act and US CHIPS Act capital redirection prioritizes domestic non-volatile memory fabrication capacity as strategic infrastructure. Acquisition targets should display embedded MRAM IP libraries with 28nm and 22nm tape-out validation, plus existing automotive tier-one foundry relationships. The signal to watch is which foundry node achieves embedded MRAM yield parity with NOR flash first—this inflection determines cost-competitive socket access in high-volume IoT deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Spin-Orbit Torque Technology Transition | Reduces write current density for energy-harvesting IoT endpoints in Taiwan sensor hubs. |
| AEC-Q100 Grade 0 Qualification Acceleration | Unlocks electric vehicle powertrain controller sockets requiring firmware resilience during over-the-air updates. |
| Cobalt-Free Magnetic Alloy Development | Neutralizes EU REACH substance restrictions threatening European medical device market access. |
| Direct Foundry Relationship Establishment | Bypasses microcontroller bundled supply consolidation by Bosch and Continental in Germany. |
| Radiation-Hardened Discrete Component Expansion | Captures satellite command-and-control demand from FAA and DoD procurement specifications. |
Research Methodology
Cross-validation between primary interviews with foundry process engineers, automotive ECU architects, and magnetic materials researchers anchors the qualitative findings against secondary sources including SEC semiconductor capex disclosures, EU Chips Act implementation documents, and AEC-Q100 qualification test data. Foundry yield reports, equipment vendor order backlogs, and Taiwan National Science and Technology Council R&D funding announcements provide bottom-up and top-down triangulation points.
Calibration against historical node ramp curves and magnetic tunnel junction bitcell density trajectories shapes the analytical framework across the analysis window. Segmentation dimensions span product architecture, integration level, end-use industry, and regional foundry cluster. CAGRs derive from wafer start projections, die size scaling assumptions, and blended ASP erosion curves for embedded versus standalone configurations. Cobalt price volatility and EU REACH substance list expansion timelines constitute industry-specific forecast inputs.
Stress conditions across foundry yield maturity timelines, equipment delivery lead times, and automotive qualification cycle durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spin-transfer torque dominance persistence and sovereign subsidy program continuity. Material shifts in export control regime stringency or perpendicular magnetic anisotropy stack breakthrough timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
MRAM Market
Memory Chips
DDR RAM Market
Memory Chips
Memory IC Market
Memory Chips
Nano RAM Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
Automotive DRAM Market
Memory Chips
Static RAM Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Global Standalone Memory Market
Memory Chips
GDDR6 Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Next Generation Memory Market