
 Germany Data Center Storage Market | 2026-2036
Germany Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Storage Market Insights
Enterprise procurement channels for storage infrastructure is tilting toward direct OEM relationships and hyperscale-adjacent integrators. Dell Technologies leverages its server-storage converged portfolio to anchor large German automotive and manufacturing accounts. Pure Storage differentiates through all-flash arrays designed for cloud-native workloads. IBM sustains mainframe-attached storage relationships across Frankfurt's banking corridor.
Germany Data Center Storage encompasses solid-state, magnetic, and software-defined media systems engineered for persistent data retention, with flash arrays achieving sub-millisecond latency and tape libraries reaching petabyte-scale air-gapped archives. The primary purpose centers on ensuring business continuity, regulatory compliance, and analytics throughput for digitally intensive organizations. Flash Memory and Software-Defined Storage command premium positioning as enterprises retire spinning disk for latency-sensitive applications. Object Storage gains traction for unstructured data lakes serving AI training pipelines. Hybrid Storage installations bridge on-premises retention with cloud burst capacity.
Germany's Federal Office for Information Security (BSI) imposes baseline protection catalog requirements that shape encryption and access-control specifications for federal and critical infrastructure deployments. The EU Energy Efficiency Directive, transposed through national building codes, forces cooling and power density disclosures that influence storage hardware selection. Germany's data localization norms under GDPR and the proposed EU Data Act restrict cross-border processing, reinforcing sovereign cloud storage demand. Stakeholders must weigh BSI certification timelines against the accelerating shift to software-defined architectures that decouple hardware refresh cycles from capacity planning.
Market Dynamics
Germany's Energy Efficiency Act is compressing storage hardware refresh cycles as operators race to meet power usage effectiveness thresholds before federal compliance deadlines lock in.
Growth Catalysts
- BSI Baseline Protection Catalog:Federal and critical infrastructure operators must deploy certified encryption and access-control systems, creating mandatory replacement demand across government and banking storage estates.
- AI training pipelines:Automotive manufacturers in Baden-Württemberg and Bavaria are provisioning petabyte-scale object storage lakes to feed machine learning model development for autonomous systems.
- Frankfurt Rhine-Main clustering:Submarine cable landings and hyperscale availability zones concentrate demand in this metropolitan region, pulling storage infrastructure investment into established fiber corridors.
Market Restraints
- NAND flash supply concentration:German buyers remain exposed to Asian foundry output volatility for solid-state drive components, with limited domestic fabrication alternatives.
- GDPR data localization friction:Cross-border processing restrictions under Germany's transposed GDPR implementation complicate hybrid cloud storage architectures that burst capacity to non-EU regions.
- Tape library substitution ceiling:Air-gapped archival demand sustains magnetic media in regulated sectors, slowing all-flash penetration for cold-tier workloads despite latency advantages.
Strategic Opportunities
- Eastern German data center greenfield:Saxony and Thuringia offer stranded renewable power assets and brownfield industrial sites suitable for sovereign cloud storage campuses outside Frankfurt's saturated market.
- EU Data Act sovereignty mandates:Proposed restrictions on cross-border data transfers will reinforce demand for storage systems meeting German federal custody requirements.
- NVMe-over-Fabric convergence:The merging of high-speed networking protocols with flash storage architectures enables disaggregated infrastructure that separates compute refresh from capacity expansion.
Industry Challenges
- BSI certification latency:Federal security approval timelines for new storage platforms lag software-defined release cycles, forcing vendors to maintain parallel hardware SKUs.
- Legacy mainframe integration:Frankfurt's banking corridor retains System z-attached storage architectures, complicating cloud-native migration paths for financial workloads.
- Specialized engineering scarcity:German technical universities produce insufficient graduates in storage systems engineering relative to hyperscale facility construction rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Storage Market |
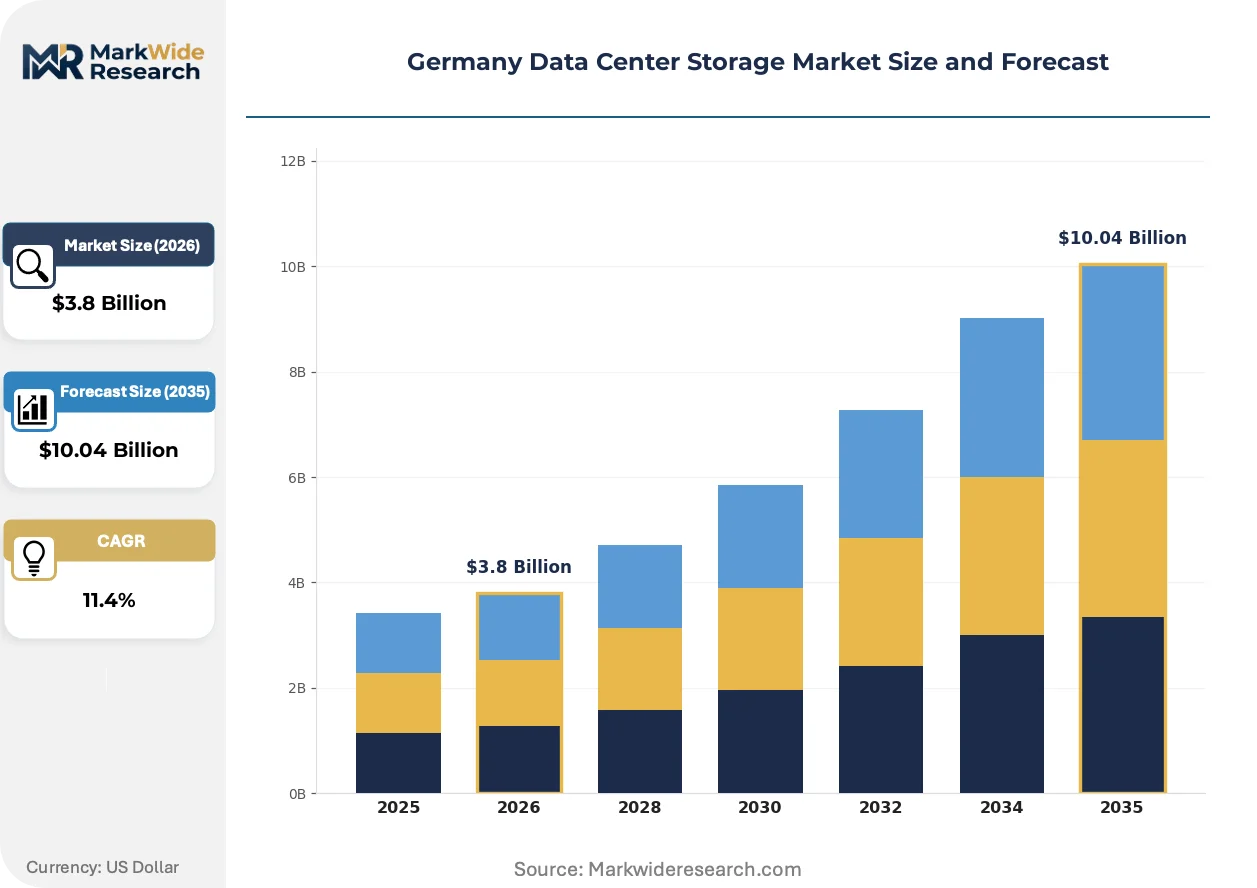
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Storage, Tape Storage, Cloud Storage, Hybrid Storage Technology: Flash Memory, Magnetic Storage, Object Storage, Software-Defined Storage End User: IT Services, Financial Institutions, Telecommunications, Government Agencies Installation: On-Premises, Colocation, Managed Services, Remote Deployment |
| Companies Covered | IBM, Pure Storage, Dell Technologies, Kingston Technology, Hitachi Vantara, Hewlett Packard Enterprise, Huawei Technologies, Lenovo Group, NetApp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Storage Market Trends and Innovations
Software-defined architectures are decoupling storage software from hardware refresh decisions, compressing traditional three-to-five-year replacement cycles into continuous capability layering.
Software-defined storage is virtualizing the data plane across commodity server hardware, enabling German enterprises to pool capacity from heterogeneous drive types behind unified management layers. Automotive and industrial machinery manufacturers in Stuttgart and Munich are deploying these architectures fastest, drawn by granular tiering that matches flash performance to real-time analytics while offloading archival streams to denser media. This abstraction layer is virtualizing vendor lock-in, allowing procurement teams to source drives from multiple suppliers without rearchitecting application storage policies.
REACH chemical substance restrictions are filtering into storage hardware supply chains, constraining flame-retardant formulations in printed circuit boards and cable insulation used in German facility deployments. Component suppliers must reformulate materials or risk exclusion from EU tenders, adding qualification overhead for new storage system introductions. Frankfurt-based colocation providers are responding by demanding full material disclosure from OEM partners ahead of hardware acceptance.
Consumption-based capacity contracts are displacing traditional capital purchase models for mid-market German enterprises, with storage vendors retaining hardware ownership and billing per terabyte-month. System integrators adjacent to hyperscale cloud regions are intermediating these arrangements, bundling operational support with elastic scaling rights. This pattern concentrates most visibly in North Rhine-Westphalia's manufacturing belt, where industrial firms prefer operational expenditure treatment for Industry 4.0 data infrastructure.
Germany Data Center Storage Market Segmentation
German data center procurement teams segment storage infrastructure across four dimensions that directly shape compliance posture and capital allocation. Product type determines power density and cooling load under the Energy Efficiency Act. Technology selection gates BSI certification eligibility. End user verticals impose divergent latency and retention requirements. Installation modality affects sovereignty and cross-border data flow risk.
Product Type:
Cost tier structures procurement decisions across German enterprises, with capital intensity and operational expenditure treatment varying sharply by media class.
- Disk Storage:Hard disk arrays deliver cost-per-terabyte economics for warm-tier workloads. Frankfurt's banking corridor deploys these systems for regulatory-mandated transaction logging where seven-year retention meets moderate access frequency.
- Tape Storage:Magnetic tape libraries achieve air-gapped isolation for ransomware protection. Germany's federal agencies and critical infrastructure operators specify LTO-9 formats under BSI baseline protection requirements for archival compliance.
- Cloud Storage:Hyperscale object repositories from Frankfurt-region availability zones serve burst capacity needs. GDPR localization constraints limit cross-border replication for sensitive datasets.
- Hybrid Storage:Tiered architectures combine on-premises flash with cloud cold tiers. Baden-Württemberg automotive manufacturers favor this model for engineering simulation data with variable access patterns.
Disk Storage holds installed capacity. Hybrid Storage is rotating up the share rankings.
Technology:
Application latency requirements and workload characteristics drive technology selection across German facility deployments.
- Flash Memory:NAND-based solid-state arrays achieve sub-millisecond response times for real-time analytics. Munich-based industrial automation firms deploy NVMe fabrics to support predictive maintenance pipelines feeding digital twin models.
- Magnetic Storage:Spinning disk and tape systems retain cost advantages for sequential access patterns. Energy Efficiency Act compliance timelines are compressing refresh cycles for legacy magnetic installations in older Frankfurt colocation facilities.
- Object Storage:Flat namespace architectures scale to exabyte capacity for unstructured data lakes. Bavarian AI research consortia provision these systems for training dataset repositories with S3-compatible APIs.
- Software-Defined Storage:Virtualized data planes decouple hardware from software refresh decisions. Saxony's emerging data center greenfield sites adopt these architectures to avoid vendor lock-in and enable multi-supplier drive sourcing.
Magnetic Storage retains archival dominance. Software-Defined Storage is climbing the fastest as procurement teams prioritize procurement flexibility.
End User:
Customer type determines security certification depth and contractual structures for German storage deployments.
- IT Services:Managed service providers aggregate multi-tenant capacity across heterogeneous client requirements. North Rhine-Westphalia's industrial belt sources storage-as-a-service through these intermediaries to convert capital expenditure to operational treatment.
- Financial Institutions:Frankfurt's banking corridor maintains mainframe-attached storage estates with strict BSI compliance mandates. System z architectures complicate cloud-native migration paths for core banking workloads.
- Telecommunications:Network operators provision edge caching and subscriber data repositories. 5G rollout timelines are driving distributed storage node deployment across rural Bavaria and Saxony.
- Government Agencies:Federal and state entities require certified encryption and access-control systems. The BSI baseline protection catalog creates mandatory replacement demand across government storage estates on fixed compliance schedules.
Financial Institutions anchor premium-tier procurement. Government Agencies are expanding fastest under federal digitization mandates.
Installation:
Geography and sovereignty risk shape modality selection for German data retention strategies.
- On-Premises:Enterprise-owned facilities in Stuttgart and Munich retain direct control over physical security and hardware maintenance. Automotive manufacturers favor this model for proprietary engineering data subject to industrial espionage concerns.
- Colocation:Shared facility space in Frankfurt Rhine-Main offers submarine cable proximity and hyperscale interconnection. Power usage effectiveness thresholds in the Energy Efficiency Act favor newer builds with liquid cooling over legacy raised-floor environments.
- Managed Services:Third-party operational responsibility includes hardware refresh and capacity scaling. Mid-market manufacturers in Thuringia prefer this model given constrained internal storage engineering resources.
- Remote Deployment:Edge and distributed architectures support low-latency requirements outside metropolitan fiber corridors. Autonomous vehicle testing zones in Lower Saxony deploy these configurations for real-time sensor data ingestion.
Colocation dominates Frankfurt-region capacity. Remote Deployment is gaining share fastest as edge computing requirements proliferate beyond core metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's submarine cable landings and hyperscale availability zones anchor Germany's data center storage demand. The Energy Efficiency Act mandates power usage effectiveness thresholds that compress hardware refresh cycles. Four sub-regions concentrate distinct deployment patterns across sovereign cloud, automotive AI, and federal compliance workloads.
Hesse
Frankfurt Rhine-Main's fiber corridors pull hyperscale storage investment into established interconnection hubs. The Energy Efficiency Act favors newer colocation builds with liquid cooling over legacy raised-floor environments. Financial institutions in Frankfurt maintain mainframe-attached storage estates with strict BSI baseline protection requirements.
Baden-Württemberg
Automotive manufacturers provision petabyte-scale object storage lakes for autonomous system training pipelines. Stuttgart-based industrial machinery firms deploy software-defined architectures to match flash performance with real-time analytics. Engineering simulation data with variable access patterns drives hybrid storage adoption across manufacturing campuses.
Bavaria
Munich's industrial automation sector deploys NVMe fabrics supporting predictive maintenance pipelines feeding digital twin models. Bavarian AI research consortia provision S3-compatible object storage systems for training dataset repositories. 5G rollout timelines drive distributed storage node deployment across rural zones.
North Rhine-Westphalia
Industrial firms across the manufacturing belt prefer consumption-based capacity contracts converting capital expenditure to operational treatment. Managed service providers aggregate multi-tenant capacity through storage-as-a-service intermediation. Dell Technologies leverages converged server-storage portfolios to anchor large automotive accounts.
Saxony
Stranded renewable power assets and brownfield industrial sites attract sovereign cloud storage greenfield development outside Frankfurt's saturated market. Emerging data center sites adopt software-defined architectures to enable multi-supplier drive sourcing. Technical university partnerships address specialized storage engineering scarcity constraining facility construction rates.
Germany Data Center Storage Market Competitive Landscape
On the supply side, the industry is tiered across converged infrastructure portfolios, all-flash specialists, and legacy mainframe-anchored relationships. Three strategic archetypes dominate: full-stack systems vendors bundling compute and storage, pure-play flash array specialists, and hybrid cloud integrators bridging on-premises retention with burst capacity. Competitive moves concentrate on direct OEM relationship cultivation and hyperscale-adjacent partnership structures.
Within the converged infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify full-stack portfolio approaches. IBM occupies a position anchoring mainframe-attached storage relationships across Frankfurt's banking corridor. Pure Storage represents the all-flash specialist archetype with cloud-native workload targeting. These three vendors collectively illustrate the market's segmentation between legacy integration demands and software-defined migration pressures.
| Leading Market Players |
|---|
| IBM |
| Pure Storage |
| Dell Technologies |
| Kingston Technology |
| Hitachi Vantara |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Lenovo Group |
| NetApp |
| Others |
Pricing and Supply Chain Analysis
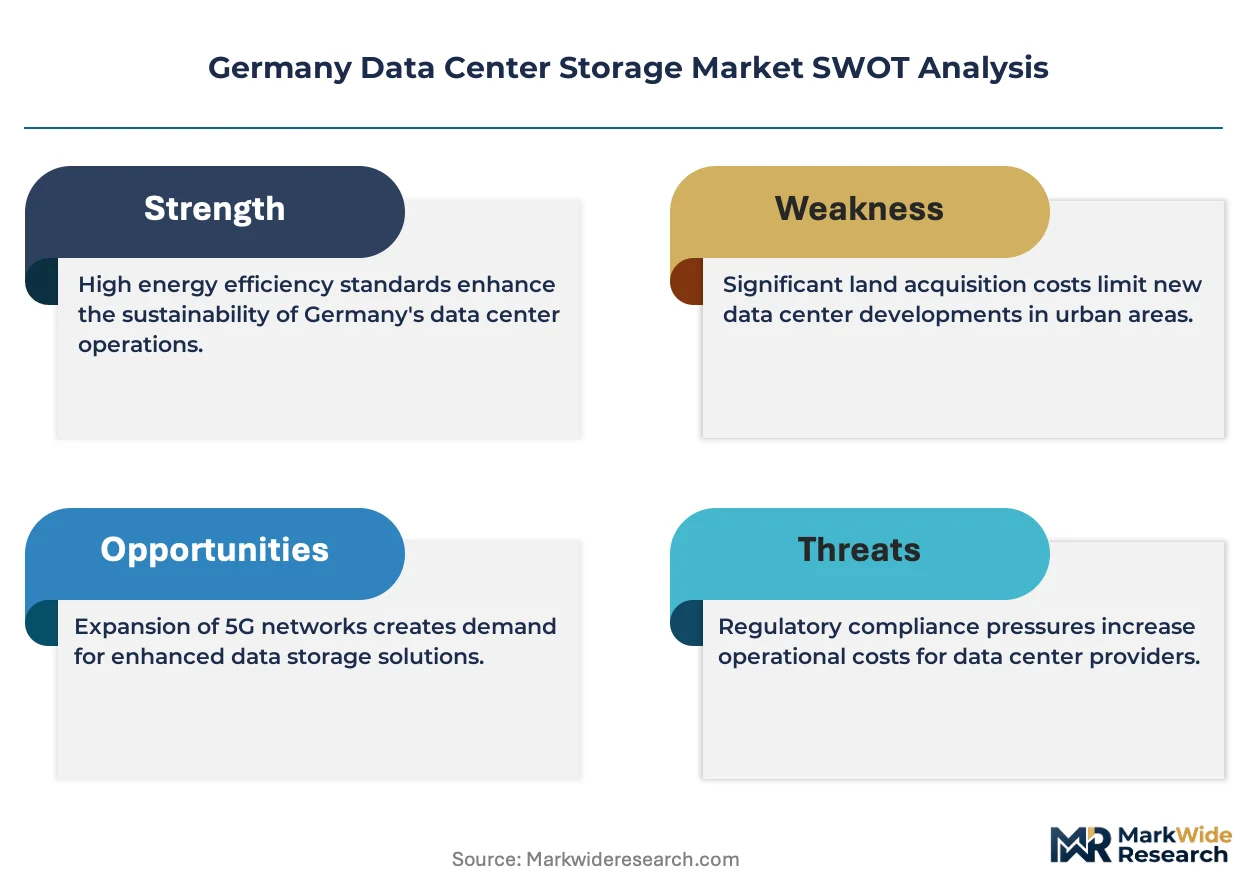
Korean and Taiwanese NAND foundry concentration feeds directly into margin capture at the flash array tier, while German automotive and banking buyers wield volume leverage to compress storage hardware premiums.
Pricing Analysis
Volume-discount tiering structures procurement negotiations across German enterprise storage, with hyperscale-adjacent integrators commanding steepest rebates against list prices. Pricing stratifies across all-flash performance tiers, BSI-certified security grades, and managed service bundling depth. Cost compression in mid-market disk arrays is intensifying because SaaS consumption models displace capital purchase treatment. Government agencies exhibit lowest price sensitivity given mandated compliance schedules, while Thuringia manufacturers negotiate hardest per terabyte-month.
Supply Chain Analysis
Extended payment terms from Frankfurt-based colocation providers now stretch component suppliers to 90-day cycles, tightening working capital across Asian contract manufacturers. NAND fabrication rests on South Korean and Taiwanese wafer output, with controller silicon sourcing from US fabless designers. Single-source vulnerability concentrates at the advanced node lithography tier. Distribution runs through Dell Technologies and HPE direct OEM channels alongside regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hyperscale-adjacent integrators as Frankfurt Rhine-Main clustering concentrates procurement leverage among fewer intermediaries.
For Market Incumbents: Entrench mainframe-attached storage relationships across Frankfurt's banking corridor through BSI certification roadmaps that outpace software-defined release cycles. Deepen upstream control over NVMe controller supply to offset NAND foundry pricing volatility. Software-defined migration pressure from cloud-native workloads threatens legacy integration revenues. For New Entrants and Emerging Players: Eastern German sovereign cloud greenfield in Saxony and Thuringia represents the most penetrable entry point given stranded renewable assets and brownfield industrial site availability. Mid-market managed services in North Rhine-Westphalia's manufacturing belt offer secondary white-space through operational expenditure conversion demand. Lead with consumption-based capacity contracts intermediated through regional system integrators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed colocation operators holding Frankfurt-region fiber corridor positions but lacking software-defined storage integration. Long-term viability hinges on disaggregated infrastructure architectures that separate compute refresh from capacity expansion cycles. Watch BSI certification timeline compression as inflection signal for hardware refresh acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| BSI Certification Fast-Track | Accelerates federal and banking sector hardware replacement cycles ahead of compliance deadlines. |
| NVMe-over-Fabric Deployment | Enables Munich industrial automation firms to feed predictive maintenance pipelines into digital twin models. |
| Sovereign Cloud Campus Buildout | Captures EU Data Act localization demand outside Frankfurt's saturated colocation market. |
| Consumption-Based Contract Expansion | Converts Baden-Württemberg automotive capital expenditure to operational treatment for Industry 4.0 workloads. |
| Software-Defined Architecture Migration | Decouples hardware refresh decisions from capacity planning for Saxony greenfield facilities. |
Research Methodology
The analysis maps solid-state arrays, magnetic archives, software-defined architectures, and hybrid cloud tiers, each validated through data center operators, storage procurement officers, BSI certification specialists, and colocation facility managers. Primary interviews combined with secondary validation from SEC hyperscaler capex disclosures, German federal procurement databases, and EU Energy Efficiency Directive transposition documents. Bottom-up capacity installations triangulate against top-down infrastructure spending estimates.
Assumption sets held German Energy Efficiency Act compliance timelines and BSI baseline protection catalog requirements fixed while varying NAND supply elasticity and hyperscale availability zone expansion rates. Segmentation dimensions modeled include product media class, technology latency tier, end-user vertical, and installation geography across the projection horizon. CAGRs derive from facility construction pipeline analysis and storage capacity-per-rack density trends. Forecast inputs incorporate power usage effectiveness threshold impacts on hardware refresh velocity and AI training pipeline storage provisioning ratios.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices or Asian semiconductor export volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and foundry capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Flash-Based Array Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Transparent Caching Market
Data Storage
External Storage Market
Data Storage
Universal Flash Storage Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
HDD Head Assembly Market
Data Storage
Ireland Data Center Storage Market
Data Storage
China Solid-State Drive Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Object-Based Storage Market
Data Storage
Americas Flash Memory Market
Data Storage
Enterprise-Class Hybrid Storage Market