
 Mobile DRAM Market | 2026-2036
Mobile DRAM Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile DRAM Market Insights
The gap between premium LPDDR5 stacks and commodity LPDDR4X modules is shifting procurement strategies across smartphone OEMs. Samsung Electronics leverages captive foundry output to anchor supply security for its own mobile division and external customers. SK Hynix sustains aggressive R&D intensity in advanced packaging, while Micron Technology competes through geographic diversification of its backend assembly network.
Mobile DRAM comprises low-power double data rate synchronous dynamic random-access memory engineered for thermal-constrained portable electronics, operating at sub-1.1V voltages with multi-channel architectures to balance bandwidth against battery drain. LPDDR5 now leads product type transitions as handset brands mandate faster data throughput for on-device AI inference. Wearables and IoT devices represent the fastest-growing end-user category, though absolute volume pools remain concentrated in smartphones where 8GB and 12GB capacity tiers command premium positioning.
South Korea's KOSPI disclosure rules, China's GB standards for electronic product energy consumption, and the United States FCC equipment authorization framework collectively shape memory module certification pathways and cross-border shipment protocols. SAMR market-access reviews in China and EPA energy-use guidelines in the United States further constrain non-compliant suppliers. Stakeholders must monitor which regulatory jurisdiction tightens power-density standards first, as this will determine whose memory architectures achieve design-in priority across next-generation mobile platforms.
Market Dynamics
The migration from LPDDR4X to LPDDR5X is compressing product lifecycles and forcing foundry partners to retool before amortization schedules complete. Memory vendors now face simultaneous pressure from EU energy-efficiency mandates and smartphone OEMs demanding higher bandwidth for on-device AI workloads.
Growth Catalysts
- EU Energy-Efficiency Directives:Tightening power-density benchmarks for portable electronics are mandating sub-1.1V operation, accelerating LPDDR5 adoption across flagship and mid-tier smartphone portfolios.
- On-Device AI Inference:Handset brands require faster data throughput for neural processing units, pulling memory configurations toward 12GB and 16GB capacity tiers in premium segments.
- South Korea-China-US Clustering:Foundry and advanced packaging ecosystems concentrate in these three markets, creating geographic pull effects that anchor supply security for regional OEMs.
Market Restraints
- Extreme Ultraviolet Lithography Dependency:EUV scanner availability constrains leading-edge node expansion, with equipment lead times extending beyond eighteen months for DRAM-specific patterning layers.
- Dual South Korean Supply Concentration:Captive production at Samsung Electronics and SK Hynix limits third-party foundry alternatives, creating vulnerability during geopolitical trade disruptions.
- GB Standards Compliance Burden:China's electronic product energy consumption certification adds testing cycles and documentation requirements that delay module qualification timelines.
Strategic Opportunities
- Wearables and IoT White Space:Ultra-low-power LPDDR4X variants for hearables and industrial sensors remain underpenetrated relative to smartphone saturation, offering volume diversification.
- Advanced Packaging Convergence:Hybrid bonding and through-silicon via stacking enable memory-logic integration that reduces board footprint for foldable handset form factors.
- SAMR Market-Access Streamlining:China's State Administration for Market Regulation is piloting expedited review pathways for energy-efficient components, potentially compressing approval timelines for compliant suppliers.
Industry Challenges
- Backend Assembly Talent Scarcity:Flip-chip and wire-bonding specialists with DRAM-specific thermal management experience command premium wages in Taiwan and Malaysia packaging hubs.
- FCC Equipment Authorization Complexity:Electromagnetic interference testing for multi-channel LPDDR5 architectures requires iterative redesign cycles that extend time-to-revenue.
- Legacy LPDDR4X Inventory Integration:Smartphone OEMs maintaining dual-sourcing strategies face firmware complexity when mixing memory generations within single product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile DRAM Market |
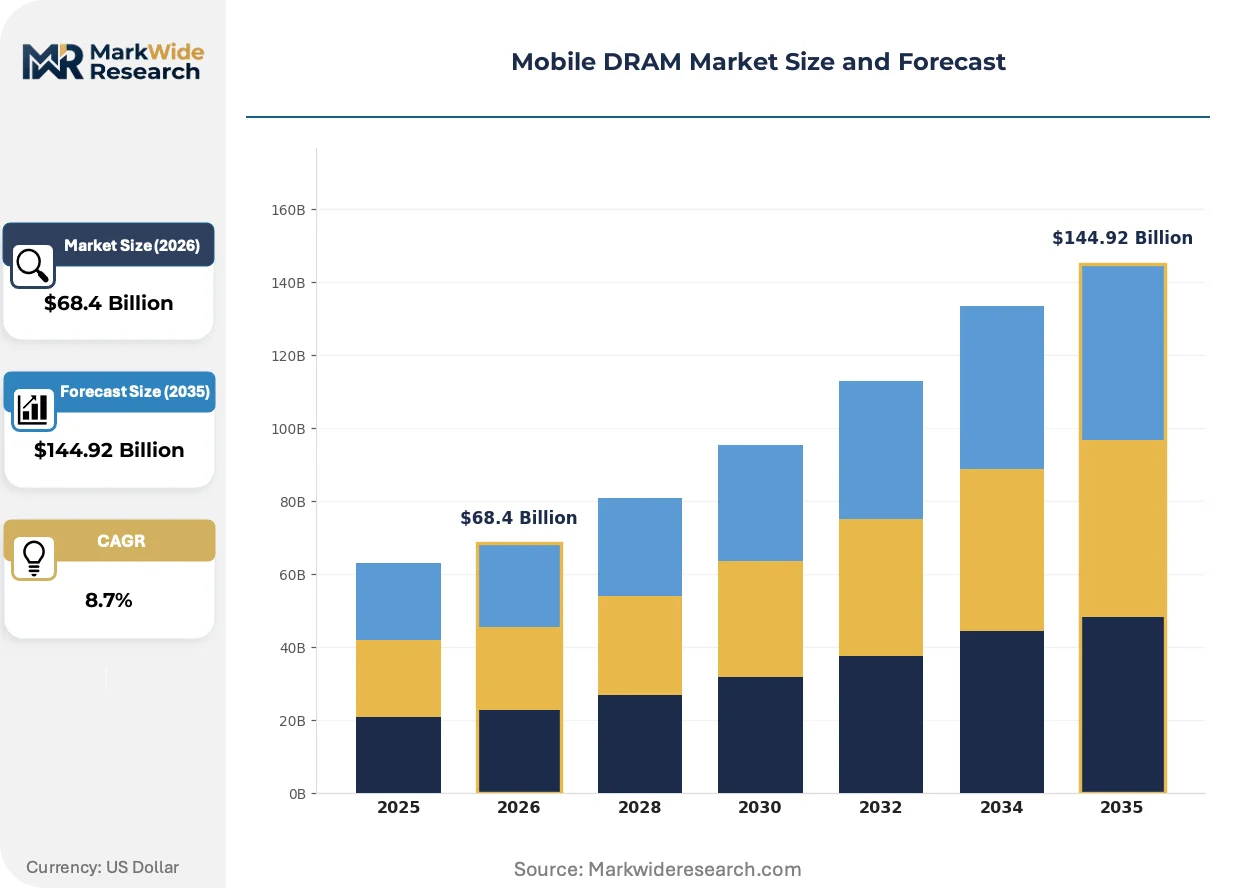
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LPDDR4, LPDDR4X, LPDDR5, Others End User: Smartphones, Tablets, Wearables, IoT Devices Technology: 3D Packaging, TSV, Fan-Out, FOWLP Capacity: 4GB, 6GB, 8GB, 12GB |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, CXMT, Nanya Technology, Winbond Electronics, Kingston Technology, Transcend Information, Powerchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile DRAM Market Trends and Innovations
Memory architectures are being redefined by the collision of AI compute requirements and thermal constraints in handheld devices. Three forces are restructuring how DRAM is designed, qualified, and procured.
LPDDR5X is electrifying bandwidth-per-watt metrics for flagship smartphones. The specification operates at 8.5Gbps per pin while maintaining sub-1.05V voltage floors. Samsung Electronics and Apple are absorbing early supply allocations for 2024-2025 handset launches. This electrifying performance envelope is compressing the viable window for LPDDR4X in devices above six hundred dollar price points.
REACH substance restrictions and RoHS amendments are tightening material declarations for memory modules entering European distribution. ECHA has added several flame retardants and stabilizers to the candidate list, forcing substrate and molding compound reformulations. Suppliers with pre-certified green material sets are securing design-in priority with Dutch and German smartphone assemblers.
Direct foundry contracting is displacing traditional distribution for tier-one smartphone OEMs. Memory vendors now negotiate annual volume commitments with Apple, Xiaomi, and OPPO rather than routing through authorized distributors. This channel compression is most visible in China, where domestic handset brands leverage proximity to SK Hynix and Samsung Semiconductor sales offices in Beijing and Shenzhen.
Mobile DRAM Market Segmentation
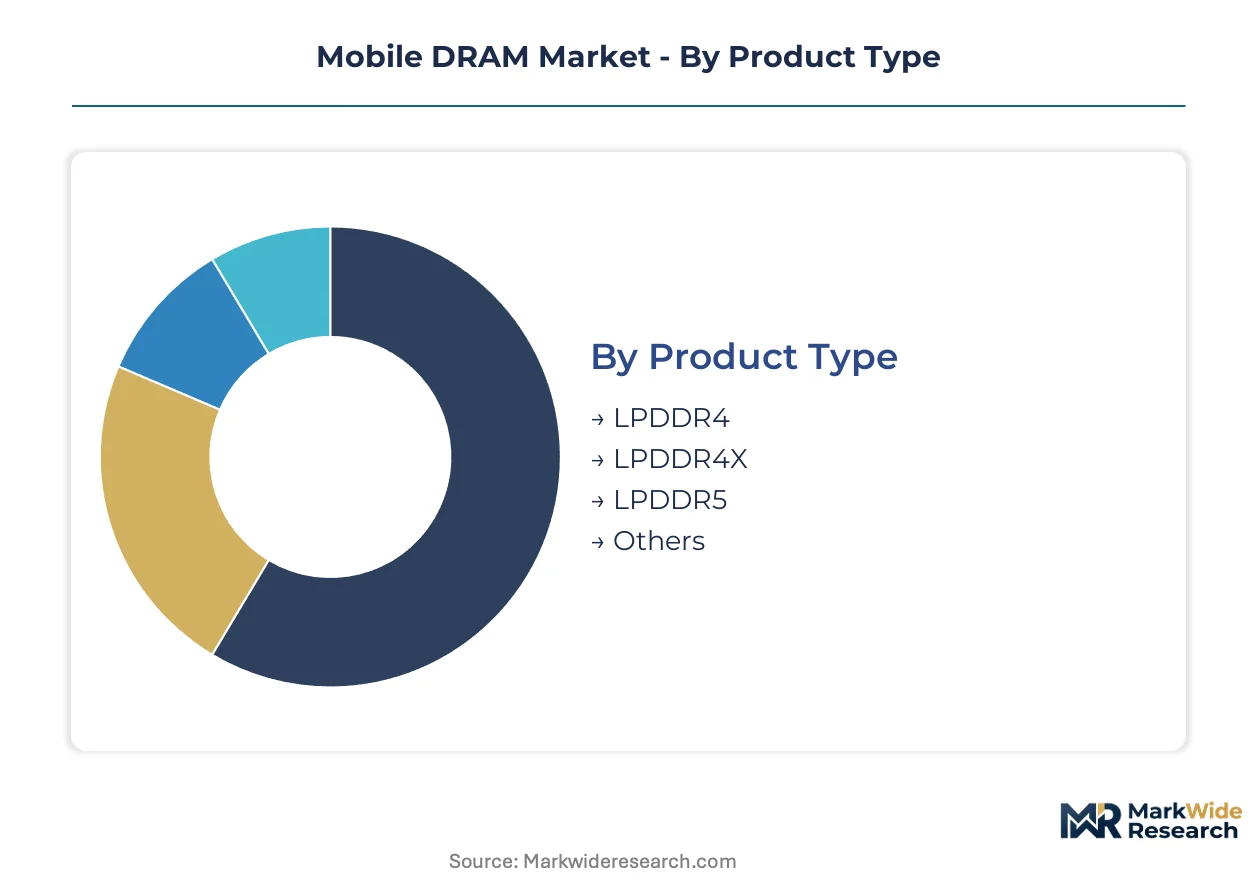
Mobile DRAM segmentation tracks the tension between established volume tiers and emerging premium configurations. OEM procurement strategies diverge sharply across product generations, end-use thermal constraints, and packaging complexity levels.
Product Type:
LPDDR5 commands premium positioning while LPDDR4X retains mid-tier volume dominance, creating a bifurcated supply landscape.
- LPDDR5:Operates at 8.5Gbps per pin with sub-1.05V voltage floors, enabling on-device AI inference in flagship smartphones. Samsung Electronics and Apple absorb early supply allocations for premium handset launches.
- LPDDR4X:Remains the workhorse for sub-six-hundred-dollar price points with mature yield curves and qualified second-source supply. Chinese smartphone OEMs maintain dual-sourcing strategies mixing LPDDR4X with newer generations.
- LPDDR4:Legacy architecture retained for industrial IoT and cost-constrained wearables where firmware stability outweighs bandwidth requirements.
- Others:Emerging LPDDR5X variants and low-power DDR3 derivatives for specialized sensor applications with extreme thermal constraints.
Today's leader: LPDDR4X. Tomorrow's challenger: LPDDR5.
End User:
Application thermal envelopes dictate memory architecture selection more than absolute bandwidth requirements.
- Smartphones:Concentrate absolute volume demand with 8GB and 12GB tiers commanding premium positioning. Handset brands mandate faster data throughput for neural processing units.
- IoT Devices:Expanding most quickly among end-use categories as industrial sensors and edge gateways adopt mobile DRAM for low-latency data processing. Absolute volume pools remain modest relative to handsets.
- Wearables:Ultra-low-power LPDDR4X variants for hearables remain underpenetrated relative to smartphone saturation, offering volume diversification opportunities.
- Tablets:Hybrid use cases blending media consumption with light productivity sustain demand for 6GB and 8GB configurations in education and enterprise deployments.
Smartphones anchor current revenue. IoT devices are climbing the fastest.
Technology:
Packaging innovation determines board footprint and thermal dissipation in foldable form factors.
- 3D Packaging:Hybrid bonding and through-silicon via stacking enable memory-logic integration that reduces board footprint for foldable handset form factors.
- TSV:Vertical interconnect technology supports high-density stacking for premium tier memory modules in space-constrained flagship devices.
- Fan-Out:Redistribution layer approaches improve signal integrity for multi-channel LPDDR5 architectures requiring iterative electromagnetic interference testing.
- FOWLP:Fan-out wafer-level packaging offers cost-advantaged alternatives for mid-tier smartphone memory modules with relaxed pitch requirements.
3D packaging leads premium qualification. Fan-out scales for cost-sensitive tiers.
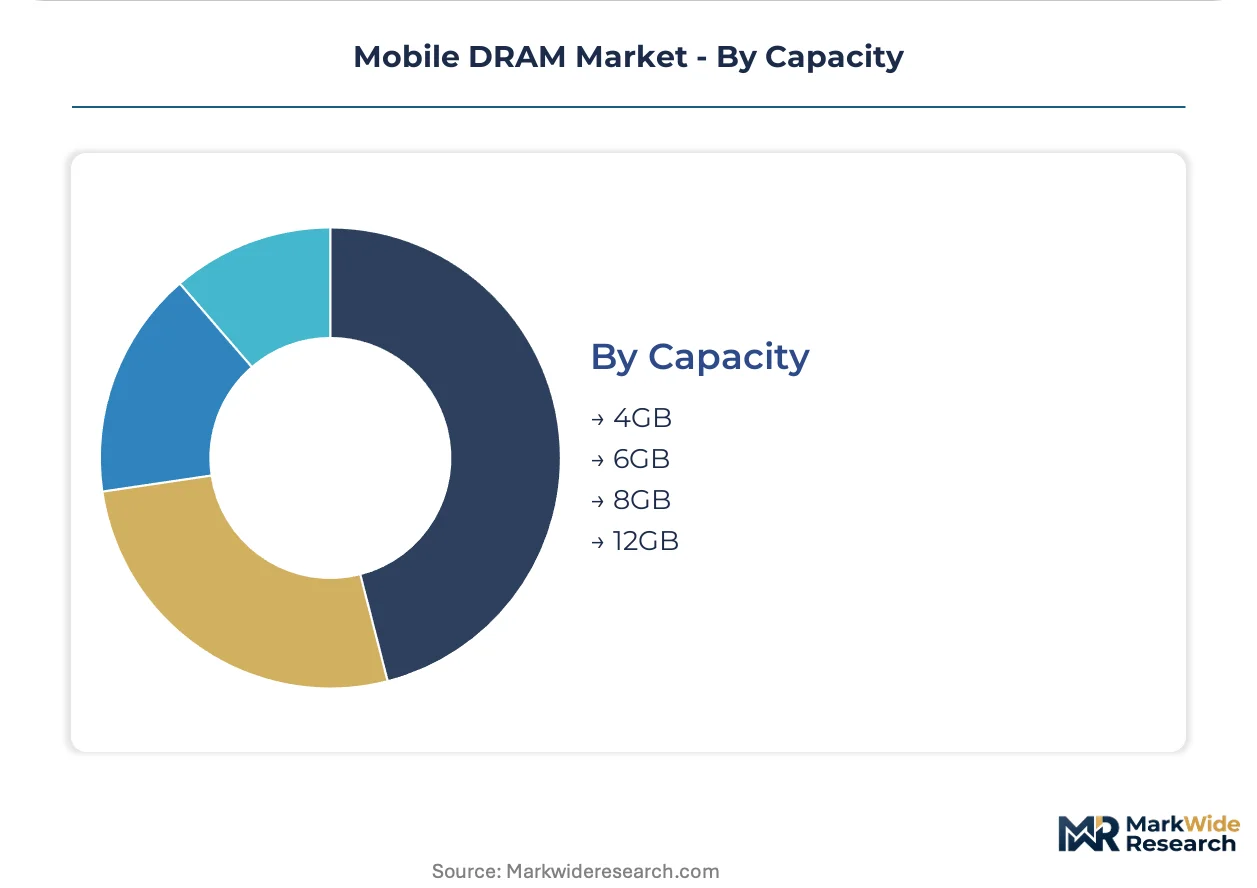
Capacity:
Configuration tiers map directly to handset price segmentation and regional purchasing power.
- 12GB:Flagship positioning for on-device AI workloads and extended multitasking in premium segments above eight hundred dollar price points.
- 8GB:Standard bearer for upper-mid-tier devices balancing future-proofing with bill-of-materials discipline across Chinese and Indian OEM portfolios.
- 6GB:Entry-premium tier sustaining volume in emerging market mid-range handsets where cost sensitivity limits configuration flexibility.
- 4GB:Baseline specification for budget smartphones and wearables with constrained thermal budgets and simplified operating system requirements.
8GB dominates shipment volume. 12GB gains share fastest in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Memory design talent clusters in South Korea's semiconductor corridors and China's Yangtze River Delta packaging hubs anchor regional competitive positioning. Backend assembly specialists with flip-chip expertise command premium wages in Taiwan and Malaysia. These workforce concentrations shape where foundry output converts into qualified mobile DRAM modules.
South Korea
Samsung Electronics and SK Hynix anchor captive foundry output for flagship smartphone launches. The MFDS oversees medical-grade component standards that influence adjacent mobile memory certification protocols. Pyeongtaek and Icheon host the world's densest concentration of EUV-enabled DRAM fabrication facilities.
China
Domestic smartphone OEMs in Beijing and Shenzhen drive 8GB and 12GB configuration demand across mid-tier portfolios. SAMR market-access reviews and GB standards for electronic product energy consumption shape module qualification timelines. The Yangtze River Delta packaging ecosystem converts wafer output into qualified LPDDR5 stacks for regional handset brands.
United States
Apple's procurement specifications pull memory architectures toward higher bandwidth-per-watt benchmarks. The FCC equipment authorization framework governs electromagnetic interference testing for multi-channel LPDDR5 architectures. Micron Technology maintains backend assembly operations that diversify geographic supply exposure.
Japan
Materials suppliers in Nagoya and Osaka prefectures provide advanced photoresists and high-purity gases for DRAM patterning layers. METI industrial policy coordinates domestic semiconductor supply chain resilience initiatives. Kyushu's silicon wafer foundries supply substrate material to South Korean and Taiwanese memory fabricators.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg source industrial-grade mobile DRAM for infotainment and driver-assistance systems. REACH substance restrictions and RoHS amendments tighten material declarations for memory modules entering European distribution. Dresden's silicon Saxony cluster hosts wafer fabrication facilities that supply European industrial electronics demand.
Mobile DRAM Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. The market consolidates around three memory fabricators controlling leading-edge node capacity, with second-tier specialists occupying legacy technology niches. Strategic archetypes include captive integrated producers, pure-play memory specialists, and fabless module assemblers. Competitive moves center on EUV scanner allocation contests and advanced packaging R&D partnerships.
Within the captive integrated tier, Samsung Electronics exemplifies foundry-to-handset vertical control. SK Hynix occupies a position bridging captive supply and external merchant sales. Micron Technology represents geographic diversification strategy through dispersed backend assembly networks. These three anchors illustrate how supply security, R&D intensity, and regional market access trade off in procurement decisions.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| CXMT |
| Nanya Technology |
| Winbond Electronics |
| Kingston Technology |
| Transcend Information |
| Powerchip Technology |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in South Korea and China anchor wafer fabrication capacity, creating pricing discipline through supply security guarantees that smartphone OEMs pay premiums to secure. This state-linked ownership pattern concentrates advanced node output while channeling contract structures toward long-term offtake agreements with volume commitments.
Pricing Analysis
Module-level pricing separates bundled firmware-qualification packages from unbundled raw memory stacks, with Chinese OEMs driving commoditization in the latter. Three-tier pricing structure across premium, standard, and economy levels maps to LPDDR5, LPDDR4X, and legacy LPDDR4 architectures respectively. Cost compression in mid-tier configurations is intensifying because foundry partners are retooling before amortization schedules complete. Budget smartphone OEMs in India and Southeast Asia exhibit highest price sensitivity, while Apple and Samsung Electronics absorb early supply allocations with least negotiation leverage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Apple, Xiaomi, and OPPO, displacing traditional distribution layers that previously managed inventory risk. Wafer output concentrates in South Korea, China, and the United States, with backend assembly drawing from Taiwan and Malaysia packaging hubs. Raw material dependencies include high-purity silicon wafers from Japan, EUV photoresists from Belgium and Japan, and specialized molding compounds subject to REACH substance restrictions. Single-source vulnerability around EUV scanner availability from ASML creates equipment lead-time risk that extends beyond eighteen months for DRAM-specific patterning layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile DRAM Market functions as a stable compounder anchored by smartphone refresh cycles that mandate memory upgrades for on-device AI inference. Foundry capacity constraints and packaging talent scarcity protect incumbent margins while creating predictable volume growth corridors.
For Market Incumbents: Lock in captive EUV scanner allocation through multi-year equipment commitments that block competitor node expansion. Secure flip-chip and wire-bonding specialists in Taiwan and Malaysia through long-term employment contracts that prevent talent migration to emerging packaging hubs. Defend against CXMT and other China-based entrants by accelerating LPDDR5X qualification timelines that exploit GB standards compliance burdens delaying rival module approvals.
For New Entrants and Emerging Players: Module assemblers without captive foundry output should target wearables and industrial IoT white space where ultra-low-power LPDDR4X variants remain underpenetrated relative to smartphone saturation. Foundry partners in China's Yangtze River Delta offer geographic proximity to domestic handset brands seeking second-source supply security. Pursue SAMR expedited review pathway pilot programs for energy-efficient components that compress approval timelines relative to incumbent qualification cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among advanced packaging specialists with hybrid bonding and TSV capabilities that enable foldable handset memory-logic integration. Long-term viability over the projection horizon rests on EUV-enabled node access and backend assembly geographic diversification. Monitor FCC equipment authorization timelines for multi-channel LPDDR5 architectures as signal of which memory vendors achieve design-in priority for next-generation flagship launches.
| Strategic Initiative | Industry Significance |
|---|---|
| EUV Scanner Allocation Lock-in | ASML equipment commitments anchor leading-edge node capacity against competitor expansion. |
| Advanced Packaging R&D Partnership | Hybrid bonding development with foldable OEMs reduces board footprint for next-generation form factors. |
| GB Standards Pre-Certification | SAMR compliance investment compresses module qualification timelines for China market access. |
| Backend Assembly Geographic Expansion | Malaysia and Vietnam packaging hubs diversify supply exposure beyond Taiwan concentration. |
| Long-Term OEM Volume Commitments | Annual contracting with Apple and Xiaomi displaces distribution margin and secures utilization. |
Research Methodology
Coverage spans South Korea, China, the United States, Japan, and Germany, with primary inputs from each market's semiconductor corridor. Interviews with DRAM foundry operations executives, smartphone OEM procurement leads, advanced packaging engineering directors, and regulatory compliance officers combined with secondary validation from SEC filings, customs trade data, SAMR disclosure databases, and FCC equipment authorization records. Bottom-up wafer output estimates and top-down smartphone BOM analysis triangulate volume and value figures.
Granularity-level framing models product type at LPDDR5, LPDDR4X, LPDDR4, and emerging variant resolution; end user at smartphone, IoT device, wearable, and tablet segmentation; capacity tier at 4GB through 16GB configurations; and packaging technology at 3D stacking, TSV, fan-out, and FOWLP differentiation. CAGRs derive from fitted growth curves applied to wafer start forecasts and die-per-wafer yield assumptions across the analysis window. EUV scanner delivery schedules and SAMR review pathway pilot expansion serve as industry-specific forecast sensitivity inputs.
Revisions become necessary when EUV equipment lead times extend beyond current eighteen-month baselines, when geopolitical trade disruptions fragment South Korean supply concentration, or when China's GB standards tighten power-density benchmarks ahead of EU timelines. Forecasts reflect documented assumptions regarding foundry yield ramp curves and smartphone refresh cycle elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
GDDR6 Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Next Generation Memory Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
In-Memory Computing Market
Memory Chips
Digital RF Memory Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
DDR SDRAM Market