
 Global Standalone Memory Market | 2026-2036
Global Standalone Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Global Standalone Memory Market Foresight
Specialized foundry engineering talent is bifurcating the competitive landscape between captive producers and merchant suppliers. Samsung Electronics leverages vertical integration across DRAM and 3D NAND to dominate wafer output. SK Hynix anchors high-bandwidth memory supply for AI accelerators through advanced packaging investments. Micron Technology navigates geopolitical trade restrictions by positioning its Idaho and Japan fabs for leading-edge node production.
Standalone memory encompasses semiconductor devices that retain or lose data based on electrical state configuration, with DRAM cells built from one transistor and one capacitor pairing refreshed thousands of times per second to preserve charge states. These components serve as the primary working and storage memory layer in virtually all electronic systems requiring fast data access. Flash memory, particularly 3D NAND with layer counts now exceeding 200 vertical tiers, occupies the bulk of storage value pools as cloud hyperscalers expand petabyte-scale deployments. Emerging resistive RAM and MRAM segments compete for embedded non-volatile slots in automotive and industrial controllers where radiation tolerance and write endurance exceed Flash capabilities.
FDA oversight of medical device data integrity and EPA hazardous substance rules affect memory packaging materials and end-of-life disposal pathways in the United States. The EU's REACH chemicals framework and RoHS substance restrictions constrain solder compositions and flame retardants used in module assembly across European supply chains. China's MIIT enforces domestic content ratios through GB standards that steer procurement toward local NAND and DRAM suppliers. Stakeholders must monitor how export control expansions and carbon border adjustments reshape fab location decisions and captive versus merchant sourcing strategies.
Market Dynamics
High-bandwidth memory packaging requirements for AI accelerators are compressing design cycles and forcing foundry customers into multi-year capacity commitments, locking in supply relationships before node qualification completes.
Growth Catalysts
- AI Training Clusters:Hyperscale data center operators in the United States are expanding DRAM procurement for large language model workloads, with petabyte-scale deployments now standard for training runs.
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating fab energy retrofits, creating demand for advanced heat recovery systems in European memory manufacturing facilities.
- 3D NAND Layer Stacking:Vertical scaling beyond 200 tiers is reducing cost per bit and enabling higher-density storage modules for enterprise solid-state drives.
Market Restraints
- Extreme Ultraviolet Lithography Costs:EUV equipment depreciation now accounts for the majority of leading-edge wafer processing expenses, compressing margins at nodes below 7nm.
- South Korean Supply Concentration:Two producers control over half of global DRAM bit shipments, creating vulnerability to single-point disruptions from seismic or geopolitical events.
- Charge Leakage in DRAM:Capacitor scaling limits are forcing more frequent refresh cycles, increasing power consumption and thermal design constraints in mobile devices.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme and dedicated memory packaging incentives are attracting test and assembly investments for regional supply chain redundancy.
- Automotive Zonal Architecture:Domain controller consolidation is creating demand for high-reliability non-volatile memory with 15-year data retention for safety-critical firmware storage.
- Resistive RAM Integration:The convergence of embedded non-volatile memory with advanced logic nodes is displacing discrete Flash in microcontroller units for industrial automation.
Industry Challenges
- Advanced Packaging Talent Scarcity:Chiplet interconnect design and hybrid bonding process engineering skills are concentrated among a small pool of specialists in Taiwan and South Korea.
- Fab Construction Timelines:Cleanroom qualification and tool installation for greenfield memory facilities now extend beyond four years, misaligning capacity ramps with demand cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Standalone Memory Market |
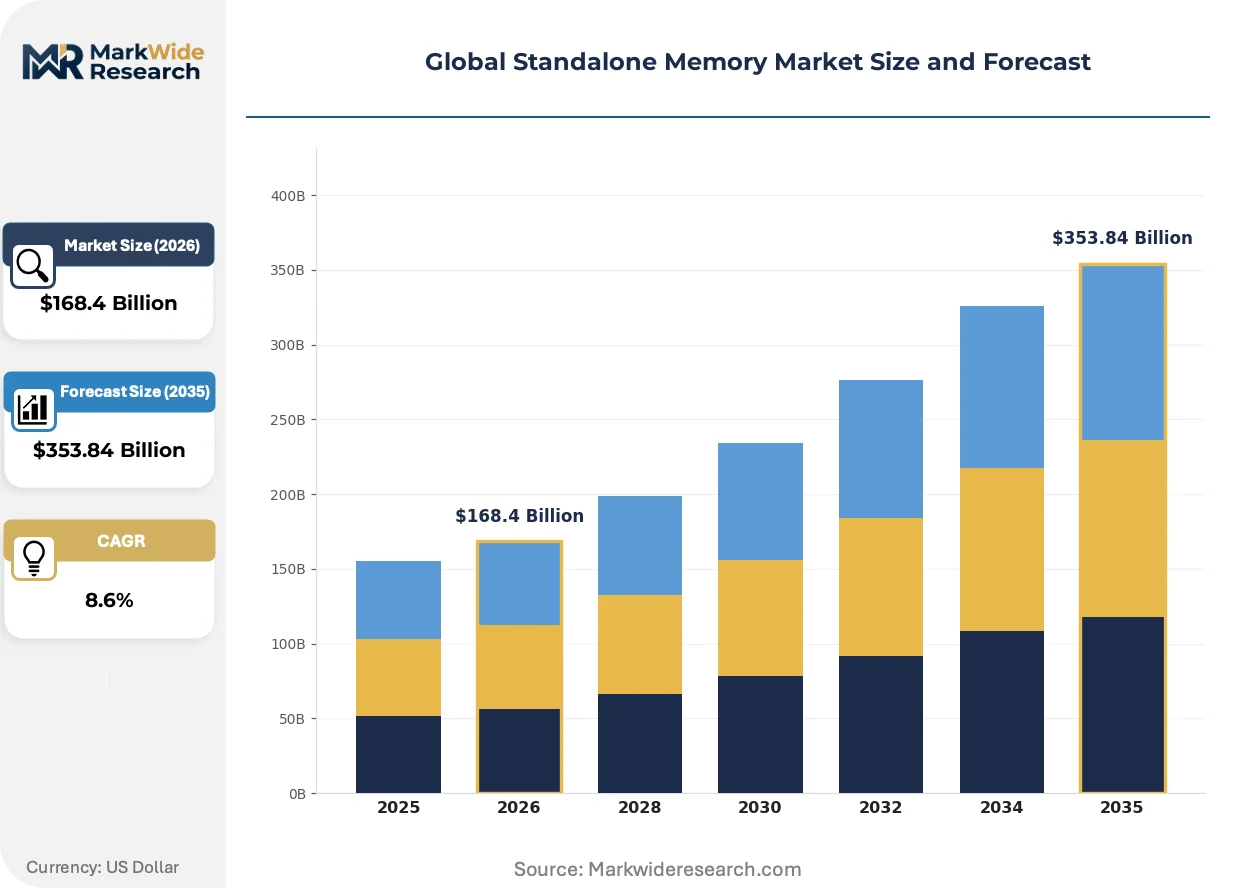
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $353.84 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Memory Type: DRAM, SRAM, Flash, PROM, EEPROM, MRAM Technology: 3D NAND, NOR, Phase Change Memory, Ferroelectric RAM, Resistive RAM, Spin Transfer Torque RAM Application: Consumer Electronics, Data Centers, Embedded Systems, Networking Equipment, Aerospace, Gaming Consoles End User Industry: Telecommunications, Automotive OEMs, Defense Systems, Industrial Automation, Artificial Intelligence, Smart Appliances |
| Companies Covered | Samsung Electronics Co. Ltd, SK Hynix Inc., Micron Technology Inc., Microchip Technology Inc., Fujitsu Semiconductor Memory Solution, Intel Corporation, Infineon Technologies AG, Nanya Technology Corporation, Powerchip Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Standalone Memory Market Shifts & Advancements
Memory architecture is bifurcating between bandwidth-optimized solutions for AI inference and density-optimized configurations for cold storage, with packaging technology becoming the primary differentiation axis.
Gate-all-around transistor architectures are displacing finFET designs in DRAM word-line drivers, enabling tighter cell packing without proportional leakage increases. Samsung Electronics and SK Hynix have both committed to process conversions at their Pyeongtaek and Icheon complexes. The structural consequence is compressing competitive parity timelines, as second-tier producers lack the capital depth for simultaneous node and packaging transitions.
China's MIIT enforcement of domestic content ratios through GB standards is redirecting procurement toward local NAND suppliers for state-affiliated cloud operators. Foreign memory module vendors must now establish joint ventures or licensing arrangements to participate in tenders for government data center builds. The server OEM segment is most affected, with several Taiwan-based suppliers accelerating mainland assembly capacity to maintain eligibility.
Hyperscale buyers are consolidating memory procurement through direct foundry relationships, bypassing traditional module vendors and distributors. Amazon Web Services, Microsoft Azure, and Google Cloud now specify die-level requirements and negotiate wafer supply agreements independently. This pattern is most visible in the United States, where vertical integration into custom memory controller design is becoming standard practice for the largest cloud operators.
Global Standalone Memory Market Segmentation
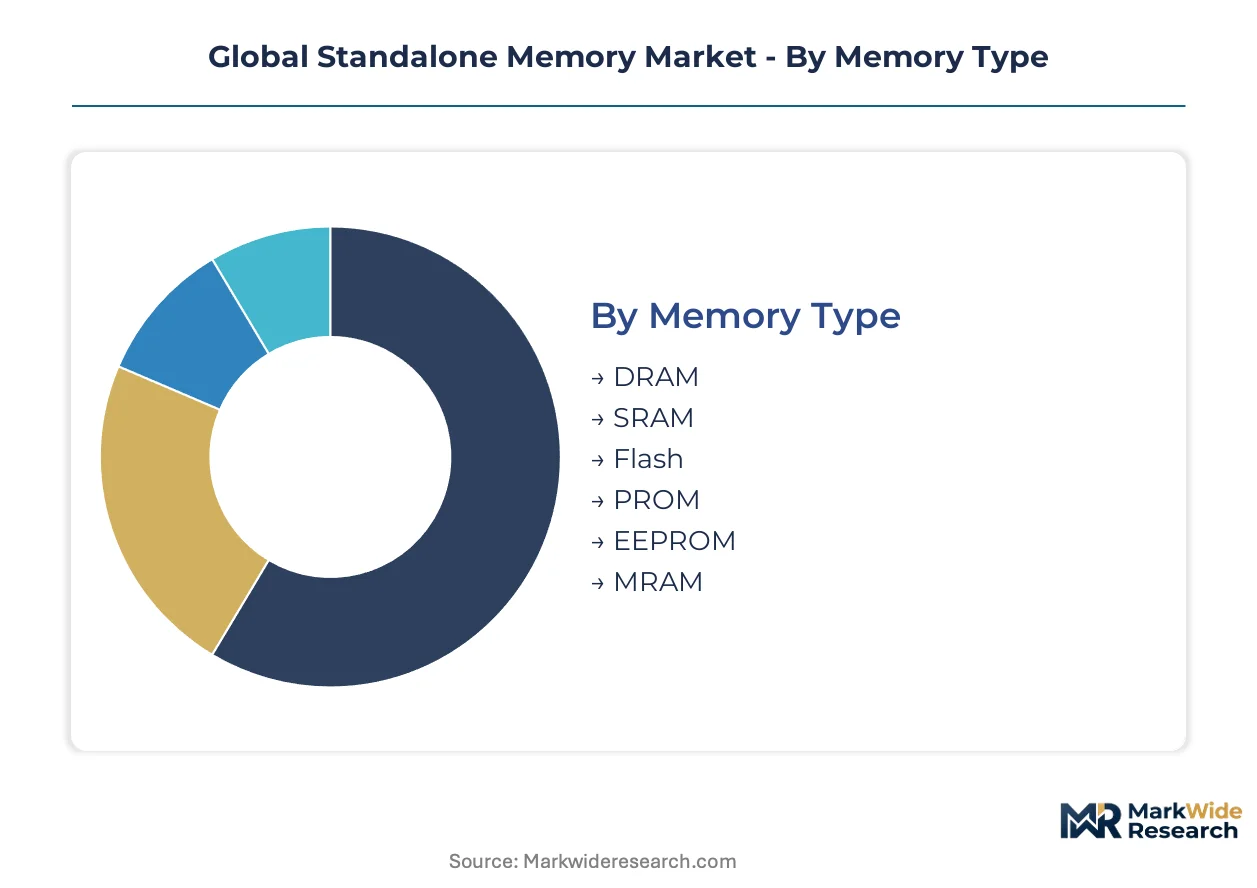
Standalone memory segmentation reveals how technology specialization fragments procurement patterns across geographies. Each category isolates distinct value pools where pricing power, volume concentration, and regulatory exposure diverge sharply.
Memory Type:
DRAM and Flash anchor domestic consumption in South Korea and the United States, while SRAM and emerging non-volatile variants ship disproportionately to export markets in Taiwan and Japan.
- DRAM:One-transistor-one-capacitor cells require constant refresh cycles to maintain charge states. Data center operators in the United States now specify die-level requirements for AI training clusters, locking in multi-year wafer supply agreements directly with foundries.
- Flash:3D NAND vertical stacking beyond 200 tiers dominates enterprise solid-state drive deployments. Cloud hyperscalers in the United States and state-affiliated operators in China drive divergent procurement specifications under MIIT domestic content enforcement.
- SRAM:Six-transistor cell designs serve cache hierarchies in high-performance processors. Demand concentrates in Taiwan's foundry ecosystem.
- PROM:One-time programmable fuse architectures retain niche status in aerospace firmware storage. Procurement runs through defense contractors in the United States.
- EEPROM:Byte-erasable floating-gate cells persist in automotive ECU configurations. European automotive OEMs specify extended temperature grades under KBA reliability mandates.
- MRAM:Magnetic tunnel junction switching enables unlimited write endurance. Industrial automation deployments in Japan leverage METI-funded pilot programs.
Flash commands the established base. The steepest expansion runs through DRAM.
Technology:
Cost tier differentiation separates commodity 3D NAND from premium resistive and phase-change variants, with process maturity determining margin capture.
- 3D NAND:Charge-trap flash stacked in vertical strings reduces cost per bit through layer multiplication. South Korean producers dominate wafer output, shipping modules to data center operators in the United States.
- Resistive RAM:Filamentary switching in metal-oxide stacks enables embedded non-volatile integration at advanced logic nodes. Industrial automation controllers in Germany adopt these for radiation-tolerant firmware storage.
- NOR:Parallel read architectures suit code execution in boot ROM applications. Automotive zonal architecture consolidation in Germany and Japan sustains demand.
- Phase Change Memory:Chalcogenide glass resistivity switching bridges DRAM and Flash performance gaps. Limited commercial deployment concentrates in specialized computing applications.
- Ferroelectric RAM:Polarization switching in perovskite films delivers unlimited endurance for smart meter data logging. Utility deployments in France leverage ANSM-certified module suppliers.
- Spin Transfer Torque RAM:Spin-polarized current switching promises DRAM-class speed with Flash-class persistence. Research consortia in Japan and the United States drive pilot production.
3D NAND commands the established base. The steepest expansion runs through Resistive RAM.
Application:
Volume concentration in data centers and consumer electronics dwarfs specialized aerospace and embedded segments, with customer type determining contract structures.
- Data Centers:Petabyte-scale DRAM deployments for large language model training require high-bandwidth memory packaging. Hyperscale operators in the United States negotiate wafer supply agreements independently of traditional module vendors.
- Consumer Electronics:Mobile devices and PCs absorb standardized DDR and LPDDR modules. Procurement flows through Taiwan-based OEMs with mainland China assembly capacity.
- Embedded Systems:Microcontroller-integrated memory serves industrial controllers and IoT endpoints. European REACH chemical constraints restrict solder compositions in module assembly.
- Networking Equipment:Buffer memory for routers and switches demands deterministic latency characteristics. 5G infrastructure buildouts in India attract test and assembly investments under the PLI scheme.
- Aerospace:Radiation-hardened memory for satellite systems commands qualification timelines exceeding three years. Defense procurement in the United States runs through FAA-certified suppliers.
- Gaming Consoles:Unified memory architectures blend high bandwidth with moderate capacity. Console OEMs in Japan and the United States source through captive foundry arrangements.
Consumer Electronics commands the established base. The steepest expansion runs through Data Centers.
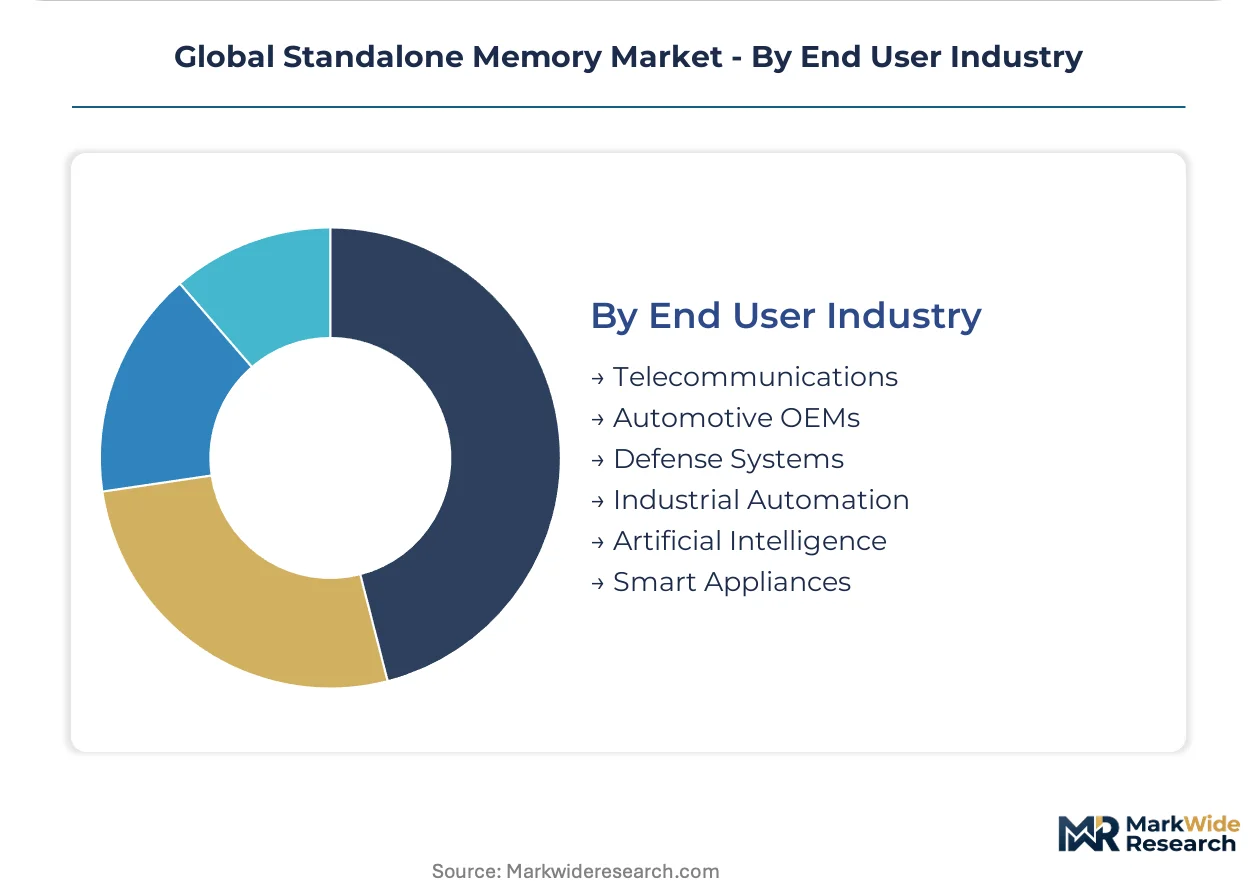
End User Industry:
Supply concentration in telecommunications and automotive OEMs creates multi-year capacity commitments, while defense and AI segments drive specification divergence.
- Artificial Intelligence:Training accelerators demand HBM3E and next-generation high-bandwidth memory with advanced packaging. GPU vendors in the United States and Taiwan secure dedicated foundry capacity before node qualification completes.
- Automotive OEMs:Zonal architecture consolidation requires 15-year data retention for safety-critical firmware. KBA and NHTSA reliability standards constrain supplier qualification pools.
- Telecommunications:Baseband processing and edge computing infrastructure absorb mid-range DDR modules. India's TRAI spectrum allocations drive domestic assembly expansion.
- Defense Systems:Tempest-rated and ruggedized memory modules face ITAR export controls in the United States. Procurement concentrates among cleared suppliers with captive packaging facilities.
- Industrial Automation:Programmable logic controllers specify extended temperature ranges and vibration tolerance. Japanese METI standards guide domestic supplier selection.
- Smart Appliances:Connected white goods integrate modest Flash capacities for firmware over-the-air updates. China's GB standards steer procurement toward local NAND suppliers.
Telecommunications commands the established base. The steepest expansion runs through Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean wafer output while procurement leverage shifts toward United States hyperscale buyers. Chinese domestic content enforcement is redirecting NAND demand toward local suppliers. European energy regulations are accelerating fab retrofit investments.
United States
Hyperscale data center operators negotiate die-level requirements directly with foundries, bypassing traditional module vendors. EPA hazardous substance rules constrain packaging materials and end-of-life disposal pathways. Idaho fabs anchor leading-edge DRAM production for AI accelerator supply.
South Korea
Captive producers control over half of global DRAM bit shipments through vertical integration across memory types. The country's national industrial regulator enforces energy efficiency standards aligned with dual carbon commitments. Pyeongtaek and Icheon complexes drive process conversions to gate-all-around architectures.
China
State-affiliated cloud operators are expanding procurement from domestic NAND suppliers under MIIT domestic content ratios. GB standards steer government data center builds toward local memory module vendors. Yangtze Memory Technologies anchors 3D NAND layer stacking advancement in Wuhan.
Japan
Industrial automation controllers specify extended temperature grades and radiation tolerance for non-volatile memory. METI-funded pilot programs accelerate MRAM deployment in factory automation systems. Yokohama and Nagoya clusters concentrate advanced packaging engineering talent.
Taiwan
Foundry ecosystem demand for SRAM cache hierarchies sustains specialized memory procurement. Several module suppliers are accelerating mainland China assembly capacity to maintain eligibility for state tenders. Hsinchu Science Park anchors test and assembly investments for regional supply chain redundancy.
Global Standalone Memory Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Captive producers with in-house fabrication capabilities dominate wafer output and advanced packaging integration. Merchant suppliers compete on module customization and regional logistics. The dominant competitive moves are multi-year capacity commitments locking in supply relationships, and strategic partnerships securing advanced packaging engineering talent.
Among South Korea-based fabricators, Samsung Electronics Co. Ltd and SK Hynix Inc. exemplify the captive producer archetype through their control of DRAM and 3D NAND wafer supply. Micron Technology Inc. represents the geographically diversified merchant supplier model, positioning production across Idaho and Japan facilities to navigate trade restrictions. These three entities anchor the competitive structure, with their strategic positioning determining procurement access for hyperscale data center operators and state-affiliated cloud builders across the United States and China.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| SK Hynix Inc. |
| Micron Technology Inc. |
| Microchip Technology Inc. |
| Fujitsu Semiconductor Memory Solution |
| Intel Corporation |
| Infineon Technologies AG |
| Nanya Technology Corporation |
| Powerchip Technology Corporation |
| Others |
Supply & Pricing Matrix
Multi-year wafer supply agreements lock in both DRAM access and price visibility for hyperscale data center operators negotiating directly with South Korean foundries. These contracts compress spot market liquidity and tether module pricing to the capital intensity of EUV tool depreciation schedules.
Pricing Analysis
Configured-to-order pricing for high-bandwidth memory modules commands a substantial premium over standardized DDR configurations. Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume commitment scale. Cost compression in commodity NAND stems from layer-stacking advancements beyond 200 tiers. Consumer electronics OEMs exhibit the highest price sensitivity, while AI training cluster operators absorb premium pricing for guaranteed die supply.
Supply Chain Analysis
Strategic stockpiling of wafer inventory dominates procurement behavior among hyperscale operators seeking insulation from Pyeongtaek seismic risk. Manufacturing concentration in South Korea, Taiwan, and the United States creates single-source vulnerability for advanced node DRAM. Raw material flows draw from high-purity silicon wafers, fluorinated gases, and photoresist chemicals. Distribution runs through Taiwan-based module assemblers with mainland China packaging capacity serving state-affiliated tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Capital requirements for EUV lithography and cleanroom construction create insurmountable barriers to replication.
For Market Incumbents: Shield market position through captive packaging investments in Japan and Idaho fabs that navigate ITAR and export control exposure. Accelerate gate-all-around process conversions before second-tier producers achieve node parity. Prioritize advanced packaging engineering talent retention in Taiwan and South Korea clusters against poaching from emerging foundry projects. For New Entrants and Emerging Players: Custom memory controller design services for mid-tier cloud operators represent an underserved layer where incumbents cede margin. Target India's PLI-backed test and assembly ecosystem for regional supply chain redundancy. Pursue joint venture structures with domestic NAND suppliers in China to access state-affiliated cloud procurement under MIIT content ratios. For Investors and Strategic Acquirers: Advanced packaging specialists with hybrid bonding process capabilities offer the most defensible acquisition profile within the memory value chain. Long-term viability hinges on five-to-ten-year demand visibility from AI accelerator deployment cycles. Monitor HBM3E qualification timelines at GPU vendors as the inflection signal for foundry capacity allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | Hybrid bonding investments at Yokohama clusters secure HBM supply for NVIDIA and AMD accelerators. |
| Geographic Manufacturing Footprint | Idaho and Hiroshima fab positioning navigates CHIPS Act incentives and Japan subsidy programs. |
| Long-term Supply Agreement | Multi-year wafer commitments from AWS and Azure lock in DRAM output before node qualification. |
| Technology Licensing Partnership | Gate-all-around transistor IP transfers compress competitive parity timelines for second-tier producers. |
| Joint Venture Formation | Mainland China assembly partnerships preserve module vendor eligibility under MIIT domestic content enforcement. |
Research Methodology
Initial hypotheses were tested against primary input from foundry process engineers, hyperscale data center procurement officers, memory module vendor sales directors, and advanced packaging specialists and refined through secondary validation. Primary fieldwork combined structured interviews with SEC 10-K filings, SEMI equipment spending reports, hyperscaler capex disclosures, and customs trade data. Bottom-up wafer output estimates and top-down demand segmentation were triangulated to anchor volume forecasts.
Variance decomposition across memory type, technology node, application segment, and end-user industry dimensions shaped the analytical framework. CAGR derivation rested on equipment depreciation schedules, node transition timelines, and hyperscaler infrastructure deployment patterns throughout the forecast period. Layer-stacking roadmaps and HBM packaging yield curves served as semiconductor-specific forecast inputs.
Forecasts assume regulatory continuity in US export control regimes and EU F-Gas phasedown schedules; material policy shifts would require re-modeling of fab location economics and procurement eligibility. Revision becomes warranted when high-bandwidth memory yield rates at advanced nodes cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Memory Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
New RAM Market
Memory Chips
Nano RAM Market
Memory Chips
DDR RAM Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Automotive Memory Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Contactless Memory Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Mobile DRAM Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
Digital RF Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market