
 Americas Dynamic Random Access Memory (DRAM) Market | 2026-2036
Americas Dynamic Random Access Memory (DRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Dynamic Random Access Memory (DRAM) Market Insights
Specialized semiconductor process engineering talent is collapsing across the Americas, tightening fabs' ability to staff advanced node production. Micron Technology Inc. sustains its Boise-based R&D footprint while competing for Arizona-based expansion slots. Samsung Electronics anchors its Taylor, Texas foundry buildout with Korean-trained process specialists. SK hynix navigates workforce gaps through partnerships with regional technical colleges.
Dynamic Random Access Memory stores data as electrical charge in capacitors accessed via transistors, with DDR5 modules operating at 4.8 Gbps base transfer rates to serve bandwidth-hungry processors. The technology's primary commercial purpose is volatile working memory for computing systems requiring rapid read-write cycling. DDR5 modules command premium positioning as server refresh cycles accelerate, while Data Centers represent the fastest-growing application segment driven by AI inference scaling. Automotive Systems remains nascent but carries above-average margin pools due to temperature-grade certification requirements.
The US Department of Commerce CHIPS Program Office governs domestic fabrication subsidies, conditioning awards on US citizen workforce development quotas. EPA emissions standards for semiconductor manufacturing influence chemical abatement system investments at new fabs. Texas and Arizona state regulators coordinate water-use permitting for desert-region foundry operations. Stakeholders must weigh localization incentives against persistent equipment import dependencies from Asian lithography suppliers.
Market Dynamics
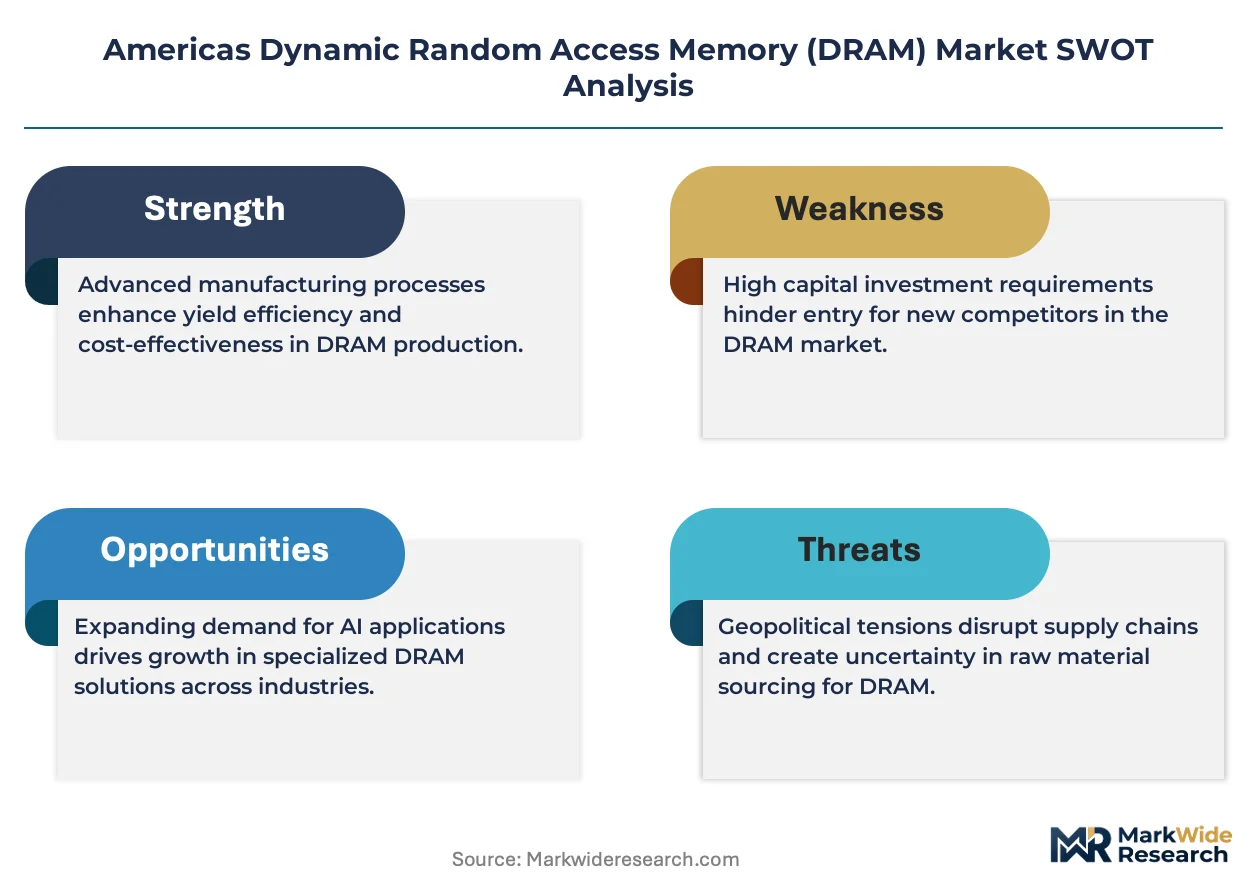
AI inference clusters are redrawing memory procurement patterns across the Americas, forcing data center operators to triple socket-level DRAM density while fabs struggle to convert planar capacity to advanced node output fast enough.
Growth Catalysts
- CHIPS Act capital subsidies:The US Department of Commerce conditions awards on domestic workforce quotas, accelerating foundry construction timelines in Arizona and Texas.
- Bandwidth-hungry processor architectures:Server CPU vendors now mandate DDR5-5600 as baseline, forcing enterprise refresh cycles that pull high-density modules through distribution.
- AI training cluster buildouts:Hyperscalers in Virginia and Oregon are commissioning exascale systems requiring HBM3E and high-capacity DDR5 in parallel configurations.
Market Restraints
- Extreme ultraviolet lithography dependency:Scanner procurement from Asian suppliers creates 18-month equipment lead times that gate Arizona and Texas fab ramp schedules.
- Perfluorinated compound emissions caps:EPA standards for semiconductor manufacturing impose abatement system costs that inflate greenfield project budgets by double-digit percentages.
- Process engineering talent scarcity:Domestic universities produce fewer than 300 specialized semiconductor manufacturing graduates annually against fab demand for thousands.
Strategic Opportunities
- Automotive temperature-grade certification:Underpenetrated demand from Detroit and Stuttgart-based Tier-1s for AEC-Q100 qualified modules carries 40-60% margin premiums over commercial-grade equivalents.
- Technical college pipeline partnerships:SK hynix and regional institutions in Idaho are prototyping 18-month certification tracks that could become template for industry-wide workforce scaling.
- Near-memory compute integration:Convergence of processing-in-memory architectures with CXL 3.0 interconnect standards opens socket redesign cycles at cloud operators.
Industry Challenges
- Legacy DDR4 inventory absorption:Enterprise datacenters in Chicago and Toronto face 24-month depreciation schedules that delay DDR5 migration despite performance gaps.
- Cleanroom construction labor shortages:Specialized concrete and HVAC contractors for fab shell completion are booked 14 months forward in the Southwest construction corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Dynamic Random Access Memory (DRAM) Market |
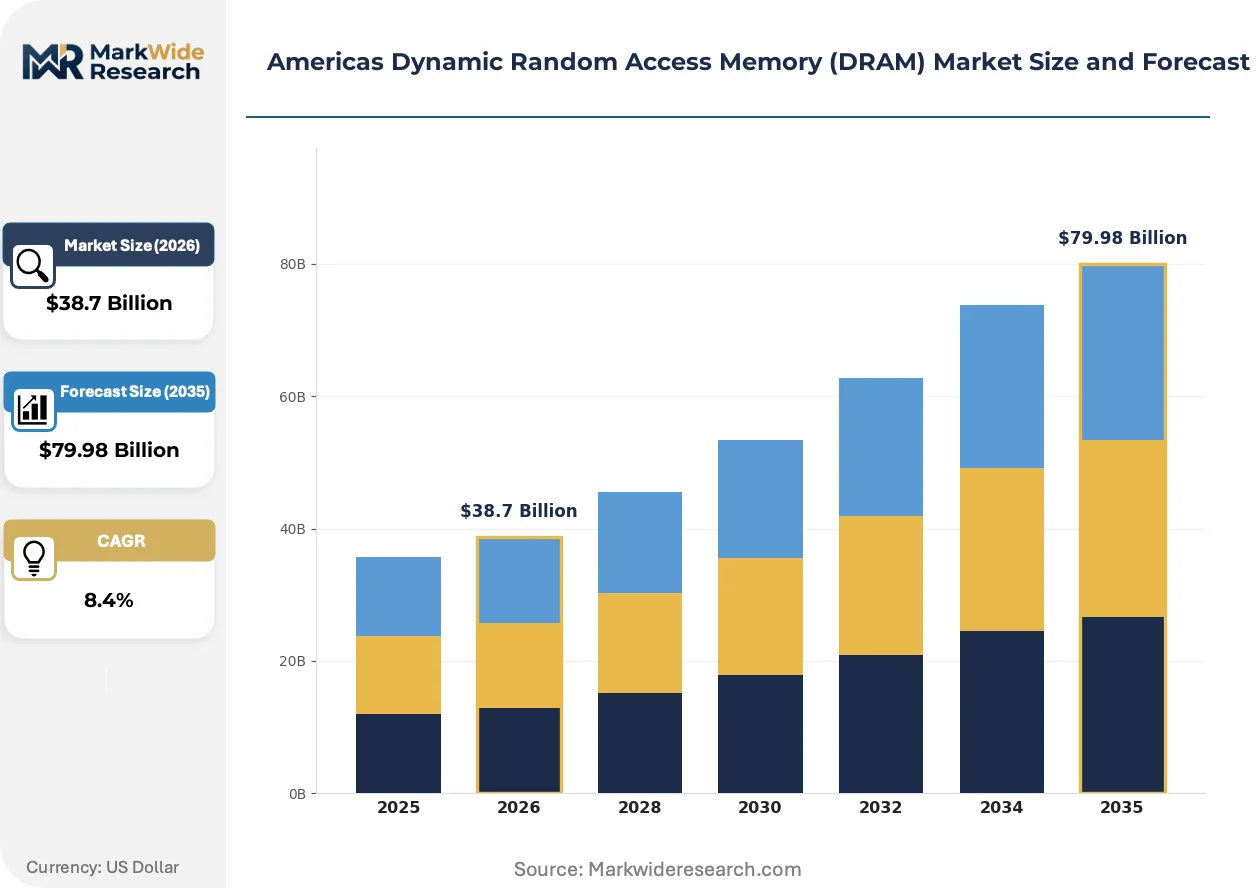
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR3, DDR4, DDR5, SDRAM Application: Consumer Electronics, Data Centers, Mobile Devices, Automotive Systems Packaging Type: FBGA, WL-CSP, TSOP, DIMM End User: OEMs, Retailers, System Integrators, Consumers |
| Companies Covered | Micron Technology Inc., Samsung Electronics, SK hynix, Nanya Technology Corporation, Winbond Electronics Corporation, Kingston Technology, Infineon Technologies, Intel Corporation, United Microelectronics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Dynamic Random Access Memory (DRAM) Market Trends and Innovations
DDR5 module architectures are fragmenting into application-specific variants while regulatory compliance costs reshape where new capacity lands. Three forces are compressing standard product lifecycles.
Heterogeneous integration is decomposing traditional monolithic DRAM die designs into stacked configurations. Cloud operators in Northern Virginia are adopting chiplet-based memory subsystems that mix logic and storage layers. This decomposition is compressing commodity module margins while expanding the addressable market for advanced packaging services.
The EPA's National Emission Standards for Hazardous Air Pollutants now explicitly covers semiconductor etch and deposition operations. New fabs in Arizona must install thermal abatement systems that destroy fluorinated gases at 99% efficiency. Texas operators are responding by pre-negotiating 20-year power purchase agreements to offset energy-intensive scrubber operations.
Hyperscalers are consolidating memory procurement through direct foundry relationships that bypass traditional distribution. Channel partners in California and Washington state are pivoting to value-added integration and firmware customization services. This behavioral shift is most visible among AI-focused cloud builders who now specify module thermal profiles and error-correction schemes at the wafer level.
Americas Dynamic Random Access Memory (DRAM) Market Segmentation
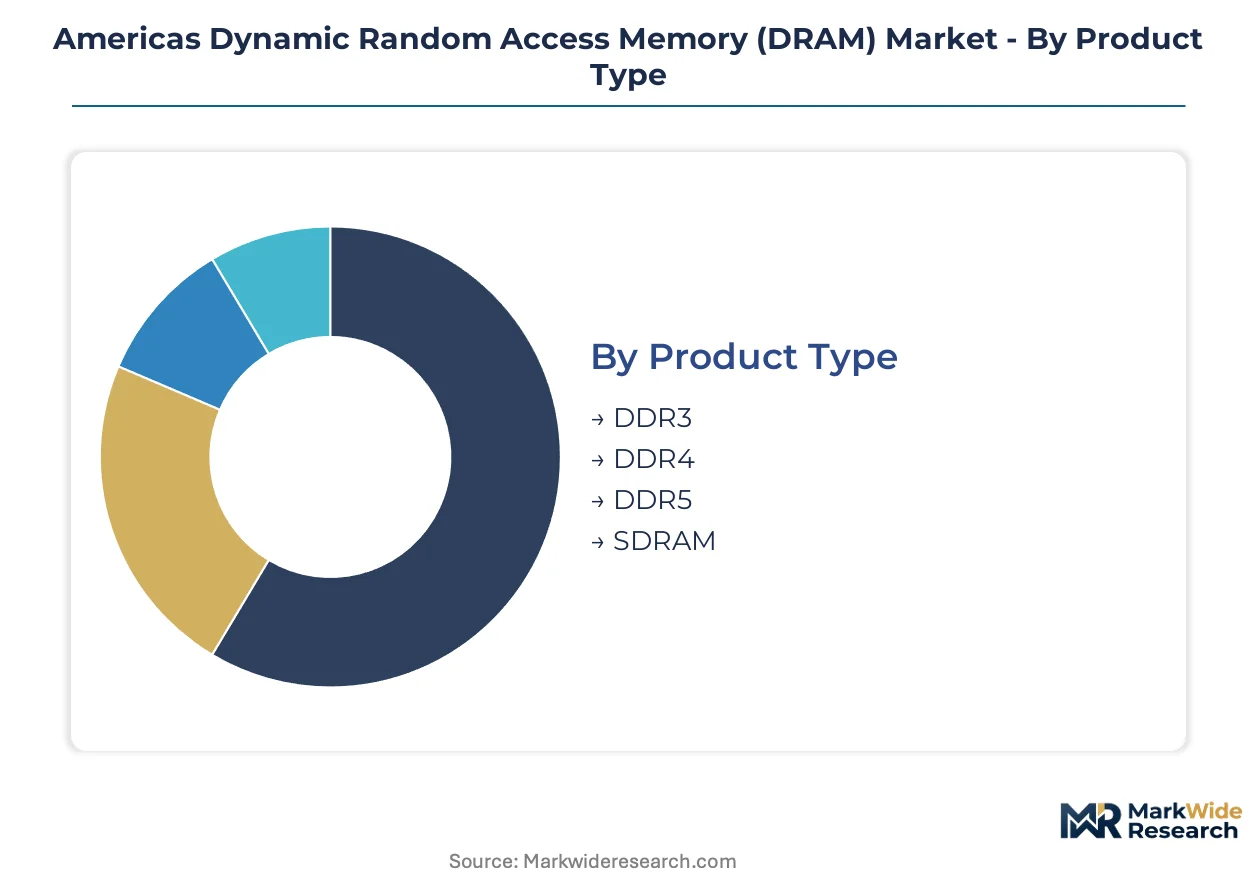
Memory procurement across the Americas fragments along performance tiers and thermal certification boundaries. Understanding these splits exposes where hyperscalers overpay for bandwidth and where automotive suppliers capture margin premiums.
Product Type:
DDR5 modules command the widest margin spreads due to server refresh urgency, while legacy DDR4 volumes still absorb depreciation-constrained enterprise budgets.
- DDR5:Operating at 4.8 Gbps base rates with on-die ECC, these modules serve bandwidth-hungry processors in Virginia and Oregon AI clusters. Hyperscalers mandate DDR5-5600 as baseline, forcing enterprise pull-through despite 40% unit premiums over DDR4.
- DDR4:Mature 3200 MT/s specifications dominate Chicago and Toronto datacenter depreciation cycles. Twenty-four-month amortization schedules delay migration despite measurable performance gaps against newer nodes.
- DDR3:Legacy embedded systems in industrial automation retain limited procurement volumes.
- SDRAM:Specialized synchronous architectures persist in legacy telecommunications infrastructure.
The dominant share belongs to DDR4, while DDR5 is closing the gap fastest.
Application:
Volume concentrates in compute-intensive installations, though margin pools sit in temperature-grade certifications.
- Data Centers:Exascale training clusters in Northern Virginia and Oregon require HBM3E and high-capacity DDR5 in parallel configurations. Socket-level density has tripled as inference scaling accelerates memory procurement cycles.
- Automotive Systems:AEC-Q100 qualified modules for Detroit-based Tier-1s carry 40-60% margin premiums over commercial-grade equivalents. Temperature-grade certification requirements create supply scarcity.
- Consumer Electronics:Notebook and desktop refresh cycles in California and Washington state drive mainstream module demand.
- Mobile Devices:Low-power LPDDR5 specifications serve handset OEMs assembling in Mexico and Brazil.
Data Centers capture the largest revenue pool, with Automotive Systems expanding most quickly.
Packaging Type:
Physical form factors separate high-density server applications from space-constrained mobile and automotive implementations.
- DIMM:Dual in-line memory modules dominate rack-scale server deployments across Arizona and Texas hyperscale facilities. JEDEC-standard thermal profiles allow direct procurement from foundry partners bypassing distribution.
- FBGA:Fine-pitch ball grid arrays serve automotive ECUs requiring vibration resistance in Detroit powertrain applications.
- WL-CSP:Wafer-level chip-scale packaging enables smartphone thickness targets.
- TSOP:Thin small-outline packages persist in legacy networking equipment.
DIMM formats hold the volume lead, though FBGA is gaining share fastest in automotive-qualified supply.
End User:
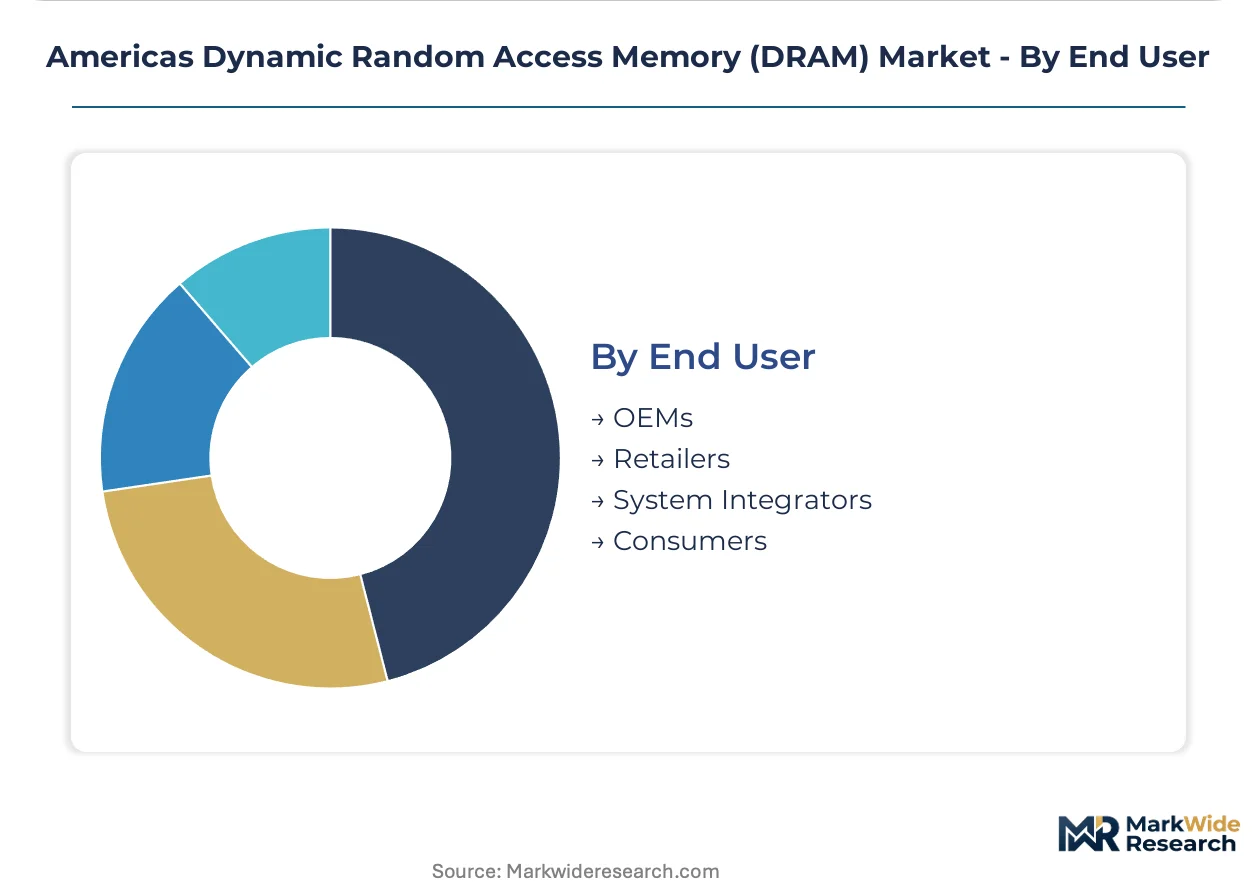
Procurement behavior diverges sharply between specification-setting OEMs and price-sensitive retail channels.
- OEMs:Server vendors and automotive Tier-1s in Michigan and California negotiate direct foundry relationships. These buyers specify thermal profiles and error-correction schemes at wafer level, consolidating purchasing power.
- System Integrators:Value-added resellers in Texas and Arizona assemble custom configurations for mid-market enterprise clients.
- Retailers:California and Washington-based channel partners pivot to firmware customization as margin compression hits commodity modules.
- Consumers:DIY upgrade cycles in North American e-commerce channels show price elasticity.
OEMs control the dominant procurement volume, while System Integrators are climbing the fastest as mid-market cloud adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Americas diverge sharply. The United States drives high-bandwidth server memory procurement for AI training clusters. Latin American markets prioritize cost-optimized modules for consumer electronics assembly.
United States
Hyperscalers in Northern Virginia and Oregon commission exascale systems requiring HBM3E and high-capacity DDR5 configurations. The Department of Commerce CHIPS Program Office governs domestic fabrication subsidies with workforce development conditions. New foundry complexes in Arizona and Texas anchor domestic capacity expansion.
Canada
Enterprise datacenters in Toronto and Montreal face depreciation-constrained refresh cycles that delay DDR5 migration. Environment and Climate Change Canada monitors fluorinated gas emissions from semiconductor manufacturing operations. Cleanroom construction labor shortages in the Southwest construction corridor extend project timelines.
Mexico
Handset OEMs assembling in Guadalajara and Tijuana drive low-power LPDDR5 specifications for export markets. The Secretariat of Economy administers incentives for electronics manufacturing under the IMMEX program. Baja California hosts memory module integration facilities serving North American distribution channels.
Brazil
Consumer electronics retailers in São Paulo and Rio de Janeiro show price elasticity in DIY upgrade cycles. ANVISA regulates electromagnetic compatibility standards for imported semiconductor components. Southeast industrial zones concentrate final assembly operations for regional consumption.
Chile
Data center operators in Santiago deploy modular server configurations with standardized DDR4 specifications. The Ministry of Mining coordinates lithium supply chain linkages for battery and memory component industries. Atacama Desert regions attract renewable-powered computing facilities with cooling advantages.
Americas Dynamic Random Access Memory (DRAM) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. The Americas DRAM market structures around three dominant memory fabricators with captive fabrication capacity. Mid-tier module integrators compete on customization velocity and regional logistics. Capacity expansion and workforce pipeline partnerships represent the dominant competitive vectors.
Among integrated memory fabricators, Micron Technology Inc., Samsung Electronics, and SK hynix occupy positions defined by wafer-level production scale. Micron exemplifies the domestic R&D anchor archetype with Boise-based engineering retention. Samsung represents the Korean-trained specialist deployment model for greenfield Texas operations. SK hynix sits within the technical college partnership tier addressing workforce gaps through regional certification tracks.
| Leading Market Players |
|---|
| Micron Technology Inc. |
| Samsung Electronics |
| SK hynix |
| Nanya Technology Corporation |
| Winbond Electronics Corporation |
| Kingston Technology |
| Infineon Technologies |
| Intel Corporation |
| United Microelectronics Corporation |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month EUV scanner lead times from Asian lithography suppliers concentrate pricing power with equipment vendors, compressing foundry margins while hyperscalers negotiate wafer-level specifications that bypass traditional distribution markups.
Pricing Analysis
Long-term offtake contracts dominate procurement between hyperscalers and integrated fabricators, though spot market activity persists for legacy DDR4 modules. Price differentiation separates AEC-Q100 automotive-qualified supply from commercial-grade equivalents, with temperature-grade certification commanding substantial premiums. Pricing pressure stems from legacy DDR4 inventory absorption in depreciation-constrained enterprise datacenters. Retail channels show highest price sensitivity, while OEMs with direct foundry relationships exhibit lowest elasticity due to specification control at wafer level.
Supply Chain Analysis
Inbound logistics costs from Asian lithography suppliers through West Coast ports create equipment delivery bottlenecks that gate Arizona and Texas fab ramp schedules. Supply concentrates in South Korea, Taiwan, and the United States for wafer fabrication, with Japan and the Netherlands contributing critical equipment and materials. Raw material dependencies span silicon wafers, photoresists, and fluorinated process gases. Single-source vulnerability in EUV scanner procurement represents the dominant structural risk. Distribution runs through direct foundry relationships for hyperscalers, with channel partners handling mid-market enterprise and retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized semiconductor process engineering talent pools have collapsed below sustainable replacement rates, with domestic universities producing fewer than three hundred qualified graduates annually against fab demand for thousands.
For Market Incumbents: Compound Boise-based R&D retention with Korean-trained specialist deployment models to secure process engineering pipelines. Expand captive fabrication capacity in Arizona and Texas before CHIPS Act subsidy windows narrow. Accelerate technical college certification partnerships to preempt workforce competition from emerging entrants.
For New Entrants and Emerging Players: Anchor in automotive temperature-grade certification segments where AEC-Q100 qualification creates supply scarcity and margin premiums. Target Detroit-based Tier-1 relationships as the most penetrable entry point. Pursue value-added integration and firmware customization services as primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because AI training cluster buildouts will sustain memory demand regardless of short-term pricing cycles. Focus acquisition screening on technical college pipeline operators and advanced packaging specialists. Monitor EPA emissions standard enforcement as inflection indicator for greenfield project viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Technical College Pipeline Partnership | SK hynix prototypes eighteen-month certification tracks with Idaho institutions to address workforce gaps. |
| Direct Foundry Relationship Expansion | Hyperscalers in Virginia and Oregon bypass distribution to specify thermal profiles at wafer level. |
| Automotive Temperature-Grade Certification | AEC-Q100 qualified modules for Detroit Tier-1s capture forty to sixty percent margin premiums. |
| Thermal Abatement System Investment | Arizona fabs install EPA-compliant scrubbers that destroy fluorinated gases at ninety-nine percent efficiency. |
| Near-Memory Compute Integration | Cloud operators adopt CXL three-point-zero interconnect standards for processing-in-memory architectures. |
Research Methodology
Operator-level perspectives from fab process engineers, data center procurement officers, automotive Tier-1 supply chain managers, and EPA regulatory compliance leads anchored the qualitative base. Primary interview findings triangulated against secondary sources including SEC semiconductor capex disclosures, CHIPS Program Office award documentation, and EPA National Emission Standards filings. Bottom-up module demand estimates from enterprise refresh cycles and hyperscaler buildout announcements reconciled with top-down wafer capacity forecasts from foundry expansion timelines.
Sensitivity analysis tested forecast robustness across equipment delivery scenarios, subsidy award timing variations, and workforce pipeline acceleration assumptions. Segmentation modeling incorporated product type, application, packaging format, and end-user procurement behavior dimensions across the projection horizon. CAGRs derived from unit volume trajectories and average selling price evolution through server refresh cycles. Industry-specific inputs included AI inference scaling coefficients and automotive qualification timeline benchmarks.
Underlying assumptions cover CHIPS Act subsidy disbursement schedules, EUV equipment delivery commitments, and technical college partnership scaling rates, with deviation risk concentrated in EPA emissions enforcement intensity and cleanroom construction labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
In-Memory Grid Market
Memory Chips
Memory Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Memory Module Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Memristor Market
Memory Chips
Static RAM Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Memory IC Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
China Flash Memory Market